
 Brazil Data Center Construction Market | 2026-2036
Brazil Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Construction Market Insights
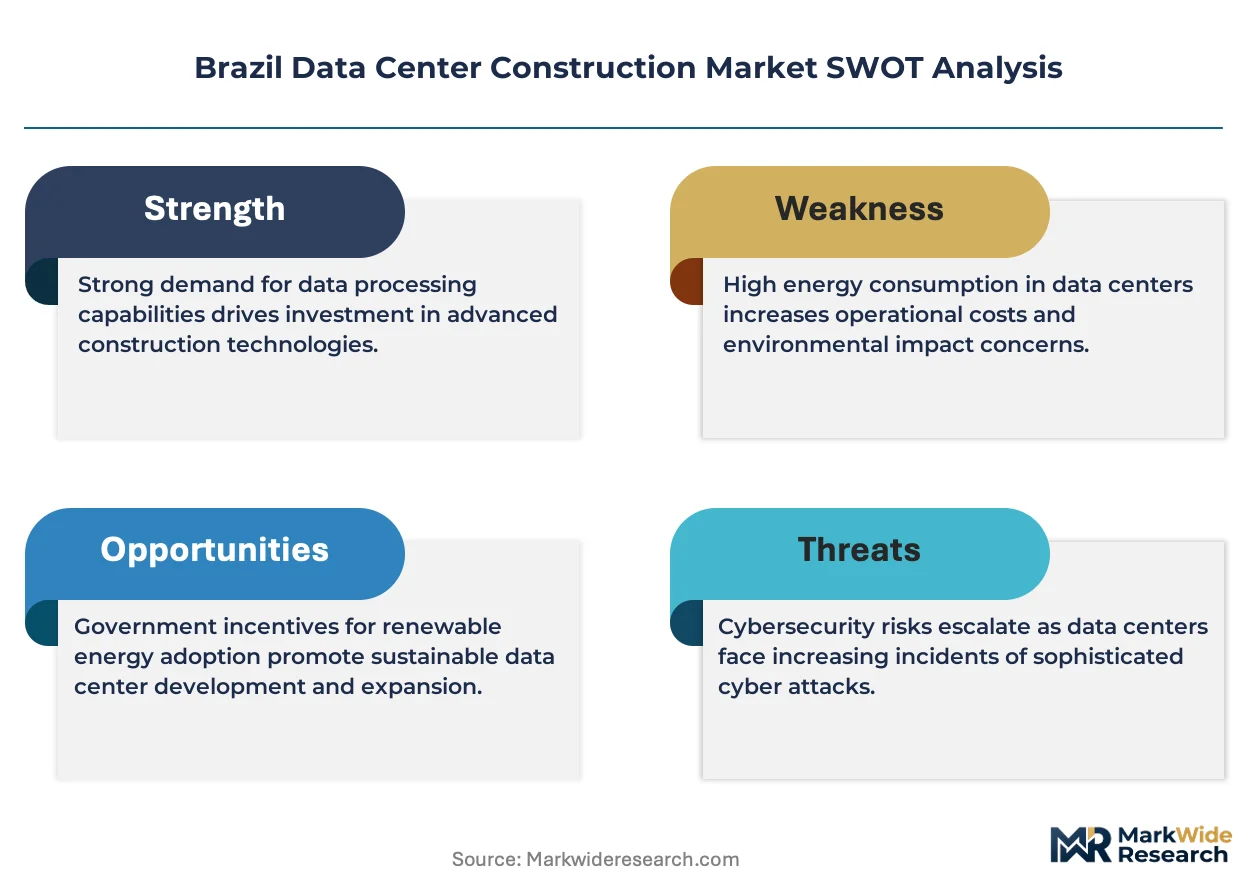
Brazilian hyperscale developers is rebalancing capacity toward Tier III and Tier IV facilities in São Paulo and Rio de Janeiro. Ascenty leverages its vertically integrated design-build-operate model to control project timelines across multiple campuses. Scala Data Centers sustains aggressive expansion through standardized modular designs that compress deployment cycles. Elea Data Centers anchors its position in the northeast through Fortaleza deployments targeting submarine cable landing zones.
Brazil data center construction encompasses the engineering, procurement, and installation of mission-critical facilities housing compute, storage, and networking infrastructure, typically requiring power densities exceeding 15 kW per rack and precision cooling maintaining ±1°C tolerance. These structures serve cloud providers, financial institutions, and telecommunications carriers requiring continuous uptime for transaction processing and content delivery. Cooling Systems and Power Supply segments command the deepest margin pools due to specialized engineering requirements and import dependency for critical components. Modular Data Centers and Containerized Solutions represent the fastest-expanding installation types as enterprises prioritize speed-to-market over custom builds.
ANATEL, the national telecommunications regulator, shapes fiber interconnection mandates that determine site viability, while ABNT NBR standards govern structural and electrical safety certifications required for operational licensing. Local environmental agencies enforce water usage restrictions that directly impact cooling technology selection in drought-prone regions. Stakeholders must monitor regulatory shifts around renewable energy sourcing requirements that will determine power contracting strategies and long-term operating economics.
Market Dynamics
Hyperscale cloud providers are compressing deployment timelines from 18 months to under 12 months, forcing construction firms to adopt prefabricated electrical and mechanical skids that ship pre-tested to São Paulo and Rio de Janeiro sites.
Growth Catalysts
- ANATEL Fiber Mandates:The regulator's updated backbone requirements accelerate dark fiber deployment to data center zones, reducing interconnection latency for financial services and streaming platforms.
- Cloud Provider Procurement Surge:Amazon Web Services, Microsoft Azure, and Google Cloud are simultaneously expanding Brazilian capacity, creating sustained order flow for Tier III and Tier IV builds.
- Submarine Cable Landings:New cable systems terminating in Fortaleza and Santos position Brazil as a Latin American traffic exchange hub, driving edge facility construction.
Market Restraints
- Import Dependency for Switchgear:Medium-voltage electrical components face 90-120 day lead times from European and Asian suppliers, constraining project velocity.
- Water Scarcity in Northeast Clusters:Ceará state environmental agencies restrict cooling tower operations during drought periods, limiting evaporative cooling economics.
- Currency Volatility:Real-dollar exchange rate swings inflate equipment procurement costs for dollar-denominated imports, compressing contractor margins.
Strategic Opportunities
- Amazon Basin Renewable Sourcing:Hydropower-rich northern states offer long-term power purchase agreements below southeast grid pricing, attracting carbon-neutral facility commitments.
- Edge Micro-Data Centers:5G network densification creates distributed compute demand in secondary cities like Curitiba, Belo Horizonte, and Recife.
- Modular Standardization:Factory-built power and cooling modules reduce on-site labor requirements, addressing skilled electrician shortages in São Paulo state.
Industry Challenges
- Certified Technician Scarcity:ABNT NBR electrical safety licensing requires 2,000+ training hours, creating bottlenecks for commissioning teams.
- Legacy Grid Interconnection Queues:Utility connection approvals for 50+ MW facilities extend 14-18 months, delaying revenue recognition for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Construction Market |
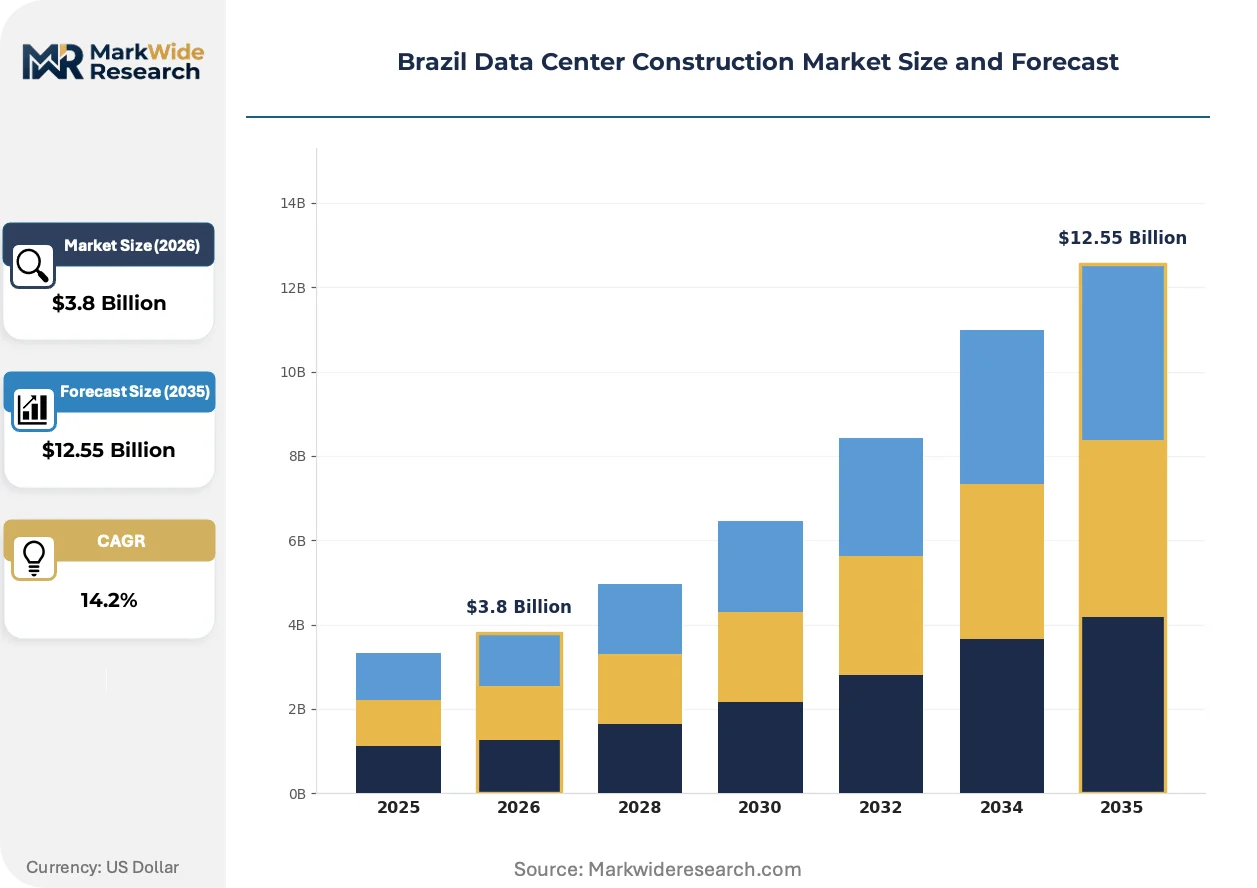
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Power Supply, Structural Framework, Fire Suppression Technology: Cloud Computing, Edge Computing, Virtualization, Data Storage End User: Retail Corporations, Financial Institutions, IT Service Providers, Telecommunications Installation Type: Modular Data Centers, Containerized Solutions, Traditional Builds, Hybrid Systems |
| Companies Covered | Ascenty, Equinix, Scala Data Centers, ODATA, Elea Data Centers, Cirion Technologies, Afonso Franca Engenharia, Racional Engenharia, Mendes Holler, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Construction Market Trends and Innovations
Liquid cooling architectures and AI-optimized building management systems are displacing conventional designs, while regulatory pressure on carbon intensity forces power sourcing innovation across Brazilian states.
Immersion cooling using dielectric fluids is converging with high-density GPU clusters deployed for generative AI training workloads. Financial services firms in São Paulo are piloting two-phase immersion systems at 40 kW per rack densities. This convergence is compressing mechanical plant footprints by 60 percent, freeing floor space for revenue-generating compute.
ANATEL's revised Resolution 2424 mandates redundant fiber paths into any facility serving telecommunications carriers, effective for new licenses. The rule elevates site selection criteria to include dual-route physical diversity, not just logical redundancy. Developers in Campinas and Barueri are now pre-negotiating easements with multiple fiber operators before breaking ground.
Enterprise buyers are unbundling design-build contracts into separate engineering, procurement, and construction phases to retain direct vendor relationships. This disintermediation shifts risk allocation toward owners while compressing general contractor margins. The pattern is most visible among Brazilian banks and insurers with captive real estate teams in Rio de Janeiro.
Brazil Data Center Construction Market Segmentation
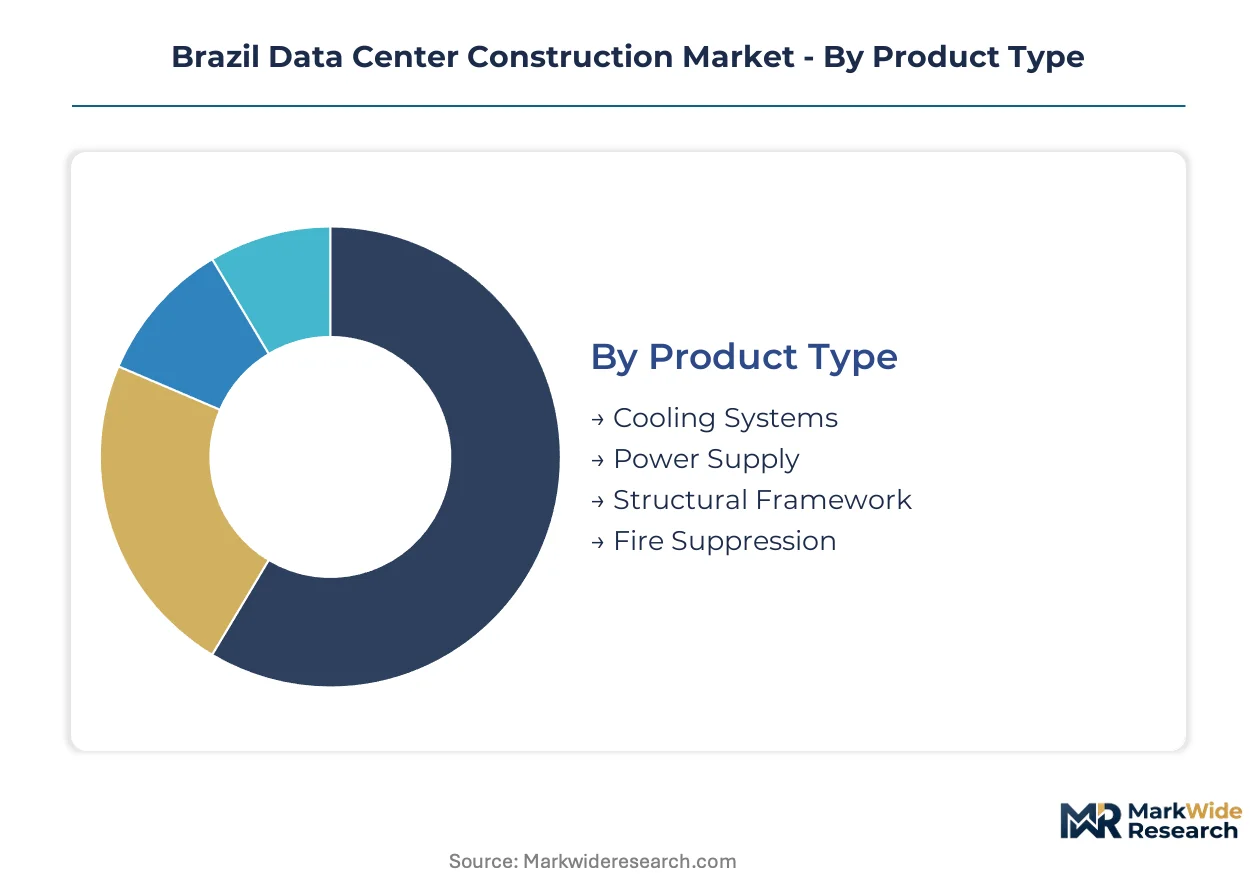
Brazilian data center construction demands granular segmentation to capture divergent engineering requirements across cooling architectures, deployment velocities, and regulatory compliance tiers. Each axis reveals distinct margin structures and procurement patterns that shape contractor specialization and developer site selection strategies.
Product Type:
Power density thresholds and thermal load characteristics determine component specification intensity across facility subsystems.
- Cooling Systems:Precision HVAC and liquid cooling architectures maintain ±1°C tolerance for high-density racks exceeding 15 kW. São Paulo state hyperscale deployments favor chilled water systems with N+1 redundancy to satisfy ABNT NBR thermal safety certifications.
- Power Supply:Medium-voltage switchgear, uninterruptible power supplies, and generator sets constitute the capital-intensive electrical backbone. Import dependency for European and Asian switchgear components creates 90-120 day procurement lead times that constrain project schedules.
- Structural Framework:Reinforced concrete and steel enclosures house mission-critical equipment with seismic resistance ratings for Brazilian fault zones.
- Fire Suppression:Clean agent and water mist systems protect electrical infrastructure without equipment damage from discharge residue.
Mature deployment sits with Power Supply. Newer deployment is concentrated in Cooling Systems.
Technology:
Workload distribution patterns between centralized hyperscale and distributed edge nodes drive divergent facility sizing and interconnection requirements.
- Cloud Computing:Hyperscale facilities consolidate compute, storage, and networking for Amazon Web Services, Microsoft Azure, and Google Cloud. ANATEL fiber mandates accelerate dark fiber deployment to these zones, reducing latency for financial services and streaming platforms.
- Edge Computing:Distributed micro-facilities position compute closer to 5G base stations and IoT endpoints. Curitiba, Belo Horizonte, and Recife clusters gain traction as telecommunications carriers densify networks.
- Virtualization:Software-defined infrastructure maximizes hardware utilization across multi-tenant environments.
- Data Storage:Object and block storage systems underpin archival and transactional workloads with tiered durability guarantees.
Cloud Computing anchors current capacity absorption. Edge Computing is gaining share fastest as latency-sensitive applications proliferate.
End User:
Risk tolerance and uptime requirements stratify buyer procurement sophistication and contract structuring approaches.
- Financial Institutions:Brazilian banks and insurers demand Tier III and Tier IV certifications with sub-10 millisecond failover capabilities. Captive real estate teams in Rio de Janeiro increasingly unbundle design-build contracts to retain direct vendor relationships.
- Telecommunications:Carriers require redundant fiber paths mandated by ANATEL Resolution 2424, elevating site selection to dual-route physical diversity criteria.
- Retail Corporations:E-commerce platforms and omnichannel retailers procure colocation for seasonal demand spikes.
- IT Service Providers:Systems integrators and managed service providers aggregate demand from mid-market enterprises.
Financial Institutions command premium specifications. IT Service Providers are expanding most quickly as outsourcing accelerates.
Installation Type:
Speed-to-market priorities and capital deployment flexibility determine prefabrication versus traditional construction trade-offs.
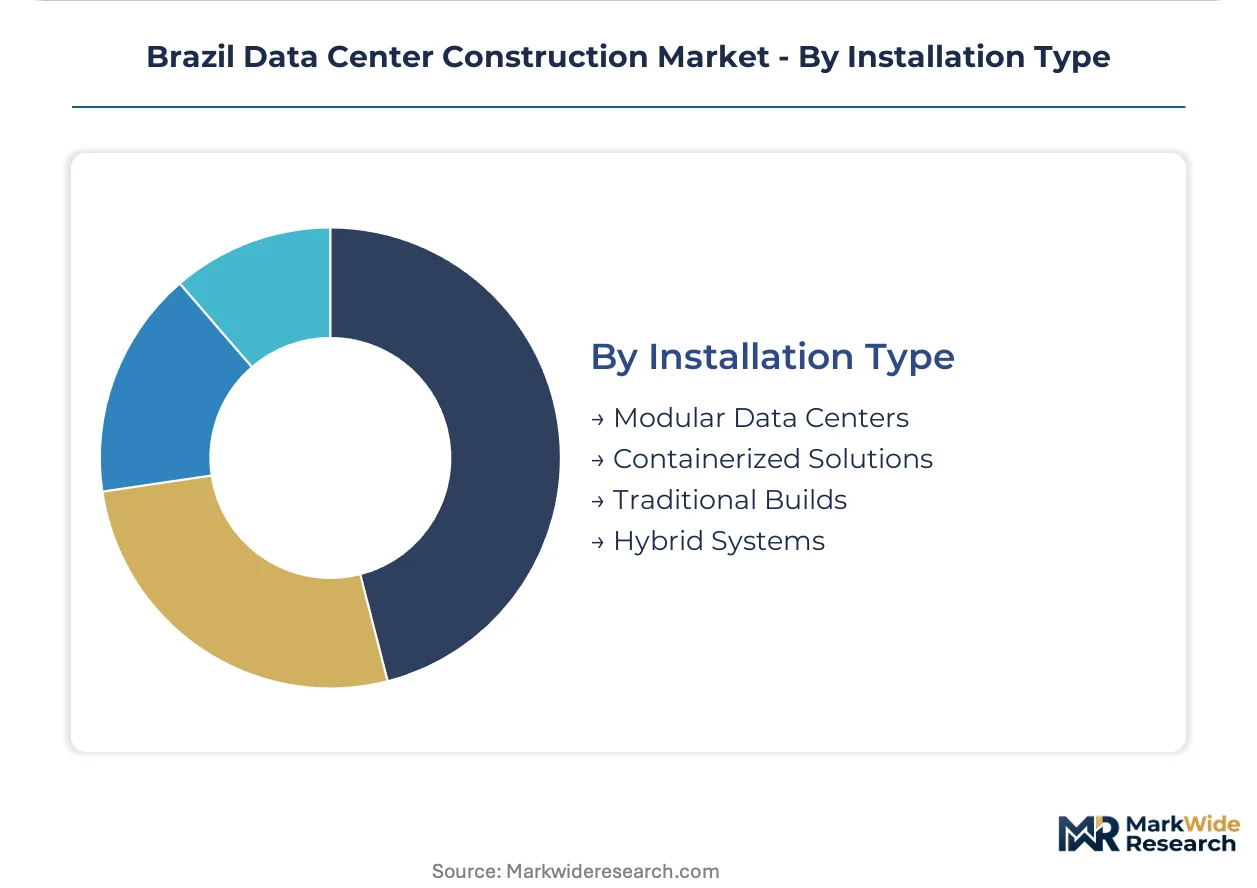
- Modular Data Centers:Factory-built power and cooling modules compress deployment cycles and reduce on-site labor requirements. Scala Data Centers leverages standardized modular designs across multiple São Paulo campuses.
- Containerized Solutions:Pre-engineered shipping container units enable rapid capacity augmentation at existing sites or remote edge locations. Submarine cable landing zones in Fortaleza and Santos favor containerized builds for temporary capacity ahead of permanent facilities.
- Traditional Builds:Custom-engineered facilities offer maximum design flexibility for specialized workloads.
- Hybrid Systems:Combinations of permanent infrastructure with modular expansion capacity balance long-term asset life with growth optionality.
Traditional Builds retain legacy footprint. Modular Data Centers and Containerized Solutions together represent the steepest expansion trajectory as hyperscale timelines compress below 12 months.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper deposits in the Carajás Mineral Province anchor northern Brazil's power infrastructure expansion. Hydropower availability from the Tucuruí and Belo Monte complexes shapes site economics across Pará and neighboring states.
São Paulo
Hyperscale cloud providers compress deployment timelines below 12 months across Campinas and Barueri corridors. ANATEL Resolution 2424 mandates redundant fiber paths, forcing developers to pre-negotiate easements with multiple operators. Financial services firms in São Paulo city pilot liquid cooling at 40 kW per rack densities for generative AI workloads.
Rio de Janeiro
Captive real estate teams at Brazilian banks and insurers unbundle design-build contracts to retain direct vendor relationships. ABNT NBR electrical safety certifications govern structural and thermal requirements for Tier III and Tier IV facilities. The metropolitan region absorbs premium colocation demand from energy trading and commodity finance sectors.
Minas Gerais
Belo Horizonte clusters gain traction as telecommunications carriers densify 5G networks for edge computing deployment. Local environmental agencies enforce water usage restrictions that constrain evaporative cooling economics during drought periods. The state offers grid interconnection queues shorter than São Paulo for sub-50 MW facilities.
Ceará
Fortaleza anchors submarine cable landing zones connecting Europe and Africa to Latin America. Elea Data Centers positions capacity to capture trans-Atlantic traffic exchange volumes. State environmental restrictions limit cooling tower operations during dry seasons, favoring closed-loop chilled water architectures over evaporative designs.
Paraná
Curitiba emerges as a secondary hub for distributed compute nodes serving IoT and autonomous vehicle development. Modular data center deployments accelerate as enterprises prioritize speed-to-market over custom builds. The state leverages skilled labor pools from automotive and aerospace manufacturing to address certified technician scarcity.
Brazil Data Center Construction Market Competitive Landscape
Global majors compete with regional champions across engineering capability and local regulatory navigation. The vendor base stratifies into three tiers: vertically integrated developers controlling design-build-operate cycles, specialized construction firms executing owner-directed specifications, and equipment suppliers shipping prefabricated mechanical and electrical skids. Dominant competitive moves include aggressive modular standardization to compress deployment timelines and strategic fiber pre-commitments to secure ANATEL-compliant site viability.
Among Brazil-based developers, Ascenty exemplifies the vertically integrated archetype through campus-level control over project timelines. Scala Data Centers occupies a position within the standardization-driven tier, leveraging repeatable modular designs across multiple São Paulo state locations. Elea Data Centers anchors the geographic specialization vector, concentrating northeast presence in Fortaleza to capture submarine cable landing traffic. These three represent distinct strategic postures: integration depth, deployment velocity, and location-specific interconnection access.
| Leading Market Players |
|---|
| Ascenty |
| Equinix |
| Scala Data Centers |
| ODATA |
| Elea Data Centers |
| Cirion Technologies |
| Afonso Franca Engenharia |
| Racional Engenharia |
| Mendes Holler |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up construction specialists now dominate Brazil's data center contracting landscape, compressing supplier margins while enforcing rigid milestone-based payment structures that shift currency risk toward equipment vendors.
Pricing Analysis
Warranty and commissioning service bundling separates Tier III facility quotes from Tier IV premiums, with ABNT NBR certification compliance acting as the primary price differentiation driver alongside liquid cooling integration depth. Project-based fixed-price contracts dominate hyperscale procurement, though real-dollar volatility is intensifying cost compression for switchgear-intensive electrical packages. Financial institutions exhibit lowest price sensitivity due to captive real estate teams, while regional colocation buyers face acute margin pressure.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale demand for prefabricated mechanical and electrical skids, bypassing traditional distribution layers. Supply concentrates in Germany, China, and South Korea for medium-voltage switchgear, uninterruptible power supplies, and precision cooling components. Single-source vulnerability for European electrical gear creates procurement bottlenecks that extend project timelines. Distribution runs through vertically integrated developers and specialized EPC firms rather than open equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANATEL Resolution 2424's redundant fiber mandate erects a formidable compliance moat, entrenching developers with pre-negotiated easements and locking out undercapitalized entrants lacking multi-operator relationships.
For Market Incumbents: Hedge against currency-driven margin erosion by securing long-term power purchase agreements in Amazon Basin states before renewable sourcing requirements tighten. Deepen backward integration into modular manufacturing to compress deployment timelines below hyperscale cloud provider thresholds. Threat substitution from liquid cooling technology obsolescence demands immediate R&D allocation to two-phase immersion systems. For New Entrants and Emerging Players: AI-optimized building management systems offer a technology-first wedge against established mechanical contractors lacking software competency. White-space targets include edge micro-facilities in Curitiba and Belo Horizonte, where 5G densification outpaces incumbent capacity positioning. Go-to-market leverage rests on factory-built skid partnerships that eliminate on-site commissioning bottlenecks. For Investors and Strategic Acquirers: ANATEL license application volume acceleration is the leading indicator that fiber-precommitted land positions are approaching scarcity value. Five-to-ten year viability favors developers with vertically integrated design-build-operate capabilities and captive renewable energy contracting. Acquisition target archetype: regional specialists with submarine cable landing zone access in Fortaleza or Santos.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Manufacturing Scale-Up | Factory-built skids address certified electrician scarcity across São Paulo state construction sites. |
| Renewable Power Purchase Agreement | Hydropower contracting in Pará secures sub-grid pricing ahead of carbon intensity mandates. |
| Fiber Easement Pre-Commitment | Dual-route physical diversity satisfies ANATEL Resolution 2424 before site development begins. |
| Liquid Cooling Technology Licensing | Two-phase immersion architectures capture 40 kW per rack density demand from generative AI workloads. |
| Edge Facility Geographic Expansion | Curitiba and Belo Horizonte deployments intercept 5G network densification compute requirements. |
Research Methodology
IBGE infrastructure statistics, ANATEL regulatory filings, and ABNT certification databases formed the secondary backbone, supplemented by customs records tracking electrical component imports. Primary fieldwork encompassed interviews with data center development executives, EPC project managers, utility interconnection officers, and fiber network operators. Bottom-up project pipeline aggregation and top-down sectoral expenditure analysis enabled cross-validation across the modeling period.
Historical trendline analysis of construction completion timelines and power density trajectories informed projection frameworks. Segmentation dimensions encompassed installation type, cooling architecture, certification tier, and regional grid interconnection queue depth. CAGRs derived from capacity absorption rates and capital expenditure disclosures by hyperscale cloud providers. Forecast inputs incorporated ANATEL mandate implementation schedules and submarine cable landing activation timelines.
Several conditions sit outside the modeled scope, including extreme drought scenarios beyond Ceará's current environmental restrictions and sovereign debt crisis impacts on real-dollar exchange rates. Forecasts reflect documented assumptions regarding utility queue progression and skilled labor training pipeline expansion. Practitioners should monitor ANATEL fiber mandate enforcement intensity and European switchgear export license delays for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Global Transportation Infrastructure Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Brazil Infrastructure Sector Market