
 Composite Railroad Tie Market | 2026-2036
Composite Railroad Tie Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Railroad Tie Market Outlook
ASTM D790 flexural-grade specification is unwinding legacy procurement patterns across the composite railroad tie industry. RailWorks Corporation leverages in-house polymer compounding to control material consistency from resin to finished tie. CXT Concrete anchors its position through integrated concrete-composite hybrid designs that bridge traditional and advanced tie architectures. Koppers Inc. competes via deep creosote-to-composite transition expertise and established rail customer relationships.
Composite railroad ties are engineered structural members manufactured from recycled plastics, wood-plastic blends, or rubber compounds, typically reinforced with fiberglass or steel inserts to achieve flexural strengths exceeding timber equivalents. They serve as permanent way support elements designed to withstand dynamic wheel loads while eliminating chemical preservative leaching associated with creosote or copper-based treatments. Plastic material formulations currently lead installed volume due to established supply chains and proven field performance across Class I networks. Heavy haul application segments command premium positioning as axle loads rise and replacement cycles compress. Track construction demand dominates new-installation revenue, though maintenance retrofit activity is expanding fastest as timber tie rejection rates accelerate.
Federal Railroad Administration track safety standards and EPA creosote discharge regulations are tightening acceptable preservative thresholds for wooden cross-ties, directly expanding composite qualification programs. ASTM International and AREMA manual specifications govern material testing protocols that determine vendor eligibility for major rail capital budgets. Stakeholders must monitor evolving FRA performance criteria and state-level environmental mandates to anticipate procurement shifts before specification lock-in periods close.
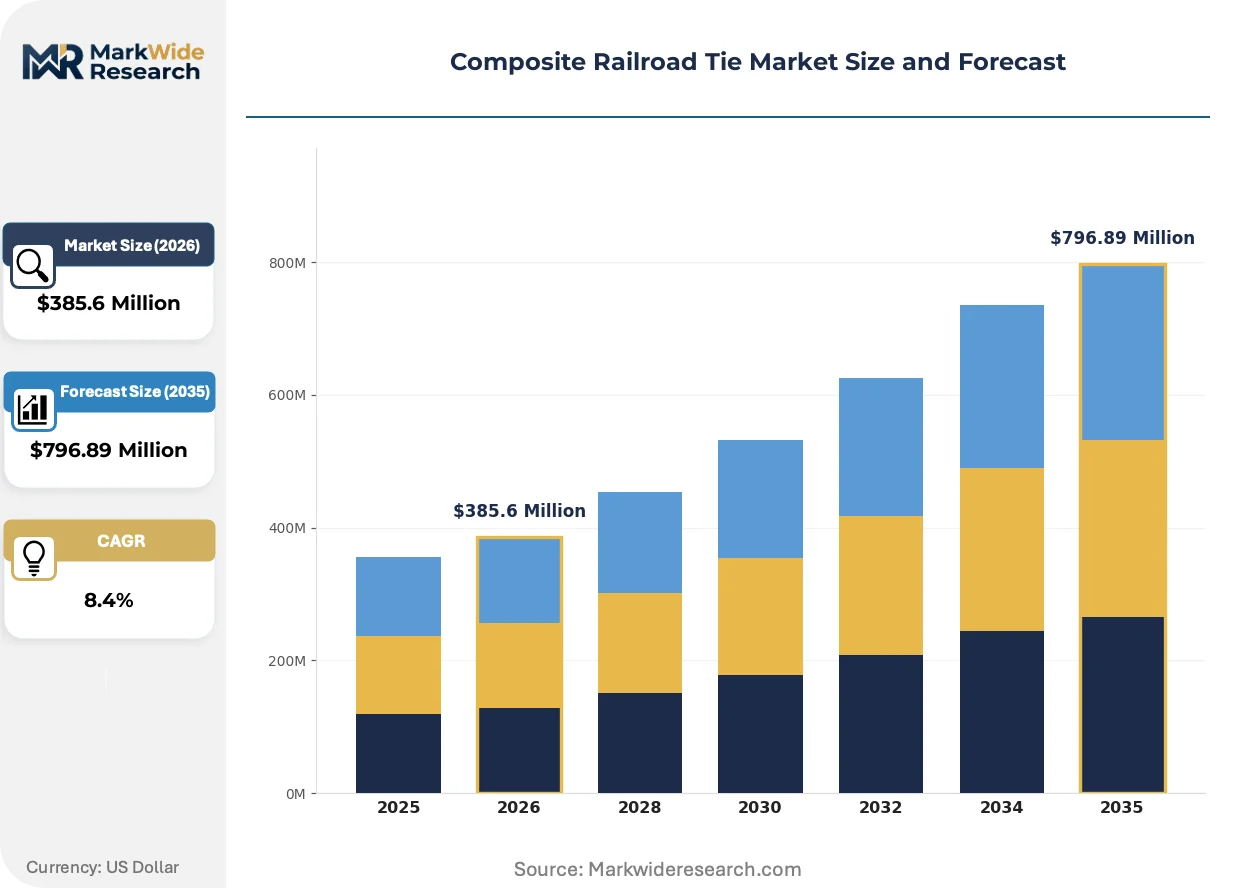
Market Dynamics
Class I railroad procurement departments are rewriting material specifications as EPA creosote discharge limits tighten and axle loads climb past 36 tons on heavy haul corridors. The shift from timber to engineered composites is compressing traditional supply relationships and forcing qualification programs that favor integrated polymer compounders over distributors.
Growth Catalysts
- EPA Creosote Discharge Regulations:Federal limits on preservative leaching from wooden cross-ties are disqualifying traditional suppliers from Class I capital budgets and accelerating composite qualification timelines.
- Heavy Haul Axle Load Escalation:Freight operators running 286,000-pound carloads demand flexural performance that timber cannot sustain across compressed replacement cycles.
- Recycled Feedstock Availability:Post-consumer polyethylene and rubber crumb supply chains in the United States have matured to support consistent polymer compounding at railroad tie scale.
Market Restraints
- Resin Price Volatility:Fluctuations in virgin polyethylene and fiberglass roving costs compress margin predictability for compounders lacking backward integration into resin production.
- Capital Intensity of Pultrusion Lines:Continuous fiber reinforcement equipment requires eight-figure capital deployment that fragments the vendor base between integrated producers and speculative entrants.
- Timber Substitution Economics:Short-term creosote-treated tie availability at distressed pricing in secondary markets delays composite conversion decisions among capital-constrained short-line operators.
Strategic Opportunities
- Maintenance Retrofit Channels:Timber tie rejection rates exceeding 15 percent annually on high-tonnage routes create replacement volume independent of new track construction.
- Hybrid Concrete-Composite Architectures:CXT-style integrated designs that blend compression zones with polymer tensile elements open specification slots previously reserved for pure concrete or pure timber.
- State-Level Environmental Mandates:California and New York procurement rules banning creosote in public infrastructure projects are forcing composite qualification ahead of federal deadlines.
Industry Challenges
- AREMA Certification Timelines:Extended laboratory testing and field performance validation periods delay revenue recognition for new compound formulations by 18 to 36 months.
- Track Geometry Integration:Composite tie elastic modulus mismatches with legacy ballast systems require recalibrated tamping procedures and specialized maintenance equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Railroad Tie Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood-Plastic Composite, Recycled Rubber, Others Application: Track Construction, Maintenance, Heavy Haul, Light Rail End User: Railroads, Contractors, Municipalities, Private Operators Performance Criteria: Durability, Weight, Cost Efficiency, Environmental Impact |
| Companies Covered | RailWorks Corporation, CXT Concrete, Koppers Inc., Composite Technologies, Plastics Engineering Company, Trelleborg AB, Vossloh AG, Graham Manufacturing, Evertrak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Railroad Tie Market Strategic Shifts
Material science advances and procurement digitization are converging to reshape how railroads specify, source, and deploy permanent way components. Three distinct vectors are compressing traditional supply cycles and elevating performance requirements.
Fiberglass-reinforced polyurethane pultrusion is supplanting unreinforced recycled plastic extrusion in heavy haul applications. Class I engineering departments specify continuous fiber architectures for mainline curves exceeding 5 degrees. The technology is compressing supplier margins on commodity-grade extruded ties while rewarding compounders with captive pultrusion capacity.
ASTM D790 flexural testing protocols are hardening into de facto procurement gatekeepers. Rail capital committees now require third-party certification before budget allocation, eliminating informal vendor relationships. Heavy haul segments in the United States face the steepest compliance burden as FRA track safety audits intensify.
Long-term performance warranties are displacing spot purchasing in Class I procurement departments. Union Pacific and BNSF negotiate decade-long tie replacement programs with compounders bearing full lifecycle liability. This shift concentrates volume with vertically integrated suppliers capable of underwriting field performance risk.
Composite Railroad Tie Market Segmentation
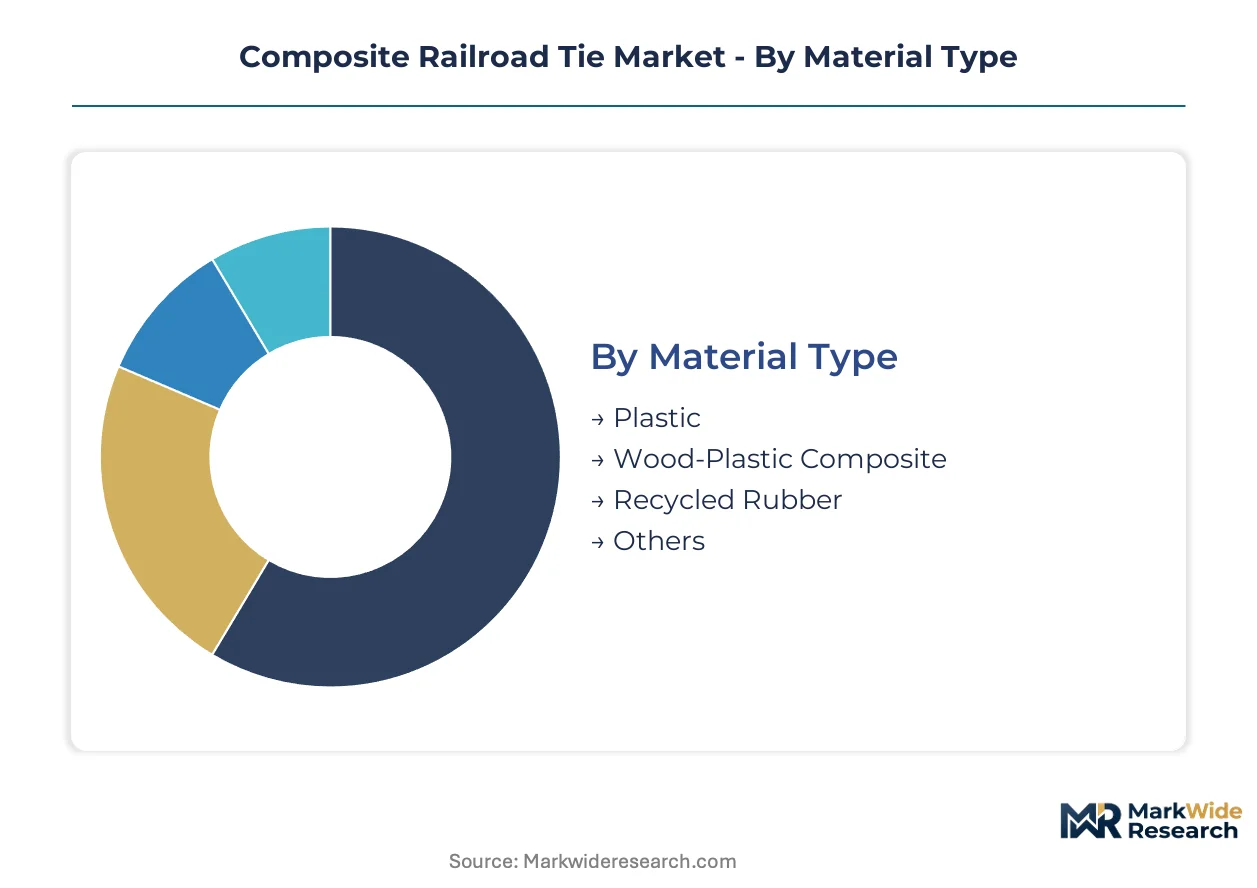
Composite railroad tie procurement divides sharply between legacy timber substitution and performance-specified new installations. Segmentation clarity determines which compounders qualify for Class I capital budgets versus short-line commodity sourcing.
Material Type:
Substitution pressure from creosote-treated timber hits recycled rubber hardest on cost grounds, while plastic formulations face downstream pressure from wood-plastic hybrid advances.
- Plastic:Formulations based on high-density polyethylene and fiberglass reinforcement dominate installed base across Union Pacific and BNSF mainlines. Demand concentrates in heavy haul corridors where 286,000-pound carloads require flexural modulus exceeding 500,000 psi. Virgin resin price volatility remains the critical margin constraint.
- Wood-Plastic Composite:Blends combining post-industrial wood fiber with thermoplastic binders bridge timber aesthetics with composite performance. California and New York municipalities specify these for light rail projects under state-level creosote bans. Moisture absorption rates in freeze-thaw cycles create qualification delays.
- Recycled Rubber:Crumb rubber from tire recycling offers superior damping characteristics for urban transit vibration control. Noise-sensitive applications in Chicago and Philadelphia transit authorities drive niche specification.
- Others:Emerging polyurethane and bio-based formulations from agricultural waste feedstocks occupy pre-qualification testing phases at AREMA laboratories.
Plastic anchors the volume base while wood-plastic composite gains share at the steepest rate.
Application:
Cost tier separation between capital-intensive new track and maintenance-driven replacement determines procurement channel access and margin structure.
- Track Construction:Greenfield mainline projects specify pultruded fiberglass-reinforced ties with 50-year design life. Class I engineering departments bundle these into billion-dollar corridor modernization programs.
- Maintenance:Timber tie rejection rates exceeding 15 percent annually on high-tonnage routes generate replacement volume independent of new construction cycles. Norfolk Southern and CSX maintenance-of-way departments accelerate composite conversion here.
- Heavy Haul:Axle loads above 36 tons demand continuous fiber architectures that commodity extruders cannot supply. Integrated compounders with captive pultrusion capacity capture premium positioning.
- Light Rail:Transit agencies in Boston, Denver, and Portland specify lower-density composites for embedded track in street-running configurations. Aesthetic surface treatments and electrical isolation properties drive specification.
Maintenance commands the largest addressable volume while heavy haul delivers the highest revenue per tie.
End User:
Customer type concentration shapes specification authority and contract structure across the vendor base.
- Railroads:Class I operators wield unilateral specification power through AREMA manual compliance requirements. BNSF and Union Pacific negotiate decade-long performance warranties with full lifecycle liability transfer.
- Contractors:Engineering-procurement-construction firms serving secondary markets source commodity-grade extruded ties through distributor relationships. Price sensitivity limits qualification investment.
- Municipalities:Transit authorities in California, New York, and Washington operate under procurement rules banning creosote in public infrastructure. Environmental mandate compliance overrides first-cost considerations.
- Private Operators:Short-line and industrial railroads face capital constraints that delay composite conversion despite timber rejection rate acceleration. Distressed creosote tie availability in secondary markets sustains substitution economics.
Railroads anchor procurement volume while municipalities expand specification fastest under regulatory pressure.
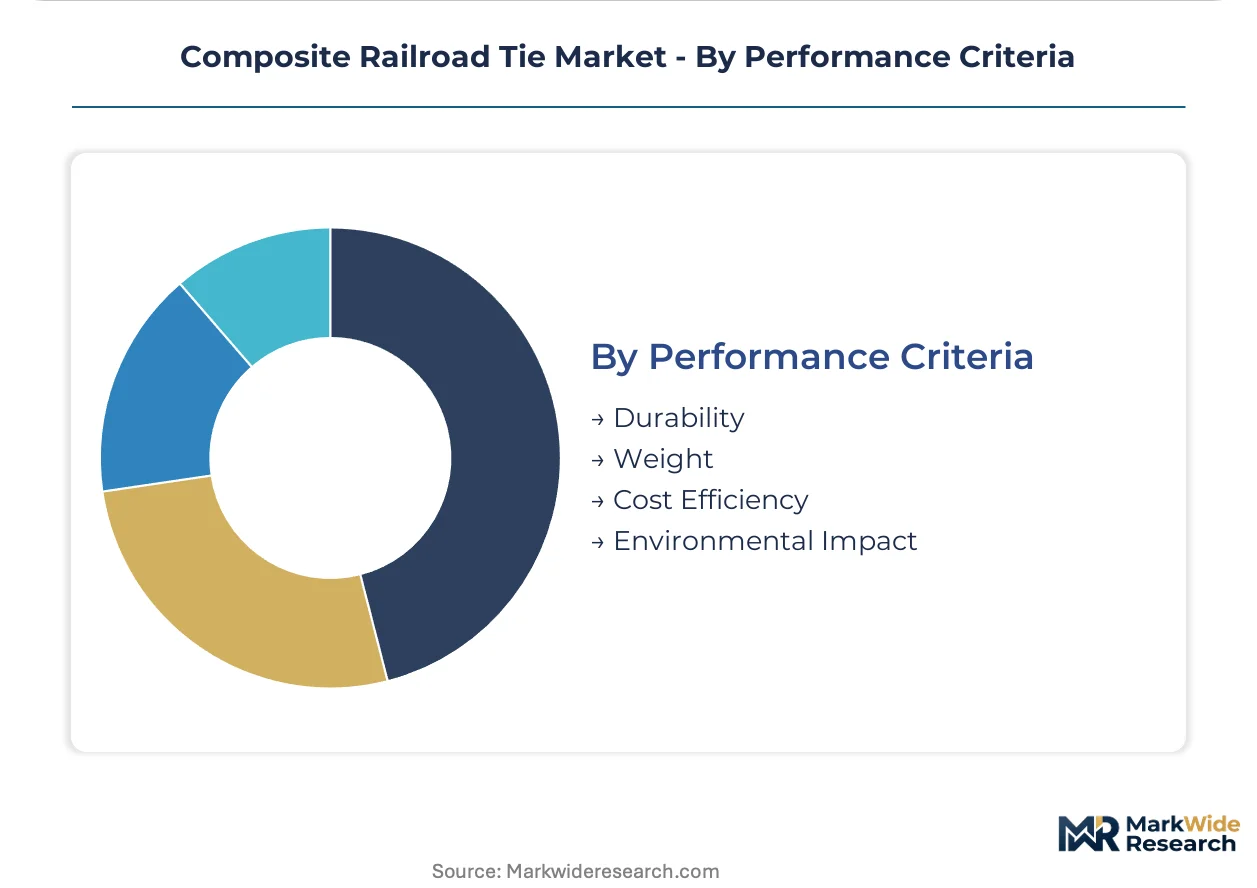
Performance Criteria:
Maturity differentiation separates specification-grade certification from commodity sourcing tiers.
- Durability:ASTM D790 flexural strength retention after accelerated weathering determines AREMA qualification eligibility. Third-party certification gates Class I capital budget access.
- Weight:Density advantages over concrete enable manual handling in remote maintenance locations. Union Pacific specifies weight-classified ties for mountain territory accessibility.
- Cost Efficiency:Lifecycle cost modeling incorporating reduced tamping frequency and extended replacement intervals favors composites in total-cost-of-ownership analyses.
- Environmental Impact:EPA creosote discharge regulations and state-level procurement bans elevate leachate-free performance to threshold specification status.
Durability remains the non-negotiable specification gate while environmental impact climbs fastest in procurement priority weighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in composite railroad ties remain lopsided, with North American manufacturers supplying heavy haul specifications domestically while European and Asian producers serve transit rail niches. Trade flows concentrate where regulatory pressure on creosote elimination runs strongest.
United States
Class I railroads BNSF and Union Pacific drive specification authority through decade-long performance warranty programs. EPA creosote discharge regulations under the Clean Water Act tighten allowable preservative thresholds annually. Chicago and Houston serve as procurement coordination hubs where maintenance-of-way departments aggregate tie replacement volumes.
Germany
Deutsche Bahn's infrastructure modernization programs specify composite alternatives for noise-sensitive urban corridors. ECHA REACH regulations restrict creosote use in railway applications, accelerating composite qualification timelines. The Ruhr industrial cluster hosts compounders supplying cross-border heavy haul networks into Poland and the Netherlands.
China
State Railway Group's high-speed rail expansion creates demand for vibration-damping tie solutions on passenger-dedicated lines. MIIT national standards for railway materials increasingly reference recycled polymer content requirements. The Yangtze River Delta manufacturing corridor concentrates pultrusion capacity serving domestic and Southeast Asian export markets.
Canada
Canadian National and Canadian Pacific Kansas City integrate composite ties into transcontinental heavy haul routes crossing permafrost zones where timber degradation accelerates. Health Canada and PMRA regulate wood preservative discharge under federal environmental protection statutes. Calgary and Winnipeg anchor prairie-region procurement for cold-climate performance validation.
India
Indian Railways targets composite tie deployment on dedicated freight corridors handling 32.5-ton axle loads. BIS railway material standards are under revision to incorporate polymer-composite performance criteria. The Dedicated Freight Corridor Corporation's Western and Eastern route projects concentrate initial specification trials near Delhi and Mumbai industrial zones.
Composite Railroad Tie Market Competitive Environment
Listed infrastructure conglomerates compete with private polymer compounders across specification authority and material science capabilities. Market structure tilts toward integrated producers with captive resin compounding and pultrusion capacity. Three archetypes dominate: vertically integrated compounders controlling formulation-to-finished-tie production, concrete-tie incumbents bridging hybrid designs, and specialized recyclers leveraging post-consumer feedstock access. Competitive moves center on AREMA certification acceleration and long-term performance warranty underwriting.
Among North American integrated producers, RailWorks Corporation and CXT Concrete exemplify distinct strategic positions. RailWorks anchors the polymer-compounding archetype with in-house resin formulation control. CXT Concrete occupies the hybrid-design tier, bridging traditional concrete compression zones with polymer tensile elements. Koppers Inc. represents incumbent-transition positioning, leveraging established rail customer relationships from creosote-treated timber supply heritage.
| Leading Market Players |
|---|
| RailWorks Corporation |
| CXT Concrete |
| Koppers Inc. |
| Composite Technologies |
| Plastics Engineering Company |
| Trelleborg AB |
| Vossloh AG |
| Graham Manufacturing |
| Evertrak |
| Others |
Value Chain & Pricing Dynamics
ASTM D790 certification gates both supplier qualification and price differentiation simultaneously, separating AREMA-compliant compounders from commodity extruders while compressing margins on uncertified production. Class I railroad procurement committees allocate capital budgets exclusively to third-party-certified vendors, creating a two-tier structure where certification status overrides volume scale in pricing power.
Pricing Analysis
Class I railroads anchor a contract-based long-term offtake pricing structure, negotiating decade-long performance warranties that transfer lifecycle liability to compounders. Price differentiation stems from AREMA certification tier and captive pultrusion capacity, with integrated producers commanding premium positioning over distributor-dependent rivals. Cost compression in commodity-grade extruded ties is intensifying because resin price volatility and distressed creosote-tie availability in secondary markets sustain timber substitution economics. Short-line operators exhibit the highest price sensitivity due to capital constraints, while Class I engineering departments prioritize total-cost-of-ownership over first-cost considerations.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane and container availability constraints on trans-Pacific routes elevate inbound logistics costs for fiberglass roving and specialty resin imports. Geographic supply concentration centers on the United States, Germany, and China, with pultrusion capacity clustering in the Yangtze River Delta and the American Midwest. Raw material dependencies draw from post-consumer polyethylene feedstocks, continuous fiberglass reinforcement, and polyurethane resin systems. Single-source vulnerability in virgin resin supply creates structural risk for non-integrated compounders lacking backward integration. Distribution runs through direct Class I procurement channels for specification-grade ties, with distributor relationships serving short-line and contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance warranty underwriting and predictive maintenance analytics represent a service-attach opportunity expanding faster than hardware revenue, as Union Pacific and BNSF negotiate full lifecycle liability transfers that compounders must support with field monitoring capabilities.
For Market Incumbents: Shield AREMA-qualified market position by accelerating certification timelines for next-generation polyurethane formulations before specification lock-in periods close. Deepen captive pultrusion capacity in the American Midwest to defend against resin price volatility and emerging hybrid concrete-composite entrants. Certification investment remains the critical defensive lever as EPA creosote discharge regulations tighten procurement eligibility. For New Entrants and Emerging Players: AREMA fast-track programs for wood-plastic composite formulations open specification slots in California and New York transit markets where state-level creosote bans override federal timelines. Target municipal light rail procurement channels in Boston, Denver, and Portland, where aesthetic surface treatments and electrical isolation properties command premium positioning. A go-to-market angle anchored in recycled feedstock storytelling aligns with public infrastructure environmental mandate compliance. For Investors and Strategic Acquirers: EPA's scheduled creosote discharge threshold reductions reshape the acquisition landscape by compressing qualification timelines for timber-to-composite transition specialists. Long-term viability over a multi-year window favors vertically integrated compounders with captive resin compounding and pultrusion capacity over distributor-dependent speculative entrants. The acquisition target archetype combines AREMA certification with established Class I performance warranty relationships. Monitor timber tie rejection rate acceleration on high-tonnage routes as the inflection signal for replacement volume independence from new construction cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AREMA Certification Acceleration | Third-party ASTM D790 validation gates Class I capital budget access before specification lock-in. |
| Backward Integration into Resin Compounding | In-house polymer formulation control insulates margin predictability from virgin polyethylene volatility. |
| Performance Warranty Underwriting | Decade-long lifecycle liability transfer aligns compounder incentives with Union Pacific and BNSF procurement. |
| Hybrid Concrete-Composite Development | CXT-style integrated designs bridge traditional compression zones with polymer tensile elements. |
| Maintenance Retrofit Channel Expansion | Timber tie rejection rates exceeding 15 percent annually generate replacement volume independent of greenfield construction. |
Study Parameters
A standing panel of Class I railroad procurement directors, AREMA laboratory technical leads, polymer compounding plant managers, and maintenance-of-way engineering supervisors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FRA track safety standards, EPA creosote discharge regulatory filings, ASTM International certification databases, and SEC 10-K disclosures from listed infrastructure conglomerates. Bottom-up tie installation volume estimates triangulated against top-down Class I capital expenditure allocations.
Consistency checks validated volume and value outputs against external benchmarks including railway industry association maintenance expenditure surveys and polymer feedstock consumption disclosures. The analytical framework segmented the market across material type, application, end user, and performance criteria dimensions over the projection horizon. CAGRs derived from logistic diffusion modeling of timber substitution rates and regulatory compliance deadlines. Industry-specific forecast inputs incorporated axle load escalation trajectories and state-level environmental mandate adoption curves.
Underlying assumptions cover EPA regulatory timeline adherence, recycled feedstock supply chain maturity, and Class I capital budget stability, with deviation risk concentrated in resin price volatility spikes and AREMA certification timeline extensions. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Brazil Data Center Construction Market