
 China Infrastructure Market | 2026-2036
China Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
China Infrastructure Market Insights
Chinese state-owned contractors is expanding aggregate project execution capacity across transportation corridors and utility backbones. China State Construction Engineering Corporation leverages vertical integration in concrete supply and design-build contracts to sustain margin capture on megaprojects. China Communications Construction Company Limited anchors offshore and port engineering expertise, dominating marine infrastructure awards. China Railway Group Limited competes on high-speed rail turnkey delivery, extending its order book through intercity networks.
China infrastructure encompasses the physical systems, engineered structures, and utility networks that enable economic activity, typically involving reinforced concrete with specified compressive strengths of 30-60 MPa, structural steel grades Q235-Q390, and asphalt mixes designed for 15-20 year service lives in highway applications. Its primary purpose is to reduce logistics costs, connect production clusters to consumption centers, and deliver water, power, and digital services at scale. Transportation and utilities project types command the dominant share of state budget allocations, while public-private partnership funding sources attract private capital into toll roads and wastewater treatment where government fiscal capacity strains. Steel and concrete construction materials face margin compression from emission compliance costs, whereas composite materials gain traction in bridge decks and wind turbine towers demanding lighter, corrosion-resistant specifications.
MIIT sets GB standards for structural steel and cement quality that gate market access for material suppliers, while MEE enforces carbon intensity benchmarks that reshape procurement toward electric arc furnace steel and low-clinker cement blends. The country's national development regulator coordinates five-year plan targets that direct infrastructure investment into western provinces and urban agglomerations. Stakeholders must monitor which project types receive priority in forthcoming plan cycles and whether green financing instruments expand to cover construction material conversion costs.
Market Dynamics
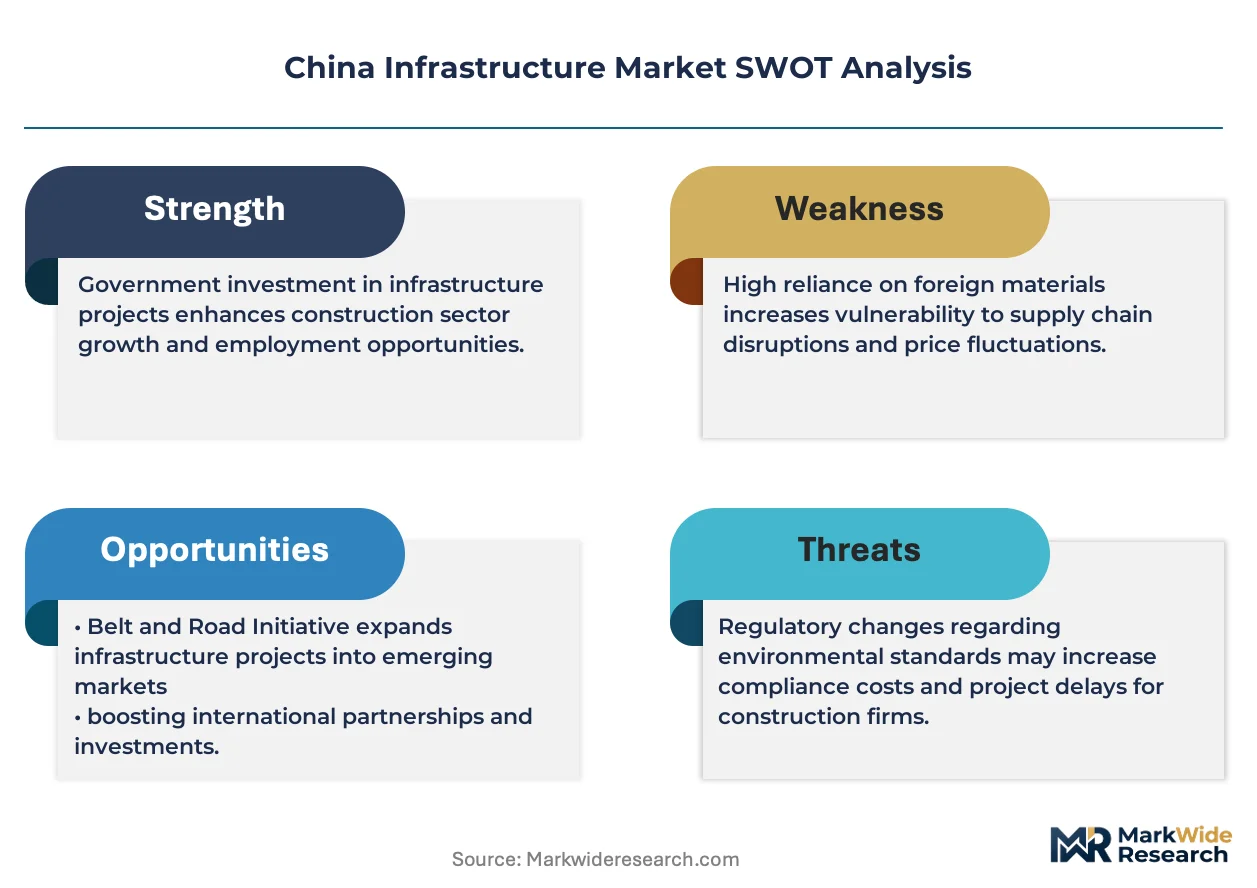
China's infrastructure market pivots on the collision between MEE carbon intensity mandates and the material throughput demands of state-led urbanization corridors. Dual carbon goals force procurement recalibration across steel and cement supply chains while megaproject timelines compress.
Growth Catalysts
- Urban Rail Capital Allocation:State budgets prioritize intercity networks in the Greater Bay Area, absorbing record fixed-asset investment flows. Guangzhou-Shenzhen-Hong Kong express corridors anchor ridership density targets.
- GB Standard Modernization:MIIT updates structural steel and cement quality thresholds, gating market access for compliant suppliers. Low-clinker cement blends gain procurement preference under revised codes.
- Western Province Connectivity:National development regulator directs five-year plan resources into Sichuan and Guizhou transportation backbones. Logistics cost reduction mandates accelerate highway and tunnel awards.
Market Restraints
- Electricity Price Volatility:Energy-intensive cement kilns face margin compression from spot power market fluctuations. Arc furnace steel operators absorb parallel cost shocks.
- Import Concentration in Premium Rebar:High-grade Q390 structural steel production clusters in coastal provinces. Inland project sites confront logistics premiums and delivery uncertainty.
- Technical Limitation in Carbon Capture:Post-combustion cement plant retrofits remain unproven at commercial scale. MEE benchmarks outpace deployable abatement technology readiness.
Strategic Opportunities
- Yangtze River Delta Expansion:Shanghai-Nanjing-Hangzhou urban agglomerations require wastewater treatment capacity doubling. Municipal fiscal strain opens PPP structures for private capital.
- Composite Material Bridge Decks:Fiber-reinforced polymer specifications displace steel in corrosion-critical coastal spans. Design-build contractors capture lifecycle cost advantages.
- Green Financing Instrument Expansion:Central bank sustainability-linked lending facilities may cover construction material conversion costs. Bond market reception for certified low-carbon concrete remains untested.
Industry Challenges
- Skilled Tunnel Boring Operation:High-speed rail turnkey delivery demands exceed trained machinery operator supply. State-owned contractors compete for finite specialist labor pools.
- Legacy System Integration:Smart sensor deployment in existing highway networks confronts incompatible traffic management protocols. Provincial procurement fragmentation blocks standardized IoT architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Infrastructure Market |
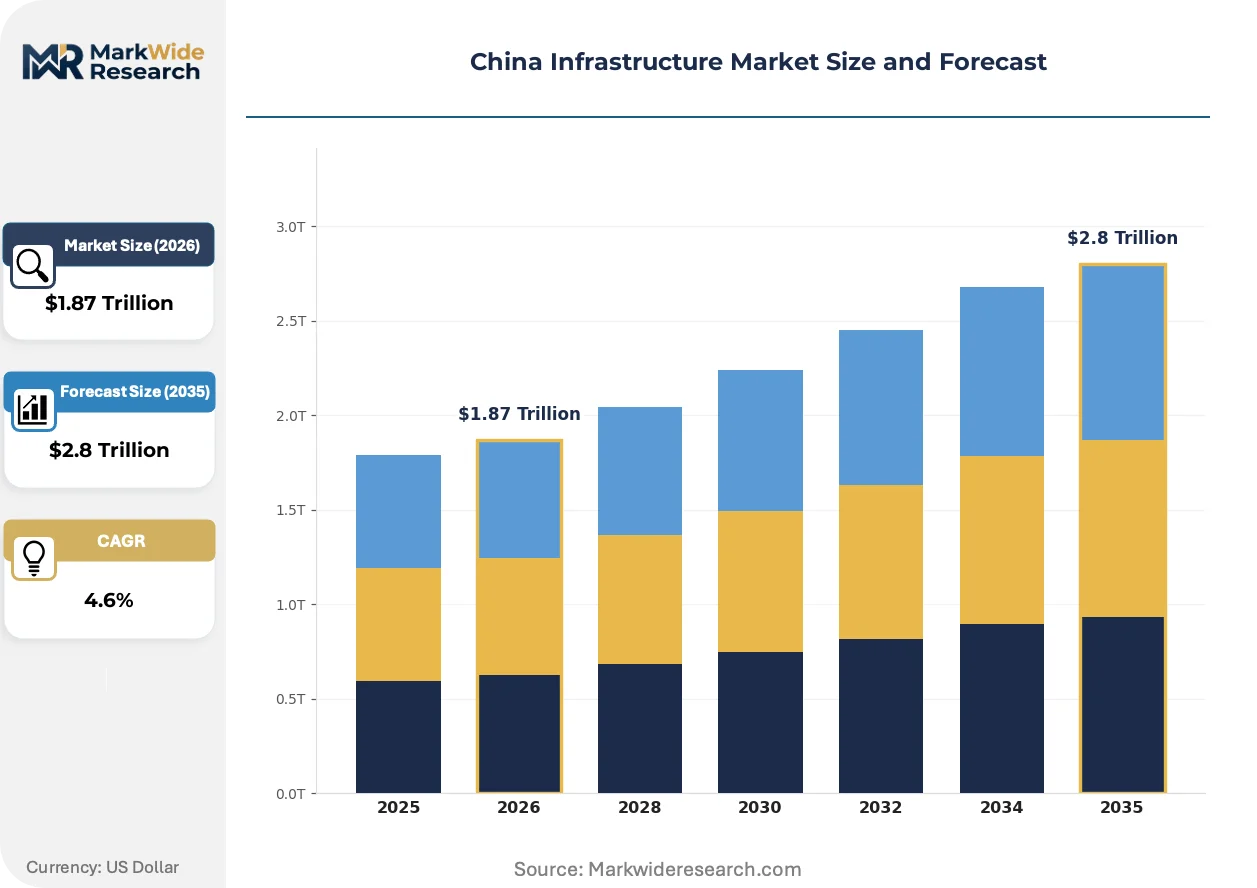
| Market Size in 2026 | $1.87 Trillion |
| Market Size in 2035 | $2.8 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Transportation, Utilities, Commercial, Residential Funding Source: Government, Private Investment, Foreign Direct Investment, Public-Private Partnerships Construction Material: Steel, Concrete, Asphalt, Composite End User: Municipalities, Developers, Contractors, Engineers |
| Companies Covered | China State Construction Engineering Corporation, China Communications Construction Company Limited, China Railway Group Limited, China Railway Construction Corporation Limited, China Electric Power Construction, State Grid Corporation of China, China National Petroleum Corporation, China Three Gorges Corporation, China Energy Engineering Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Infrastructure Market Trends and Innovations
Prefabrication and digital delivery methods are compressing traditional construction timelines in China's infrastructure sector. Material science advances and procurement digitization now reshape competitive positioning across state megaprojects.
Modular precast concrete systems are modularizing foundation and superstructure assembly for high-speed rail stations. China Railway Group and provincial transport bureaus specify factory-cast segments to minimize on-site curing delays. This shift compresses project schedules and reduces weather-dependent construction risk.
MEE dual carbon enforcement tightens emission intensity benchmarks for steel and cement procurement. Contractors must document supply chain carbon footprints or face exclusion from state tender shortlists. Low-clinker cement and electric arc furnace rebar capture preferential scoring in Greater Bay Area awards.
Digital twin platforms now accompany major transportation corridor bids. Design-build contractors embed BIM-to-asset-management handover requirements, displacing paper-based as-built documentation. Municipal clients in Shenzhen and Guangzhou mandate real-time structural health monitoring for bridges exceeding specified spans.
China Infrastructure Market Segmentation
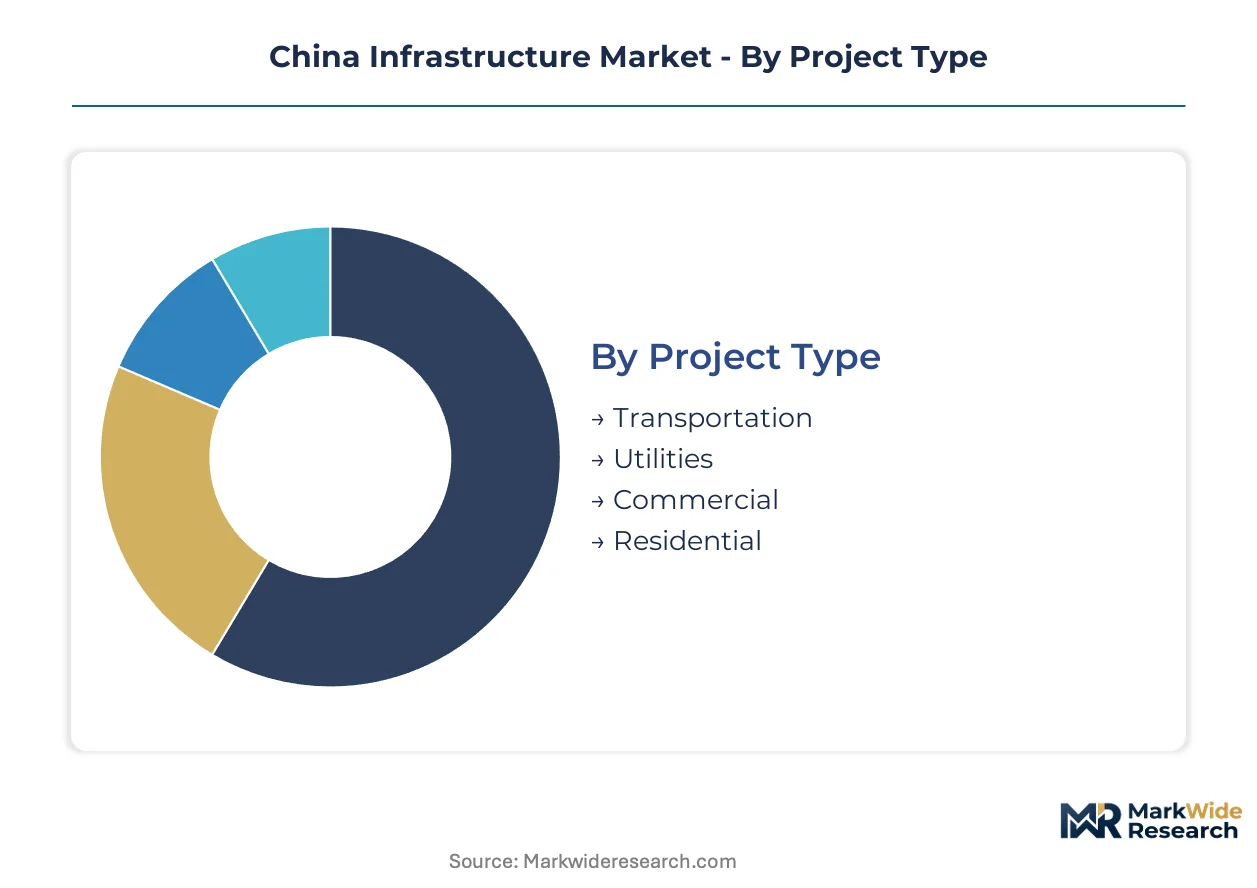
Segmentation in China's infrastructure market reveals how MEE carbon mandates and MIIT quality standards differentially burden each project category. Procurement scoring systems now weight compliance certifications alongside cost bids, reshaping competitive dynamics across material suppliers and construction consortia.
Project Type:
Transportation corridors and utility networks carry distinct certification burdens under GB standards and dual carbon enforcement protocols.
- Transportation:High-speed rail and highway projects require GB 50010 concrete compliance and MEE carbon intensity documentation for steel rebar. Demand concentrates in Greater Bay Area intercity networks where ridership density targets justify premium material specifications.
- Utilities:Wastewater treatment and power distribution infrastructure face SAMR safety certifications and provincial environmental impact approvals. Yangtze River Delta municipalities drive capacity expansion where fiscal strain opens PPP structures.
- Commercial:Mixed-use developments require fire safety GB 50016 compliance and seismic resistance certifications per regional building codes.
- Residential:Prefabricated housing projects carry MIIT modular construction standards and local habitability inspections.
Transportation sits at the top of the volume ranking, with Utilities climbing the fastest.
Funding Source:
Capital origin determines regulatory oversight intensity and approval timeline predictability across project portfolios.
- Government:State budget allocations flow through national development regulator five-year plan mechanisms with MEE environmental clearance requirements. Western province connectivity mandates absorb dominant fixed-asset investment flows.
- Private Investment:Toll road and energy infrastructure attracts domestic capital through SAMR antitrust review and provincial concession agreements. Greater Bay Area projects offer shortest regulatory pathways.
- Foreign Direct Investment:Cross-border capital faces NDRC security screening and technology transfer restrictions in critical infrastructure sectors.
- Public-Private Partnerships:Hybrid structures require Ministry of Finance value-for-money assessments and performance-based contracting frameworks.
Government funding commands the dominant share, with Public-Private Partnerships gaining share fastest in municipal wastewater treatment.
Construction Material:
Material selection locks in carbon footprint trajectories and determines MIIT GB standard compliance pathways.
- Steel:Q235-Q390 grades face MEE emission intensity benchmarks favoring electric arc furnace production. Coastal production clusters supply Greater Bay Area megaprojects with logistics cost advantages.
- Concrete:30-60 MPa compressive strength specifications incorporate low-clinker cement blends under revised GB 175 standards. Guangzhou-Shenzhen corridors specify factory-cast precast systems.
- Asphalt:15-20 year service life highway mixes require polymer modification and regional temperature grade compliance.
- Composite:Fiber-reinforced polymer bridge decks bypass corrosion inspection cycles in coastal salt exposure zones.
Steel and Concrete together absorb the dominant material budget, with Composite specifications expanding most quickly in marine infrastructure.
End User:
Client type shapes procurement sophistication and sustainability scoring weight in tender evaluations.
- Municipalities:Shenzhen and Guangzhou transport bureaus mandate BIM-to-asset-management handover and real-time structural health monitoring for major spans.
- Developers:Mixed-use project sponsors prioritize speed-to-market through prefabrication and design-build contracting.
- Contractors:State-owned construction groups maintain captive concrete supply and specialist tunnel boring equipment fleets.
- Engineers:Design institutes specify digital twin platforms and lifecycle cost optimization in corridor planning.
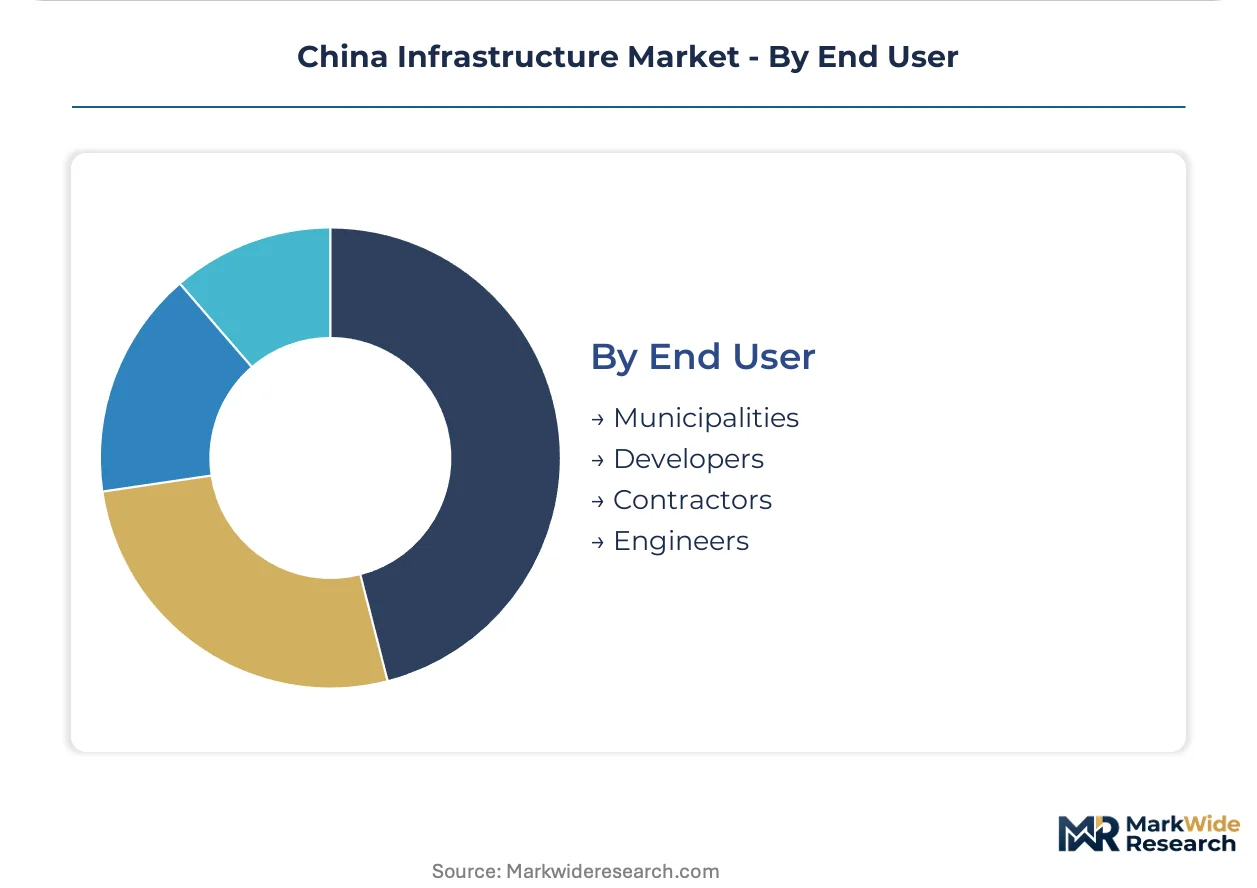
Municipalities sit at the top of the procurement volume ranking, with Contractors capturing execution margins fastest through vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward provinces offering lower carbon compliance costs under MEE benchmarks, creating arbitrage opportunities for contractors sourcing electric arc furnace steel and low-clinker cement. Western provinces attract transport infrastructure investment through relaxed procurement timelines, while coastal clusters absorb premium material premiums for Greater Bay Area megaprojects.
Guangdong Province
Guangzhou-Shenzhen-Hong Kong express corridors anchor ridership density targets for intercity rail networks. MIIT GB standard modernization gates market access for compliant steel and cement suppliers. The Pearl River Delta concentration absorbs record fixed-asset investment flows for urban agglomeration connectivity.
Sichuan Province
Western province connectivity mandates accelerate highway and tunnel awards through Chengdu-Chongqing economic circle expansion. The national development regulator directs five-year plan resources into transportation backbones reducing logistics costs. Sichuan-Chongqing cluster construction sites confront import premiums for high-grade Q390 structural steel from coastal production centers.
Jiangsu Province
Yangtze River Delta municipalities require wastewater treatment capacity doubling across Shanghai-Nanjing-Hangzhou urban agglomerations. Municipal fiscal strain opens PPP structures for private capital in utility infrastructure. Nanjing and Suzhou transport bureaus mandate BIM-to-asset-management handover for major bridge spans.
Shandong Province
Jinan-Qingdao urban rail networks absorb state budget allocations for regional connectivity under provincial five-year targets. Shandong Peninsula steel producers face MEE emission intensity benchmarks favoring electric arc furnace conversion. Qingdao port infrastructure dominates marine engineering awards through China Communications Construction Company Limited offshore expertise.
Beijing-Tianjin-Hebei
Capital region integration mandates drive high-speed rail extensions and utility backbone upgrades under coordinated planning mechanisms. SAMR safety certifications govern power distribution infrastructure expansion across the Jing-Jin-Ji corridor. Beijing municipal specifications require real-time structural health monitoring for bridges exceeding designated span thresholds.
China Infrastructure Market Competitive Landscape
Established state-owned contractors occupy the standard tier; emerging specialized entrants pursue composite material applications and digital delivery platforms. The market structure consolidates around vertically integrated construction groups with captive concrete supply and design-build capabilities. Three archetypes dominate: rail turnkey specialists with tunnel boring equipment fleets, marine engineering contractors with port authority relationships, and utility backbone builders with power sector integration. Competitive moves center on backward integration into construction materials and strategic partnerships for carbon footprint documentation systems.
Among Beijing-based state-owned construction groups, China State Construction Engineering Corporation and China Railway Group Limited exemplify the vertical integration archetype through in-house concrete production and specialist machinery fleets. China Communications Construction Company Limited occupies a position within the marine infrastructure tier, anchoring offshore and port engineering expertise for coastal megaprojects. These three entities represent the dominant competitive positioning under MEE dual carbon enforcement protocols and MIIT quality standard modernization.
| Leading Market Players |
|---|
| China State Construction Engineering Corporation |
| China Communications Construction Company Limited |
| China Railway Group Limited |
| China Railway Construction Corporation Limited |
| China Electric Power Construction |
| State Grid Corporation of China |
| China National Petroleum Corporation |
| China Three Gorges Corporation |
| China Energy Engineering Group |
| Others |
Pricing and Supply Chain Analysis
MEE dual carbon mandates gate qualified supply access and premium-tier pricing eligibility for infrastructure contractors. Low-clinker cement and electric arc furnace steel command procurement preference scoring that translates into bid premiums, while non-compliant suppliers face tender exclusion regardless of cost position.
Pricing Analysis
Direct-to-state-contractor discounts dominate material procurement, bypassing distributor markups for megaproject volumes. Three-tier pricing structure across MEE-certified premium, GB-compliant standard, and uncertified economy levels reflects carbon documentation burden and quality grade differentiation. Cost compression in standard-tier concrete intensifies because inland logistics premiums erode margin capture for non-coastal suppliers. Municipal transport bureaus exhibit highest price sensitivity, whereas state-owned contractors with captive supply chains demonstrate lowest sensitivity due to backward integration into material production.
Supply Chain Analysis
Single-source vulnerability sits with coastal province steel production clusters supplying high-grade Q390 rebar to inland western projects. Geographic supply concentration centers on Hebei, Jiangsu, and Shandong for structural steel, with Anhui and Sichuan emerging for low-clinker cement blending. Raw material dependencies rest on Australian iron ore, Mongolian coking coal, and domestic limestone reserves. Tariff exposure on premium rebar imports from Japan and South Korea threatens margin stability for specialty bridge projects. Distribution runs through state-owned trading companies with direct mill-to-site logistics contracts, minimizing third-party handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's infrastructure market functions as a geographic-arbitrage play where MEE compliance costs in coastal provinces create sourcing advantages for western province contractors with lower carbon intensity benchmarks. Regulatory divergence between provincial environmental enforcement tiers reshapes competitive positioning across material supply chains.
For Market Incumbents: Extend carbon footprint documentation capabilities to maintain tender eligibility under tightening MEE protocols. State-owned contractors should deepen backward integration into electric arc furnace steel production to secure supply chain control against import volatility. Certification investment in GB 175 low-clinker cement blends represents a defensive priority lever against emerging composite material substitutes in bridge construction.
For New Entrants and Emerging Players: MEE dual carbon enforcement in Guangdong Province opens a window for specialized carbon accounting service providers to embed into contractor procurement workflows. White-space targets include real-time structural health monitoring systems for municipal bridge portfolios and fiber-reinforced polymer decking specifications for coastal salt exposure zones. A design-build partnership route with provincial transport bureaus offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size precast concrete specialists with unexploited low-clinker conversion potential. Long-term viability over a multi-year horizon hinges on regulatory tailwinds for green financing instruments covering material conversion capex. Acquisition targets should display captive limestone reserves or electric arc furnace steel partnerships. The signal to monitor is central bank sustainability-linked lending facility expansion to construction material suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Clinker Cement | Captures MEE procurement preference scoring in Greater Bay Area tenders. |
| Electric Arc Furnace Steel Conversion | Reduces carbon intensity documentation burden for state rail contracts. |
| Digital Twin Platform Deployment | Satisfies Shenzhen and Guangzhou BIM-to-asset-management handover mandates. |
| Composite Material Bridge Deck Specification | Displaces corrosion-vulnerable steel in coastal salt exposure zones. |
| Green Financing Instrument Access | Central bank sustainability-linked facilities may cover material conversion costs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates. Primary fieldwork engaged state-owned contractor procurement directors, MEE regional enforcement officers, MIIT standards committee members, provincial transport bureau planners, and cement plant operations managers. Secondary validation drew from NDRC five-year plan documents, SAMR certification registries, China Railway Group annual disclosures, and provincial fixed-asset investment statistics. Bottom-up project pipeline aggregation and top-down macroeconomic allocation models were cross-referenced for triangulation.
Segment-weighting approaches distributed value and volume across project type, funding source, construction material, and end user dimensions. The analytical framework modeled transportation, utilities, commercial, and residential categories with differential growth trajectories across the projection horizon. CAGRs were derived from historical capital allocation patterns and policy target trajectories rather than linear extrapolation. Forecast inputs incorporated MEE carbon intensity benchmark phase-in schedules and MIIT GB standard revision timelines.
Revisions become necessary when MEE enforcement intensity deviates from provincial implementation schedules or when central green financing instrument eligibility expands beyond current pilot scope. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Global Transportation Infrastructure Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Pipeline Network Market