
 Vietnam Infrastructure Market | 2026-2036
Vietnam Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Infrastructure Market Insights
Grade 60 rebar specification is collapsing the gap between provincial and national project standards. Coteccons Construction JSC leverages its integrated design-build capability to dominate high-rise commercial complexes in Ho Chi Minh City. Hoa Binh Construction Group JSC anchors its position through specialized hospital and education infrastructure expertise. Vietnam Expressway Corporation (VEC) controls the longest contiguous expressway development pipeline in Southeast Asia.
Vietnam infrastructure encompasses civil engineering systems including transport networks, power transmission, water treatment, and telecommunications backbone, typically engineered to Vietnamese Standard TCVN load specifications and tropical climate durability parameters. Roads and bridges command the largest project-type allocation as the Ministry of Transport prioritizes north-south expressway continuity, while precast construction methods are gaining fastest traction among contractors seeking to compress pour cycles in monsoon-affected zones. Steel and concrete together absorb the dominant material-type spend, though asphalt specifications are tightening for high-axle-load freight corridors.
The Ministry of Construction enforces TCVN structural codes that mandate seismic design for Class I bridges, while the Prime Minister's Decision 262 approves master planning that directs public investment toward lagging Mekong Delta provinces. Provincial People's Committees now require environmental impact assessments for infrastructure exceeding defined capital thresholds, tightening market access for underqualified bidders. Stakeholders must track how the national power development plan revision reallocates transmission spending between state utility EVN and private independent power producers.
Market Dynamics
Grade 60 rebar adoption is compressing design cycles across Vietnam's bridge and high-rise segments, forcing provincial contractors to retool quality systems or exit Class I project eligibility.
Growth Catalysts
- North-South Expressway continuity mandate:The Ministry of Transport's lane-kilometer targets are pulling precast yard investment into central provinces.
- TCVN seismic code expansion:Class I bridge classification now covers structures above 100-meter spans, widening the addressable project pool for certified designers.
- Red River Delta logistics density:Haiphong container throughput growth is accelerating demand for load-rated freight corridors linking deepwater terminals to inland clearance depots.
Market Restraints
- Steel rebar import dependency:Domestic billet capacity shortages force project managers to absorb ASEAN spot price volatility through escalator clauses.
- Environmental licensing bottlenecks:Provincial People's Committee EIA thresholds are extending pre-construction timelines by 8-14 months on capital-intensive transport projects.
- Precast fabrication concentration:Three-quarters of certified yard capacity sits within 150 kilometers of Ho Chi Minh City, inflating logistics costs for northern corridor bids.
Strategic Opportunities
- Mekong Delta provincial backlog:Decision 262 directs public investment toward Ca Mau and An Giang, where transport infrastructure lags national averages by 40%.
- Independent power producer transmission access:Revised power development plan rules are opening EVN monopoly corridors to private capital deployment.
- Monsoon-adaptive construction methods:Accelerated curing additives and covered pour enclosures are compressing wet-season work stoppages from 90 to 45 days.
Industry Challenges
- Seismic design certification scarcity:Fewer than 200 engineers hold TCVN Class I bridge credentials, creating bidding bottlenecks for transport megaprojects.
- Legacy asphalt specification inertia:Provincial maintenance departments resist polymer-modified binder adoption despite Ministry of Transport freight corridor mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Infrastructure Market |
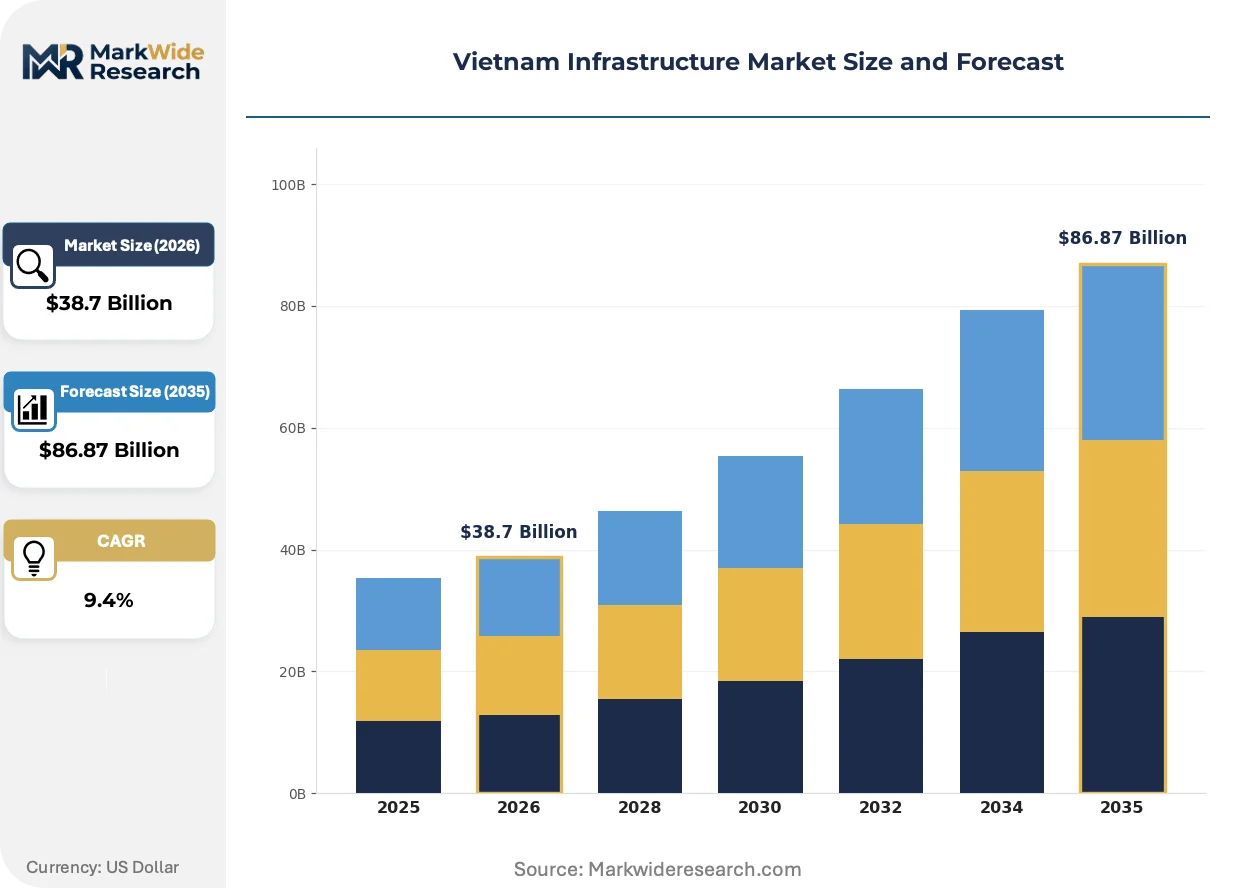
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material Type: Concrete, Steel, Asphalt, Aggregates End User: Government, Contractors, Developers, Investors Construction Method: Traditional, Modular, Precast, BIM |
| Companies Covered | Vietnam Expressway Corporation (VEC), Coteccons Construction JSC, Hoa Binh Construction Group JSC, Central Power Corporation (EVNCPC), Song Da Corporation JSC, Fecon Corp., Vinaconex, Power Construction 1 (PCC1), Petroleum Construction JSC (PVC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Infrastructure Market Trends and Innovations
Precast concrete systems, digital project delivery platforms, and procurement model evolution are restructuring how Vietnam's infrastructure contractors compete for public and private capital deployment.
BIM-integrated quantity surveying is decomposing traditional design-bid-build timelines into overlapping work packages. Tier-one contractors now model structural elements through fabrication before site mobilization, compressing pour cycles by 30% in monsoon-affected zones. This convergence is collapsing the gap between design completion and steel-rebar procurement lead times.
The Ministry of Construction's TCVN structural code amendments are mandating performance-based seismic design for all Class I bridges. Engineers must now validate ductility through nonlinear pushover analysis rather than prescriptive detailing rules. Central province contractors are responding by licensing finite element software and retraining detailers in displacement-based methods.
Build-operate-transfer concession terms are shortening from 25 to 18 years as state budget constraints shift risk to private operators. Transport developers now front-load construction finance against shorter traffic revenue recovery windows, concentrating bidding power among firms with captive equipment fleets. This compression is most visible on central highland expressway segments where geological risk premiums have widened by 200 basis points.
Vietnam Infrastructure Market Segmentation
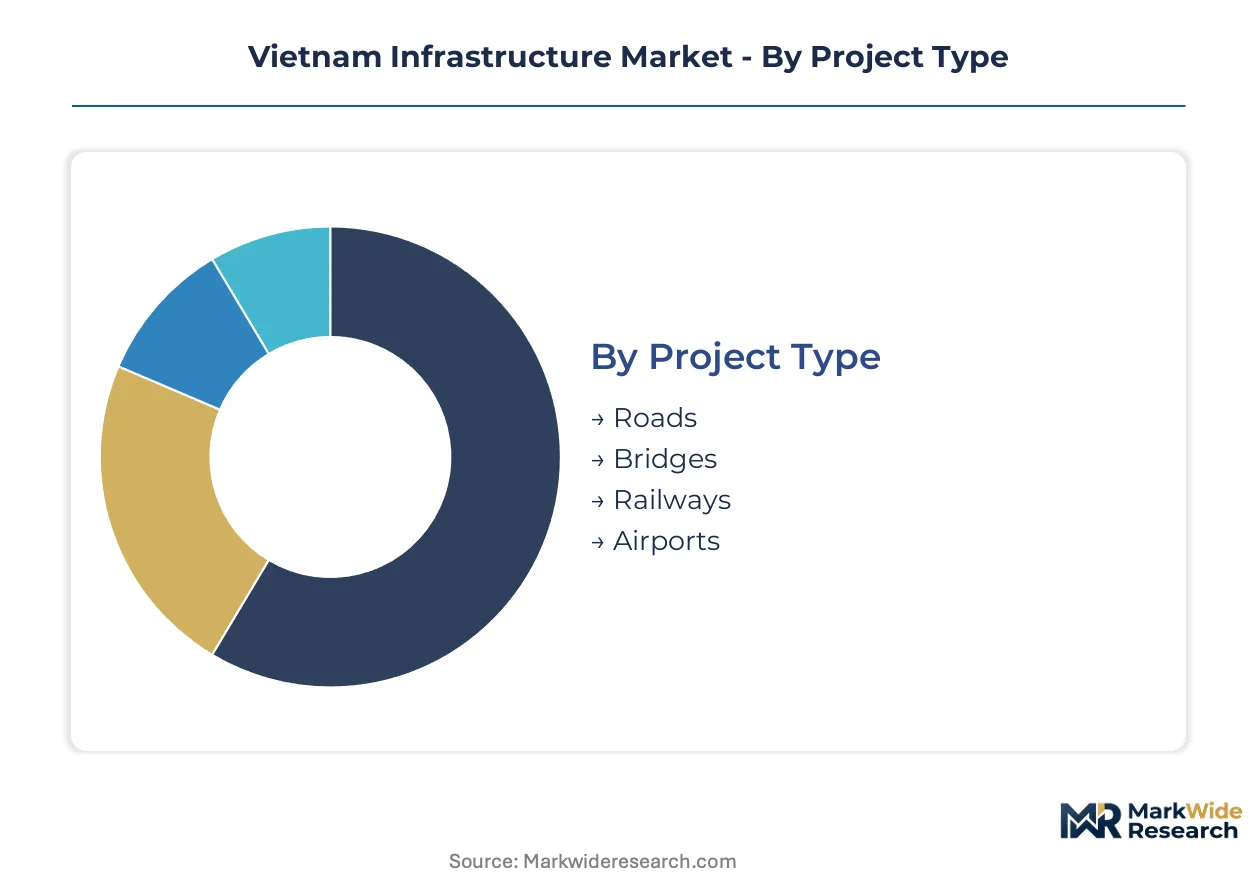
Vietnam's infrastructure segmentation reveals how procurement decisions cascade through material specifications, construction techniques, and stakeholder risk allocation. Understanding these category boundaries clarifies where contractor capabilities align with Ministry of Transport lane-kilometer targets and where capability gaps persist.
Project Type:
Roads and bridges capture the dominant margin pools in this category, driven by north-south expressway continuity mandates and TCVN seismic code expansion for Class I structures.
- Roads:Expressway and arterial corridor construction absorbs the largest capital allocation under Ministry of Transport planning. Demand concentrates in the Red River Delta corridor linking Hanoi to Haiphong, where Haiphong container throughput growth accelerates load-rated freight corridor requirements.
- Bridges:Class I bridge classification now covers structures above 100-meter spans, mandating performance-based seismic design through nonlinear pushover analysis. Central province contractors are responding by licensing finite element software and retraining detailers in displacement-based methods.
- Railways:Urban metro systems and intercity lines are gaining traction in Hanoi and Ho Chi Minh City metropolitan planning.
- Airports:Terminal expansion and runway upgrades support international passenger volume growth at Noi Bai, Tan Son Nhat, and Long Thanh.
Roads hold installed capacity. Bridges is rotating up the share rankings.
Material Type:
Cost tier differentiation separates commodity-grade inputs from specification-tightened materials required for seismic and heavy-axle applications.
- Concrete:Precast yard investment is concentrating in central provinces to serve expressway continuity targets, with accelerated curing additives compressing wet-season work stoppages. Grade 60 rebar specification is collapsing the gap between provincial and national project standards.
- Steel:Domestic billet capacity shortages force project managers to absorb ASEAN spot price volatility through escalator clauses on transport megaprojects.
- Asphalt:Polymer-modified binder adoption faces resistance from provincial maintenance departments despite Ministry of Transport freight corridor mandates for high-axle-load corridors.
- Aggregates:Crushed stone and sand sourcing is tightening around environmental licensing bottlenecks that extend pre-construction timelines.
Concrete dominates volume throughput. Steel is climbing the fastest on specification intensity.
End User:
Customer type determines risk allocation between public budget cycles and private capital deployment horizons.
- Government:Ministry of Transport and provincial People's Committees control lane-kilometer targets and environmental impact assessment thresholds. Decision 262 directs public investment toward lagging Mekong Delta provinces where transport infrastructure trails national averages.
- Contractors:Tier-one firms with integrated design-build capability and captive equipment fleets concentrate bidding power on build-operate-transfer concessions.
- Developers:Commercial and industrial park developers drive secondary road and utility networks in emerging manufacturing zones.
- Investors:Independent power producers and transport concessionaires face shortened recovery windows as BOT terms compress from 25 to 18 years.
Government holds committed pipeline visibility. Investors is gaining leverage on concession restructuring.
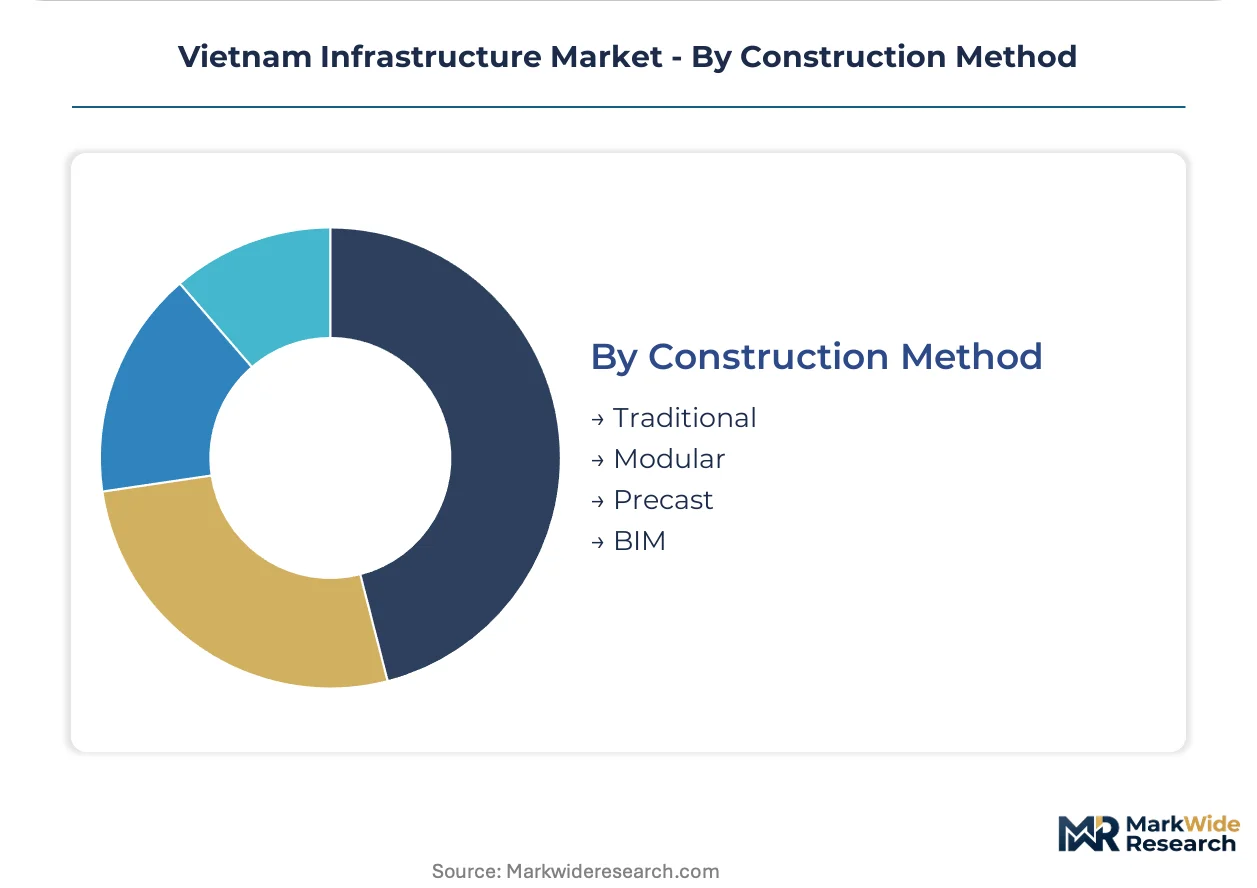
Construction Method:
Technology maturity separates established techniques from digitally integrated approaches compressing project timelines.
- Traditional:Cast-in-place methods retain dominance in provincial markets where precast yard proximity is uneconomical.
- Modular:Standardized bridge components and tunnel segments are reducing on-site labor exposure in monsoon-affected zones.
- Precast:Three-quarters of certified yard capacity sits within 150 kilometers of Ho Chi Minh City, inflating logistics costs for northern corridor bids. Pour cycles compress by 30% where yard access aligns with project geography.
- BIM:Digital project delivery platforms decompose design-bid-build timelines into overlapping work packages, collapsing the gap between design completion and steel-rebar procurement lead times.
Traditional retains volume foundation. BIM is expanding most quickly on timeline compression value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Vietnam's sub-regions. Northern provinces exhibit the highest price sensitivity on material specifications, while southern corridor buyers absorb premium-grade inputs for accelerated project timelines.
Red River Delta
Haiphong container throughput growth drives load-rated freight corridor demand linking deepwater terminals to inland clearance depots. Provincial People's Committees enforce environmental impact assessment thresholds that extend pre-construction timelines. Hanoi anchors precast yard investment serving expressway continuity targets northward to Lao Cai.
Northern Midlands and Mountains
Geological complexity on Lao Cai-Lang Son corridor segments widens risk premiums for transport developers. Ministry of Transport lane-kilometer targets pull precast fabrication capacity into Thai Nguyen and Vinh Phuc. Cao Bang and Ha Giang lag national infrastructure density averages by 35%, concentrating Decision 262 public investment flows.
North Central and Central Coast
Central province contractors license finite element software to meet TCVN Class I bridge seismic design mandates. Da Nang and Quang Nam concentrate three-quarters of certified precast yard capacity within 150 kilometers of Ho Chi Minh City, inflating logistics costs for northern corridor bids. Khanh Hoa and Binh Dinh absorb accelerated curing additive adoption to compress wet-season work stoppages.
Southeast
Ho Chi Minh City metropolitan planning drives urban metro system and intercity line traction. Coteccons Construction JSC leverages integrated design-build capability to dominate high-rise commercial complexes. Dong Nai and Binh Duong industrial park developers drive secondary road and utility networks for emerging manufacturing zones.
Mekong Delta
Decision 262 directs public investment toward Ca Mau and An Giang where transport infrastructure trails national averages by 40%. Can Tho anchors regional logistics demand though bridge and expressway connectivity remains sparse. Provincial contractors face Grade 60 rebar specification retooling requirements or exit Class I project eligibility.
Vietnam Infrastructure Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Vietnam's infrastructure sector. State-linked enterprises control longest contiguous expressway development pipelines through preferential land access and sovereign credit backing. Private contractors with integrated design-build capability concentrate on high-rise commercial and specialized hospital segments. The competitive arena tilts on two moves: captive equipment fleet accumulation to shorten build-operate-transfer concession recovery windows, and precast yard geographic expansion to capture central province expressway awards.
Among state-affiliated developers, Vietnam Expressway Corporation exemplifies the scale-driven archetype controlling contiguous corridor pipelines. Coteccons Construction JSC and Hoa Binh Construction Group JSC occupy positions within the integrated capability tier, with the former representing design-build commercial complex specialists and the latter anchoring hospital and education infrastructure expertise. These three names illustrate how contractor bidding power concentrates among firms with either sovereign backing or specialized technical credentials.
| Leading Market Players |
|---|
| Vietnam Expressway Corporation (VEC) |
| Coteccons Construction JSC |
| Hoa Binh Construction Group JSC |
| Central Power Corporation (EVNCPC) |
| Song Da Corporation JSC |
| Fecon Corp. |
| Vinaconex |
| Power Construction 1 (PCC1) |
| Petroleum Construction JSC (PVC) |
| Others |
Pricing and Supply Chain Analysis
TCVN structural code certification gates both contractor eligibility and bid price stratification across Vietnam's infrastructure sector, compressing margins for uncertified provincial operators while enabling premium positioning for seismic-qualified firms.
Pricing Analysis
After-sales service contracts on transport assets now anchor lifetime value capture for equipment-intensive operators. Project-based pricing dominates public procurement, with bid differentiation hinging on Grade 60 rebar certification status and captive precast yard proximity. Cost compression in northern corridor bids intensifies as logistics premiums inflate material landed costs. Provincial contractors exhibit highest price sensitivity, while integrated design-build specialists absorb premium positioning.
Supply Chain Analysis
Steel billet inventory cycles and rebar import lead times tether project timelines to ASEAN spot market volatility. Domestic supply concentrates in Thai Nguyen and Ninh Binh, with China, Japan, and South Korea filling billet shortfalls. Polymer-modified asphalt binders and finite element software licenses constitute critical import dependencies. Single-source vulnerability runs through certified precast yard concentration near Ho Chi Minh City. Distribution runs through Ministry of Transport tender portals and provincial People's Committee procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's infrastructure sector is approaching a platform-economics inflection as BIM-integrated project delivery collapses traditional design-bid-build sequencing into interoperable digital workflows.
For Market Incumbents: Fortify bidding power through captive precast yard expansion into Thai Nguyen and Vinh Phuc, offsetting logistics cost penalties on northern expressway segments. Deepen TCVN Class I bridge certification pipelines to capture seismic-mandate project pools. Retool quality systems for Grade 60 rebar specification or surrender Class I eligibility to certified competitors. For New Entrants and Emerging Players: Modular construction capability gaps in monsoon-adaptive methods present white-space entry points. Target Mekong Delta provincial backlog under Decision 262, where transport infrastructure trails national benchmarks. Lead with accelerated curing additive partnerships and covered pour enclosures to compress wet-season work stoppages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precast fabrication and captive equipment fleet accumulation. Long-term viability favors contractors with sovereign-linked concession access or specialized technical credentials in seismic design. Monitor TCVN code expansion scope as inflection signal for addressable project pool widening.| Strategic Initiative | Industry Significance |
|---|---|
| Precast Yard Geographic Expansion | Captures northern expressway awards by compressing logistics premiums on Red River Delta corridor bids. |
| TCVN Class I Bridge Certification Investment | Unlocks seismic-mandate project pools above 100-meter spans under expanded structural codes. |
| Build-Operate-Transfer Concession Restructuring | Front-loads construction finance against shortened 18-year recovery windows on central highland segments. |
| BIM-Integrated Project Delivery Adoption | Overlaps design and procurement timelines to compress pour cycles in monsoon-affected zones. |
| Mekong Delta Provincial Market Entry | Accesses Decision 262-directed public investment flows to Ca Mau and An Giang transport backlog. |
Research Methodology
The analysis maps transport networks, power transmission, water treatment, and telecommunications backbone segments, each validated through project directors at Vietnam Expressway Corporation, procurement leads at provincial People's Committees, structural engineers holding TCVN Class I credentials, and equipment fleet managers at tier-one contractors. Primary fieldwork combined with secondary validation against Ministry of Transport lane-kilometer targets, Prime Minister's Decision 262 investment flows, and EVN power development plan revisions enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include project type, material specification grade, construction method maturity, and end-user risk allocation profile. CAGRs were derived from infrastructure spend trajectories anchored to national technical standard adoption curves and public investment planning cycles. Forecast inputs incorporated monsoon seasonality impacts on pour cycles and environmental licensing timeline extensions.
Underlying assumptions cover TCVN code expansion scope, steel rebar import dependency persistence, and precast yard certification concentration, with deviation risk concentrated in ASEAN spot price volatility and provincial EIA threshold adjustments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market