
 Italy Infrastructure Investment Market | 2026-2036
Italy Infrastructure Investment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Infrastructure Investment Market Insights
A widening capability gap between engineering-heavy conglomerates and financial sponsors is unwinding traditional procurement hierarchies in Italian infrastructure. Webuild leverages its tunneling and bridge-building heritage to dominate complex transport megaprojects. Enel Group anchors the energy transition segment through grid-scale renewable and storage investments. ASTM sustains its position in motorway concessions via operational excellence across the Autostrade network.
Infrastructure investment encompasses the allocation of capital into physical systems and structures that enable economic activity, typically involving project finance structures with concession periods spanning 20-50 years and internal rate of return thresholds of 8-12%. These assets serve industrial logistics, urban connectivity, and energy security objectives for public and private beneficiaries. Transport infrastructure within the project category category captures the largest share of deployed capital, reflecting Italy's geographic position as a Mediterranean logistics bridge. Energy projects represent the fastest-expanding segment, driven by offshore wind auctions in the Adriatic and Tyrrhenian seas and hydrogen backbone development. Public-private partnership structures concentrate margin pools in construction and long-term operations phases, while pure public funding channels face execution bottlenecks.
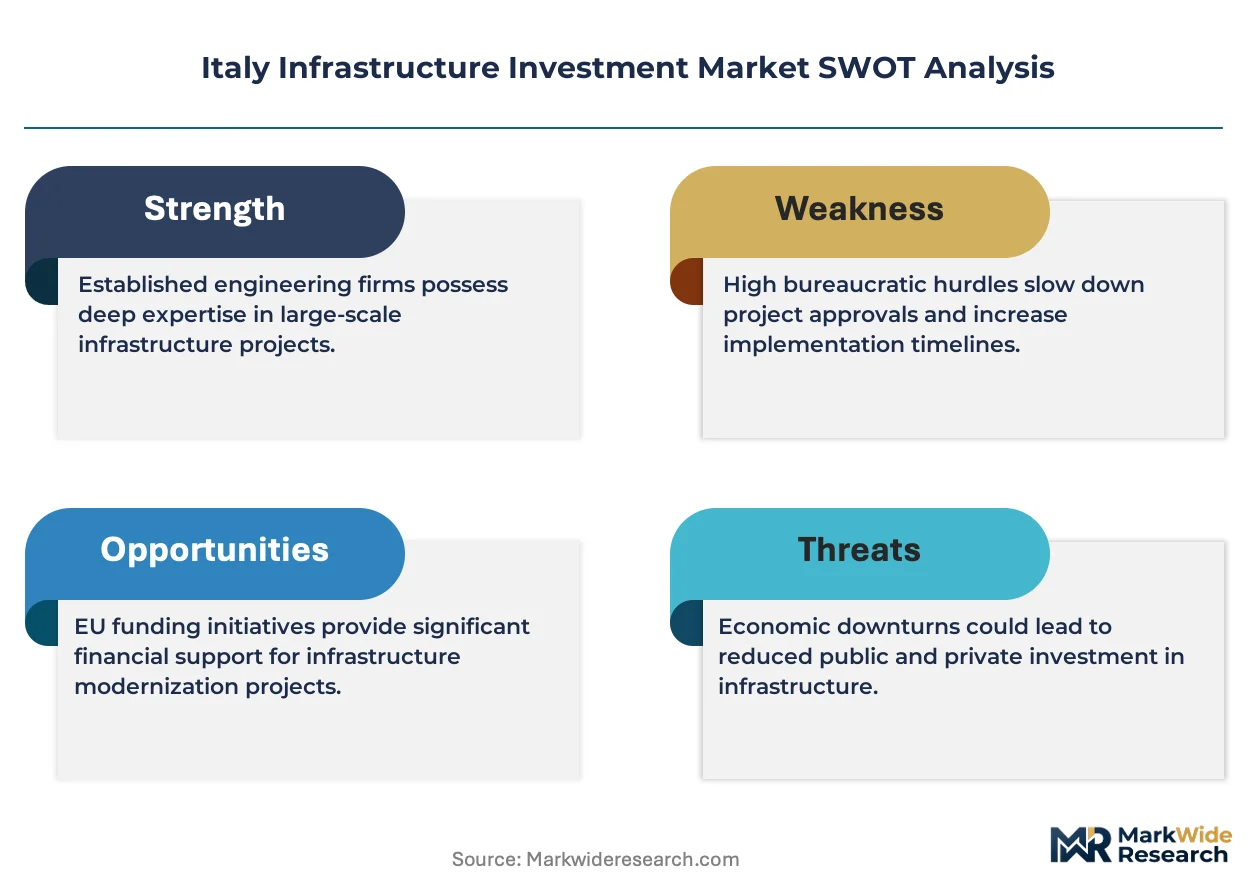
Italy's infrastructure sector operates under the oversight of ANAC, the national anti-corruption authority, which mandates transparency in public procurement above EU threshold values, while the Ministry of Infrastructure and Transport enforces technical standards aligned with EU TEN-T corridor specifications. The PNRR compliance framework requires projects to meet EU taxonomy criteria for climate adaptation and digital transition, reshaping eligibility for state guarantees and concessional lending. Stakeholders must monitor the convergence of EU cohesion fund disbursement timelines with domestic permitting reform momentum to calibrate capital deployment schedules.
Market Dynamics
Italy's infrastructure investment landscape is being restructured by the collision of EU cohesion fund disbursement timelines with domestic permitting bottlenecks, forcing capital deployment schedules to compress into narrower execution windows while project pipelines swell.
Growth Catalysts
- PNRR Fund Flows:Italy's National Recovery and Resilience Plan channels EU cohesion funds into priority transport corridors, accelerating railway modernization and hydrogen backbone development across northern industrial hubs.
- Offshore Wind Auctions:Competitive allocation rounds in the Adriatic and Tyrrhenian seas are unlocking gigawatt-scale renewable capacity, drawing institutional capital into grid-scale storage and interconnection infrastructure.
- TEN-T Alignment:Technical standards enforced by the Ministry of Infrastructure and Transport under EU corridor specifications are de-risking cross-border logistics investments along Milan-Turin-Venice arteries.
Market Restraints
- Steel and Cement Input Volatility:Construction material cost fluctuations compress margin predictability for transport megaprojects, particularly tunneling and bridge segments where fixed-price concessions dominate.
- Permitting Concentration Risk:Environmental authorization timelines cluster in regional bureaucracies, creating execution bottlenecks that delay EU fund absorption and trigger clawback provisions.
- Legacy Grid Interconnection:Transmission infrastructure limitations in southern regions constrain renewable project bankability, restricting capital flows to northern zones with existing substation capacity.
Strategic Opportunities
- Sicily-Linked Hydrogen Corridors:Underdeveloped southern logistics networks present first-mover positioning for green hydrogen export infrastructure targeting North African and Mediterranean shipping routes.
- Digital Twin Convergence:Integration of Building Information Modeling with real-time sensor networks is opening predictive maintenance revenue streams across motorway concession portfolios.
- EU Taxonomy Compliance Services:Climate adaptation and digital transition eligibility criteria under PNRR frameworks are creating specialized advisory and certification demand from project sponsors seeking state guarantees.
Industry Challenges
- Geotechnical Engineering Scarcity:Specialized tunneling and subsurface construction expertise concentrates in aging workforce cohorts, constraining execution capacity for complex Alpine and Apennine crossings.
- Concession Handover Complexity:Twenty-to-fifty-year operational phase transitions require asset condition documentation and performance warranty structures that strain sponsor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Infrastructure Investment Market |
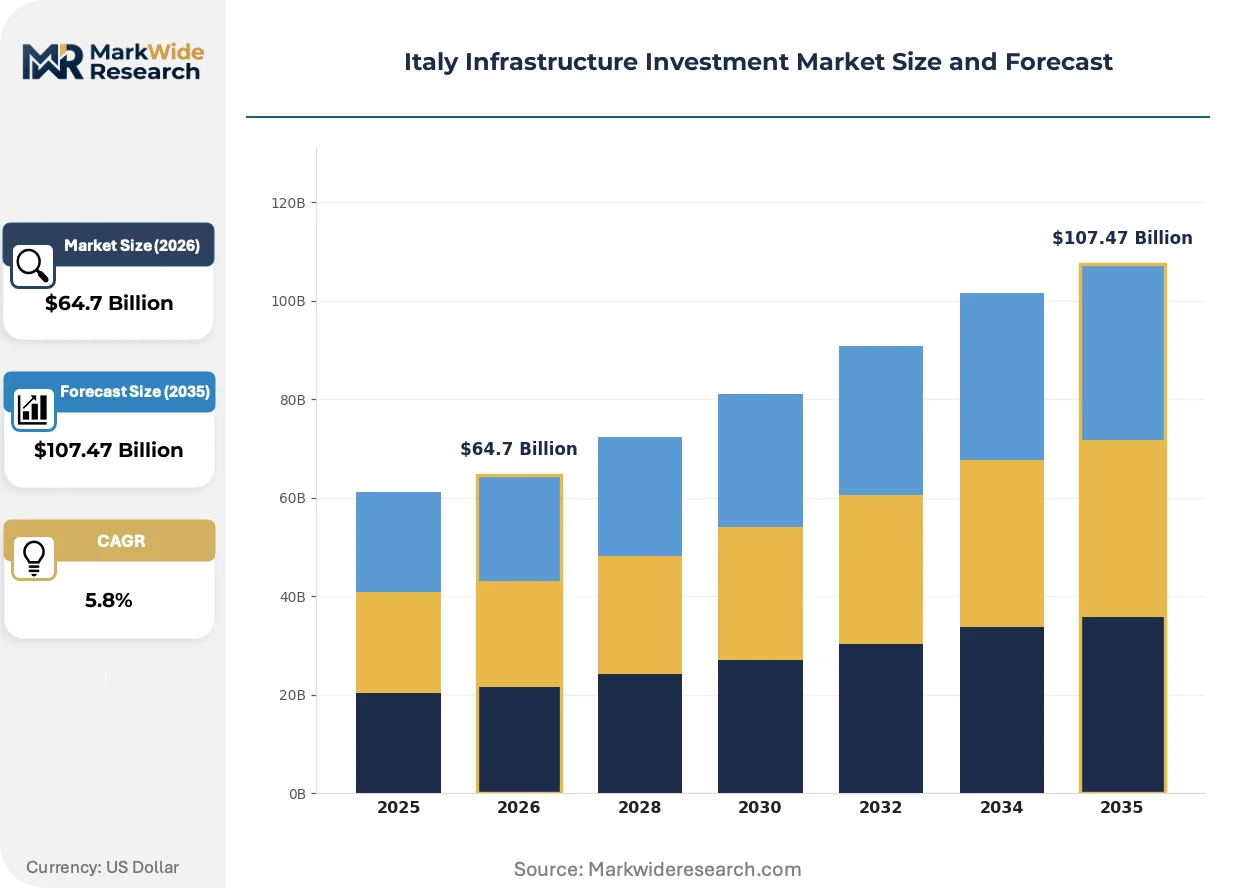
| Market Size in 2026 | $64.7 Billion |
| Market Size in 2035 | $107.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Public Funding, Private Equity, Foreign Direct Investment, Public-Private Partnership Project Category: Transport Infrastructure, Energy Projects, Water Supply, Urban Development Infrastructure Segment: Roads, Railways, Airports, Ports Funding Stage: Pre-Construction, Construction, Post-Construction, Project Planning |
| Companies Covered | ASTM, Fincantieri, Saipem, SSE plc, Caisse des Dépôts et Consignations, Webuild, Enel Group, Green Investment Group, Maire Tecnimont, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Infrastructure Investment Market Trends and Innovations
Modular construction methodologies and predictive asset management systems are compressing project delivery timelines while reshaping risk allocation between public authorities and private operators across Italian infrastructure.
Building Information Modeling is decomposing traditional design-bid-build procurement sequences by enabling real-time clash detection and quantity surveying before ground-breaking. Tier-one contractors and concession holders are mandating BIM Level 2 compliance for transport megaprojects, collapsing rework costs and accelerating environmental clearance documentation. This technology is decomposing the historical separation between engineering design and construction execution, forcing engineering-heavy conglomerates to absorb fabrication capabilities or cede margin to integrated delivery specialists.
The EU Green Deal's taxonomy criteria are reshaping eligibility for concessional lending and state guarantees by mandating climate adaptation and digital transition benchmarks. Project sponsors must now demonstrate alignment with EU taxonomy technical screening criteria to access PNRR funds, redirecting capital toward electrified rail and renewable hydrogen corridors. Transport infrastructure faces the steepest compliance burden, with motorway concessions retrofitting toll systems for carbon accounting and noise mitigation.
Long-term availability-based contracts are displacing traditional unit-price procurement in operational asset management, transferring revenue risk from public authorities to private operators. Motorway and railway concession holders are consolidating facility management and energy procurement under single-sponsor umbrellas, compressing subcontractor tiers. This consolidation is most visible along the Milan-Turin-Venice logistics triangle, where institutional investors demand integrated performance guarantees spanning construction through operations.
Italy Infrastructure Investment Market Segmentation
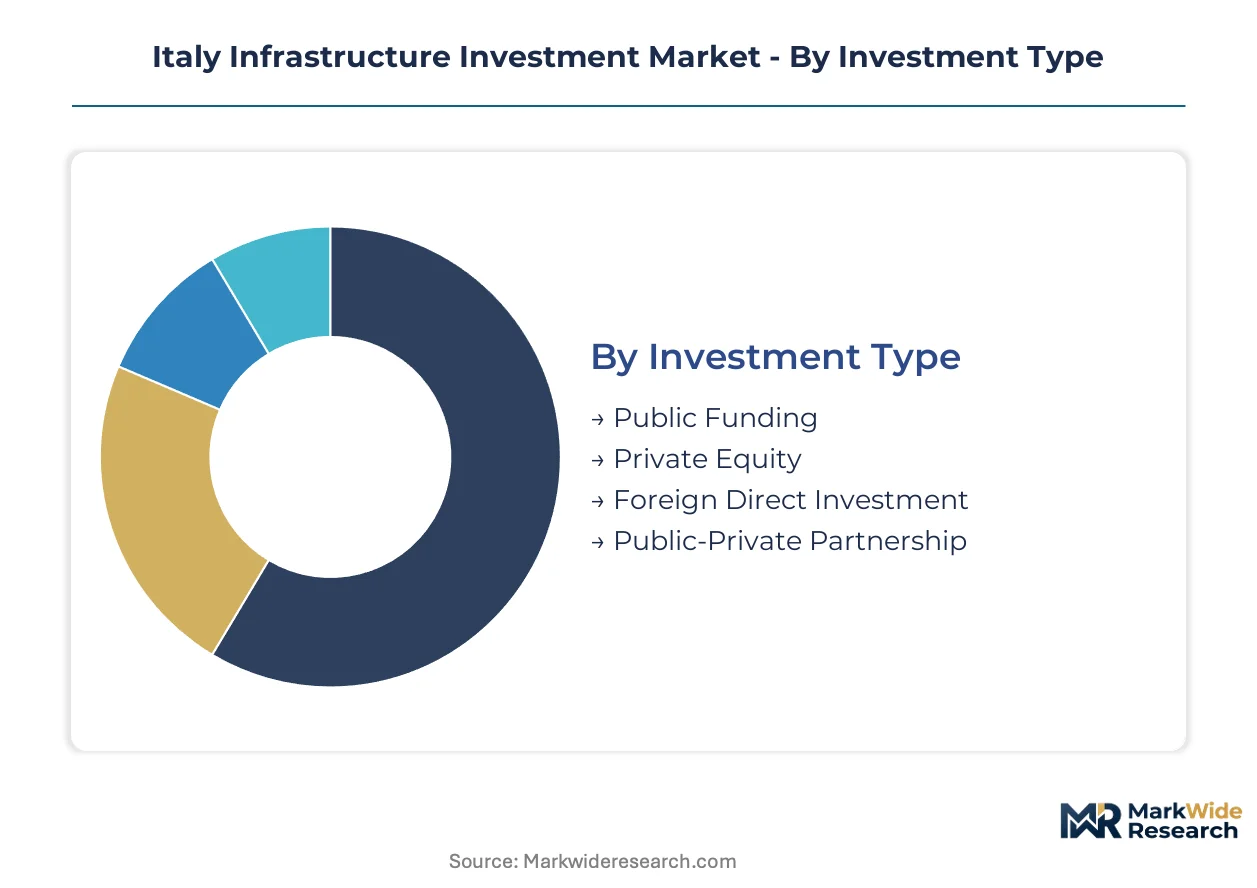
Segmentation in Italian infrastructure investment reveals how capital sources, project types, and funding phases interact with regulatory frameworks. ANAC procurement thresholds and PNRR eligibility criteria reshape allocation patterns across investor classes and asset categories.
Investment Type:
ANAC transparency mandates and EU fund absorption requirements differentiate capital deployment structures, with public procurement thresholds determining which channels dominate specific project scales.
- Public Funding:Direct state allocation channels EU cohesion funds through PNRR frameworks, concentrating in railway modernization and hydrogen backbone corridors where ANAC oversight applies above threshold values. Milan-Turin-Venice logistics arteries absorb the largest share of these flows due to TEN-T corridor alignment.
- Private Equity:Institutional capital targets operational-phase assets with 20-50 year concession structures, favoring availability-based contracts that transfer revenue risk from public authorities. Pension funds and infrastructure specialists concentrate in motorway concessions and grid-scale renewable portfolios.
- Foreign Direct Investment:Cross-border capital enters through bilateral frameworks and EU single market mechanisms, with Middle Eastern sovereign wealth vehicles and European utilities targeting offshore wind auctions in Adriatic and Tyrrhenian development zones.
- Public-Private Partnership:Concession structures concentrate margin pools across construction and long-term operations phases, with risk allocation between public authorities and private operators governed by Ministry of Infrastructure and Transport technical standards.
Established volume favors public funding; emerging adoption favors private equity.
Project Category:
Cost tier differentiation separates capital-intensive megaprojects from distributed network upgrades, with EU taxonomy compliance costs filtering sponsor capabilities across categories.
- Transport Infrastructure:Railway modernization and motorway concessions dominate deployed capital, reflecting Italy's Mediterranean logistics bridge positioning. TEN-T corridor specifications de-risk cross-border investments along northern industrial hubs.
- Energy Projects:Offshore wind auctions and hydrogen backbone development attract the steepest expansion trajectory, with grid-scale storage and interconnection infrastructure drawing institutional capital into Adriatic and Tyrrhenian zones.
- Water Supply:Regional utility consolidation and climate adaptation investments channel PNRR funds into reservoir modernization and leakage reduction networks, with southern regions presenting execution bottlenecks due to legacy infrastructure deficits.
- Urban Development:Digital twin integration and smart city infrastructure concentrate in metropolitan regeneration zones, with Building Information Modeling mandates reshaping procurement sequences for municipal project sponsors.
Transport infrastructure maintains revenue concentration; energy projects gain share fastest.
Infrastructure Segment:
Application-specific engineering requirements determine contractor specialization and margin structures, with geotechnical complexity filtering execution capacity.
- Roads:Motorway concessions across the Autostrade network generate availability-based revenue streams, with carbon accounting retrofits and noise mitigation systems responding to EU Green Deal taxonomy criteria.
- Railways:High-speed and freight corridor modernization absorbs PNRR priority funding, with Alpine and Apennine tunneling projects constrained by specialized workforce scarcity in aging engineering cohorts.
- Airports:Passenger volume recovery and cargo hub development drive terminal expansion and runway capacity additions, with northern gateways capturing disproportionate investment due to industrial logistics demand concentration.
- Ports:Mediterranean shipping route positioning supports intermodal terminal development and hydrogen export infrastructure, with Sicily-linked corridors presenting first-mover opportunities for North African connectivity.
Roads retain established concession value; railways capture emerging policy priority.
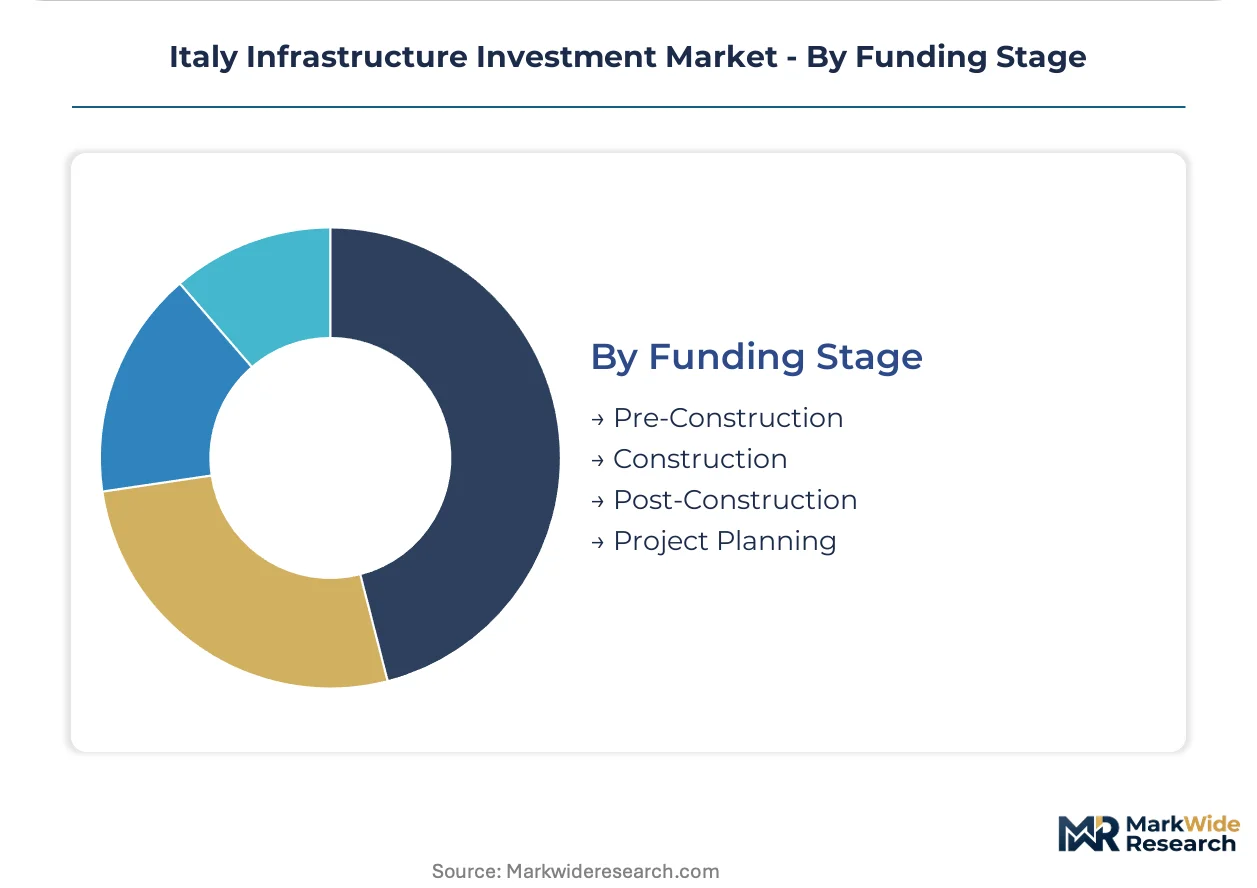
Funding Stage:
Customer-type differentiation separates development-phase advisory demand from operational-phase asset management, with risk-return profiles shifting across the project lifecycle.
- Pre-Construction:Environmental authorization and permitting services cluster in regional bureaucracies, with EU taxonomy compliance documentation creating specialized advisory demand from project sponsors seeking state guarantees.
- Construction:Fixed-price concession structures dominate transport megaprojects, with steel and cement input volatility compressing margin predictability for tunneling and bridge segments.
- Post-Construction:Twenty-to-fifty-year operational phase transitions require asset condition documentation and performance warranty structures that strain sponsor balance sheets, consolidating facility management under single-sponsor umbrellas.
- Project Planning:Digital twin convergence and predictive maintenance system integration open revenue streams across concession portfolios, with real-time sensor networks enabling outcome-based contracting models.
Construction-phase deployment holds established volume; project planning services expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Italy's northern industrial triangle show lowest price elasticity for premium logistics infrastructure, while southern regions exhibit higher sensitivity to cost overruns and extended concession timelines. This demand-elasticity divide concentrates capital deployment in Lombardy-Piedmont-Veneto corridors while constraining project bankability in Sicily and Calabria.
Lombardy
Milan anchors the Milan-Turin-Venice logistics artery where high-speed rail modernization and intermodal terminals absorb the largest PNRR transport allocations. ANAC procurement oversight applies to corridor investments above EU threshold values, mandating transparency in concession awards. The Milan metropolitan zone concentrates digital twin integration for predictive maintenance across motorway and rail portfolios.
Piedmont
Turin-based automotive supply chains drive demand for freight rail capacity and hydrogen refueling infrastructure along Alpine transit routes. Ministry of Infrastructure and Transport technical standards enforce TEN-T corridor specifications for cross-border tunneling projects. The Susa Valley corridor hosts geotechnically complex rail crossings where specialized engineering scarcity constrains execution timelines.
Veneto
Port of Venice and Mestre logistics hubs attract intermodal terminal investment targeting Adriatic shipping routes and Central European connectivity. EU Green Deal taxonomy criteria mandate climate adaptation benchmarks for port retrofitting and shore power infrastructure. The Venice-Trieste coastal zone concentrates offshore wind auction development in Adriatic lease areas.
Lazio
Rome metropolitan regeneration and Fiumicino airport expansion channel urban development capital into smart city infrastructure and terminal capacity additions. PNRR compliance frameworks require EU taxonomy alignment for state guarantee eligibility on public-private partnership structures. The Rome-Naples high-speed corridor remains a priority for residual capacity upgrades.
Sicily
Underdeveloped southern logistics networks present first-mover positioning for green hydrogen export infrastructure targeting North African shipping routes. Environmental authorization timelines cluster in regional bureaucracies, creating execution bottlenecks that delay EU fund absorption. The Messina Strait crossing and Palermo port zone anchor Mediterranean connectivity investments with constrained bankability due to legacy grid interconnection deficits.
Italy Infrastructure Investment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with engineering-heavy conglomerates dominating complex transport megaprojects while financial sponsors concentrate in operational-phase concessions. The market structure favors players with tunneling heritage and concession management capabilities over pure construction contractors. Three archetypes prevail: integrated infrastructure developers spanning design-build-operate cycles, energy transition specialists anchoring renewable and hydrogen investments, and motorway concession operators monetizing availability-based revenue streams. Competitive dynamics center on M&A consolidation of facility management capabilities and strategic partnerships securing geotechnical engineering talent.
Within the integrated infrastructure tier, Webuild and ASTM occupy positions reflecting divergent specialization vectors—Webuild represents complex civil engineering execution while ASTM anchors long-dated concession operations. Enel Group exemplifies the energy transition archetype through grid-scale renewable and storage investment platforms. These three entities illustrate how capability concentration in tunneling heritage, motorway network management, and energy infrastructure development defines competitive positioning in Italian project finance markets.
| Leading Market Players |
|---|
| ASTM |
| Fincantieri |
| Saipem |
| SSE plc |
| Caisse des Dépôts et Consignations |
| Webuild |
| Enel Group |
| Green Investment Group |
| Maire Tecnimont |
| Others |
Pricing and Supply Chain Analysis
Ninety-day steel rebar inventory cycles at northern Italian fabrication yards concentrate pricing leverage with engineering-heavy conglomerates, while cement input volatility compresses margin predictability for fixed-price concession holders across Alpine tunneling segments. This lead-time asymmetry rewards integrated players with backward integration into quarries and precast facilities, penalizing pure construction contractors exposed to spot-market commodity swings.
Pricing Analysis
Availability-based service contracts spanning twenty-to-fifty-year operational phases drive lifetime value for motorway concession holders, with revenue streams anchored in traffic-guarantee structures rather than upfront construction margins. Three-tier pricing stratification separates premium engineering consortia with tunneling heritage from standard-tier facility management operators and economy-tier maintenance subcontractors. Cost compression in cement and steel inputs is intensifying because EU carbon-border adjustment mechanisms reshape import sourcing economics. Public authorities show lowest price elasticity for complex geotechnical segments, while municipal sponsors exhibit highest sensitivity to lifecycle cost overruns.
Supply Chain Analysis
Strategic stockpiling of specialized tunnel-boring machine components dominates inventory strategy, with just-in-time procurement reserved for standardized construction materials where substitution flexibility exists. Supply concentration rests on Germany for precision engineering equipment, China for steel reinforcement, and domestic Lombardy-Piedmont fabrication clusters for precast concrete segments. Critical dependencies include high-grade cement clinker, copper cabling for electrified rail, and polymer composites for bridge deck surfacing. Single-source vulnerability concentrates in Alpine tunneling machinery where two European OEMs control specialized cutterhead technology. Distribution runs through Ministry of Infrastructure and Transport-certified logistics corridors with TEN-T corridor alignment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's infrastructure sector sits at a platform-economics inflection where Building Information Modeling interoperability standards are consolidating engineering design, construction execution, and predictive maintenance into unified data environments. This ecosystem shift rewards players who control digital twin infrastructure across concession lifecycles.
For Market Incumbents: Shield concession portfolios from margin erosion by capturing in-house geotechnical engineering capability before workforce scarcity peaks, while securing EU taxonomy compliance certification services to lock in PNRR fund access. Vertical integration into digital twin platform development anchors long-term operational phase revenue against pure construction competitors.
For New Entrants and Emerging Players: EU taxonomy technical screening fast-tracks offer entry velocity into advisory and certification demand from project sponsors seeking state guarantees. White-space targets cluster in Sicily-linked hydrogen corridor development and southern grid interconnection upgrades where legacy infrastructure deficits constrain incumbent execution capacity. Go-to-market positioning should emphasize climate adaptation documentation specialization for regional bureaucracies.
For Investors and Strategic Acquirers: Long-term, this sits as a concession-arbitrage play because twenty-to-fifty-year availability-based contracts transfer revenue risk from public authorities while inflation-linked tariff structures preserve real returns. Acquisition targets should screen for tunneling heritage and operational-phase asset management integration. The signal to watch is EU cohesion fund disbursement velocity against permitting reform momentum as inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Cement input cost control secures margin predictability for fixed-price Alpine tunneling contracts. |
| EU Taxonomy Compliance Certification | Climate adaptation documentation unlocks PNRR state guarantee eligibility for transport megaprojects. |
| Digital Twin Platform Development | Real-time sensor integration enables predictive maintenance revenue across motorway concession portfolios. |
| Geotechnical Engineering Talent Acquisition | Specialized tunneling expertise scarcity constrains execution capacity for complex Apennine crossings. |
| Hydrogen Backbone Joint Venture | Sicily-linked corridor positioning captures North African export route first-mover advantage. |
Research Methodology
A standing panel of concession operation directors, ANAC procurement compliance officers, infrastructure fund portfolio managers, and Ministry of Infrastructure and Transport technical standards specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with engineering-heavy conglomerate executives and financial sponsor due diligence teams, cross-referenced against secondary validation from EU cohesion fund disbursement records, TEN-T corridor specification documents, and PNRR implementation progress reports. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic scenario modeling.
Consistency checks validated volume and value outputs against external benchmarks including EU structural fund absorption databases and infrastructure investment tracker disclosures. The analytical framework segmented the market across investment type, project category, infrastructure segment, and funding stage dimensions, with additional modeling of regional execution capacity differentials. CAGRs were derived from project finance cash flow modeling across the projection horizon, incorporating steel and cement input cost trajectories, permitting timeline distributions, and EU fund disbursement schedule assumptions.
Underlying assumptions cover EU cohesion fund absorption rates, permitting reform momentum, and geotechnical engineering workforce availability, with deviation risk concentrated in environmental authorization timeline clustering and legacy grid interconnection bottlenecks. Revision becomes warranted when EU fund clawback provision triggers cross material thresholds or when steel-cement input volatility exceeds modeled bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Concrete Canvas Market