
 Pipeline Construction Market | 2026-2036
Pipeline Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Construction Market Outlook
The capital-intensity divergence between fully integrated EPC providers and specialized installation contractors is reorganizing competitive tiers in pipeline construction. Bechtel Corporation leverages its self-perform fabrication and construction capability to capture mega-project awards across multiple continents. Saipem S.p.A. anchors its position through deepwater pipeline installation vessels and subsea expertise. Kiewit Corporation differentiates via vertically integrated project delivery from engineering through commissioning.
Pipeline construction encompasses the engineering, fabrication, installation, and commissioning of tubular conduit systems for fluid and gas transport, typically employing API 5L-grade steel with diameters ranging from 2 to 56 inches and operating pressures up to 1,440 psi. Welding technology segments command premium margins due to automated pipeline welding systems that reduce defect rates and accelerate lay rates. Steel material categories dominate total tonnage deployed, though HDPE is displacing legacy materials in municipal water applications where corrosion resistance and trenchless installation reduce lifecycle costs. Oil and gas application segments absorb the majority of capital expenditure, with slurry transport representing a smaller but growing niche in mining logistics.
PHMSA in the United States enforces Part 192 and Part 195 safety standards that mandate integrity management programs, directly shaping inspection technology demand and coating specification requirements. The EU Green Deal and F-Gas Regulation are redirecting European pipeline investment toward hydrogen-ready infrastructure and carbon capture transport networks. Stakeholders must monitor regulatory divergence between methane emission mandates in North America and hydrogen blending standards emerging in Europe to align certification strategies with project eligibility criteria.
Market Dynamics
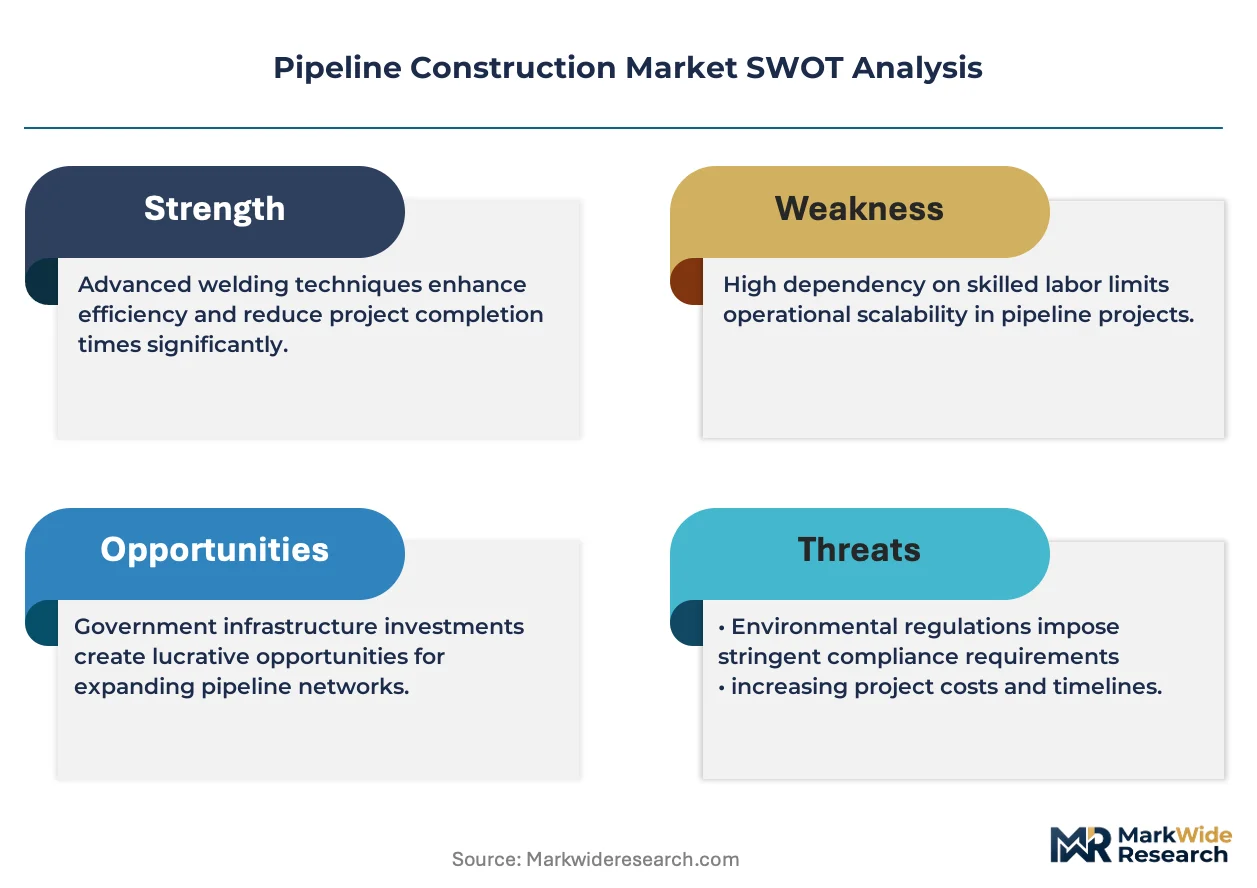
Automated welding systems are compressing project timelines and redefining labor economics across large-diameter pipeline installations. This technological inflection is redistributing margins from manual contractors to equipment-integrated EPC providers.
Growth Catalysts
- Permian Basin infrastructure gap:Midstream capacity in West Texas and southeastern New Mexico trails hydrocarbon production growth by approximately 18 months. Pipeline developers are accelerating Permian-to-Gulf Coast corridor construction to capture export arbitrage.
- EU Green Deal hydrogen readiness mandate:European operators must certify new pipelines for 20% hydrogen blending by 2030. This retrofit obligation is generating demand for high-grade steel and specialized coating systems.
- Automated orbital welding:Mechanized girth welding systems reduce defect rates below 0.5% while doubling lay rates versus manual stick welding. Contractors with automated fleets capture premium day-rate contracts.
Market Restraints
- API 5L steel price volatility:Hot-rolled coil and plate costs fluctuate with scrap metal and energy input prices. EPCs with fixed-price contracts absorb margin compression when steel prices spike.
- Specialized vessel concentration:Deepwater pipeline installation requires dynamically positioned lay barges. The global fleet numbers fewer than 25 operational units, creating scheduling bottlenecks for subsea projects.
- PHMSA integrity management mandates:Part 192 and Part 195 regulations require continuous monitoring and periodic hydrostatic testing. Compliance adds 8-12% to lifecycle operating costs.
Strategic Opportunities
- Carbon capture transport networks:Post-combustion CO2 capture projects require dense-phase pipeline infrastructure. Early movers in Louisiana and Texas industrial corridors are securing right-of-way ahead of federal 45Q credit expansion.
- HDPE municipal water replacement:Corrosion-resistant polyethylene pipe is displacing ductile iron in urban distribution systems. Trenchless horizontal directional drilling reduces surface disruption in dense metropolitan areas.
- India's National Gas Grid expansion:The Petroleum and Natural Gas Regulatory Board targets 30,000 kilometers of additional trunk lines. Domestic fabrication capacity is insufficient, creating import windows for foreign EPCs.
Industry Challenges
- Certified welding inspector shortage:AWS CWI and API 1169 qualifications require 5-7 years field experience. Training pipelines cannot replenish retirements from the 1980s construction boom cohort.
- Legacy SCADA integration:New smart pigging and fiber-optic monitoring systems must interface with decades-old control architectures. Interoperability testing delays commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Construction Market |
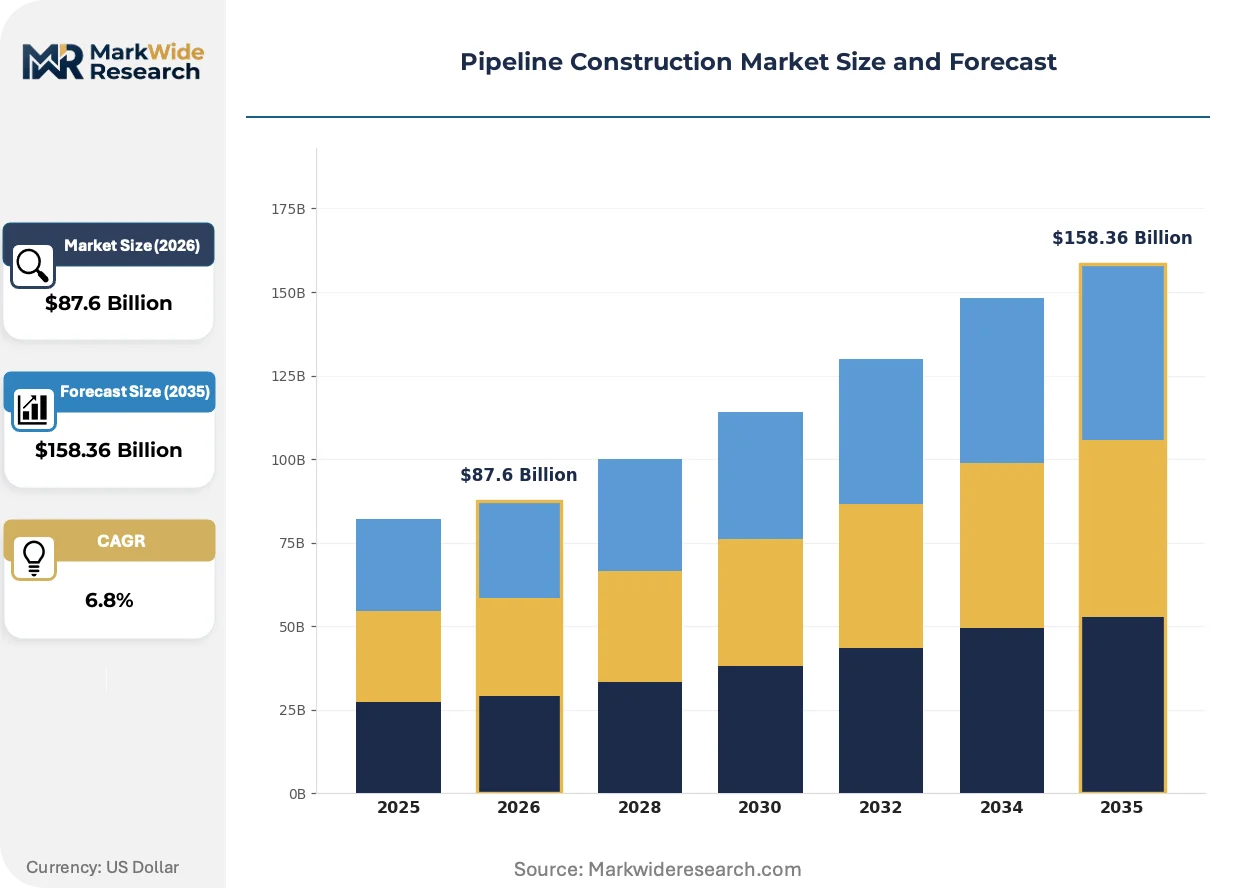
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Welding, Trenching, Coating, Inspection Material: Steel, PVC, HDPE, Ductile Iron Application: Oil & Gas, Water Supply, Wastewater, Slurry Transport End User: Energy Sector, Municipalities, Industrial Plants, Contractors |
| Companies Covered | Bechtel Corporation, Saipem S.p.A., TechnipFMC plc, McDermott International Ltd., Enbridge Inc., Kinder Morgan, Inc., TC Energy Corporation, Larsen & Toubro Limited, Kiewit Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Construction Market Strategic Shifts
Digital twin technology and predictive maintenance platforms are converging with materials science advances to redefine asset lifecycle management. These developments compress inspection intervals while extending operational horizons.
Dual-torch automated welding systems with real-time radiographic feedback are displacing conventional single-arc mechanized units. Major operators in the Gulf of Mexico and North Sea have adopted these systems for tie-in work. The technology is displacing third-party inspection subcontractors by embedding quality assurance directly into the welding process.
The EU F-Gas Regulation and delegated acts under the EU Green Deal now require methane leak detection at 0.05% sensitivity across new transmission infrastructure. This mandate accelerates deployment of aerial LiDAR and satellite monitoring constellations. European transmission system operators are retrofitting compressor stations with electrified drives to eliminate venting events.
Integrated service contracts now bundle engineering, procurement, construction, and 20-year integrity management into single-source agreements. Midstream operators in the United States are abandoning fragmented subcontracting models. This consolidation concentrates risk with EPCs but reduces interface management overhead for asset owners.
Pipeline Construction Market Segmentation
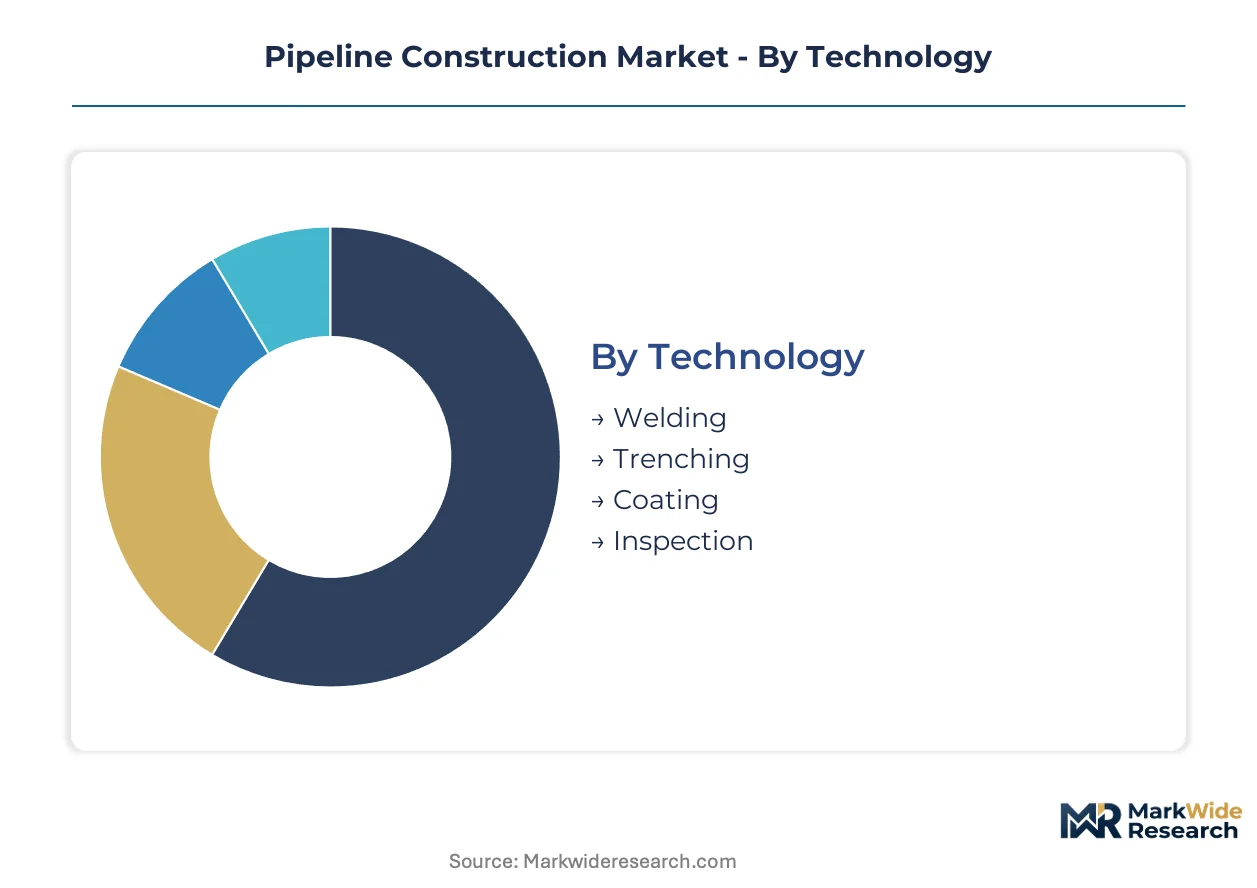
Pipeline construction segmentation reveals divergent margin profiles and capital intensity across technology tiers and material classes. Understanding these divisions exposes where automation investments concentrate and which application verticals absorb disproportionate capital expenditure.
Technology:
Domestic demand dominates welding and inspection segments tied to Permian Basin infrastructure, while coating and trenching technologies serve export-led projects across Gulf Coast export corridors.
- Welding:Automated orbital and dual-torch systems with real-time radiographic feedback embed quality assurance directly into the welding process. Demand concentrates in large-diameter oil and gas trunk lines across Texas and Louisiana, driven by labor shortage pressures and PHMSA defect-rate standards.
- Inspection:Smart pigging platforms and fiber-optic monitoring systems interface with legacy SCADA architectures. Deployment clusters around integrity management mandates under Part 192 and Part 195, particularly in mature basins requiring continuous leak detection.
- Trenching:Mechanized excavation systems support open-cut and trenchless installation methods. Projects in the Marcellus Shale and Appalachian corridor deploy these units for rocky terrain penetration.
- Coating:Fusion-bonded epoxy and three-layer polyethylene systems protect against corrosion in subsea and high-moisture environments. Offshore Gulf of Mexico developments specify these materials for 25-year design lives.
Welding holds the largest share; momentum sits with Inspection as PHMSA tightens monitoring mandates.
Material:
Cost tier stratification separates commodity-grade steel from premium corrosion-resistant alternatives, with municipal procurement favoring lifecycle economics over first-cost minimization.
- Steel:API 5L-grade carbon and alloy steels withstand operating pressures up to 1,440 psi in transmission applications. Price volatility in hot-rolled coil and plate creates margin compression risk for fixed-price EPC contracts.
- HDPE:High-density polyethylene displaces legacy materials in municipal water distribution where trenchless horizontal directional drilling reduces surface disruption. Urban replacement cycles in Houston and Phoenix drive specification shifts.
- PVC:Polyvinyl chloride serves low-pressure irrigation and drainage applications with limited temperature tolerance. Agricultural districts in California's Central Valley specify these for cost-sensitive lateral networks.
- Ductile Iron:Legacy material retains presence in water transmission mains above 24-inch diameter. Corrosion susceptibility accelerates replacement schedules in coastal environments.
Steel dominates capital deployment; HDPE is climbing the fastest on municipal lifecycle cost advantages.
Application:
Volume concentration in hydrocarbon transport contrasts with project count density in municipal water infrastructure, creating divergent customer procurement patterns.
- Oil & Gas:Crude oil, natural gas, and NGL pipelines absorb the majority of industry capital expenditure. Midstream developers in the Permian-to-Gulf Coast corridor accelerate construction to capture export arbitrage windows.
- Water Supply:Potable water transmission and distribution networks prioritize corrosion resistance and leak reduction. Metropolitan utilities in drought-stressed regions deploy large-diameter trunk replacements.
- Wastewater:Sanitary sewer and stormwater systems require pressure-rated materials for force mains. Combined sewer overflow remediation drives infrastructure upgrades in legacy Northeastern cities.
- Slurry Transport:Mining logistics applications transport mineral concentrates and tailings as dense-phase slurries. Copper and iron ore operations in Arizona and Minnesota specify abrasion-resistant linings.
Oil & Gas commands the largest capital pool; Water Supply generates the highest project velocity.
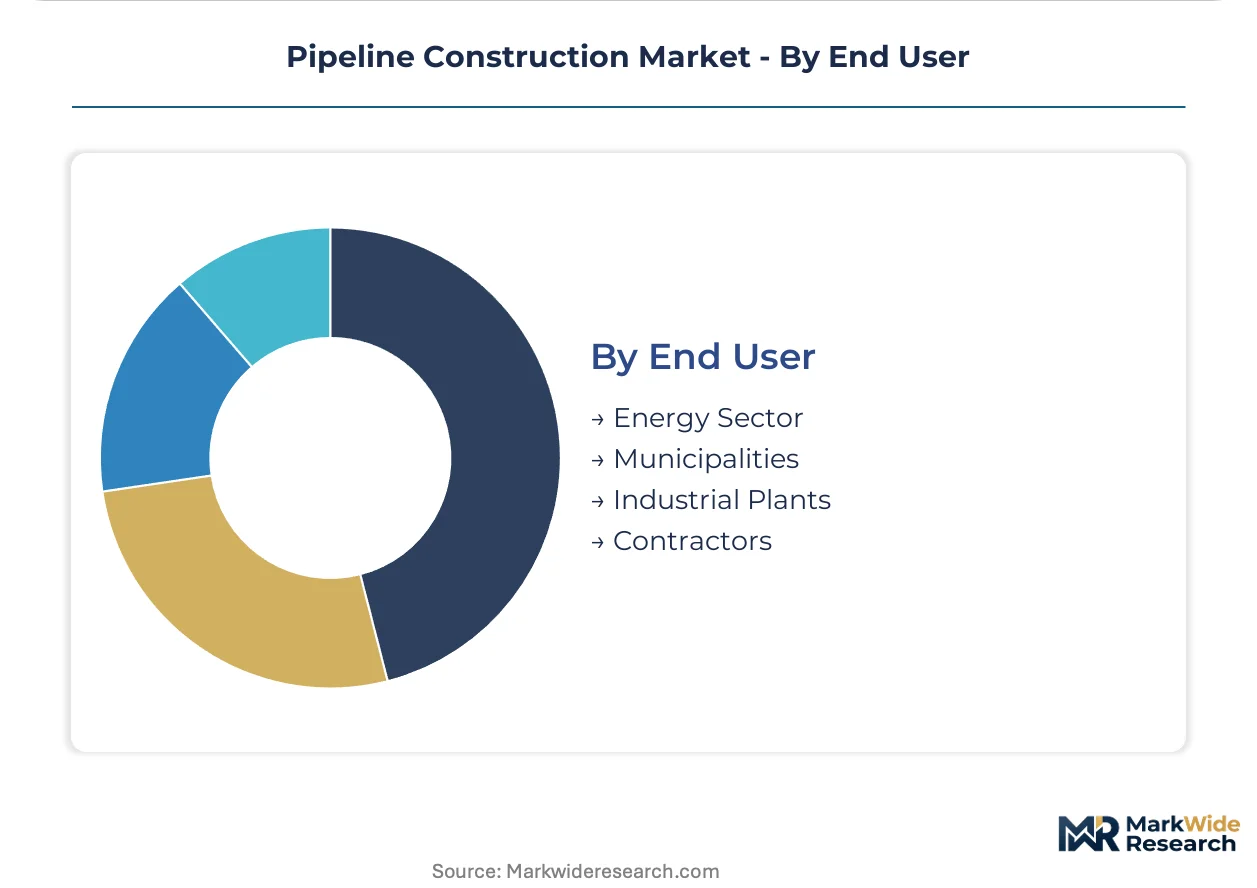
End User:
Customer type determines contract structure, with integrated energy companies favoring bundled EPC-integrity agreements versus municipalities procuring through segmented public bidding.
- Energy Sector:Midstream operators and integrated majors specify mega-projects with 20-year integrity management bundled into single-source contracts. Permian Basin producers dominate current capital allocation.
- Municipalities:City and county water utilities procure through competitive bidding with lifecycle cost evaluation criteria. Federal infrastructure funding accelerates replacement schedules in older industrial cities.
- Industrial Plants:Refineries, petrochemical complexes, and power generation facilities require process piping and utility distribution networks. Carbon capture retrofit projects in Louisiana and Texas create emerging demand.
- Contractors:Specialized installation firms serve as subcontractors or direct bidders on smaller-diameter projects. AWS CWI certification shortages constrain capacity expansion for qualified welding crews.
Energy Sector holds the largest share; Industrial Plants show steepest expansion trajectory on carbon capture infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across pipeline construction markets. Energy sector buyers in export corridors absorb premium pricing for speed and reliability. Municipal procurement in water infrastructure remains highly cost-sensitive, prioritizing lifecycle economics over upfront capital expenditure.
United States
Permian Basin midstream developers dominate capital deployment, accelerating Permian-to-Gulf Coast trunk lines to capture LNG export arbitrage. PHMSA Part 192 and Part 195 mandates shape coating specifications and integrity management programs. West Texas and southeastern New Mexico host the densest concentration of active spreads, where automated welding fleets compress construction timelines.
Canada
Alberta oil sands operators and British Columbia LNG export projects drive large-diameter demand. The Canadian Energy Regulator oversees cross-border certificate applications and environmental compliance. Calgary anchors engineering and project management functions, while fabrication yards in Edmonton and Vancouver serve Arctic and Pacific export corridors.
Germany
EU Green Deal hydrogen readiness mandates redirect investment toward retrofittable high-grade steel infrastructure. ECHA REACH regulations govern coating chemical composition and environmental release protocols. The Ruhr industrial cluster and Bavarian chemical corridor host pilot projects for 20% hydrogen blending certification.
India
Petroleum and Natural Gas Regulatory Board targets 30,000 kilometers of additional trunk line capacity. Domestic fabrication shortfalls create import windows for foreign EPCs. Gujarat and Maharashtra concentrate demand, with Hazira and Dahej serving as primary import terminals for equipment and specialized materials.
Saudi Arabia
Aramco expansion programs and NEOM giga-project hydrogen pipelines absorb specialized installation capacity. The national oil company sets technical specifications that exceed regional standards. The Eastern Province hosts the densest contractor presence, with Jubail Industrial City serving as the primary fabrication and logistics hub.
Pipeline Construction Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in pipeline construction. Fully integrated EPC providers capture mega-project awards through bundled engineering-procurement-construction-commissioning offerings. Specialized installation contractors compete on welding crew availability and regional right-of-way expertise. Two competitive moves dominate: consolidation through acquisition of regional fabrication assets, and strategic partnerships to secure vessel access for deepwater installation.
Within the integrated tier, Bechtel Corporation and Saipem S.p.A. exemplify divergent geographic anchoring strategies. Bechtel represents the self-perform fabrication and construction model with multi-continent project execution. Saipem occupies a position defined by deepwater pipeline installation vessel access and subsea technical specialization. Kiewit Corporation sits within the North American-focused tier, anchoring vertically integrated delivery from engineering through commissioning.
| Leading Market Players |
|---|
| Bechtel Corporation |
| Saipem S.p.A. |
| TechnipFMC plc |
| McDermott International Ltd. |
| Enbridge Inc. |
| Kinder Morgan, Inc. |
| TC Energy Corporation |
| Larsen & Toubro Limited |
| Kiewit Corporation |
| Others |
Value Chain & Pricing Dynamics
API 5L certification requirements gate both steel supplier qualification and EPC contractor pricing tiers simultaneously, creating dual barriers that concentrate procurement power among certified mills and integrated fabricators while fragmenting price discovery across spot and contract mechanisms.
Pricing Analysis
Integrity management service contracts drive lifetime value for pipeline operators, with bundled EPC-commissioning-maintenance agreements commanding premium day-rates over fragmented subcontracting models. Three-tier pricing structure across premium certified, standard compliant, and economy spot procurement levels segments buyers by risk tolerance and project scale. Cost compression in standard-grade steel contracting is intensifying because hot-rolled coil price volatility transfers margin risk to fixed-price EPCs. Municipal water utilities exhibit highest price sensitivity through competitive bidding mandates, while Permian Basin midstream developers absorb premium pricing for speed-to-market certainty.
Supply Chain Analysis
Extended lead times for API 5L-grade plate and specialized coating systems stretch project planning horizons, with hot-rolled coil inventory cycles running longer than fabrication scheduling windows. Steel production draws from United States, China, and India as primary supply nodes, with domestic mills capturing premium share for PHMSA-compliant specifications. Specialized inputs include fusion-bonded epoxy resins, automated welding consumables, and smart pigging sensor arrays. Single-source vulnerability concentrates in deepwater lay vessel availability, with fewer than 25 operational units globally. Distribution runs through integrated EPC direct procurement for mega-projects and tiered distributor networks for municipal and industrial maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipeline construction market sits in cyclical recovery mode, with LNG export capacity expansion and hydrogen infrastructure retrofit obligations providing sequential demand waves across the analysis window.
For Market Incumbents: Compound defensive positioning through backward integration into specialized coating manufacturing and captive welding automation fleet expansion. Threat from automated equipment vendors disrupting traditional labor-contractor margins demands counter-investment in real-time radiographic welding systems. Certification investment in EU hydrogen-blend standards opens eligibility for emerging European retrofit contracts.
For New Entrants and Emerging Players: Lead with carbon capture transport infrastructure as the most penetrable white-space segment, targeting Louisiana and Texas industrial corridor right-of-way ahead of federal credit expansion. Municipal HDPE water replacement cycles in drought-stressed Southwestern cities offer second-tier entry with lower capital barriers. Go-to-market angle centers on trenchless horizontal directional drilling expertise bundled with lifecycle cost modeling for utility procurement committees.
For Investors and Strategic Acquirers: EU Green Deal hydrogen readiness mandates reshape the acquisition landscape toward retrofittable high-grade steel fabrication assets and specialized coating system providers. Long-term viability frames around 20-year integrity management contract backlogs rather than construction-only revenue streams. Signal to watch is PHMSA methane leak detection sensitivity threshold adjustments accelerating inspection technology procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Fleet Expansion | Dual-torch systems with embedded radiographic feedback displace third-party inspection subcontractors in Gulf of Mexico tie-in work. |
| Hydrogen-Ready Steel Certification | EU 20% blending mandates by 2030 redirect European investment toward retrofittable high-grade infrastructure specifications. |
| Carbon Capture Pipeline Buildout | Louisiana and Texas industrial corridors secure right-of-way ahead of federal 45Q credit program expansion. |
| Integrated EPC-Integrity Contracts | Single-source 20-year agreements concentrate risk with contractors while reducing interface management for Permian Basin operators. |
| Deepwater Vessel Access Partnerships | Strategic alliances with Saipem and TechnipFMC unlock subsea project eligibility for mid-tier installation contractors. |
Study Parameters
The analysis maps welding automation technologies, coating system specifications, and integrity management service tiers, each validated through EPC project directors, midstream operator procurement leads, and municipal utility engineering managers. Primary interviews with welding automation OEMs, specialty steel mill sales directors, and PHMSA compliance consultants combined with secondary validation from FERC certificate filings, EIA pipeline construction databases, and EU Green Deal delegated act texts. Bottom-up project pipeline aggregation and top-down capital expenditure benchmarking provided triangulation across data sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology tier, material grade, application vertical, and end-user procurement structure, with regional regulatory framework as an additional industry-specific dimension. CAGRs derived from project backlog analysis and announced capacity expansion timelines, incorporating steel price elasticity assumptions and labor availability constraints as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Permian Basin production growth, stable API 5L steel pricing, and incremental PHMSA regulatory tightening would require recalibration. Forecasts reflect documented assumptions regarding LNG export terminal completion schedules and EU hydrogen blending timeline adherence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
India Transportation Infrastructure Construction Market