
 Pipeline Network Market | 2026-2036
Pipeline Network Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Network Market Intelligence
The substitution of traditional steel with advanced composite materials is repositioning the economic calculus for pipeline longevity and maintenance. Enbridge Inc. operates one of the largest energy delivery networks in North America, focusing on crude oil and natural gas. Siemens AG provides critical automation and digitalization solutions for pipeline integrity management. Meanwhile, Emerson Electric Co. specializes in control valves and measurement instrumentation vital for efficient fluid transport systems.
A pipeline network is an integrated system of tubes, pumps, valves, and monitoring equipment designed to transport fluids like oil, gas, or water across vast distances, often operating at pressures exceeding 1,000 psi. Its primary purpose is the bulk, continuous movement of resources from production sites to refineries or distribution centers. Analysis of pipeline types shows natural gas transport represents a high-growth application. Within materials, steel continues to dominate high-pressure transmission, but polyethylene gains share in lower-pressure gas and water distribution.
Regulatory frameworks from bodies like the US EPA, which mandates stringent methane leak detection and repair programs, directly impact operational technology choices. In Europe, the EU Green Deal influences investment towards hydrogen-ready pipelines, while China's MEE enforces strict environmental impact assessments for new projects. The key strategic decision for operators is balancing investment in retrofitting legacy steel assets versus constructing new, digitally-native composite networks to meet future energy and environmental demands.
Market Dynamics
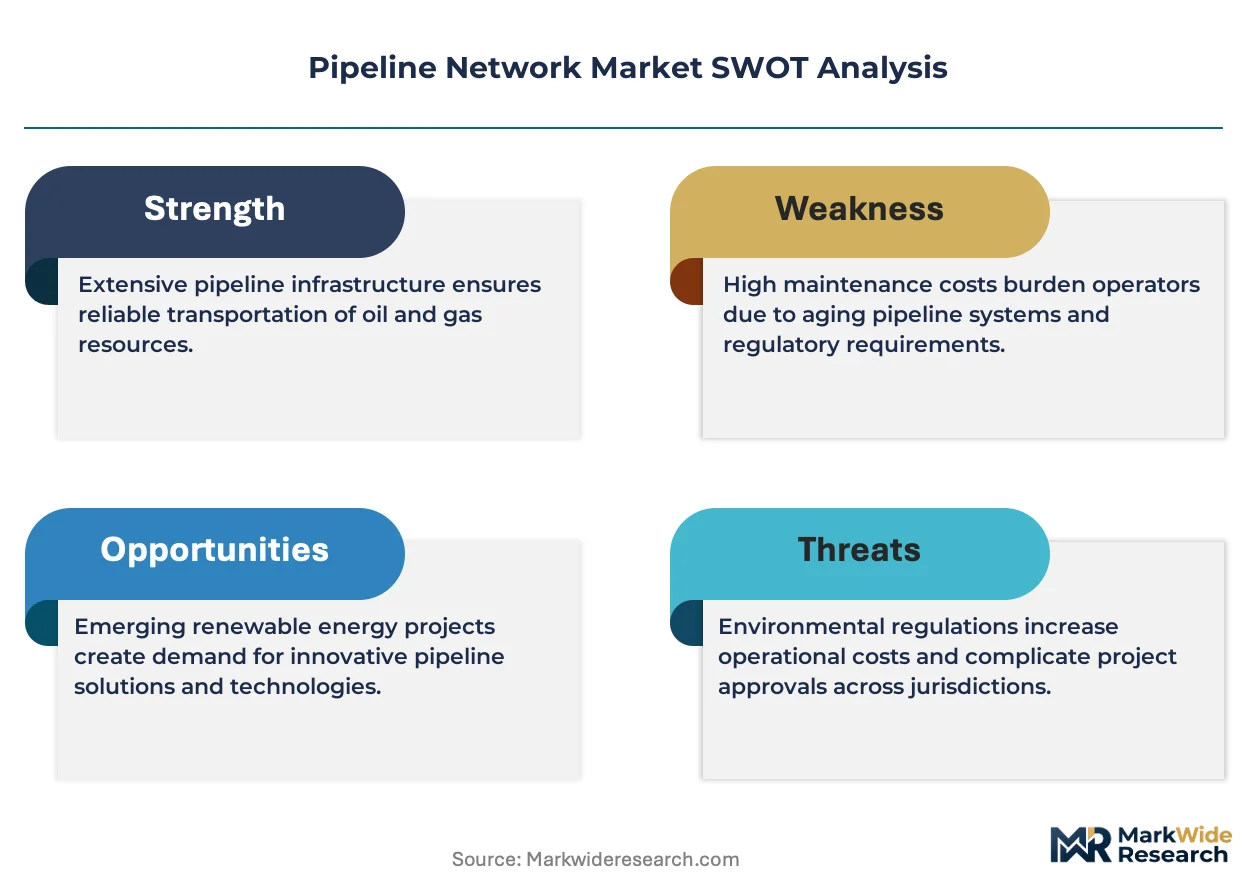
The central structural force shaping the market is the tension between retrofitting vast, aging steel networks for continued fossil fuel transport and the immense capital investment required to build new, digitally native pipeline systems designed for future energy carriers like hydrogen.
Growth Catalysts
- Energy Security Policies:National energy independence goals, particularly for liquefied natural gas (LNG) exports in the United States and gas imports in Europe, are spurring the construction of new large-diameter transmission pipelines and associated infrastructure.
- Advanced Composite Materials:The adoption of non-metallic materials like reinforced thermoplastic pipe (RTP) is lowering lifecycle costs by offering superior corrosion resistance, reducing the need for expensive ongoing maintenance programs common with traditional steel.
- Urbanization in Developing Economies:Rapid expansion of cities in countries like India and Vietnam necessitates significant investment in new water distribution and natural gas utility networks to support residential and commercial development.
Market Restraints
- Stringent Permitting Processes:Environmental regulations, such as impact assessments mandated by China's MEE or lengthy reviews in the European Union, create significant delays and uncertainty for new pipeline projects, increasing pre-construction costs.
- Volatile Raw Material Costs:Price fluctuations for high-grade steel and specialized polymers directly impact project profitability and budget forecasting, creating a barrier for operators committing to long-term capital-intensive builds.
- Public Opposition and Land Access:Securing rights-of-way for new pipeline corridors faces growing resistance from landowners and environmental groups, leading to protracted legal challenges and project cancellations in North America and Europe.
Strategic Opportunities
- Carbon Capture and Storage (CCUS):Repurposing existing natural gas pipelines or building new dedicated networks for transporting captured CO2 from industrial sites to sequestration locations represents a significant new application area.
- Hydrogen Infrastructure Development:Government incentives under frameworks like the EU Green Deal and the US Inflation Reduction Act (IRA) are creating opportunities to build the first generation of dedicated hydrogen transport pipelines.
- Digital Twin and Predictive Analytics:Offering sophisticated software and sensor packages for real-time monitoring and predictive maintenance allows technology providers to capture recurring service revenue from pipeline operators seeking to optimize asset performance.
Industry Challenges
- Skilled Labor Shortages:A critical deficit exists for specialized personnel, including certified welders for high-pressure systems and data scientists capable of managing complex pipeline integrity management software, constraining project execution.
- Legacy System Integration:Integrating modern digital monitoring and control systems with decades-old analog infrastructure is technically complex and requires substantial capital outlay without immediate returns, slowing technology adoption.
- Cybersecurity Threats:The increasing digitalization and remote operation of pipeline networks exposes critical energy infrastructure to a greater risk of cyberattacks, demanding continuous investment in advanced security protocols and threat detection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Network Market |
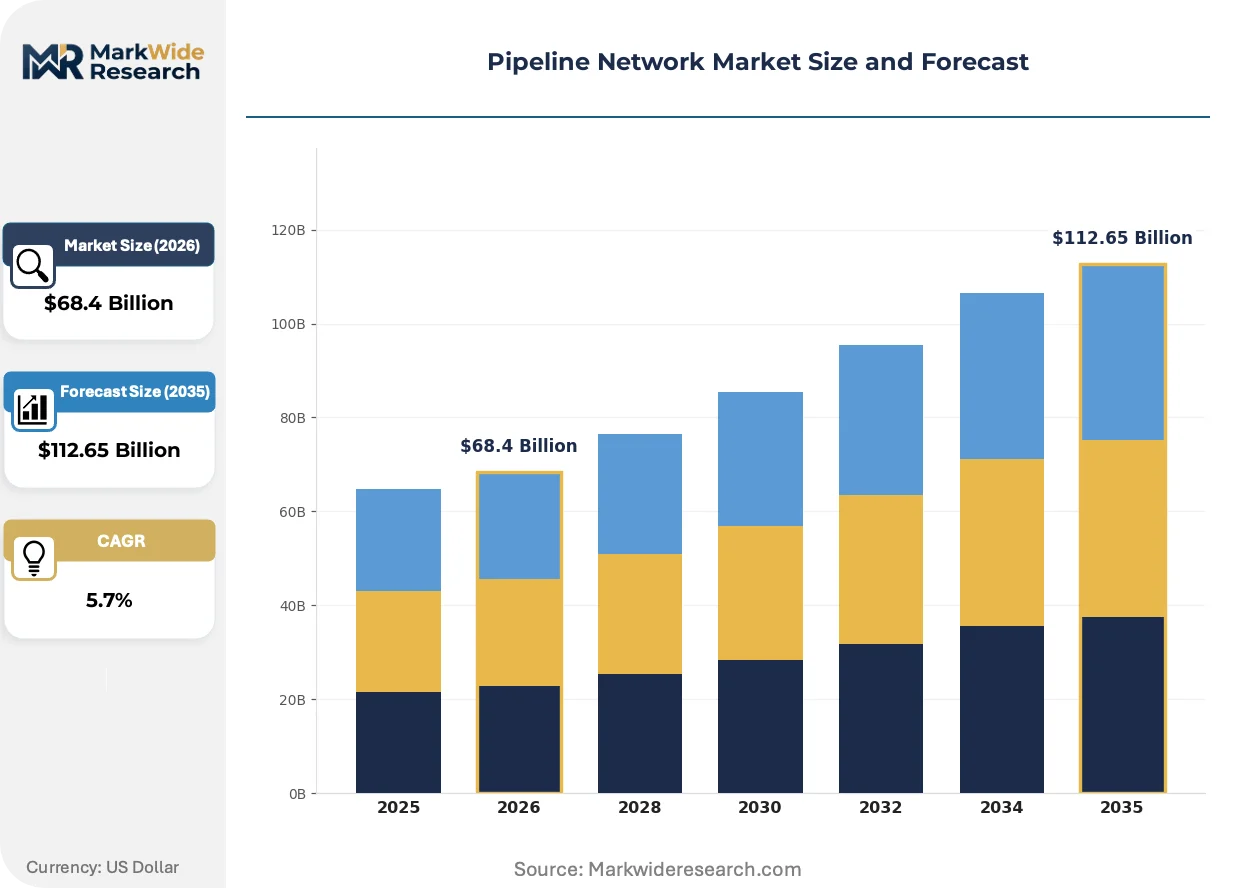
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipeline Type: Crude Oil, Natural Gas, Refined Products, Water, Chemical Fluids Material: Steel, Polyethylene, Polyvinyl Chloride, Ductile Iron, Composite Application: Fuel Transport, Waste Disposal, Process Industry, Agriculture Irrigation, Fire Protection End User: Energy Producers, Waste Management Firms, Chemical Manufacturers, Agricultural Enterprises, Municipal Utilities |
| Companies Covered | Honeywell International Inc., Emerson Electric Co, Siemens AG, The Williams Companies Inc., Enbridge Inc., General Electric Company, ABB Ltd., Huawei Technologies Co. Ltd., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Network Market Strategic Shifts & Innovations
The convergence of digital oversight and advanced materials science is reshaping pipeline network economics and operational risk profiles. This shift moves the focus from reactive maintenance to predictive asset management, driven by new regulatory pressures and the demands of a changing energy mix.
Digital Twin technology creates a virtual, real-time replica of physical pipeline assets for stress testing and failure prediction. Midstream operators are adopting this for integrity management programs to simulate the impact of operational changes or environmental conditions. This technology is unifying disparate data from SCADA, inline inspection tools, and geospatial systems into a single, predictive operational model.
In Europe, the EU Green Deal is creating a direct regulatory pull for investment in hydrogen-ready pipeline infrastructure. This policy influences material selection and long-term investment strategies, forcing operators to evaluate the hydrogen compatibility of new and existing assets. The natural gas transmission segment is most affected, with companies planning for phased blending of hydrogen into existing networks.
Project execution models are pivoting toward modular construction and pre-fabrication to shorten deployment timelines and improve safety. This approach disrupts traditional, labor-intensive on-site construction by moving fabrication to controlled factory environments, ensuring higher quality welds and coatings. This trend is most visible in large-scale LNG projects in the United States and Australia, where speed to market is a critical competitive factor.
Pipeline Network Market Segmentation
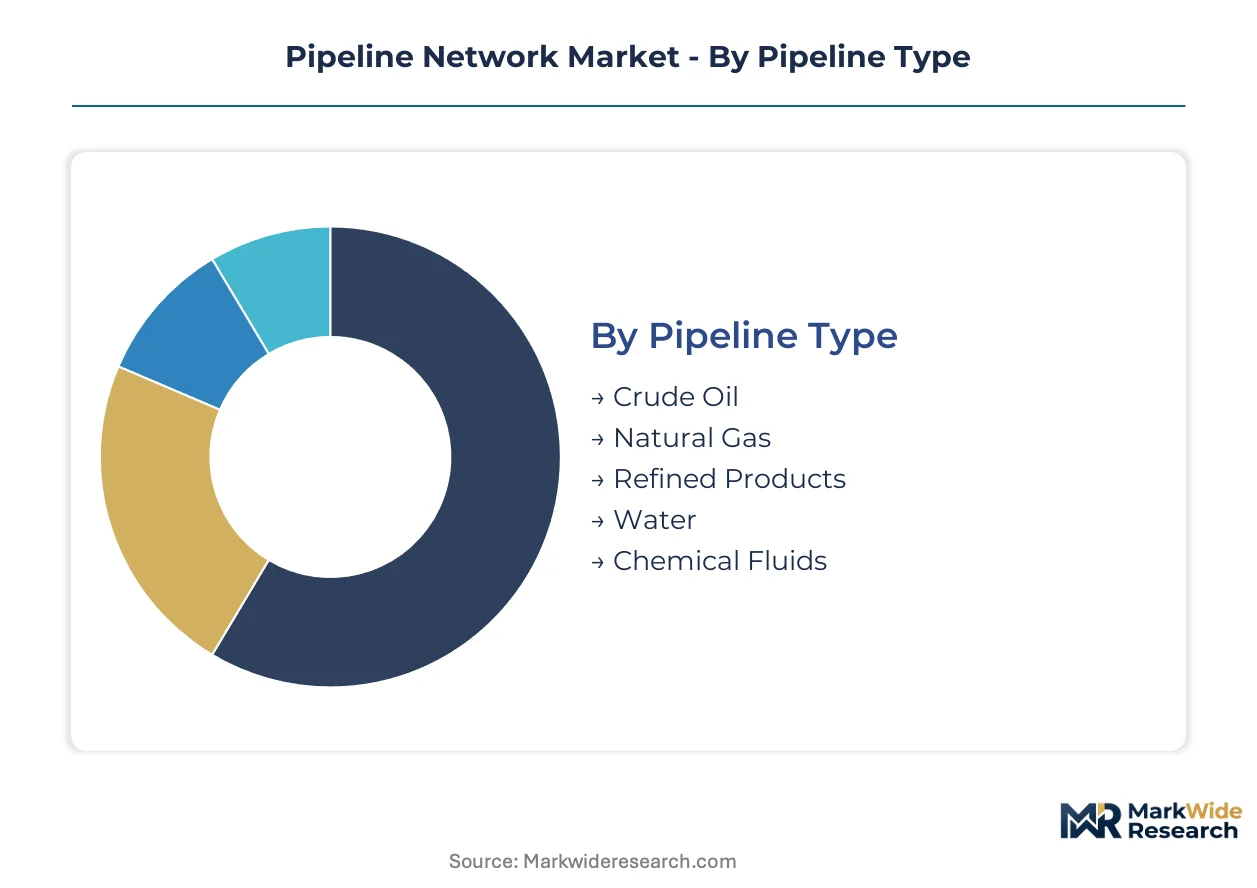
The Pipeline Network Market segmentation provides a granular view of distinct operational requirements and material preferences. Analyzing these categories reveals where capital investments are flowing and how technological advancements are being deployed. This detailed breakdown informs strategic planning for operators and technology providers.
Pipeline Type:
The segmentation by pipeline type highlights the varying degrees of infrastructure integration, from dedicated large-diameter transmission lines to complex, interconnected distribution networks.
- Crude Oil:Networks designed for crude oil move unrefined petroleum from extraction sites to refineries, requiring robust infrastructure to handle varying viscosities and pressures. Crude oil pipeline demand remains high in North America, supporting major oil sands projects and shale plays.
- Natural Gas:These pipelines transport gaseous hydrocarbons from production fields to processing plants and end-users, often operating at high pressures exceeding 1,000 psi. Demand for natural gas transport is strong in the United States, driven by LNG export infrastructure development.
- Refined Products:These systems transport processed petroleum products like gasoline, diesel, and jet fuel from refineries to distribution terminals.
- Water:Pipelines for water convey potable, wastewater, or irrigation water, often using lower pressure systems.
- Chemical Fluids:Specialized pipelines transport various industrial chemicals, requiring specific material compatibility and stringent safety protocols.
Crude Oil leads volumes today; Natural Gas is gaining share fastest.
Material:
Material choices directly influence the initial capital expenditure and long-term operational costs, creating distinct cost tiers across the pipeline network market.
- Steel:High-strength carbon steel pipes remain the standard for high-pressure, large-diameter transmission lines due to their proven durability and structural integrity. Adoption is prevalent in new large-scale projects requiring extreme pressure resistance, particularly for natural gas and crude oil.
- Composite:These advanced materials, including reinforced thermoplastic pipe (RTP), offer superior corrosion resistance and lighter weight, reducing installation and maintenance costs. Demand for composites is concentrating in developing economies in Asia for new energy grids, where lifecycle cost reduction is critical.
- Polyethylene:Flexible and corrosion-resistant, polyethylene pipes are prevalent in lower-pressure gas distribution and water utility networks.
- Polyvinyl Chloride:PVC pipes are cost-effective for water distribution, sewage, and irrigation systems.
- Ductile Iron:Known for its strength and durability, ductile iron is used in water and wastewater infrastructure.
Steel materials dominate high-pressure applications; composite materials are expanding most quickly.
Application:
The application segments delineate the primary use cases for pipeline networks, with some applications commanding significantly higher transport volumes than others.
- Fuel Transport:This application involves the bulk movement of crude oil, natural gas, and refined petroleum products over long distances, forming the backbone of energy supply chains. Fuel transport demand is robust in the United States for LNG export infrastructure.
- Process Industry:Pipelines within industrial facilities transport raw materials, intermediate products, and finished goods, integrating various manufacturing stages. Investment within the process industry is significant in chemical manufacturing hubs, requiring specialized fluid handling.
- Waste Disposal:These networks manage the transport of industrial and municipal wastewater, often requiring corrosion-resistant materials.
- Agriculture Irrigation:Pipelines supply water to agricultural fields, supporting crop growth and livestock.
- Fire Protection:Dedicated pipeline systems deliver water to fire hydrants and sprinkler systems for urban safety.
Fuel Transport applications account for the largest volumes; Waste Disposal is climbing the fastest.
End User:
End-user segmentation reflects the diverse customer base for pipeline networks, each with unique operational scales, regulatory environments, and investment priorities.
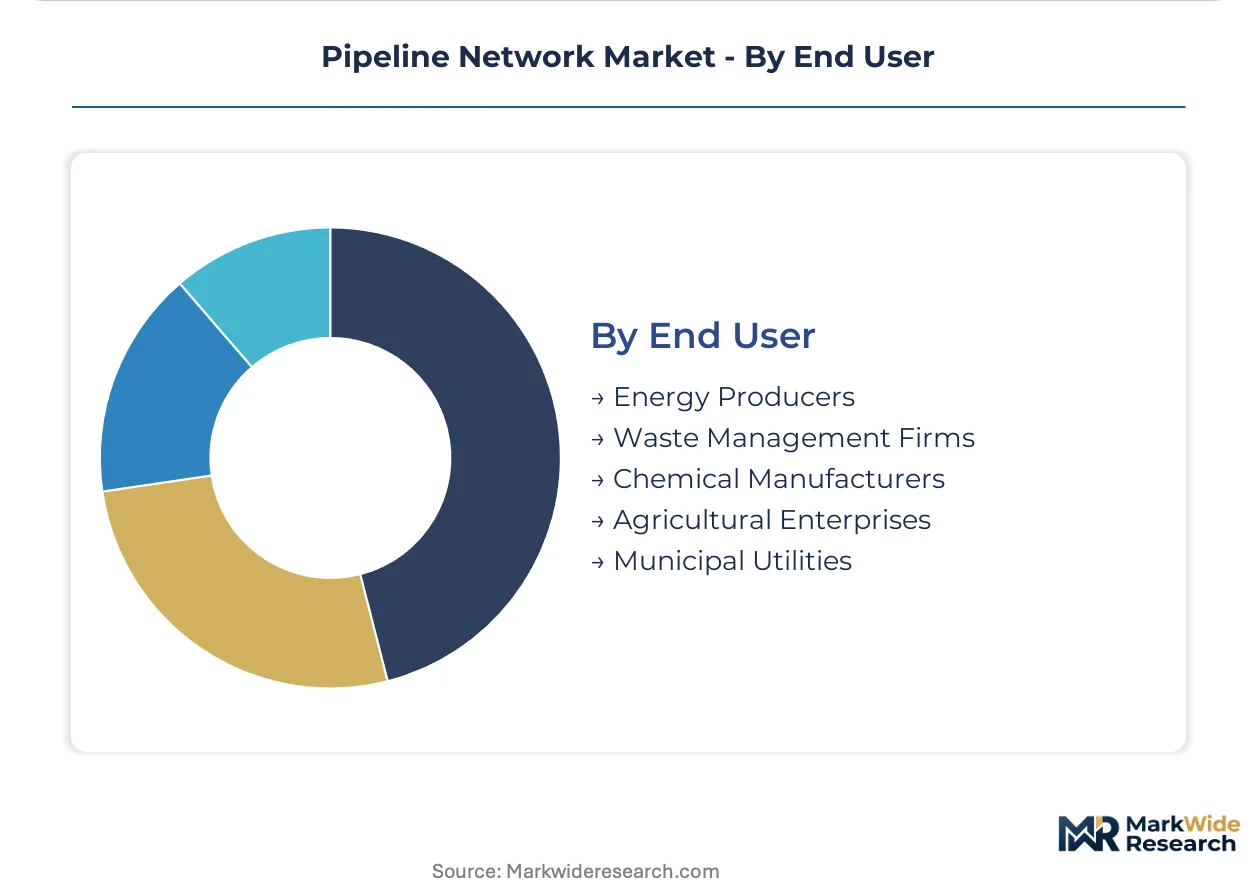
- Energy Producers:Companies involved in oil and gas exploration, production, and processing require extensive pipeline networks for resource extraction and transport to market. Energy producers are actively investing in new natural gas transmission lines to meet global energy demands.
- Municipal Utilities:Public and private entities managing urban infrastructure rely on pipelines for water distribution, wastewater collection, and local gas networks. Municipal utilities are expanding new water distribution and natural gas utility networks in rapidly urbanizing developing economies.
- Waste Management Firms:These companies utilize pipelines for the collection and transport of industrial waste streams.
- Chemical Manufacturers:Chemical plants employ complex pipeline systems for moving raw materials and finished chemical products.
- Agricultural Enterprises:Large farms and agricultural cooperatives use pipelines for efficient irrigation and nutrient delivery.
Energy Producers drive the largest capital expenditures; Chemical Manufacturers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' extensive energy infrastructure drives significant investment in pipeline networks. Global energy transitions and infrastructure upgrades are shaping regional demand patterns. Developing economies are also witnessing substantial growth in new energy grids.
United States
Demand for pipeline networks in the United States is spurred by LNG export infrastructure and natural gas transport. The US EPA mandates stringent methane leak detection and repair programs, influencing operational technology choices. The Gulf Coast region, particularly around Houston, is expanding its network for crude oil and natural gas exports. New projects support global energy security goals.
China
China's pipeline network demand originates from new energy grids and environmental impact assessments for large projects. China's MEE enforces strict environmental impact assessments for new pipeline projects. The Yangtze River Delta region is investing in pipeline expansion for industrial chemical transport and urban gas distribution. This supports rapid industrialization and urbanization.
India
India's pipeline growth is driven by rapid urbanization and the expansion of natural gas utility networks and water distribution systems. National energy independence goals influence pipeline development for gas and refined products. Major cities like Mumbai and Delhi are expanding their natural gas and water distribution networks to meet residential and commercial development needs. This supports significant infrastructure upgrades.
Germany
Germany's pipeline network development focuses on hydrogen-ready pipelines and the broader energy transition initiatives. The EU Green Deal influences investment towards hydrogen-ready infrastructure and material selection. The Ruhr area, a traditional industrial heartland, is evaluating existing natural gas pipelines for hydrogen blending and dedicated hydrogen transport. This aligns with national decarbonization targets.
Canada
Canada's pipeline demand is linked to crude oil and natural gas transport from vast extraction sites to markets. Federal environmental assessments influence project approvals for new transmission lines across the country. Alberta's oil sands region requires robust pipeline systems to move crude oil to refining and export markets. Expansion projects face stringent regulatory reviews.
Pipeline Network Market Key Industry Players
Global majors compete with regional champions across technology and service offerings within the pipeline network market. The market exhibits a tiered structure, with established infrastructure providers alongside specialized technology vendors. Key strategic archetypes include integrated engineering solutions providers and material science innovators. Companies are engaging in strategic partnerships for project execution and portfolio diversification to address evolving energy demands.
Specialists in automation and control systems include Siemens AG, which offers critical digitalization solutions for pipeline integrity management. Emerson Electric Co. occupies a position as a provider of control valves and measurement instrumentation vital for efficient fluid transport systems. Meanwhile, Enbridge Inc. represents a major North American energy delivery network operator, focusing on crude oil and natural gas transport across vast distances. These companies anchor different segments of the value chain, driving innovation in operational efficiency and safety.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co |
| Siemens AG |
| The Williams Companies Inc. |
| Enbridge Inc. |
| General Electric Company |
| ABB Ltd. |
| Huawei Technologies Co. Ltd. |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Global steel commodity prices directly influence the cost structure of new pipeline projects, cascading through the supply chain into distinct pricing tiers for operators. This volatility impacts capital expenditure planning for energy infrastructure developers.
Pricing Analysis
Input-cost pass-through remains a critical mechanism for pipeline operators managing volatile material expenses. Contract-based long-term offtake agreements dominate the pricing model, providing stability for large-scale infrastructure investments. Price differentiation stems from material quality grades and specialized certifications, such as hydrogen-ready pipe, while pricing pressure stems from volatile raw material costs and stringent regulatory compliance. Developing economies often exhibit higher price sensitivity compared to established energy producers.
Supply Chain Analysis
Dual-sourcing requirements mitigate supply risks for critical pipeline components, ensuring project continuity. Geographic supply concentration for high-grade steel centers on China, while specialized control systems often originate from Germany. Raw material dependencies include high-strength carbon steel, advanced polymers, and precision measurement instrumentation. Commodity price volatility represents a key structural risk, with distribution primarily involving project-based engineering, procurement, and construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pipeline Network Market functions as a stable compounder, driven by continuous global energy transitions. This fundamental shift necessitates ongoing infrastructure development and upgrades across various geographies.
For Market Incumbents:
Hedge against future regulatory shifts by investing in hydrogen-ready pipeline infrastructure and advanced CCUS network development. Incumbents should prioritize R&D into composite materials compatible with new energy carriers to mitigate long-term asset obsolescence. Proactive cybersecurity investments are essential to protect critical energy infrastructure from increasing digital threats. Strategic partnerships with technology providers can accelerate the adoption of digital twin solutions for integrity management.
For New Entrants and Emerging Players:
Price-point gaps between premium steel solutions and cost-effective alternatives present opportunities for new entrants. Target underpenetrated segments like water distribution and lower-pressure gas networks in rapidly urbanizing developing economies. A go-to-market angle focusing on superior lifecycle cost reduction through advanced composite materials can attract municipal utilities. Offering integrated digital solutions for remote monitoring and predictive maintenance provides further differentiation.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized technology providers offer critical solutions for pipeline integrity management and energy transition. The market maintains long-term viability as essential infrastructure for global energy supply and decarbonization efforts. Target acquisition archetypes include firms specializing in advanced composite manufacturing or digital twin software. A key signal to watch is the approval rate and funding allocation for hydrogen and CCUS projects under new government incentives.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout for LNG Export | Expands United States' role in global energy security and natural gas transport. |
| Technology Licensing for Digital Twin Solutions | Enhances pipeline integrity management and predictive maintenance for operators. |
| Green Certification Program for Hydrogen Readiness | Validates infrastructure for future energy carriers, aligning with EU Green Deal. |
| Long-term Supply Agreements for Advanced Polymers | Secures critical raw materials for composite pipe manufacturing, stabilizing costs. |
| Joint Venture for New Composite Pipeline Projects | Accelerates deployment of corrosion-resistant networks in developing economies. |
Research Approach
Coverage spans North America, Europe, and Asia, with primary inputs from each region. The analysis combines in-depth interviews with pipeline operators, material suppliers, engineering consultants, and regulatory bodies. Secondary validation draws from US EPA reports, EU Green Deal policy documents, and China MEE publications. This approach ensures robust bottom-up and top-down triangulation of market data.
Granularity was modeled across pipeline type, material, application, end user, and regional energy policy for the Pipeline Network Market. The analytical framework projects market evolution across the analysis window. Compound Annual Growth Rates were derived through a comprehensive review of historical market performance and future growth projections. Energy demand forecasts and raw material price trends served as key industry-specific forecast inputs.
Caveats apply where volatile raw material costs or evolving environmental regulations could materially shift the outlook. Forecasts reflect specific assumptions regarding technological adoption and geopolitical stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market