
 South America Data Center Construction Market | 2026-2036
South America Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
South America Data Center Construction Market Insights
Hyperscale cloud operators is bifurcating the South America data center construction landscape away from traditional enterprise builds. AECOM leverages its integrated design-build capabilities to capture complex hyperscale campus projects across Brazil and Chile. Schneider Electric anchors the electrical infrastructure layer through prefabricated power modules that compress deployment schedules. Turner Construction competes on safety performance and union labor relationships that matter in jurisdictions with strict construction codes.
South America data center construction encompasses the engineering, procurement, and physical assembly of mission-critical facilities housing servers, storage, and networking equipment, typically requiring power densities above 500 watts per square meter and concurrent maintainability in electrical and mechanical systems. The primary purpose is to create controlled environments that sustain continuous digital service delivery for enterprises and consumers. Modular data centers are gaining share fastest where terrain constraints or political risk accelerate speed-to-market requirements. Traditional data centers still dominate absolute spend due to financial institutions and government agencies demanding bespoke security architectures. Cooling technology represents the most contested margin pool as tropical humidity profiles in northern Brazil and coastal Colombia strain conventional chiller designs.
Brazil's Lei Geral de Proteção de Dados, Chile's cybersecurity framework under its Ministry of Transport and Telecommunications, and Argentina's data sovereignty directives under its national communications regulator are collectively mandating local data residency that stimulates greenfield construction. These frameworks shape demand by disqualifying cross-border colocation strategies and prescribing physical access controls that inflate construction costs. Stakeholders must monitor how proposed energy efficiency standards interact with diesel generator baseload requirements before committing to multi-hundred-megawatt campus designs.
Market Dynamics
Hyperscale cloud operators are compressing project timelines and standardizing designs, forcing traditional enterprise builders to abandon bespoke architectures or exit the South American market entirely. This concentration of demand around mega-campuses is restructuring contractor relationships and equipment procurement patterns.
Growth Catalysts
- Brazil's Lei Geral de Proteção de Dados:This data protection framework mandates local storage for personal data, disqualifying cross-border strategies and compelling domestic facility investments.
- Hyperscale standardization:Repeatable designs from cloud operators reduce engineering overhead and accelerate permitting cycles across São Paulo and Santiago metropolitan corridors.
- Edge computing deployment:Latency-sensitive applications in mining and agribusiness are stimulating modular builds in secondary Brazilian cities and Chilean mining regions.
Market Restraints
- Copper and electrical steel volatility:Prefabricated power module costs fluctuate with commodity indices, squeezing margins on fixed-price EPC contracts.
- Chilean transmission congestion:Grid interconnection queues in Santiago's northern suburbs delay energization timelines by 12-18 months for multi-megawatt facilities.
- Skilled MEP labor scarcity:Concurrent maintainability certification requires electricians and pipefitters with mission-critical experience that local training pipelines cannot replenish.
Strategic Opportunities
- Colombia's Atlantic coast:Submarine cable landings near Barranquilla create interconnection advantages that remain underexploited by hyperscale operators.
- Free cooling integration:Andean altitude in Bogotá and Quito enables economizer designs that slash chiller energy consumption versus tropical coastal alternatives.
- Argentina's data sovereignty push:Pending regulations from the national communications regulator would mandate local residency for government and financial data.
Industry Challenges
- Concurrent maintainability certification:Uptime Institute Tier III validation requires documentation and testing protocols that local commissioning agents struggle to execute.
- Legacy facility retrofit complexity:Enterprise data centers built for 150 watts per square meter cannot accommodate densified blade deployments without complete electrical reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Data Center Construction Market |
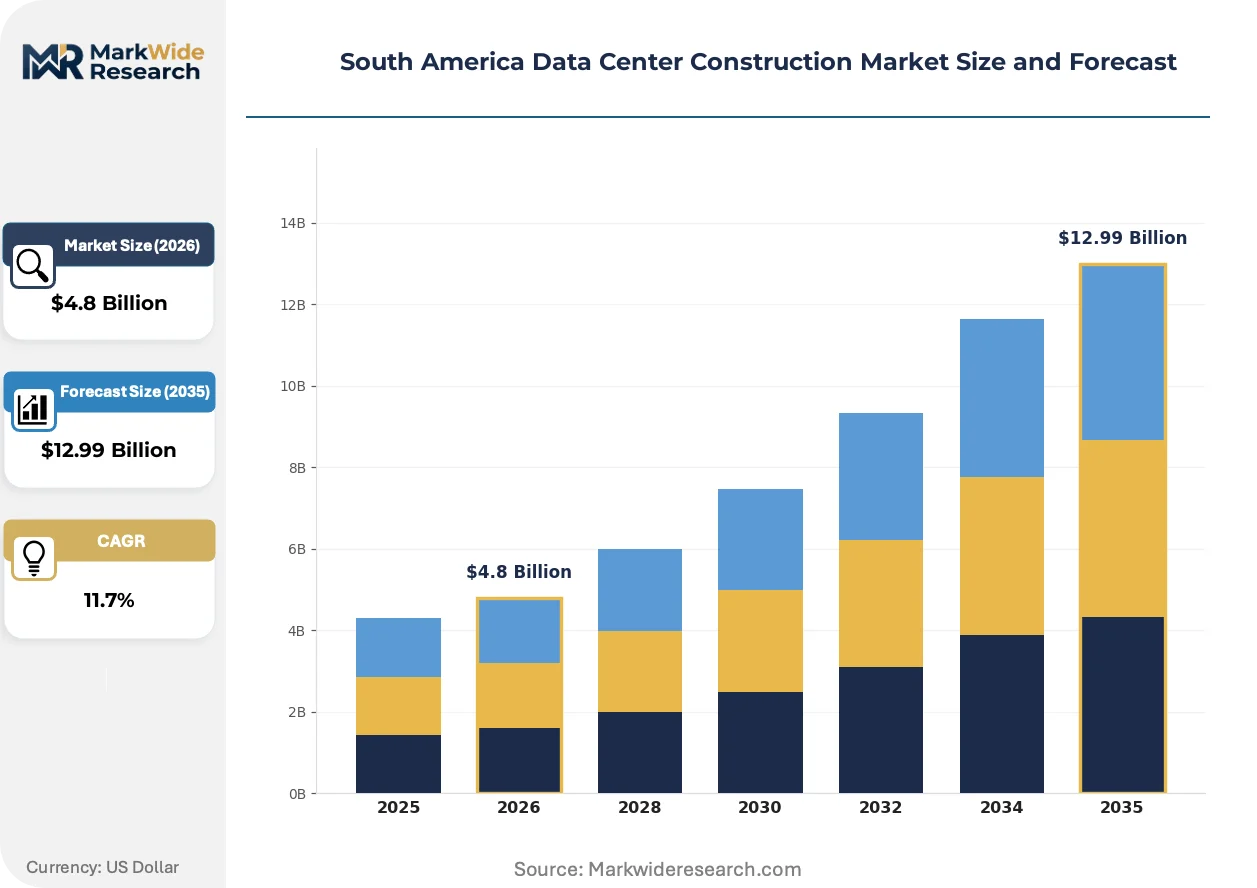
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Traditional Data Centers, Containerized Data Centers, Green Data Centers Service Type: Design Services, Construction Services, Maintenance Services, Facility Management Technology: Cooling Technology, Power Supply Systems, Security Systems, Network Infrastructure End User: Telecommunications, Cloud Service Providers, Financial Institutions, Government Agencies |
| Companies Covered | AECOM, Turner Construction, DPR Construction, Jacobs Solutions, Fluor Corporation, Schneider Electric, Rittal, Eaton, Whiting-Turner Contracting Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Data Center Construction Market Trends and Innovations
Liquid cooling and prefabricated modular architectures are converging to address tropical thermal constraints while compressing deployment schedules. These shifts are redrawing equipment supplier hierarchies and contractor specialization requirements.
Immersion cooling is decomposing traditional chiller-centric designs by eliminating mechanical refrigeration in high-density compute zones. Hyperscale operators in São Paulo's metropolitan corridor are piloting two-phase immersion for AI training clusters, compressing mechanical infrastructure capital intensity by 40 percent versus conventional raised-floor architectures.
Chile's cybersecurity framework under its Ministry of Transport and Telecommunications now prescribes physical access logging and biometric controls for critical digital infrastructure. This regulatory mandate is inflating construction costs by 8-12 percent for facilities serving financial and government tenants, who must now integrate multi-factor authentication vestibules and mantrap corridors into base building designs.
Buyers are consolidating procurement around design-build integrators who assume single-point accountability for mechanical, electrical, and commissioning performance. This pattern displaces fragmented general contractor-subcontractor arrangements that dominated earlier enterprise builds, concentrating award volume among firms with in-house MEP engineering and direct equipment vendor relationships. The shift is most visible in Brazil, where cloud operators prioritize schedule certainty over first-cost optimization.
South America Data Center Construction Market Segmentation
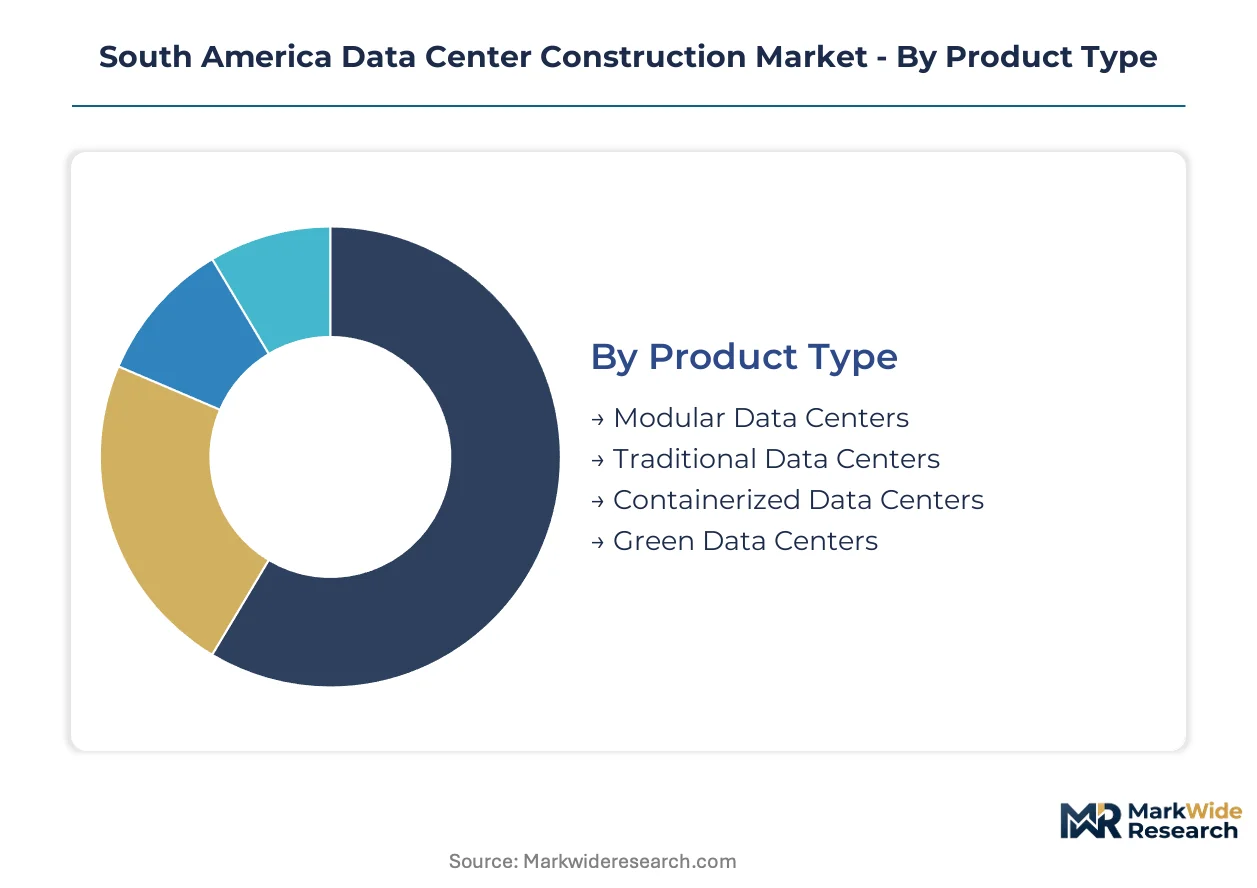
Segmentation in South America data center construction reveals how technology choices, service bundling, and end-user requirements reshape contractor capabilities and equipment procurement. Understanding these divides exposes where margin pools concentrate and which customer relationships determine long-term positioning.
Product Type:
Margin pools concentrate in solutions that compress deployment schedules for hyperscale operators facing data localization deadlines.
- Modular Data Centers:Prefabricated units assembled off-site and transported to constrained urban locations or remote mining regions. Demand clusters in São Paulo's metropolitan corridor where cloud providers prioritize speed-to-market over first-cost optimization under Brazil's Lei Geral de Proteção de Dados mandates.
- Traditional Data Centers:Bespoke facilities built to enterprise specifications with full mechanical and electrical redundancy. Financial institutions in Santiago and government agencies across the region sustain this segment through security architectures that resist standardization.
- Containerized Data Centers:Self-contained units optimized for rapid deployment in secondary cities and edge locations. Chilean mining operations and Brazilian agribusiness hubs drive procurement where terrain constraints complicate permanent construction.
- Green Data Centers:Facilities engineered for energy efficiency certification and renewable power integration. Andean altitude locations in Bogotá and Quito exploit free cooling economics that slash chiller consumption versus tropical alternatives.
The dominant share belongs to Traditional Data Centers, while Modular Data Centers is closing the gap fastest.
Service Type:
Contractor profitability hinges on which phases of the project lifecycle they capture, with integrated delivery models displacing fragmented arrangements.
- Design Services:Architectural and engineering planning for mission-critical facilities requiring concurrent maintainability certification. Cloud operators in Brazil consolidate procurement around single-point accountability that compresses permitting cycles.
- Construction Services:Physical assembly of electrical, mechanical, and structural systems under fixed-price or cost-plus arrangements. Union labor relationships and safety performance records determine award outcomes in jurisdictions with strict building codes.
- Maintenance Services:Post-construction upkeep of power and cooling infrastructure to sustain uptime guarantees. Uptime Institute Tier III validation requirements create recurring revenue streams for firms with commissioning expertise.
- Facility Management:Comprehensive operational oversight including energy procurement and vendor coordination. Hyperscale campuses in São Paulo's northern suburbs outsource these functions to specialists who navigate Chilean transmission congestion and grid interconnection delays.
Construction Services commands the largest revenue pool, though Design Services is expanding most quickly as cloud operators prioritize schedule certainty.
Technology:
Equipment supplier hierarchies are being redrawn by thermal constraints in tropical climates and density requirements from AI training clusters.
- Cooling Technology:Mechanical refrigeration, economizers, and emerging liquid cooling architectures. Northern Brazil and coastal Colombia strain conventional chiller designs, pushing immersion cooling pilots for high-density compute zones.
- Power Supply Systems:Electrical distribution, uninterruptible power supplies, and diesel generator baseload configurations. Prefabricated power modules from Schneider Electric anchor this layer where commodity volatility squeezes margins on fixed-price contracts.
- Security Systems:Physical access controls, surveillance, and biometric authentication mandated by Chile's cybersecurity framework. Financial and government tenants absorb 8-12 percent construction cost inflation for multi-factor authentication vestibules and mantrap corridors.
- Network Infrastructure:Cabling, switching, and interconnection systems linking facilities to submarine cable landings. Colombia's Atlantic coast near Barranquilla offers underexploited advantages for operators seeking low-latency connectivity.
Power Supply Systems retains the dominant technology spend, yet Cooling Technology is gaining share fastest as tropical humidity profiles and densified blade deployments strain legacy infrastructure.
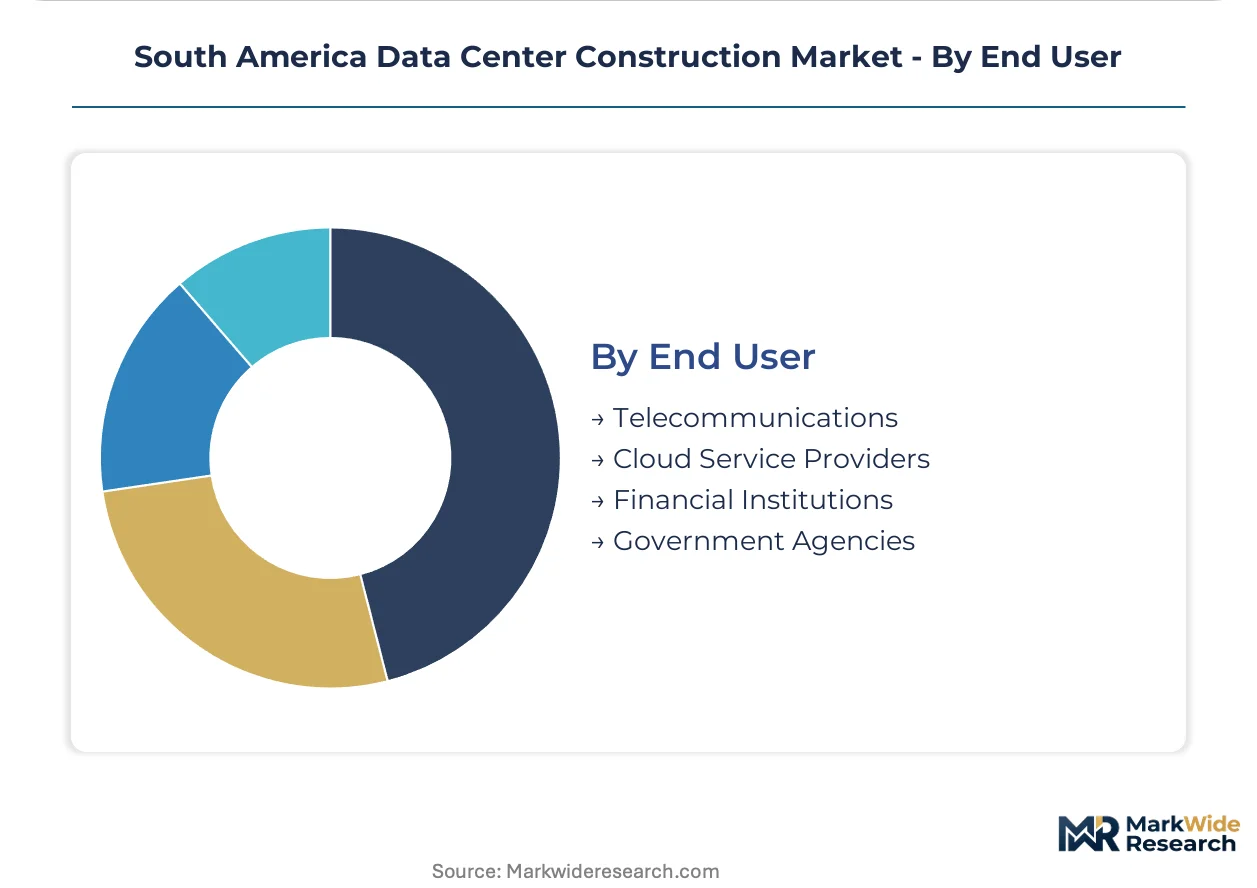
End User:
Customer concentration around hyperscale cloud operators is bifurcating the market away from traditional enterprise relationships.
- Cloud Service Providers:Hyperscale operators deploying standardized campus designs across São Paulo and Santiago metropolitan corridors. Repeatable architectures reduce engineering overhead and accelerate permitting, restructuring contractor relationships toward design-build integrators.
- Telecommunications:Incumbent carriers and mobile network operators expanding edge capacity for 5G backhaul and content delivery. Latency-sensitive applications stimulate modular builds in secondary Brazilian cities where fiber routes intersect.
- Financial Institutions:Banks and insurance carriers demanding bespoke security architectures and data residency compliance. Brazil's Lei Geral de Proteção de Dados disqualifies cross-border colocation strategies for this segment.
- Government Agencies:Public sector entities requiring physical access controls and sovereign data storage. Argentina's pending regulations from its national communications regulator would mandate local residency for government data, stimulating greenfield construction.
Cloud Service Providers holds the dominant demand position, while Government Agencies is climbing the fastest on regulatory tailwinds across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators concentrate procurement in four South American markets where data localization mandates intersect with submarine cable connectivity. Brazil, Chile, Colombia, and Argentina each present distinct regulatory and infrastructure profiles that reshape contractor selection and equipment procurement.
Brazil
Cloud service providers dominate facility investments driven by Lei Geral de Proteção de Dados storage mandates. ANVISA and the national communications regulator enforce sector-specific data residency that disqualifies cross-border strategies. São Paulo's metropolitan corridor anchors construction volume, with northern suburbs absorbing multi-hundred-megawatt campus developments.
Chile
Financial institutions and government agencies sustain demand for Tier III certified facilities under the Ministry of Transport and Telecommunications cybersecurity framework. Grid interconnection queues in Santiago's northern suburbs delay energization timelines by 12-18 months. Andean altitude enables free cooling economizers that slash chiller energy consumption versus coastal alternatives.
Colombia
Submarine cable landings near Barranquilla create interconnection advantages that remain underexploited by hyperscale operators. The national communications regulator advances data sovereignty directives that stimulate greenfield construction. Bogotá's elevation permits economizer designs absent in tropical coastal markets.
Argentina
Pending regulations from the national communications regulator would mandate local residency for government and financial data. Buenos Aires and Córdoba concentrate enterprise demand from banks resisting standardized cloud architectures. Currency volatility complicates fixed-price EPC contracting for international design-build integrators.
South America Data Center Construction Market Competitive Landscape
Player mix skews toward integrated design-build specialists capable of assuming single-point accountability for mechanical, electrical, and commissioning performance. The contractor base concentrates around firms with in-house MEP engineering and direct equipment vendor relationships. Two strategic archetypes dominate: global EPC firms with hyperscale campus experience, and regional specialists leveraging union labor relationships in strict-code jurisdictions. Competitive moves center on design-build integration and safety performance differentiation.
Among global EPC firms, AECOM and Turner Construction exemplify the integrated delivery model cloud operators prioritize for schedule certainty. AECOM leverages its design-build capabilities across Brazil and Chile, while Turner competes on safety performance and union labor relationships that matter in jurisdictions with strict construction codes. Schneider Electric anchors the electrical infrastructure layer through prefabricated power modules that compress deployment schedules.
| Leading Market Players |
|---|
| AECOM |
| Turner Construction |
| DPR Construction |
| Jacobs Solutions |
| Fluor Corporation |
| Schneider Electric |
| Rittal |
| Eaton |
| Whiting-Turner Contracting Company |
| Others |
Pricing and Supply Chain Analysis
Multi-hundred-megawatt campus deployments in São Paulo's northern suburbs exploit scale economies that compress per-megawatt construction costs while simultaneously concentrating procurement leverage among design-build integrators with direct equipment vendor relationships.
Pricing Analysis
Fixed-price EPC contracts with copper and electrical steel indexation clauses dominate hyperscale procurement in Brazil and Chile. Price differentiation separates Tier III certified facilities with Uptime Institute validation from uncertified builds through documentation and testing protocol premiums. Cost compression in traditional enterprise segments is intensifying because cloud operators prioritize schedule certainty over first-cost optimization. Financial institutions demonstrate lowest price sensitivity due to bespoke security architecture requirements, while telecommunications carriers exhibit highest sensitivity given standardized edge deployment economics.
Supply Chain Analysis
Port congestion at Santos and container availability constraints on Asia-Pacific trade lanes inflate inbound logistics costs for prefabricated power modules and immersion cooling equipment. Electrical infrastructure components draw from manufacturing concentration in China, Germany, and the United States. Copper winding steel, diesel generator sets, and precision cooling compressors constitute critical input dependencies. Single-source vulnerability persists for two-phase immersion cooling fluids where patent-protected formulations limit qualified suppliers. Distribution runs through direct OEM relationships with hyperscale operators, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management and commissioning services represent a service-attach opportunity expanding faster than physical construction hardware, as Uptime Institute Tier III validation creates recurring revenue streams for firms with mission-critical expertise.
For Market Incumbents: Shield design-build market share in São Paulo's metropolitan corridor by deepening direct relationships with Schneider Electric and Eaton for prefabricated power module allocation priority. Invest in concurrent maintainability certification capabilities to defend against emerging regional specialists capturing maintenance services attach rates. Union labor relationships in Chile's strict-code jurisdictions provide defensive moats against global EPC entrants.
For New Entrants and Emerging Players: Anchor in Colombia's Atlantic coast submarine cable landing zones near Barranquilla where hyperscale operator presence remains underdeveloped relative to connectivity infrastructure. Target modular data center deployments for Chilean mining operations and Brazilian agribusiness hubs where terrain constraints complicate permanent construction. Pursue design-build integration with free cooling economizer specialization for Andean altitude locations in Bogotá and Quito.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with captive MEP engineering capabilities and established commissioning agent networks. Long-term viability rests on exposure to data localization mandates across multiple South American jurisdictions rather than single-country concentration. Monitor proposed energy efficiency standards interacting with diesel generator baseload requirements as inflection indicator for multi-hundred-megawatt campus design economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Integration | Single-point accountability compresses permitting cycles for cloud operators facing Brazil's Lei Geral de Proteção de Dados deadlines. |
| Free Cooling Economizer Deployment | Andean altitude locations in Bogotá slash chiller energy consumption versus tropical coastal alternatives. |
| Prefabricated Power Module Scale-Up | Schneider Electric's electrical infrastructure modules accelerate deployment schedules for hyperscale campuses. |
| Liquid Cooling Pilot Expansion | Immersion cooling for AI training clusters reduces mechanical infrastructure capital intensity in São Paulo's tropical humidity. |
| Commissioning Agent Certification | Uptime Institute Tier III validation expertise creates recurring maintenance revenue streams post-construction. |
Research Methodology
Initial hypotheses were tested against primary input from data center construction executives, MEP engineering directors, hyperscale cloud procurement officers, and commissioning agents and refined through secondary validation against ANVISA regulatory filings, national communications regulator data residency directives, submarine cable landing records, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline analysis triangulated with top-down market sizing across facility type, service bundling, and end-user concentration dimensions.
Variance decomposition across the projection horizon isolates growth contributions from data localization mandates, hyperscale standardization patterns, and edge computing deployment acceleration. Segmentation modeling incorporates product type, service bundling, technology layer, and end-user archetype dimensions with regional regulatory cluster overlays. CAGRs derive from facility completion timelines, power density evolution curves, and equipment procurement cycle analysis.
Decision-makers should treat outputs as directional under sustained data residency enforcement and copper price stability assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market