
 Europe Aluminum Door and Window Market | 2026-2036
Europe Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminum Door and Window Market Analytics
Green project finance and sustainability-linked leasing is reconfiguring capital access for facade contractors across Europe. Alumil leverages its integrated extrusion and coating capacity to anchor supply security for large-scale French commercial projects. Reynaers Aluminium sustains R&D intensity in thermally efficient profiles, while Schüco competes through precision-engineered hardware systems that extend building lifecycle performance.
Europe aluminum door and window systems comprise extruded aluminum alloy frames with polyamide thermal breaks, typically achieving U-values below 1.0 W/m²K when paired with double or triple glazing, manufactured through profile extrusion, thermal barrier insertion, and precision machining processes designed to manage heat transfer, acoustic insulation, and structural loads in building envelopes. Casement windows and sliding doors occupy the largest share of specification volumes, while bi-folding doors represent the fastest-growing product category as residential developers prioritize indoor-outdoor connectivity. The renovation and retrofitting application segment deepens its share of demand as the EU Energy Performance of Buildings Directive tightens compliance thresholds across existing stock.
REACH regulation and the EU F-Gas Regulation shape material compliance and thermal insulation gas specifications for glazing units sold across member states, while CE marking under the Construction Products Regulation mandates declared performance for structural safety and energy efficiency. ECHA's evolving substance restrictions on chromium VI in surface treatments are forcing coating line investments. Stakeholders must monitor how the EU Green Deal's embodied carbon reporting requirements will alter supplier qualification criteria for public procurement frameworks.
Market Dynamics
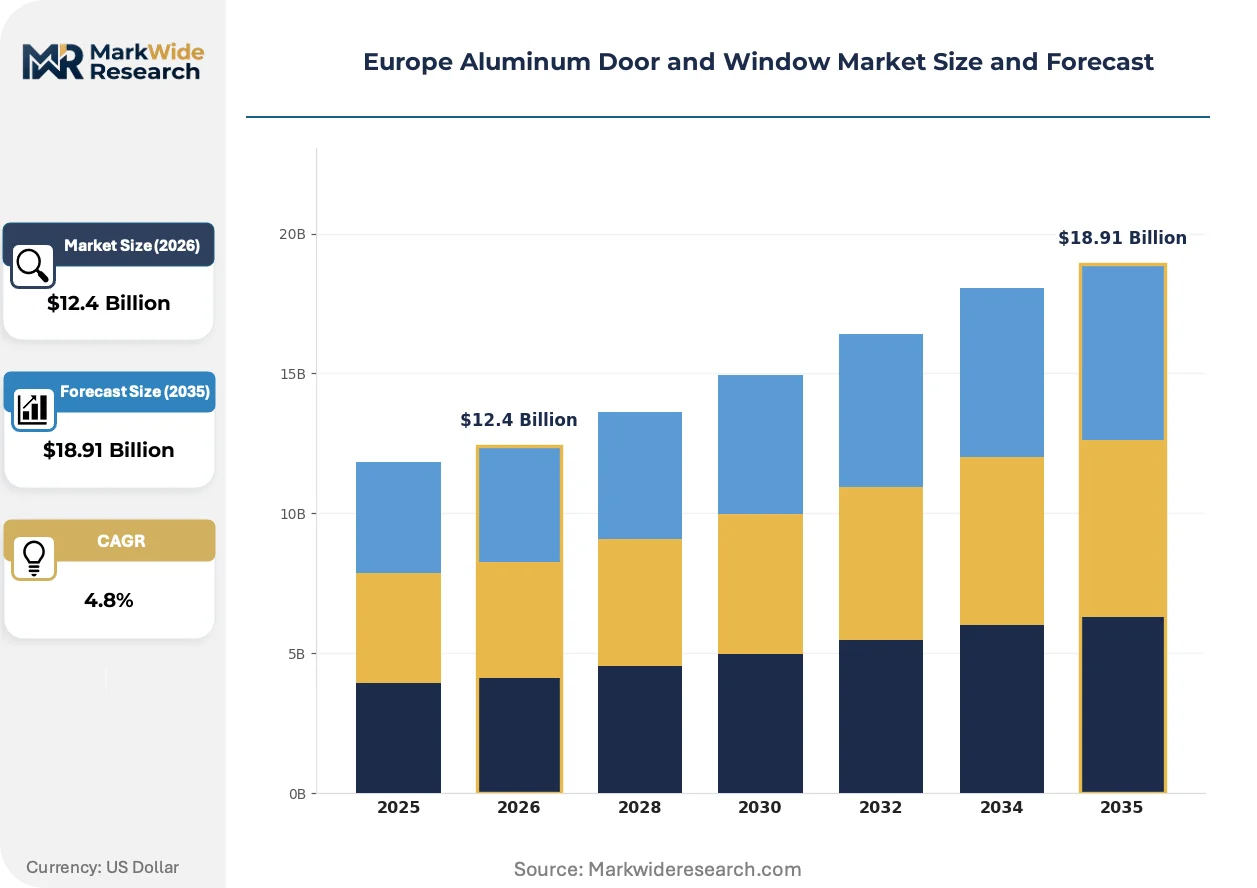
The EU Green Deal's tightening energy performance standards are compressing replacement cycles across Europe's building stock, forcing asset owners to accelerate facade upgrades and reconfiguring procurement priorities for thermal efficiency.
Growth Catalysts
- EPBD compliance mandates:The EU Energy Performance of Buildings Directive tightens thresholds for existing stock, deepening renovation demand in France's Île-de-France corridor and Germany's Rhine-Ruhr zone.
- France commercial office expansion:Developers across Paris and Lyon are specifying thermally broken aluminum systems to meet sustainability-linked leasing requirements and secure green project finance.
- Thermal break polymer advancement:Polyamide thermal barrier insertion processes now achieve U-values below 1.0 W/m²K, enabling specification in passive house and net-zero building envelopes.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum input costs fluctuate with LME pricing and European energy premiums, squeezing margin predictability for extrusion-dependent fabricators.
- ECHA substance restrictions:REACH evolving limits on chromium VI in surface treatments force coating line capital investments before payback periods mature.
- Steel-PVC hybrid substitution:Cost-sensitive residential developers in Southern Europe pivot to steel-reinforced PVC frames where thermal performance requirements permit.
Strategic Opportunities
- Netherlands retrofit acceleration:Amsterdam and Rotterdam municipal building codes now mandate facade energy upgrades for commercial stock over 15 years old.
- Bi-folding door residential penetration:Indoor-outdoor connectivity specifications expand in Spanish and Portuguese coastal developments where aluminum corrosion resistance outperforms alternatives.
- Embodied carbon procurement criteria:EU Green Deal reporting requirements for public frameworks will privilege suppliers with verified low-carbon extrusion and coating processes.
Industry Challenges
- Thermal break installation skill scarcity:Precision machining and polyamide insertion require certified technicians that training pipelines have not matched to demand velocity.
- CE marking documentation burden:Construction Products Regulation declared performance testing for structural safety and energy efficiency extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminum Door and Window Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Casement Windows, Bi-Folding Doors, Awning Windows End User: Residential, Commercial, Industrial, Institutional Application: New Construction, Renovation, Remodeling, Retrofitting Installation Type: Inward Opening, Outward Opening, Fixed, Modular |
| Companies Covered | Alumil, Wicona, Schüco, Fintecnic, Technal, Reynaers Aluminium, Hydro Building Systems, GEZE, AluK, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminum Door and Window Market Evolving Landscape
Thermal efficiency engineering and digital fabrication are reshaping how aluminum systems are specified, manufactured, and installed across European building envelopes.
Polyamide thermal break technology is migrating from standard 14.8mm barrier widths to 24mm and 34mm multi-chamber configurations. German and French commercial developers now specify these enhanced profiles as baseline for Class A energy ratings. The shift is compressing specification margins for legacy single-barrier systems and forcing extruders to retool die configurations.
REACH and the EU F-Gas Regulation are reshaping glazing unit gas fills and coating chemistry compliance. Krypton and xenon substitution for argon in triple glazing now requires documented supply chain traceability under ECHA substance restrictions. Fabricators serving Benelux and Nordic markets are consolidating supplier audits to preempt certification gaps.
Façade contractors are consolidating specification authority through design-build contracts that bypass traditional architect-led procurement. Large-scale commercial projects in Milan and Madrid now route aluminum system selection through contractor engineering teams with lifecycle cost modeling tools. This concentrates volume with fabricators offering integrated extrusion, thermal break, and hardware packages.
Europe Aluminum Door and Window Market Segmentation
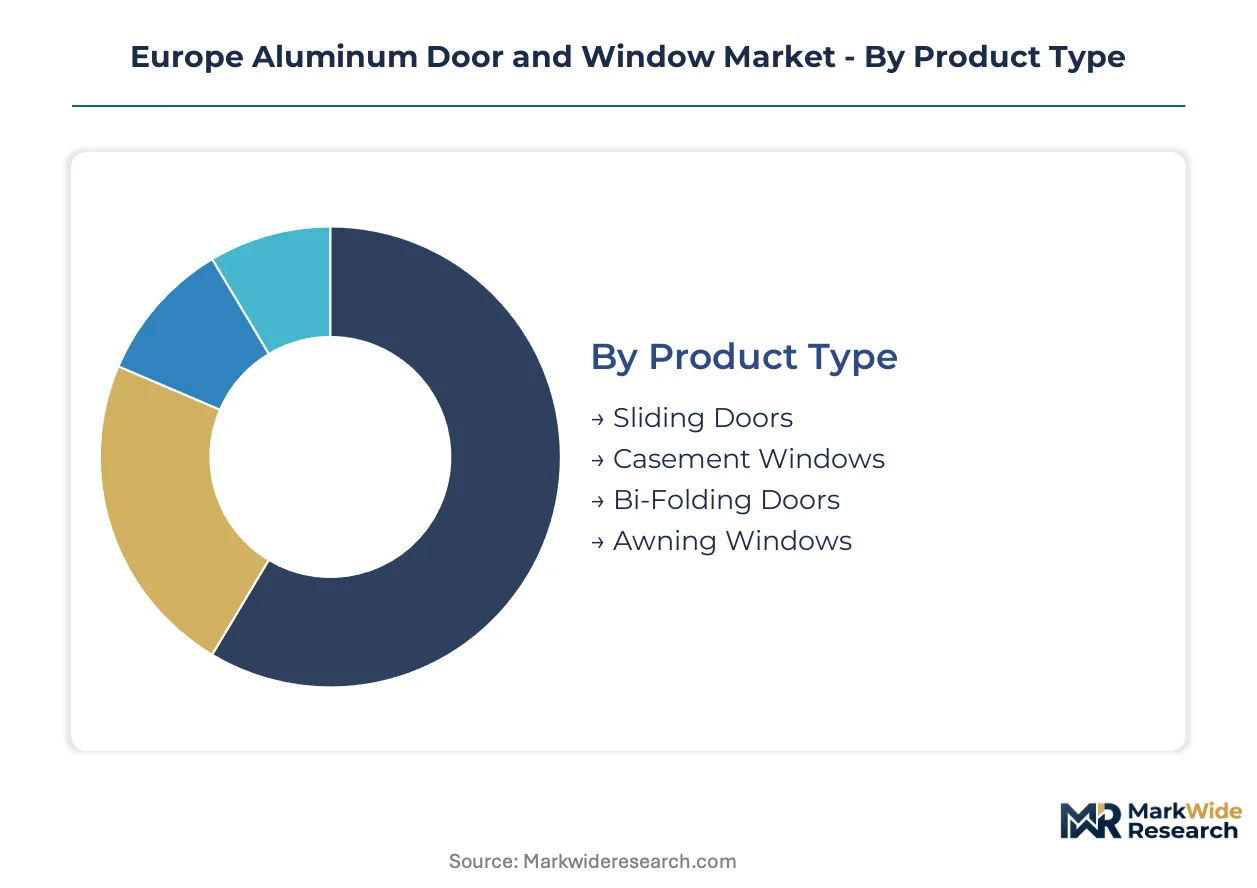
Specification cycles vary dramatically across Europe's aluminum door and window market. Product type determines thermal performance upgrade frequency, while application context shapes procurement authority and margin structures.
Product Type:
Replacement velocity diverges sharply — exterior-facing systems weather faster than interior partitions, and moving hardware wears quicker than fixed glazing.
- Casement Windows:Hinged sashes with compression seals achieve U-values below 1.0 W/m²K when paired with triple glazing. Rhine-Ruhr commercial developers specify these as baseline for Class A energy ratings, though thermal break installation skill scarcity extends lead times.
- Bi-Folding Doors:Multi-panel track systems with corrosion-resistant aluminum framing enable full aperture opening. Spanish and Portuguese coastal residential projects prioritize indoor-outdoor connectivity, driving specification where salt air degrades alternatives.
- Sliding Doors:Horizontal track systems with tandem roller hardware dominate balcony and terrace applications across French Île-de-France multifamily stock.
- Awning Windows:Top-hinged projection sashes with rain-shedding geometry serve ventilation-focused specifications in Benelux educational facilities.
Casement windows dominate installed base. Bi-folding doors are where expansion concentrates.
End User:
Procurement sophistication scales with project scale — institutional buyers wield lifecycle cost models, while residential selection hinges on immediate thermal comfort.
- Commercial:Office developers across Paris and Lyon specify thermally broken aluminum systems to secure green project finance and sustainability-linked leasing. Façade contractors now consolidate specification authority through design-build contracts.
- Residential:Single-family and multifamily owners prioritize indoor-outdoor connectivity in Spanish and Portuguese coastal zones, where aluminum corrosion resistance outperforms steel-PVC hybrids.
- Institutional:Schools and healthcare facilities in Amsterdam and Rotterdam face municipal mandates for facade energy upgrades on stock over 15 years old.
- Industrial:Warehousing and logistics facilities specify fixed modular systems where thermal performance requirements permit lower-tier solutions.
Commercial commands specification value. Residential delivers volume velocity.
Application:
Project origin determines compliance burden — new construction embeds standards from foundation, while retrofit must reconcile with existing structural constraints.
- Renovation:EU Energy Performance of Buildings Directive thresholds force asset owners across Germany and France to accelerate facade upgrades. ECHA chromium VI restrictions complicate coating line transitions.
- New Construction:Greenfield commercial projects in Milan and Madrid route aluminum system selection through contractor engineering teams with embodied carbon modeling tools.
- Retrofitting:Amsterdam and Rotterdam municipal codes mandate energy upgrades for commercial stock exceeding 15 years, deepening demand for thermally efficient profiles.
- Remodeling:Residential interior reconfigurations drive selective window replacement where full envelope upgrades prove cost-prohibitive.
Renovation deepens share of demand. New construction concentrates premium specification.
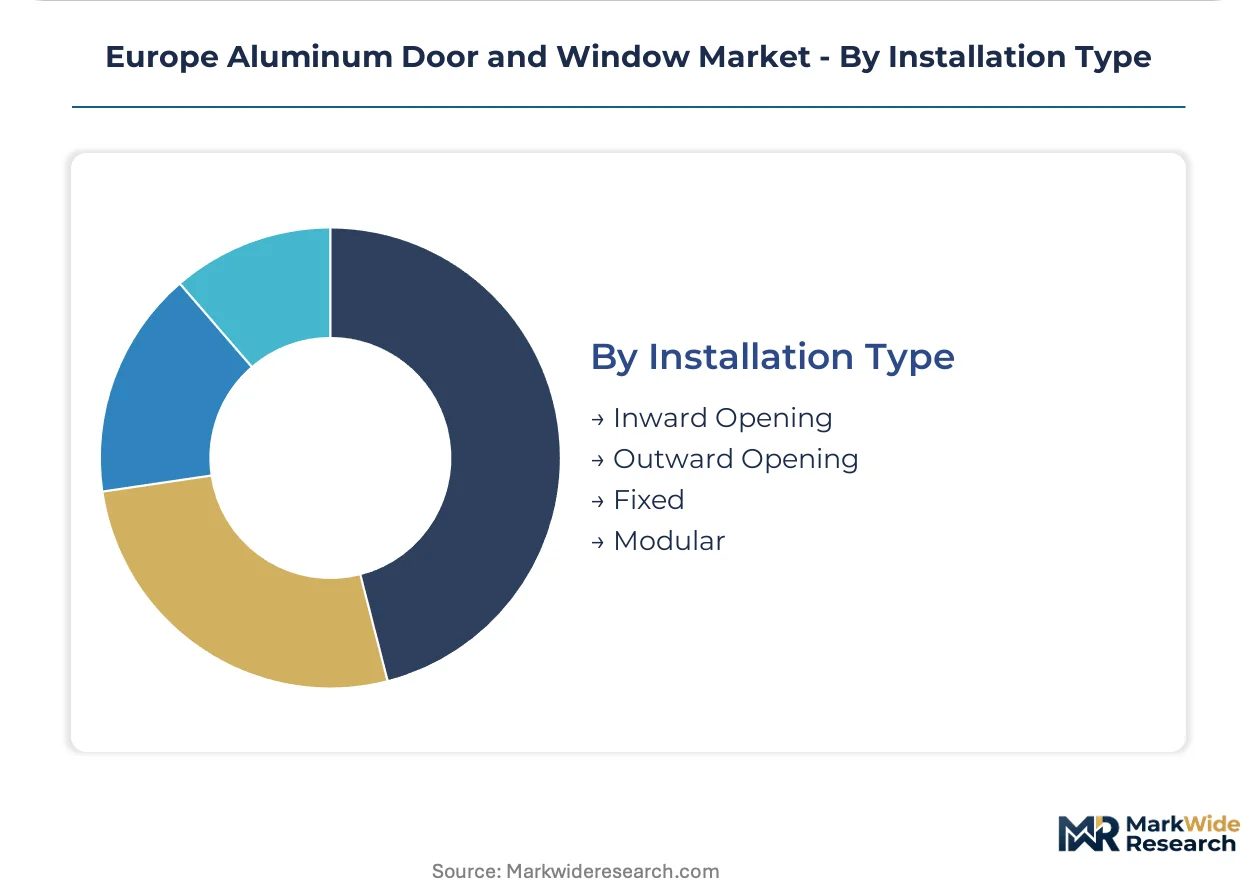
Installation Type:
Hardware complexity and weather exposure determine service intervals and lifecycle cost profiles.
- Outward Opening:Hinged sashes projecting exterior maximize interior floor area. German commercial specifications favor these for rain-shedding performance.
- Modular:Pre-assembled frame and sash units reduce on-site labor dependence. Façade contractors in Benelux consolidate procurement with fabricators offering integrated extrusion and hardware packages.
- Inward Opening:Interior projection enables cleaning access from inside, preferred in French high-rise residential.
- Fixed:Non-operable glazing minimizes hardware cost and air infiltration, specified where ventilation is handled mechanically.
Outward opening dominates commercial specification. Modular systems are climbing fastest as labor scarcity bites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's tightening energy performance standards are compressing replacement cycles across Europe's building stock, forcing asset owners to accelerate facade upgrades and reconfiguring procurement priorities for thermal efficiency.
Germany
Rhine-Ruhr metropolitan zone developers specify thermally broken aluminum systems for Class A energy ratings. The national building energy code (GEG) mandates stepwise efficiency improvements for existing commercial stock. Düsseldorf-based facade contractors consolidate procurement with fabricators offering integrated extrusion and hardware packages.
France
Paris and Lyon commercial office developers prioritize sustainability-linked leasing requirements to secure green project finance. The RE2020 environmental regulation tightens carbon thresholds for new construction and major renovations. Île-de-France corridor projects concentrate specification volumes for high-performance casement and sliding systems.
Netherlands
Amsterdam and Rotterdam municipal codes now mandate facade energy upgrades for commercial buildings exceeding 15 years of age. The national implementation of the EU Energy Performance of Buildings Directive accelerates retrofit demand. Randstad region contractors face thermal break installation skill scarcity that extends project lead times.
Spain
Coastal residential developments in Barcelona and Valencia prioritize bi-folding doors for indoor-outdoor connectivity. The national technical building code (CTE) updates thermal transmittance requirements for envelope components. Mediterranean climate corrosion resistance drives aluminum specification over steel-PVC hybrids.
Belgium
Brussels-Capital Region enforces stringent energy performance standards for building renovations under regional climate ordinances. Benelux educational facilities specify awning windows with rain-shedding geometry. Flemish and Walloon fabricators consolidate supplier audits to preempt REACH certification gaps.
Europe Aluminum Door and Window Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification tiers. The vendor base organizes around three strategic archetypes: integrated extrusion-coating fabricators, precision hardware system engineers, and regional installation specialists. Consolidation pressures intensify as facade contractors assume specification authority through design-build contracts. Dominant competitive moves include backward integration into thermal barrier polymer supply and geographic expansion through certified installer networks.
Among integrated European fabricators, Alumil and Reynaers Aluminium exemplify the extrusion-capability archetype, while Schüco occupies a position within the precision-engineered hardware tier. These entities represent contrasting strategic postures: captive supply security versus lifecycle performance extension. Hydro Building Systems anchors the Nordic-Benelux axis through its building systems division. Smaller specialists including Wicona, Technal, and AluK sit within regional specification niches where contractor relationships determine volume allocation.
| Leading Market Players |
|---|
| Alumil |
| Wicona |
| Schüco |
| Fintecnic |
| Technal |
| Reynaers Aluminium |
| Hydro Building Systems |
| GEZE |
| AluK |
| Others |
Value Network & Pricing Analysis
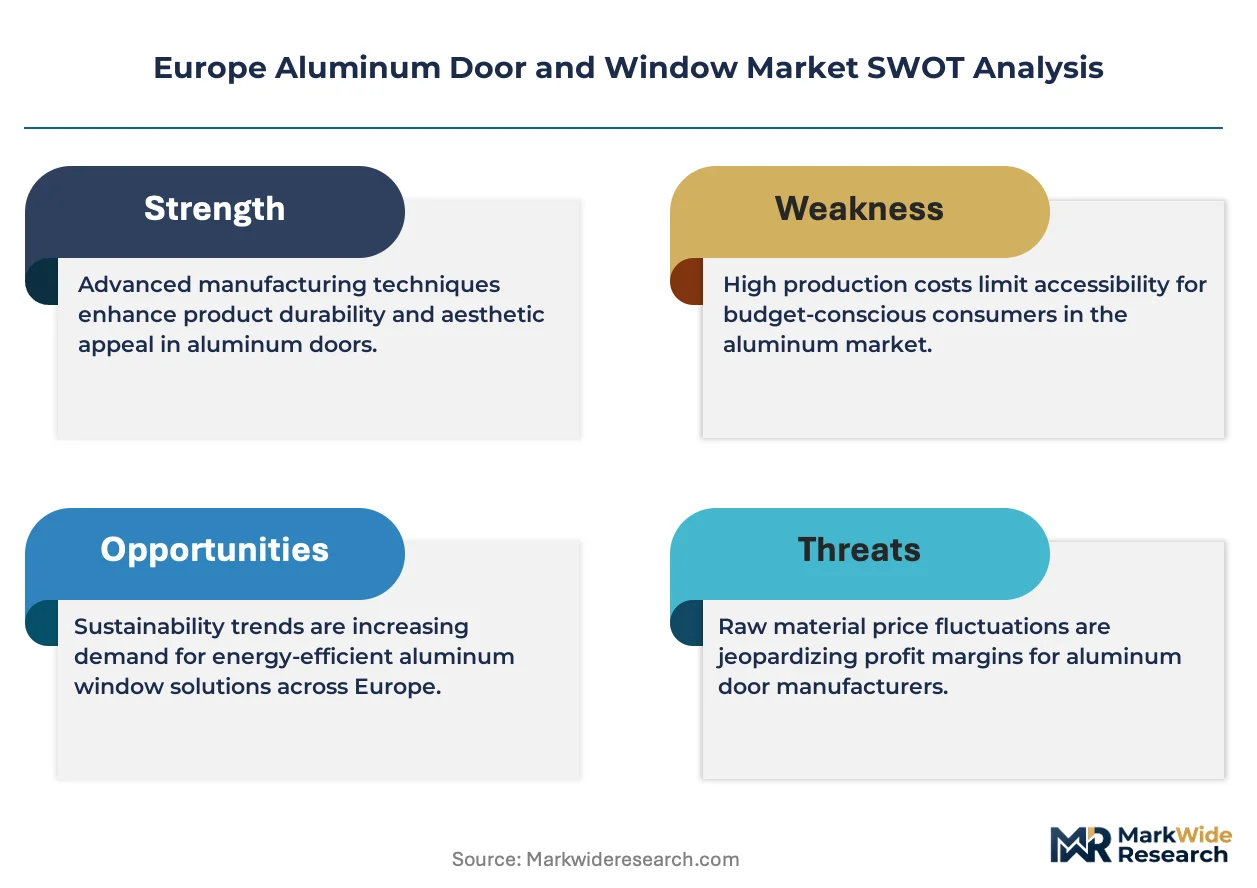
Overcapacity in Southern European extrusion capacity is pressuring margin structures while Rhine-Ruhr fabricators maintain pricing power through integrated thermal break capabilities. Utilization differentials between these regions are forcing asset-light competitors toward project-based pricing models and selective outsourcing.
Pricing Analysis
Certification level under CE marking and the Construction Products Regulation creates the primary spread between premium and standard tiers. Pricing stratifies across passive house-certified, Class A energy-rated, and baseline thermal performance levels. Cost compression in standard-grade extrusions is intensifying because steel-PVC hybrids are capturing price-sensitive residential volume in Mediterranean markets. Institutional buyers in the Netherlands and Germany exhibit the lowest price sensitivity due to lifecycle cost modeling mandates, while Southern European residential developers prioritize upfront capital minimization.
Supply Chain Analysis
Integrated extrusion capacity concentrates with Alumil in Greece, Reynaers Aluminium in Belgium, and Hydro Building Systems in Norway. Primary aluminum ingot draws from Norwegian smelters and Russian-origin metal subject to EU sanctions screening. Single-source vulnerability sits with polyamide thermal barrier polymer supply from German and Austrian compounders. Distribution runs through facade contractor networks in France and Germany, with direct specification authority bypassing traditional architect channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe aluminum door and window market functions as a regulatory-entrenchment defensive moat. CE marking requirements and ECHA substance restrictions create switching costs that protect incumbent positions while complicating new entrant qualification.
For Market Incumbents:Insulate specification share by securing captive polyamide thermal barrier supply through backward integration into polymer compounding. Accelerate coating line investments ahead of ECHA chromium VI phase-out deadlines to preempt competitor compliance gaps. Steel-PVC hybrid substitution in Southern Europe represents the primary substitution threat requiring differentiated corrosion-resistance positioning.
For New Entrants and Emerging Players:Netherlands municipal retrofit mandates for commercial stock over 15 years old represent the most penetrable entry point for certified installation services. Portuguese coastal residential bi-folding door specifications offer white-space access where aluminum corrosion resistance outperforms alternatives. Partner with Randstad region facade contractors lacking thermal break installation capacity to bypass direct certification burden.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across thermal break insertion and coating compliance lines. Target acquisition archetypes include regional fabricators with installed CE marking documentation and certified installer networks. Monitor LME aluminum pricing spreads against European energy premiums as the inflection signal for margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Supply | Captive thermal barrier polymer secures margin control against ECHA regulatory tightening. |
| Coating Line Compliance Upgrade | Chromium VI-free surface treatment capacity unlocks EU Green Deal procurement eligibility. |
| Certified Installer Network Expansion | Randstad and Rhine-Ruhr technician scarcity creates channel control leverage. |
| Design-Build Contractor Partnership | Façade engineering team relationships bypass architect-led procurement concentration. |
| Embodied Carbon Verification Program | Low-carbon extrusion documentation qualifies for Netherlands and France public frameworks. |
Research Methodology
Cross-validation between facade contractor procurement data and ECHA regulatory filing databases anchors the qualitative findings. Primary interviews with extrusion plant managers, thermal break installation technicians, commercial developer specification leads, and municipal building code officers in Germany, France, and the Netherlands were synthesized with secondary validation from EU Construction Products Regulation declarations, REACH substance restriction updates, and national building energy code implementations. Bottom-up project pipeline tracking and top-down regional construction permit analysis were triangulated to establish volume baselines.
Calibration against historical replacement cycle data and energy efficiency mandate implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, application context, and installation complexity, with regional regulatory cluster as an industry-specific overlay. CAGRs were derived from installed base depreciation curves and compliance-driven upgrade velocity assumptions. Primary aluminum price volatility and thermal break polymer supply constraints were incorporated as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in European construction lending rates and green project finance availability would shift the trajectory. Forecasts reflect assumptions on EPBD implementation consistency and ECHA substance restriction timelines. Quarterly review of municipal retrofit mandate adoption and LME aluminum forward curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
France Architectural Coatings Market
Building Materials
Steel Products Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Geocells Market
Building Materials
Concrete Admixtures Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Construction Stone Market
Building Materials
Aluminum Door and Window Market
Building Materials
US Facade Market
Building Materials
Thin Brick Market
Building Materials
Roofing and Insulation Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Natural Stone Market