
 Rubbing Bricks Market | 2026-2036
Rubbing Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Rubbing Bricks Market Analysis
ISO 9001 quality management certification is redrawing competitive boundaries in rubbing brick supply. Saint-Gobain leverages its fused mineral technology leadership to sustain premium positioning across European and North American distribution channels. Zische Schleifwerkzeuge GmbH anchors its competitiveness through specialized silicon carbide formulations for precision stonework applications.
Rubbing bricks are abrasive hand tools manufactured from bonded silicon carbide, aluminum oxide, or synthetic diamond particles set in vitrified or resinoid matrices, typically measuring 150-250 mm in length with grit ratings spanning 16 to 220 for controlled material removal. Contractors deploy these tools for dressing concrete joints, smoothing masonry surfaces, and refining stone edges where power equipment risks substrate damage. Silicon carbide variants dominate volume due to superior hardness on masonry substrates, while diamond-impregnated grades command premium pricing in stone finishing where extended tool life justifies higher unit costs. Application demand skews toward construction and maintenance segments as infrastructure age drives resurfacing activity across developed economies.
OSHA enforces permissible exposure limits for respirable crystalline silica that mandate wet-cutting methods and respiratory programs on sites using abrasive tools. EPA hazardous air pollutant standards affect kiln-fired abrasive manufacturing, pushing producers toward lower-emission bonding processes. ECHA REACH compliance requirements govern chemical composition disclosures for imported abrasive products entering European markets. Stakeholders must monitor evolving silica exposure thresholds and bonding chemistry restrictions that will determine which product formulations retain market access.
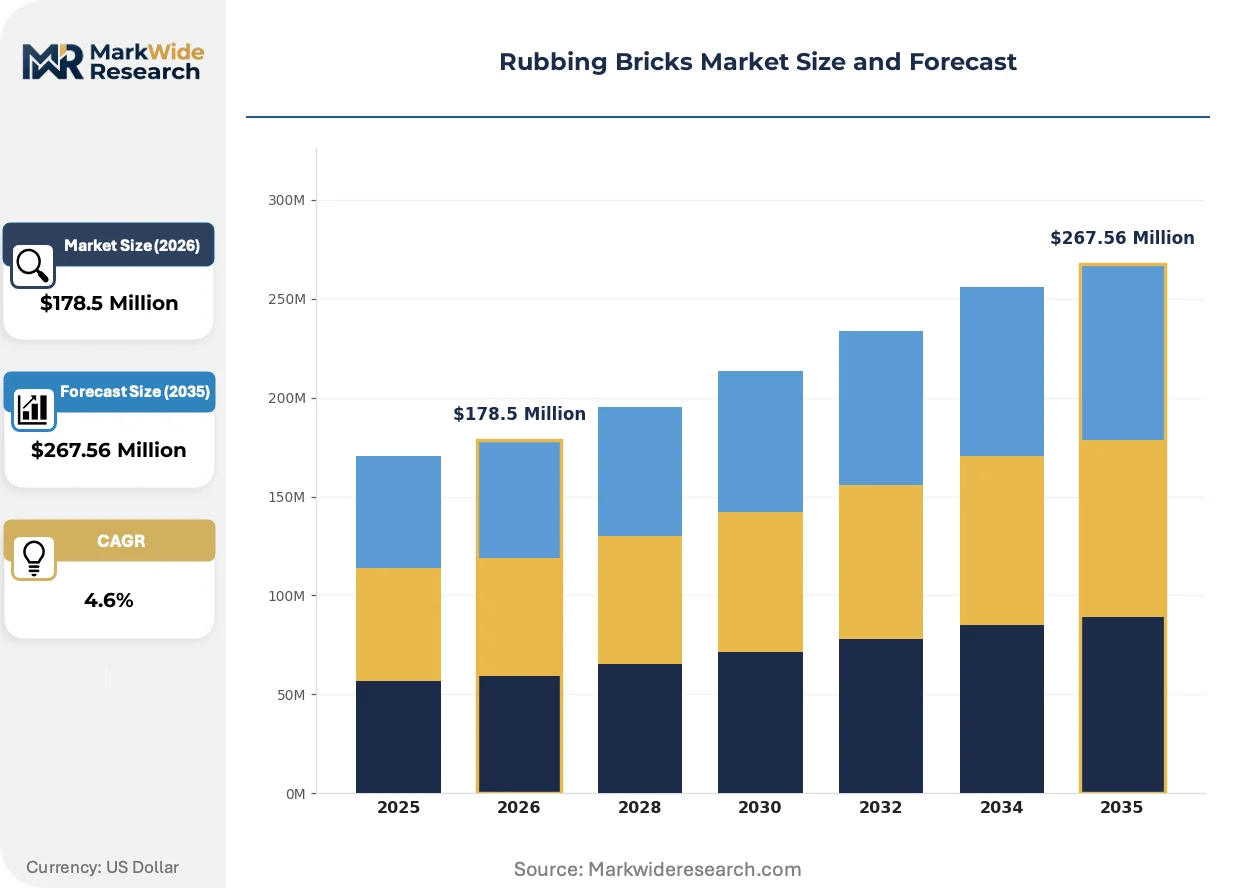
Market Dynamics
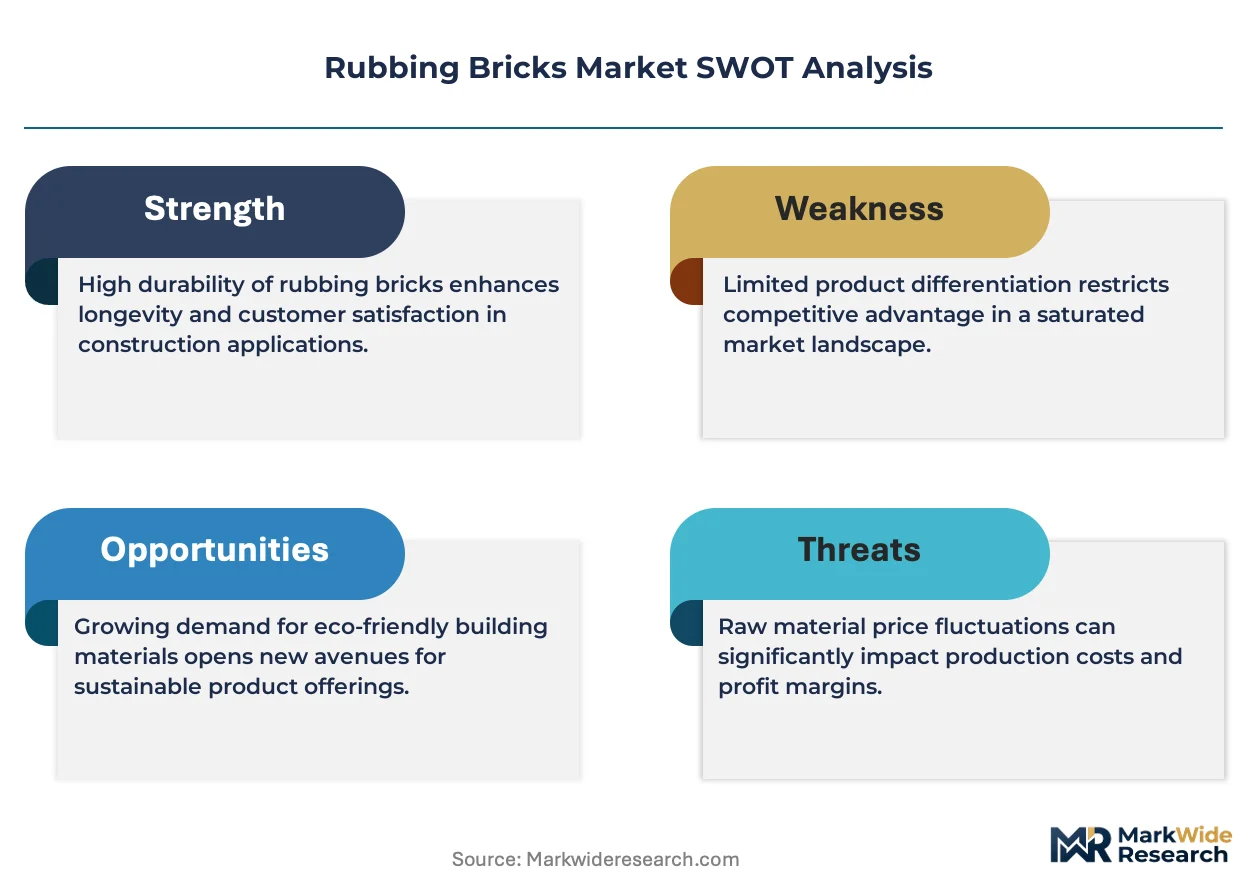
OSHA's respirable crystalline silica exposure limits are compressing job-site practices across commercial masonry, forcing contractors toward wet-cutting protocols and certified respiratory programs that favor premium bonded-abrasive formulations over commodity alternatives.
Growth Catalysts
- Commercial Construction Rebound:Masonry contractors in the United States are expanding tool procurement as infrastructure spending accelerates renovation and new-build activity.
- REACH Compliance Requirements:ECHA chemical disclosure mandates for imported abrasives are filtering out low-grade suppliers and consolidating shelf space for certified European producers.
- Synthetic Diamond Bonding:Precision stone-finishing applications are migrating toward diamond-impregnated matrices that extend tool life on high-value restoration projects.
Market Restraints
- Fused Mineral Input Volatility:Silicon carbide and aluminum oxide prices fluctuate with energy-intensive kiln operations concentrated in China and Ukraine.
- Kiln-Firing Emission Controls:EPA hazardous air pollutant standards raise compliance costs for vitrified bond manufacturing, squeezing smaller domestic producers.
- Power Tool Substitution:Battery-operated angle grinders with diamond blades are capturing joint-dressing tasks from manual rubbing bricks on large commercial sites.
Strategic Opportunities
- Heritage Restoration Demand:Aging infrastructure across Germany and Italy is driving specialized procurement for precision stonework tools that protect substrate integrity.
- Wet-Cutting Accessory Bundling:Distributors are pairing silicon carbide rubbing bricks with OSHA-compliant water suppression kits to capture bundled specification wins.
- ISO 9001 Certification Gap:Mid-tier suppliers lacking quality management credentials face exclusion from European public works tenders, creating acquisition targets for certified competitors.
Industry Challenges
- Silica Competency Certification:Contractors must train crews on respirable dust recognition and wet-method compliance, extending project mobilization timelines.
- Bond Chemistry Reformulation:Manufacturers are racing to replace phenolic resin matrices ahead of anticipated EPA air toxics rulemaking, straining R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubbing Bricks Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $267.56 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide, Aluminum Oxide, Diamond, Others Application: Construction, Metalworking, Maintenance, Stone Finishing Grade: Coarse, Medium, Fine, Ultra-Fine End User: Contractors, Fabricators, DIY Users, Industrial Users |
| Companies Covered | Saint-Gobain, Norton, Kraft Tool, Marshalltown, Zische Schleifwerkzeuge GmbH, 3M, Hilti, Bosch, A. Richard Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubbing Bricks Market Emerging Trajectories
Product differentiation is migrating from grit specification toward certified safety bundling and substrate-specific formulation, while distribution channels consolidate around specialized construction supply platforms.
Diamond-impregnated resinoid matrices are supplanting conventional silicon carbide vitrified bonds in high-end stone restoration, where heritage contractors prioritize substrate preservation over unit cost. Museum and monument conservators in France and Italy specify these grades exclusively. The shift is compressing volume share for standard 16-80 grit silicon carbide lines in premium channels.
OSHA's silica enforcement is tightening respiratory protection mandates on U.S. job sites using abrasive hand tools. Wet-cutting methods and documented exposure assessment programs are becoming de facto requirements for commercial masonry tenders. Contractors lacking compliant protocols face project disqualification, redirecting procurement toward suppliers offering certified safety documentation packages.
Specification authority is concentrating with general contractors and facility managers who unbundle tool procurement from traditional distributor relationships. Direct-to-site fulfillment platforms are capturing specification influence previously held by local masonry supply houses. This channel compression is most visible in the United States, where national construction groups centralize purchasing across multi-state project portfolios.
Rubbing Bricks Market Segmentation
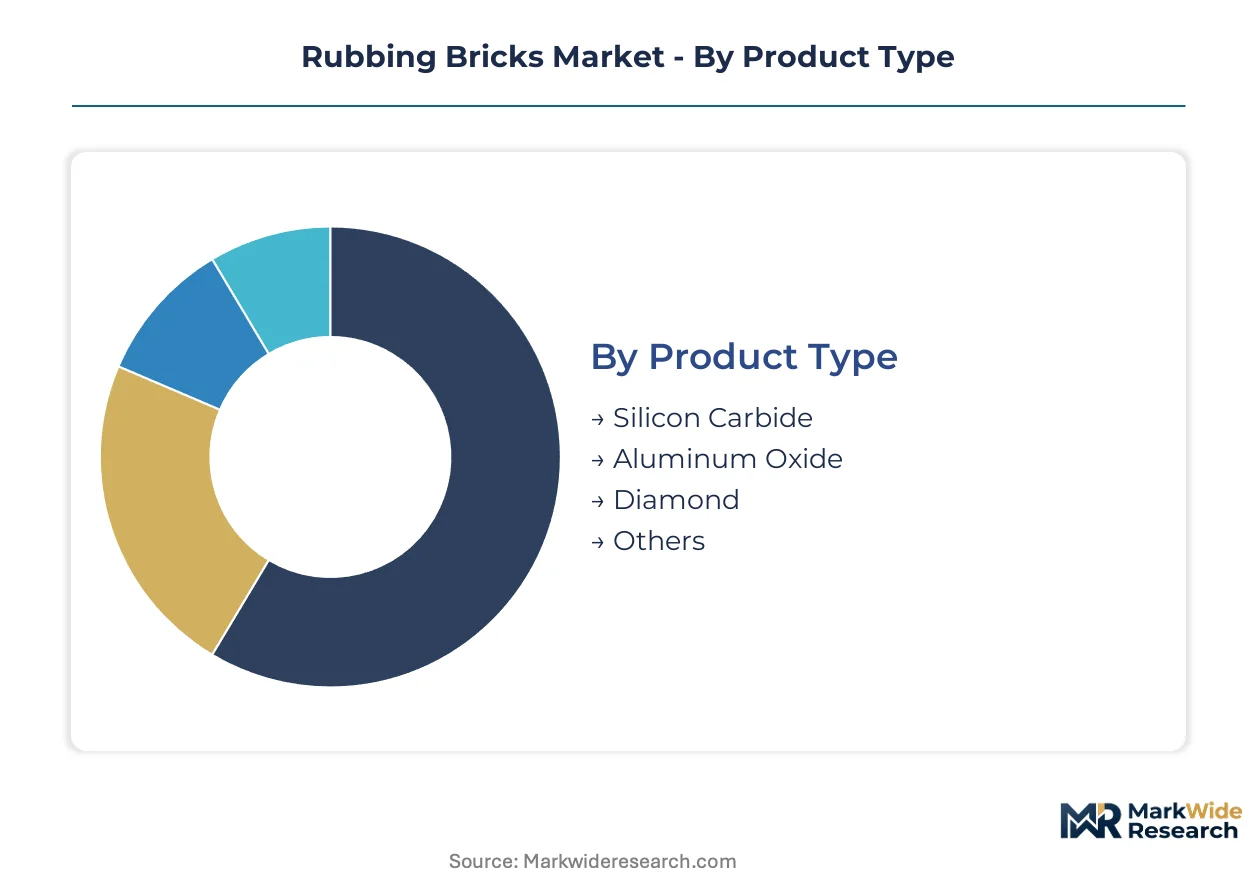
Rubbing bricks serve distinct substrate requirements across masonry, metal, and stone restoration workflows. Channel strategy varies sharply by segment—construction supply houses dominate bulk contractor sales, while specialized distributors capture heritage restoration and precision fabrication demand.
Product Type:
Distribution channels stratify sharply by abrasive technology, with silicon carbide flowing through construction supply houses and diamond grades concentrating in specialized restoration distributors.
- Silicon Carbide:Vitrified or resinoid-bonded silicon carbide particles deliver superior hardness against concrete and masonry substrates. Demand concentrates with U.S. masonry contractors dressing control joints and smoothing poured surfaces where OSHA wet-cutting mandates now prevail.
- Aluminum Oxide:Tougher fracturing characteristics suit ferrous metalworking applications. Fabricators in Germany and Italy specify aluminum oxide for weld seam preparation and edge refinement on structural steel components.
- Diamond:Impregnated resinoid matrices command premium positioning in heritage stone restoration where substrate preservation outweighs unit cost.
- Others:Ceramic alumina and sol-gel formulations serve niche high-temperature metalworking applications.
Silicon carbide dominates installed base. Diamond is where expansion concentrates.
Application:
Cost tier differentiation separates commodity construction procurement from premium restoration specification.
- Construction:Joint dressing and surface preparation on commercial masonry projects drive volume procurement through national distributor networks. U.S. infrastructure spending is accelerating specification of OSHA-compliant wet-cutting accessory bundles.
- Metalworking:Weld cleanup and edge refinement on structural steel require aluminum oxide formulations with controlled fracture properties. German fabricators prioritize ISO 9001-certified supply for automotive and machinery sector compliance.
- Maintenance:Infrastructure resurfacing across aging U.S. highways and bridges sustains recurring demand for coarse-grade silicon carbide lines.
- Stone Finishing:Museum and monument conservators in France and Italy specify diamond-impregnated grades exclusively for substrate-sensitive restoration work.
Construction commands volume share. Stone finishing is climbing the fastest.
Grade:
Customer type determines grade specification—contractors bulk-purchase coarse and medium grades while fabricators and conservators precision-specify fine and ultra-fine lines.
- Coarse:16-36 grit silicon carbide formulations remove material aggressively on concrete joint dressing and heavy stock removal. U.S. commercial masonry contractors deploy coarse grades for initial surface preparation before finer finishing.
- Medium:46-80 grit balances removal rate with surface quality for general construction finishing and maintenance resurfacing.
- Fine:100-180 grit aluminum oxide serves metal fabricators requiring controlled edge refinement without substrate damage.
- Ultra-Fine:220 grit and finer diamond matrices enable precision stone polishing where heritage substrate integrity is paramount.
Coarse and medium grades dominate installed base. Ultra-fine is gaining share fastest.
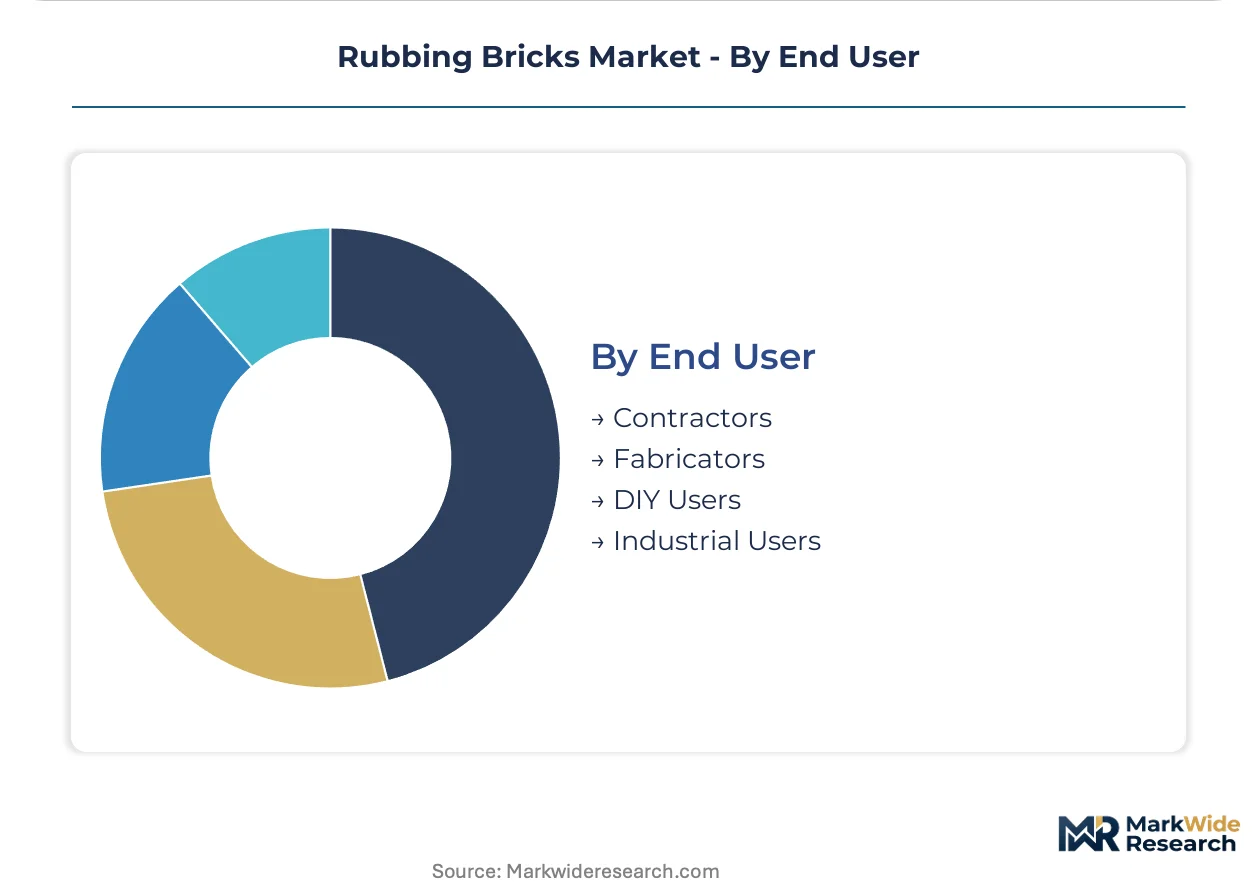
End User:
Procurement authority is shifting from traditional distributors toward direct-to-site platforms as national construction groups centralize purchasing.
- Contractors:Commercial masonry and concrete specialists in the United States drive bulk procurement through construction supply distributors. OSHA silica competency certification requirements are extending project mobilization timelines for non-compliant crews.
- Fabricators:Metalworking shops and structural steel processors specify aluminum oxide grades for weld preparation and edge refinement.
- DIY Users:Home improvement retailers serve occasional users with economy-grade silicon carbide lines for small-scale masonry repair.
- Industrial Users:Manufacturing maintenance departments procure coarse grades for equipment resurfacing and floor repair in facility management programs.
Contractors dominate installed base. Fabricators represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites German abrasives demand, while the Trans-Canada Highway renewal program anchors Canadian procurement volumes. Distribution networks radiate from these logistics nodes to serve masonry contractors and restoration specialists.
United States
Infrastructure spending packages are accelerating commercial masonry activity across the Sun Belt and Rust Belt corridors. OSHA silica exposure limits mandate wet-cutting protocols and respiratory protection programs on federal and state-funded job sites. Dallas-Fort Worth contractors are expanding tool procurement as warehouse construction booms along the Interstate 35 corridor.
Germany
Heritage restoration demand across Bavaria and Baden-Württemberg is driving precision stonework tool specification. ECHA REACH compliance requirements filter imported abrasives, consolidating shelf space for certified domestic and European producers. The Nuremberg industrial cluster hosts specialized distributors serving monument conservators and cathedral restoration workshops.
Italy
Museum and monument conservation programs in Rome, Florence, and Venice specify diamond-impregnated grades for substrate-sensitive restoration. EU Green Deal procurement guidelines favor lower-emission bonding processes in public works tenders. Lombardy fabricators supply precision aluminum oxide formulations to automotive and machinery sector metalworkers.
France
Grand Paris infrastructure renewal and provincial highway maintenance sustain coarse-grade silicon carbide demand. ANSM workplace safety oversight aligns with EU silica exposure frameworks, extending compliance documentation requirements. The Lyon-Rhône manufacturing belt concentrates aluminum oxide production for structural steel fabricators serving aerospace and automotive supply chains.
Canada
Trans-Canada Highway bridge rehabilitation and municipal infrastructure aging drive maintenance segment procurement. Health Canada occupational exposure guidelines parallel OSHA frameworks, requiring respiratory programs on federally funded construction sites. Ontario construction supply distributors are bundling wet-cutting accessories with silicon carbide lines to capture provincial tender specifications.
Rubbing Bricks Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and bonding technology. The vendor base stratifies between scale-driven multinational suppliers and focused regional fabricators. Three archetypes dominate: fused mineral technology leaders, specialized silicon carbide formulators, and diversified construction tool conglomerates. Consolidation pressure is intensifying through ISO 9001 certification gaps and REACH compliance barriers that favor acquisition of credentialed mid-tier producers.
Within the premium technology tier, Saint-Gobain and Zische Schleifwerkzeuge GmbH exemplify divergent competitive positions. Saint-Gobain occupies a scale-driven position leveraging fused mineral leadership across European and North American channels. Zische Schleifwerkzeuge GmbH anchors specialized silicon carbide formulation expertise for precision stonework applications. Among diversified construction tool suppliers, Kraft Tool and Marshalltown represent North American distribution-focused archetypes competing through channel reach and contractor relationship density rather than proprietary abrasive technology.
| Leading Market Players |
|---|
| Saint-Gobain |
| Norton |
| Kraft Tool |
| Marshalltown |
| Zische Schleifwerkzeuge GmbH |
| 3M |
| Hilti |
| Bosch |
| A. Richard Tools |
| Others |
Supply Flow & Price Mechanics
Diamond-impregnated resinoid matrices replacing conventional silicon carbide vitrified bonds are redrawing supply geography toward specialized European formulators while compressing pricing power in commodity-grade channels. This substitution dynamic concentrates premium supply in Germany and Italy where heritage restoration demand justifies unit-cost premiums, while standard silicon carbide pricing faces downward pressure from Chinese kiln capacity and power-tool substitution.
Pricing Analysis
Volume-discount tiering structures separate procurement across construction-grade silicon carbide, precision aluminum oxide, and heritage-specification diamond matrices. Price differentiation rests on ISO 9001 certification status and OSHA-compliant safety documentation bundling. Cost compression in coarse-grade silicon carbide lines is intensifying because battery-operated angle grinders capture joint-dressing tasks from manual tools. Commercial masonry contractors exhibit highest price sensitivity; museum conservators demonstrate lowest sensitivity due to substrate-preservation mandates.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen container ports to Hamburg and Rotterdam are conditioning European distributor inventory strategies and landed-cost calculations. Fused mineral supply concentrates in China and Ukraine where energy-intensive kiln operations anchor silicon carbide and aluminum oxide production. Raw material flows draw from petroleum coke for silicon carbide synthesis, bauxite refining for aluminum oxide, and synthetic diamond feedstock from high-pressure presses. Single-source vulnerability runs through Ukrainian fused alumina capacity exposed to regional instability. Distribution runs through construction supply houses for bulk contractor sales and specialized restoration distributors for premium grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rubbing bricks market is entering a cyclical recovery phase as commercial construction rebounds across North America and infrastructure maintenance backlogs accumulate. This cyclical upswing favors suppliers with certified quality credentials and compliant safety bundling capabilities.
For Market Incumbents: Consolidate mid-tier ISO 9001-certified producers lacking REACH compliance bandwidth to capture European public works tender exclusion effects. Acquire specialized silicon carbide formulators in Germany to anchor heritage restoration channel control. Battery-powered tool substitution threatens manual rubbing brick volume; defend through wet-cutting accessory bundling and OSHA-compliant documentation packages that commodity alternatives cannot replicate.
For New Entrants and Emerging Players: Lead with diamond-impregnated resinoid matrices targeting museum and monument conservators in France and Italy where incumbent concentration remains lowest. White-space opportunity sits in precision stone-finishing applications where substrate-sensitive restoration mandates create specification barriers for commodity suppliers. Pursue direct-to-site fulfillment partnerships with national construction groups centralizing multi-state procurement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed construction tool distributors lacking proprietary abrasive technology and facing channel compression from direct-to-site platforms. Five-to-ten year viability hinges on bonding chemistry reformulation capabilities ahead of anticipated EPA air toxics rulemaking. Monitor phenolic resin replacement progress as inflection indicator for manufacturing cost structure and regulatory access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fused Mineral Supply | Captive silicon carbide production insulates margin from Chinese kiln energy cost volatility. |
| ISO 9001 Certification Investment | Quality credentials unlock European public works tenders filtering uncertified competitors. |
| Wet-Cutting Accessory Bundling | OSHA-compliant water suppression kits capture specification wins on federally funded masonry sites. |
| Diamond Matrix R&D Expansion | Heritage restoration demand in Rome and Florence commands premium pricing for substrate-preserving formulations. |
| Direct-to-Site Channel Development | National construction group procurement centralization favors fulfillment platforms over traditional distributors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association publications, customs import records, and regulatory filing databases. Primary interviews engaged procurement managers at commercial masonry contractors, product directors at construction supply distributors, and technical sales leads at specialized restoration equipment suppliers. Secondary validation drew from OSHA enforcement guidance documents, ECHA REACH substance registrations, and kiln-fired abrasive manufacturing emission disclosures. Bottom-up channel volume estimates triangulate against top-down construction spending allocation models.
Segmentation dimensions modeled include abrasive technology type, substrate application, grit grade specification, and end-user procurement authority across the projection horizon. CAGRs derive from installed base attrition rates, replacement cycle analysis, and specification trend extrapolation. Forecast inputs incorporate commercial construction permit data, infrastructure maintenance backlog reporting, and silica exposure regulation enforcement intensity indices.
Forecasts assume regulatory continuity in OSHA respirable crystalline silica frameworks and ECHA REACH chemical disclosure regimes; material policy shifts would require re-modeling. Bond chemistry restrictions, energy cost volatility in kiln operations, and power-tool substitution rates represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Coatings Market
Building Materials
Exterior Doors Market
Building Materials
Granite Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
US Cement Tiles Market
Building Materials
China Cement Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Fly Ash Bricks Market
Building Materials
Cement Tiles Market
Building Materials
Earthen Plasters Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
West Africa Cement Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
HDG Steel Pipe Market