
 Global Corrugated Steel Sheets Market | 2026-2036
Global Corrugated Steel Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corrugated Steel Sheets Market Intelligence
Production consolidation in China is broadening the range of pre-painted and galvanized products available for global export. ArcelorMittal leverages its extensive manufacturing footprint to serve large-scale construction projects across multiple continents. JSW Steel Ltd sustains its competitive edge through significant backward integration into raw material sourcing. Tata Steel Limited specializes in developing high-strength, value-added steel grades for specialized industrial applications.
Corrugated steel sheets are produced by cold-rolling steel coils into a ribbed or wavy profile, which significantly increases the material's structural rigidity and load-bearing capacity. This product is primarily used for durable, lightweight, and weather-resistant coverings in construction and agriculture. Hot-dip galvanized sheets remain the dominant product type due to their cost-effectiveness and proven corrosion resistance. Within applications, roofing constitutes the largest segment, while wall cladding represents a high-growth area in modern commercial and industrial building design.
Product quality and performance are governed by ISO 9001 standards for manufacturing and specific national building codes that dictate structural integrity. The European Union's REACH regulation impacts the chemical composition of coatings, while the US Environmental Protection Agency (EPA) influences rules on volatile organic compounds in paints. Stakeholder success will depend on navigating the evolving landscape of sustainable building material certifications and circular economy principles.
Market Dynamics
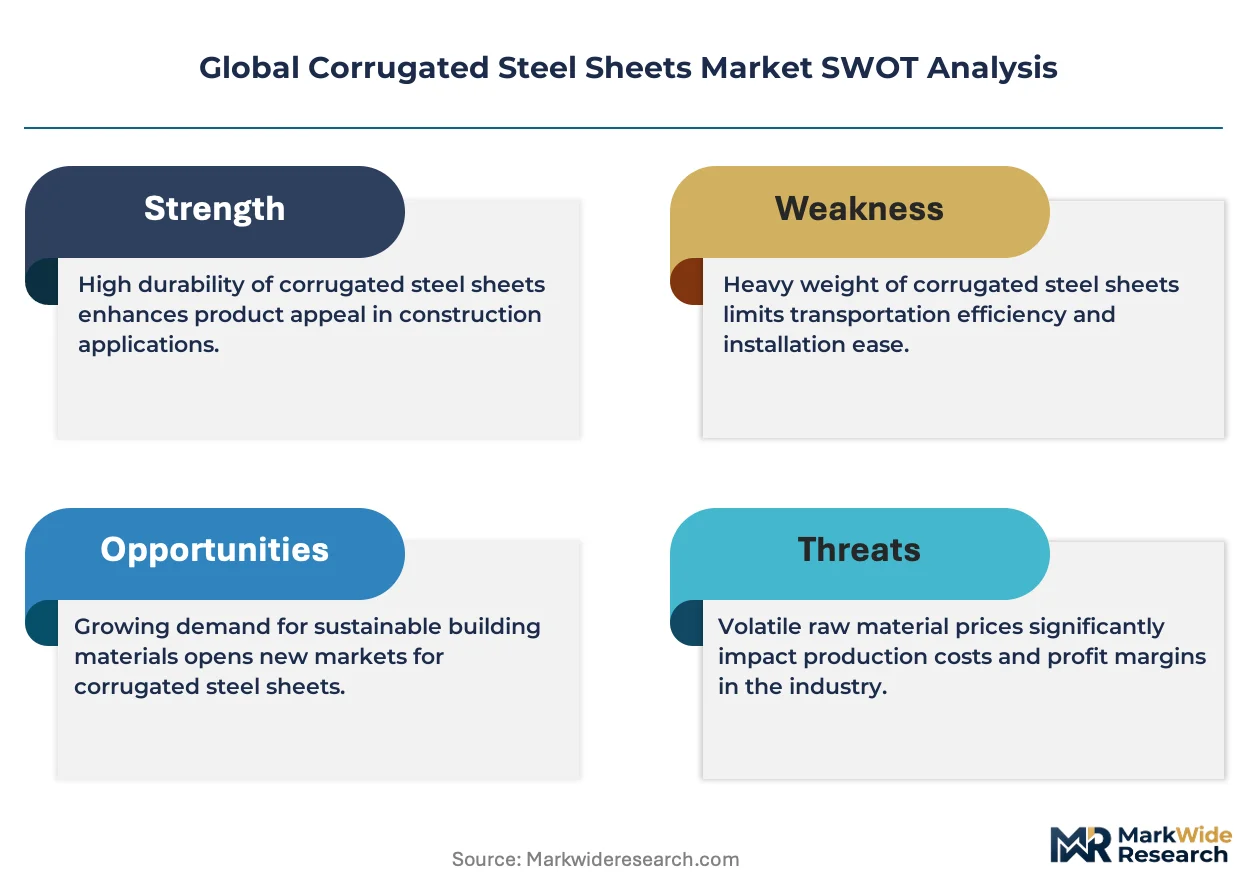
The expansion of warehousing and logistics infrastructure, driven by e-commerce growth, provides the central demand-side pull for the corrugated steel sheets market. This structural force is most prominent in roofing and cladding applications for large-span industrial buildings.
Growth Catalysts
- Infrastructure Investment:Government-led infrastructure projects in developing economies, particularly in India and Vietnam, are creating sustained demand for construction materials, including corrugated steel for roofing and siding in public works and industrial zones.
- Warehousing Expansion:The global build-out of fulfillment centers and logistics hubs to support e-commerce requires vast quantities of durable, cost-effective roofing and cladding, a core application for corrugated steel sheets.
- Coating Technology:Innovations in Aluzinc and other advanced alloy coatings are enhancing corrosion resistance and product longevity, expanding the material's viability in harsher environmental conditions and for higher-value architectural applications.
Market Restraints
- Raw Material Volatility:Price fluctuations in key inputs, specifically steel coil and zinc, create margin pressure and make long-term project cost estimation difficult for both manufacturers and end-users in the construction sector.
- Substitution Threat:In certain segments like agricultural buildings and residential roofing, alternative materials such as polycarbonate panels, fiber cement, and asphalt shingles present a significant competitive challenge based on aesthetics, insulation properties, or installation ease.
- Regulatory Compliance Costs:Adherence to environmental regulations like the EU's REACH directive for chemical substances in coatings increases production costs and complexity, particularly for exporters targeting multiple international markets.
Strategic Opportunities
- Prefabricated Construction:The increasing adoption of modular and prefabricated building methods creates an opportunity for standardized, factory-cut corrugated panels that can accelerate construction timelines and reduce on-site waste.
- African Market Development:Underpenetrated markets in Sub-Saharan Africa offer significant growth potential for low-cost, durable building solutions for housing, agricultural structures, and small-scale commercial facilities.
- Sustainable Product Lines:Developing corrugated sheets with high-recycled steel content and bio-based or low-VOC coatings can capture demand from projects seeking green building certifications like LEED or BREEAM.
Industry Challenges
- Code Harmonization:Manufacturers face the operational challenge of navigating a fragmented landscape of national and regional building codes, which dictate different structural, fire, and wind-load performance requirements.
- Export Logistics:Managing the complex and cost-sensitive logistics of shipping high-volume, relatively low-value corrugated steel products from concentrated production hubs in China to diverse global markets remains a significant hurdle.
- Certification Delays:The time and expense required to achieve product certification against multiple standards, such as ISO 9001 for quality management and specific national building approvals, can slow market entry for new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corrugated Steel Sheets Market |
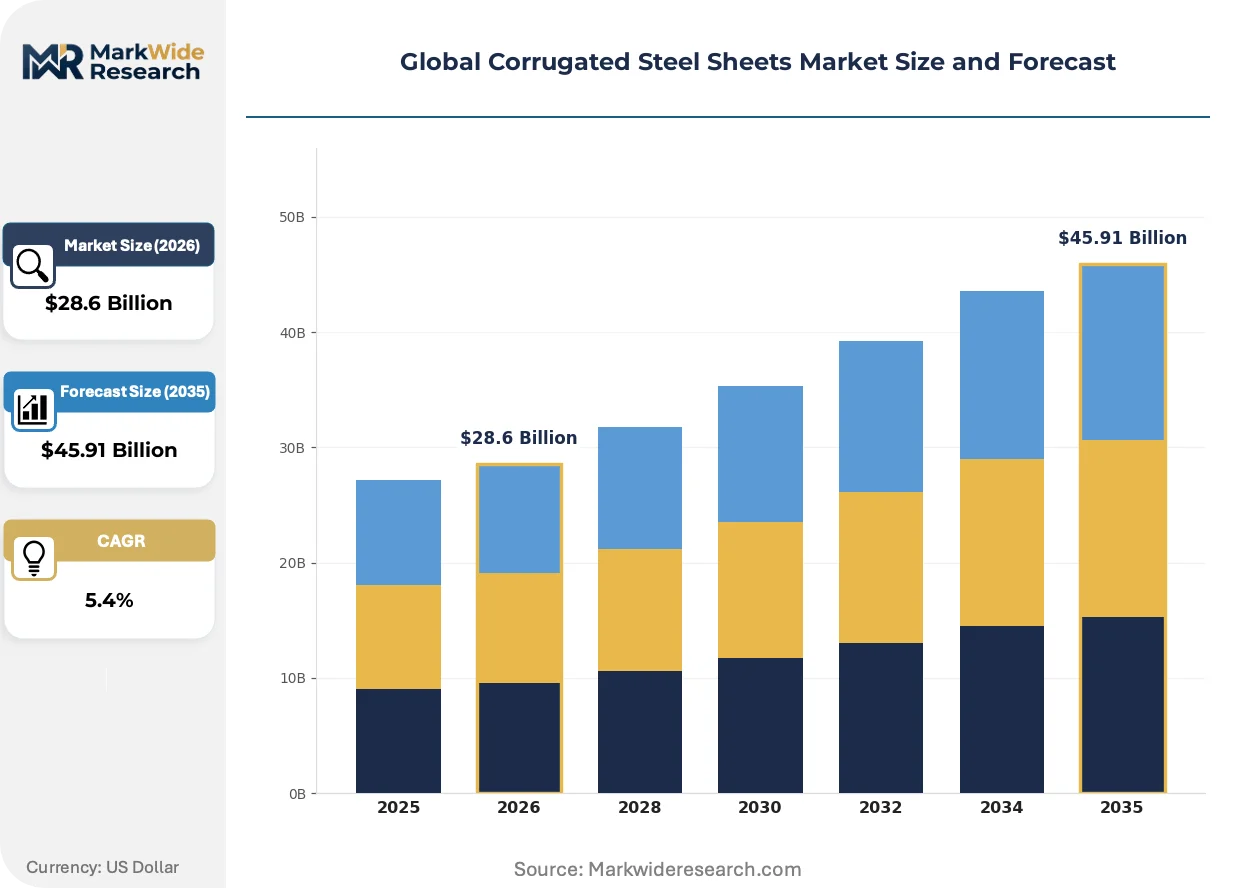
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot-Dip Galvanized, Galvannealed, Pre-Painted, Stainless Steel, Aluzinc Application: Roofing, Wall Cladding, Fencing, Packaging, Flooring End User: Construction Firms, Agricultural Enterprises, Warehousing Facilities, Manufacturing Units, Commercial Complexes Coating Technology: Zinc Coating, Organic Coating, Epoxy Coating, Polyester Coating, PVC Coating |
| Companies Covered | BlueScope Steel Limited, JSW Steel Ltd, ArcelorMittal, Nippon Steel Corporation, Tata Steel Limited, Bansal Roofing Products, McElroy Metal, Inc., Shandong Hengze New Material Co.,Ltd, Zhongjie Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corrugated Steel Sheets Market Strategic Shifts & Innovations
The market's evolution is defined by a dual focus on material science advancements that enhance durability and a response to global sustainability mandates. These pressures are compelling producers to innovate beyond basic product offerings toward value-added, certified solutions.
Advanced alloy coatings, particularly Aluzinc, provide superior long-term corrosion resistance by combining the barrier protection of aluminum with the sacrificial properties of zinc. The construction sector, especially for industrial buildings in coastal and high-pollution areas, is increasingly specifying these premium products. This higher performance standard is overtaking traditional hot-dip galvanization in applications where lifecycle cost and durability are the primary decision drivers.
European Union regulations, notably REACH, are placing stringent controls on chemicals used in metal coatings and surface treatments, impacting the entire supply chain. This is forcing manufacturers to invest in R&D for compliant, chrome-free passivation technologies and alternative paint formulations. The roofing and cladding segment is most affected, prompting a shift toward more environmentally benign coating systems to ensure continued access to the European market.
A notable behavioral shift among specifiers and large construction contractors is the prioritization of materials with documented environmental credentials, such as Environmental Product Declarations (EPDs). This disrupts purchasing decisions based purely on initial cost, favoring suppliers who can provide data on recycled content and lifecycle impacts. This trend is most prominent in North American and European commercial projects pursuing green building certifications.
Global Corrugated Steel Sheets Market Segmentation
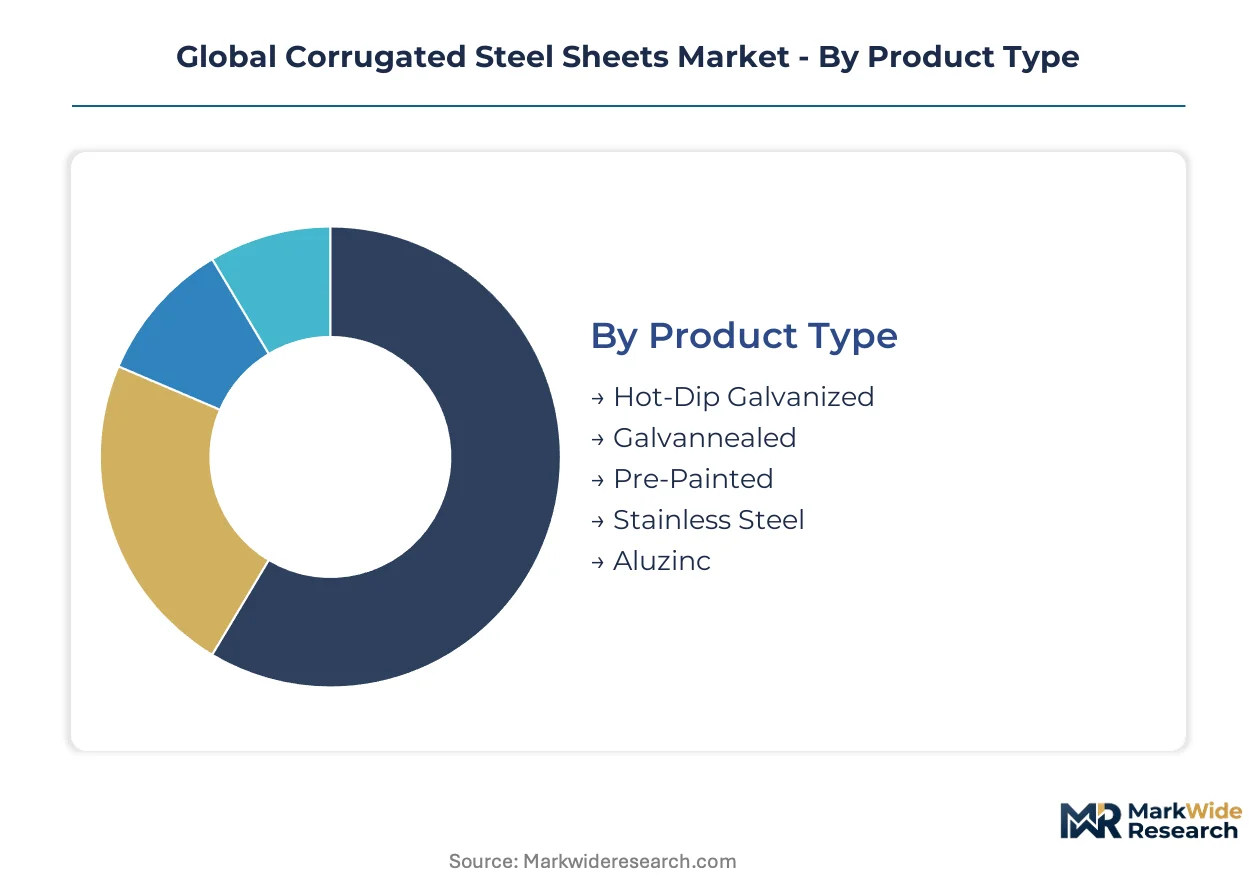
The corrugated steel sheets market is diverse, reflecting varied material specifications, application demands, and end-user requirements across global construction and industrial sectors. Understanding these distinct segments allows manufacturers to tailor product offerings and target specific niches for optimized market penetration. Each segment presents unique performance criteria and commercial considerations for market participants.
Product Type:
The technical specifications of corrugated steel sheets define their suitability for various environmental conditions and structural demands.
- Hot-Dip Galvanized:This product type features a protective zinc coating applied through a hot-dipping process, offering proven corrosion resistance and cost-effectiveness. Demand remains strong in general construction and agricultural applications across developing economies like India and Vietnam.
- Aluzinc:Aluzinc coatings combine aluminum and zinc to provide superior long-term corrosion resistance and enhanced aesthetic appeal compared to traditional galvanization. This premium product is increasingly specified for industrial buildings in coastal regions and architectural projects in Europe.
- Galvannealed:Galvannealed sheets undergo a heat treatment after galvanization, creating a matte finish that readily accepts paint and offers good weldability. This product finds application in automotive components and specific industrial enclosures.
- Pre-Painted:These sheets are coated with paint systems prior to corrugation, offering a wide range of colors and improved aesthetic and protective properties. Pre-painted products are popular for roofing and wall cladding in commercial and residential construction.
- Stainless Steel:Stainless steel corrugated sheets provide exceptional corrosion resistance and durability, particularly in harsh or hygienic environments. Specialized industrial facilities and high-end architectural projects utilize these high-performance materials.
Hot-Dip Galvanized leads on scale; Aluzinc leads on momentum.
Application:
The primary use cases for corrugated steel sheets dictate specific product characteristics and performance requirements.
- Roofing:Corrugated steel sheets provide a durable, lightweight, and weather-resistant covering for a vast array of structures, from industrial warehouses to residential buildings. This segment represents the largest volume consumption globally, driven by infrastructure projects and commercial construction.
- Wall Cladding:Used for exterior walls, corrugated steel cladding offers aesthetic versatility, structural protection, and thermal insulation properties for commercial and industrial buildings. Modern architectural designs in North America and Europe increasingly favor this application for its efficiency and appearance.
- Packaging:Corrugated steel sheets, often in lighter gauges, are employed in robust packaging solutions for heavy machinery and sensitive industrial goods. This application demands high structural integrity and protection during transit.
- Fencing:Durable and secure, corrugated steel is utilized for perimeter fencing in industrial sites, agricultural properties, and temporary construction zones. Fencing applications prioritize material strength and resistance to environmental wear.
- Flooring:In certain industrial and mezzanine applications, corrugated steel sheets serve as robust and slip-resistant flooring solutions. This segment values load-bearing capacity and long-term durability.
Roofing currently holds the largest market share, while wall cladding exhibits the steepest expansion trajectory.
End User:
Different customer types drive demand based on their specific project needs, scale, and material specifications.
- Warehousing Facilities:The rapid expansion of e-commerce infrastructure globally fuels significant demand for corrugated steel sheets for roofing and wall cladding of large-span logistics hubs. These facilities prioritize cost-effectiveness, durability, and rapid construction.
- Construction Firms:General construction firms represent a broad end-user segment, utilizing corrugated steel for diverse projects including commercial buildings, residential complexes, and public infrastructure. Their procurement patterns are influenced by project scale and local building codes.
- Agricultural Enterprises:Corrugated steel is extensively used for barns, silos, animal shelters, and other farm buildings due to its durability, weather resistance, and ease of maintenance. Demand from this sector is consistent across rural economies.
- Manufacturing Units:Industrial manufacturing units employ corrugated steel for factory roofing, wall panels, and internal partitions, valuing its structural integrity and fire resistance. These users often require specialized coatings for harsh operational environments.
- Commercial Complexes:Shopping centers, office parks, and other commercial developments use corrugated steel for both functional and aesthetic purposes in roofing and facade systems. Design flexibility and long-term performance are critical in this segment.
Warehousing Facilities exhibit the highest growth in consumption, whereas Construction Firms represent the largest base of demand.
Coating Technology:
The protective layer applied to steel sheets significantly influences their performance, longevity, and environmental compliance.
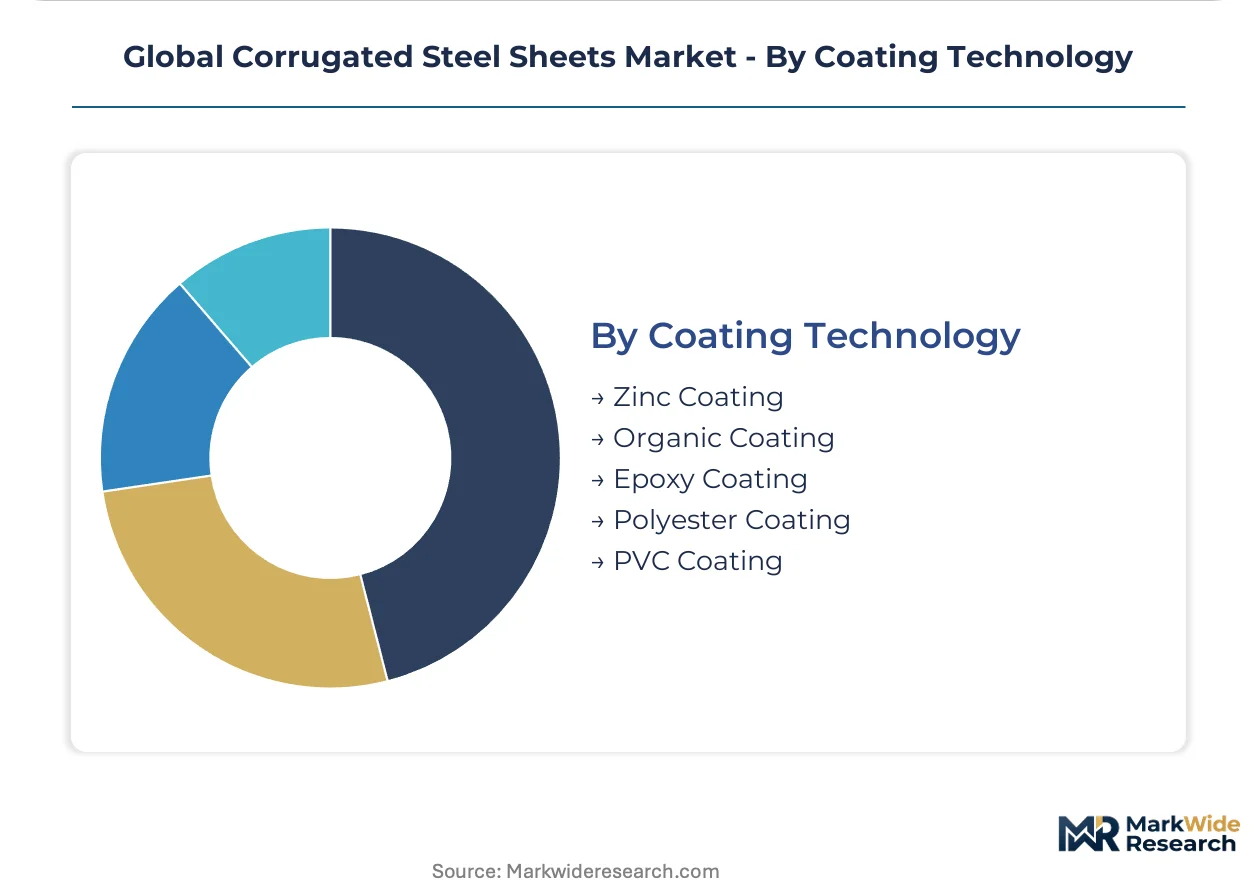
- Zinc Coating:This traditional method involves applying a layer of zinc to steel, primarily through hot-dip galvanization, offering fundamental corrosion protection. Zinc-coated sheets are widely used in cost-sensitive applications across various construction segments.
- Organic Coating:Organic coatings, typically paint systems, are applied over metallic coatings to enhance aesthetic appeal, provide additional corrosion resistance, and improve weatherability. These coatings are crucial for pre-painted corrugated sheets specified for architectural projects.
- Polyester Coating:Polyester-based coatings offer good color retention, flexibility, and resistance to weathering, making them a popular choice for roofing and wall cladding in moderate environments. These coatings balance performance with cost-effectiveness.
- Epoxy Coating:Epoxy coatings provide excellent adhesion, hardness, and chemical resistance, suitable for industrial environments where exposure to aggressive substances is expected. Specialized manufacturing units often specify epoxy-coated corrugated sheets.
- PVC Coating:Polyvinyl chloride (PVC) coatings offer superior corrosion resistance and durability, especially in harsh or marine environments. PVC-coated sheets are often selected for agricultural buildings and coastal structures requiring extended service life.
Zinc Coating commands the largest volume of production, while Organic Coating technologies are expanding most quickly due to performance demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's infrastructure development drives significant demand for corrugated steel sheets, contrasting with China's role as a major production hub for global exports. This market demonstrates varied regional dynamics, influenced by local construction trends, regulatory environments, and economic growth. Developing economies continue to prioritize cost-effective and durable building materials for rapid urbanization and industrialization. Established markets focus on advanced coatings and sustainable building practices.
China
China's production consolidation broadens the range of pre-painted and galvanized products available for global export. The nation's GB standards influence manufacturing processes and product quality for both domestic use and international trade. Industrial clusters in the Yangtze River Delta continue to expand, driving demand for corrugated steel in factory construction and warehousing facilities.
India
India's government-led infrastructure projects create sustained demand for corrugated steel in public works and industrial zones. The PLI scheme for steel manufacturing supports domestic production capabilities, aligning with national development goals. Gujarat's rapidly expanding industrial zones require vast quantities of corrugated steel for new manufacturing units and logistics hubs.
United States
Warehousing expansion, driven by e-commerce, fuels significant demand for corrugated steel in large-span industrial buildings across the United States. The EPA's rules on volatile organic compounds in paints influence coating formulations for pre-painted sheets. Logistics hubs in Texas exhibit robust construction activity, utilizing corrugated steel for roofing and wall cladding in new distribution centers.
Germany
Germany's modern commercial and industrial building designs increasingly specify corrugated steel for wall cladding and architectural projects. The European Union's REACH regulation impacts the chemical composition of coatings, requiring compliant materials. The Ruhr Valley's ongoing industrial revitalization projects incorporate corrugated steel for durable and aesthetically pleasing building envelopes.
Vietnam
Vietnam's infrastructure investment and industrial zone development generate consistent demand for corrugated steel in construction materials. National building codes dictate structural integrity and performance requirements for all construction projects. Ho Chi Minh City's expanding logistics facilities and industrial parks are major consumers of corrugated steel for roofing and siding.
Global Corrugated Steel Sheets Market Key Industry Players
Chinese producers anchor one tier, emphasizing high-volume, cost-effective manufacturing for global export; European and Indian specialists hold another, focusing on value-added products and regional market penetration. The market exhibits a tiered structure, with large, globally integrated steelmakers and more specialized regional manufacturers. Strategic archetypes include global conglomerates, regional powerhouses with strong backward integration, and niche innovators focusing on advanced coating technologies. Companies pursue capacity expansion and portfolio diversification to enhance their market positions.
At the scale-driven end, ArcelorMittal, a global entity, leverages its extensive manufacturing footprint across multiple continents. JSW Steel Ltd, an India-based firm, exemplifies strong backward integration into raw material sourcing. Tata Steel Limited, also from India, represents a focus on developing high-strength, value-added steel grades for specialized industrial applications. These entities shape the market through their distinct operational models and strategic priorities.
| Leading Market Players |
|---|
| BlueScope Steel Limited |
| JSW Steel Ltd |
| ArcelorMittal |
| Nippon Steel Corporation |
| Tata Steel Limited |
| Bansal Roofing Products |
| McElroy Metal, Inc. |
| Shandong Hengze New Material Co.,Ltd |
| Zhongjie Group |
| Others |
Cost & Logistics Intelligence
Warehousing facilities' prioritization of rapid construction and cost-effectiveness compels manufacturers to optimize production efficiency. This demand-side pressure influences pricing across the supply chain, particularly for high-volume orders.
Pricing Analysis
Distributor margins significantly influence final corrugated steel sheet prices for smaller construction projects. The market primarily operates on a contract-based long-term offtake model for large industrial buyers, with some commodity spot pricing for raw steel. Price differentiation stems from Aluzinc coating technology and geographic delivery costs. Pricing softness reflects intense competition from Chinese producers, especially for standard galvanized products, making agricultural enterprises highly price sensitive, while specialized industrial facilities prioritize performance.
Supply Chain Analysis
Direct sales to large construction firms and warehousing facilities dominate the corrugated steel sheets distribution model. Geographic supply concentration centers heavily on China, India, and Vietnam. The industry relies on steel coil, zinc, and aluminum as critical raw materials. Commodity price volatility for these inputs presents a significant supply chain risk, while manufacturers navigate complex export logistics from concentrated production hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated steel sheets market functions as a geographic-arbitrage play, leveraging lower production costs in Asian hubs against demand in higher-wage economies. This cost differential creates opportunities for optimized supply chain strategies.
For Market Incumbents: Acquire advanced coating technology patents to counter substitution threats from alternative materials. Consolidate regional distribution networks in India to optimize logistics and strengthen market presence. Investment in green building certifications offers a lever against evolving regulatory shifts. ArcelorMittal can leverage its extensive manufacturing footprint.
For New Entrants and Emerging Players: Aluzinc coating innovations offer a technology-first wedge into higher-value architectural applications in Europe. Target underpenetrated markets in Sub-Saharan Africa for low-cost, durable building solutions. Focus on prefabricated construction methods for standardized panels. A direct-to-builder sales model emphasizing rapid delivery provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized manufacturers developing sustainable product lines in the corrugated steel market. This market demonstrates long-term viability over 5-10 years, driven by infrastructure and warehousing expansion. Acquisition targets should be mid-sized firms with strong R&D in bio-based coatings. Increased mandated green building certifications is the signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Supports regional infrastructure development and e-commerce warehousing growth in Southeast Asia. |
| Advanced Aluzinc Coating R&D | Enhances product longevity and corrosion resistance for industrial buildings in coastal regions. |
| Green Building Certification Pursuit | Captures demand from commercial projects seeking LEED or BREEAM environmental credentials. |
| Backward Integration into Zinc Sourcing | Mitigates raw material price volatility for hot-dip galvanized sheet producers like JSW Steel Ltd. |
| Modular Construction System Development | Accelerates construction timelines for large-span industrial buildings and reduces on-site waste. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This involved interviews with plant managers, procurement leads at construction firms, and technical R&D directors. Secondary validation utilized customs/trade data, national building code documents, and corporate financial filings. Bottom-up and top-down triangulation ensured data consistency and market sizing accuracy.
Rate-of-change decomposition formed the basis for projecting market expansion across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and coating technology. Compound Annual Growth Rates were derived from historical trends and anticipated shifts in demand drivers. Infrastructure investment levels and e-commerce growth served as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and evolving environmental regulations. Forecasts reflect underlying assumptions regarding global economic stability and construction activity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Long Steel Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Engineered Wood Product Market
Building Materials
Construction Glass Market
Building Materials
Composite Decking and Railing Market
Building Materials
Cribbing Blocks Market
Building Materials
Global Facade Market
Building Materials
Masonry Cement Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Qatar Facade Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
Low-E Construction Glass Market
Building Materials
Global Metal Cladding Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
China Cement Market