
 India Concealed Cistern Market | 2026-2036
India Concealed Cistern Market Size, Share, and Industry Trends Forecast 2026-2036
India Concealed Cistern Market Insights
Premium residential developers is reorganizing procurement priorities across India's concealed cistern landscape, shifting volume toward water-efficient fixtures in gated communities and high-rise towers. Cera leverages its Gujarat manufacturing base to dominate western India distribution, while Jaquar sustains R&D intensity across thermoset polymer flush plates. Hindware anchors its position through backward integration into ceramic casting, and Kohler competes on design-led specifications for luxury hospitality projects in Bengaluru and Hyderabad.
A concealed cistern is a water storage vessel engineered for in-wall or in-furniture installation, typically fabricated from high-density polyethylene or vitreous ceramic with dual-flush valve mechanisms rated between three and six liters per discharge, serving the primary purpose of enabling minimalist bathroom architecture while reducing water consumption. Dual flush configurations command the widest installation base across Indian metros, though smart cisterns with sensor-actuated release represent the fastest-growing segment as commercial buildings pursue automation. Ceramic material grades retain margin concentration in premium residential specification, while plastic variants penetrate mass-market renovation channels through cost-accessible retrofitting kits.
BIS watermark certification and the CEA's building efficiency guidelines shape product compliance thresholds, with state-level municipal corporations in Maharashtra and Tamil Nadu enforcing mandatory dual-flush standards for new construction permits. The PLI scheme for ceramic sanitaryware incentivizes domestic capacity expansion, though import dependency on European flush valve assemblies creates supply vulnerability. Stakeholders must monitor evolving state urban development authority mandates on concealed plumbing specifications and assess captive molding capabilities before committing to capacity scaling.
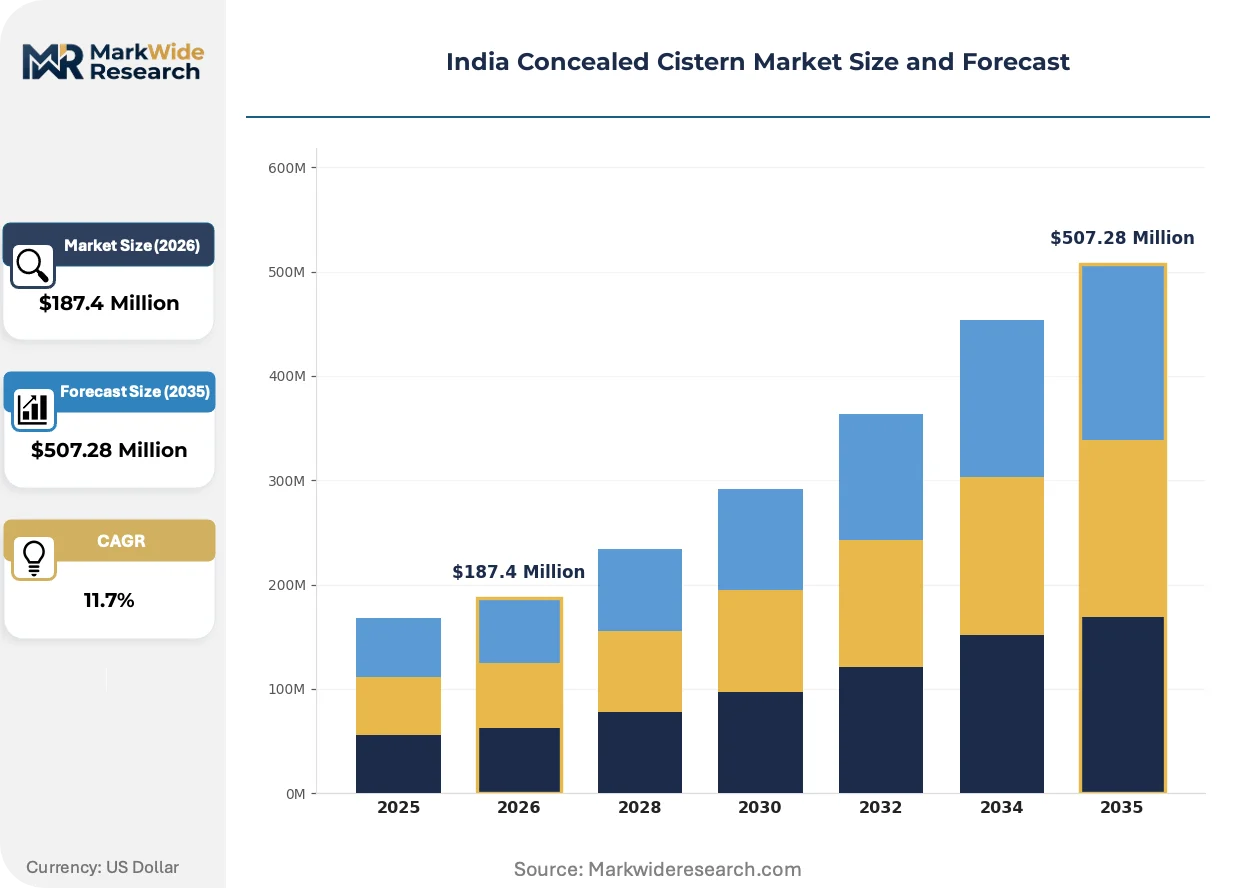
Market Dynamics
Municipal water conservation mandates under BIS standards are compressing installation timelines for concealed cisterns across Indian metros, forcing developers to pre-qualify dual-flush systems before construction permits issue.
Growth Catalysts
- Maharashtra dual-flush mandates:Municipal corporations in Mumbai and Pune now require three-six liter discharge ratings for all new residential permits, pulling volume toward certified suppliers.
- Smart city infrastructure:Public restroom contracts in Bengaluru and Hyderabad specify sensor-actuated concealed systems, creating anchor demand for automation-ready manufacturers.
- PLI scheme for ceramic sanitaryware:Domestic production incentives under this framework reduce landed cost disadvantages against Southeast Asian imports.
Market Restraints
- European flush valve dependency:Import concentration for pneumatic valve assemblies from Germany and Italy creates forex exposure and lead time volatility.
- HDPE resin cost structure:Polyethylene cistern bodies face margin pressure from petrochemical feedstock fluctuations tied to crude benchmarks.
- Skilled installer scarcity:Concealed plumbing requires certified wall-frame technicians, a credential pool concentrated in Gujarat and Tamil Nadu.
Strategic Opportunities
- Tier-2 city underpenetration:Jaipur, Lucknow, and Kochi residential stock lacks concealed cistern penetration, offering first-mover positioning for regional distributors.
- Retrofit channel emergence:E-commerce platforms now stock thin-profile retrofit kits, opening renovation demand outside new construction cycles.
- CEA building efficiency guidelines:Updated standards for commercial water fixtures create compliance-driven replacement pull in hospitality and office segments.
Industry Challenges
- BIS watermark certification timelines:Testing protocols for ceramic-bodied units extend product launch cycles by four to six months.
- Legacy masonry compatibility:Older high-rise stock in Delhi NCR requires structural assessment before in-wall cistern installation, complicating sales conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Concealed Cistern Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Flush, Single Flush, Smart Cisterns, Wall-Mounted Material: Ceramic, Plastic, Stainless Steel, Composite Installation Type: New Construction, Renovation, Retrofitting, Modular Design Style: Modern, Traditional, Minimalist, Custom |
| Companies Covered | Cera, Jaquar, Hindware, Kohler, Parryware Limited, Toto India Industries Pvt. Ltd., Duravit India, Roca, H&R Johnson (India) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Concealed Cistern Market Trends and Innovations
Concealed cistern architecture is pivoting toward automation-ready platforms as developers trade mechanical reliability for sensor integration and water analytics. Three distinct vectors now reshape competitive positioning.
Sensor-actuated flush mechanisms with embedded flow meters are displacing manual dual-lever systems in premium commercial specifications. Five-star hotel chains in Hyderabad and Chennai now specify IoT-enabled cisterns that transmit consumption data to facility management dashboards. This displacement compresses margins for purely mechanical valve suppliers while opening software-service revenue streams for integrated system vendors.
BIS watermark certification protocols have tightened discharge tolerance testing, requiring manufacturers to submit units for repeated cycle validation. Ceramic-bodied cisterns face stricter thermal shock assessments than polyethylene alternatives. Western India manufacturers with captive testing laboratories now compress compliance timelines versus competitors dependent on third-party labs.
Architect specification behavior has rotated toward water-efficiency scoring as a project marketing asset. Gated community developers in Mumbai now lead with BIS-compliant fixture lists in pre-sales collateral, displacing aesthetic-only selection criteria. This preference compression is most visible in luxury residential towers where sustainability credentials command price premiums over pure design differentiation.
India Concealed Cistern Market Segmentation
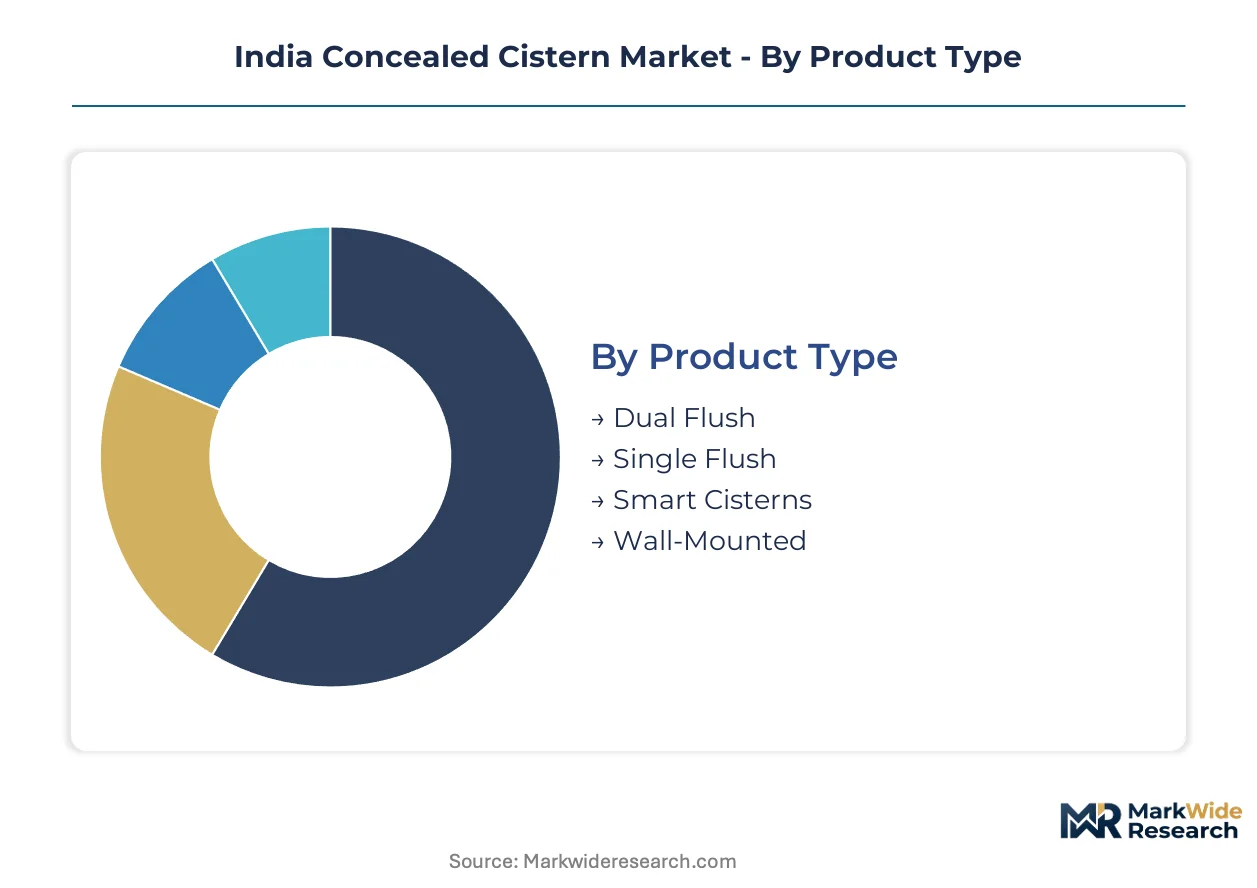
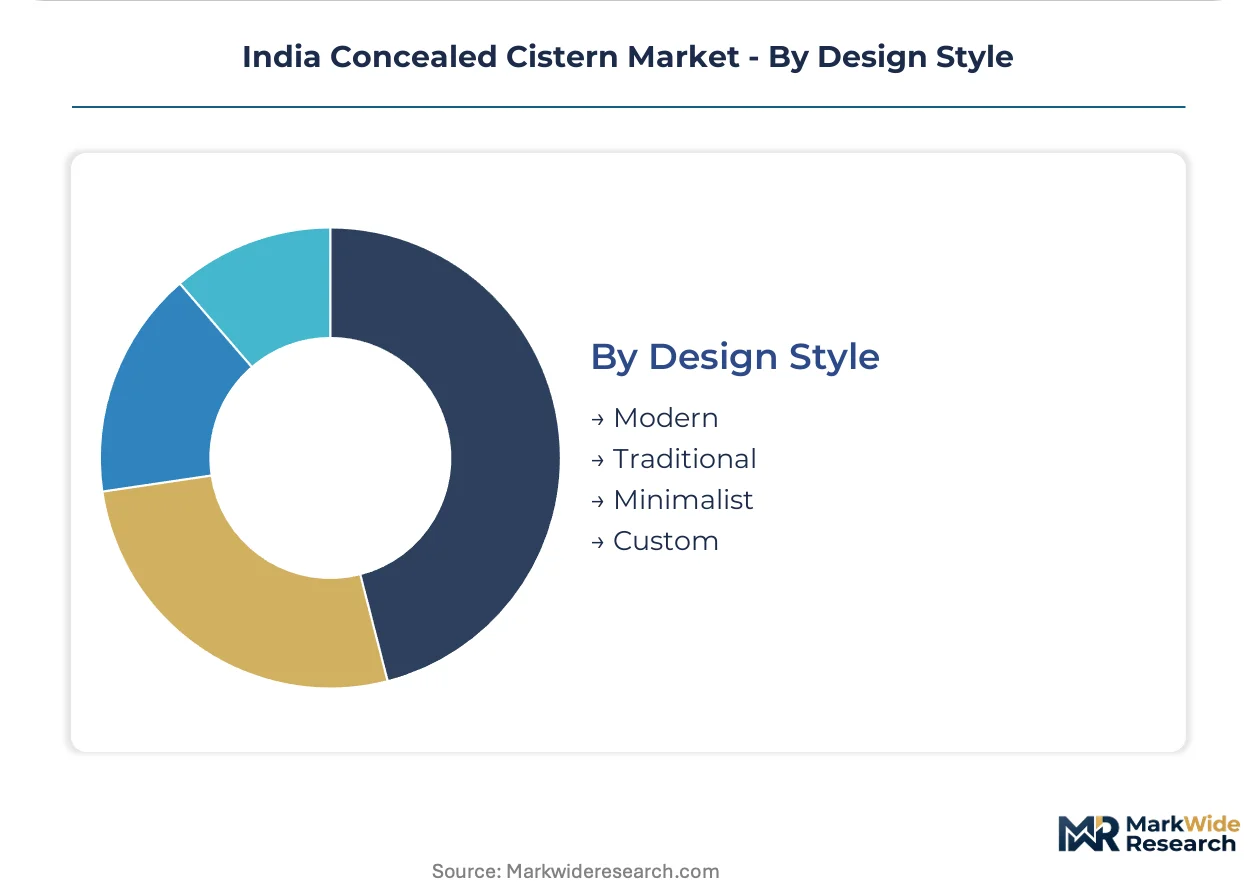
Segmentation reveals how concealed cistern demand fragments across technical specifications, material grades, and installation contexts in India. Manufacturers align capacity and distribution to capture specific pockets where regulatory mandates or architectural preferences concentrate procurement.
Product Type:
Dual flush systems dominate domestic volume through Maharashtra and Delhi NCR municipal mandates, while smart cisterns draw export inquiries from Gulf hospitality developers seeking automation integration.
- Dual Flush:Mechanical valve assemblies rated at three-six liters per discharge constitute the bulk of certified installations. Mumbai and Pune municipal corporations require these ratings for residential permits, pulling procurement toward BIS-watermarked suppliers with captive testing laboratories.
- Smart Cisterns:Sensor-actuated release mechanisms with embedded flow meters transmit consumption data to facility dashboards. Five-star hotel chains in Hyderabad and Chennai specify these for automation-ready infrastructure, creating premium positioning for integrated system vendors.
- Single Flush:Legacy six-liter constant discharge units persist in cost-sensitive public restroom contracts where sensor reliability remains a concern.
- Wall-Mounted:Thin-profile frames designed for structural integration in high-rise towers where floor loading constraints limit tank volumes.
Dual Flush commands the established base. The steepest expansion runs through Smart Cisterns.
Material:
Cost tier stratification separates ceramic-bodied premium specifications from polyethylene mass-market penetration, with stainless steel occupying niche commercial durability requirements.
- Ceramic:Vitreous-fired bodies withstand thermal shock testing under tightened BIS watermark protocols. Luxury residential towers in Bengaluru specify these for sustainability credentialing in pre-sales collateral, commanding price premiums over plastic alternatives.
- Plastic:High-density polyethylene cisterns penetrate renovation channels through cost-accessible retrofitting kits. E-commerce platforms stock thin-profile variants for Tier-2 city consumers outside new construction cycles.
- Stainless Steel:Corrosion-resistant fabrication serves coastal hospitality installations in Kochi and Chennai where saline exposure degrades polymer bodies.
- Composite:Glass-reinforced polymer blends attempt mid-tier positioning but face certification delays against established ceramic and HDPE testing benchmarks.
Ceramic retains margin concentration in premium specification. Plastic variants are gaining share fastest through retrofit channel expansion.
Installation Type:
Volume concentration follows new construction permits, though renovation activity accelerates as aging high-rise stock in Delhi NCR requires fixture replacement.
- New Construction:Gated community developers in Mumbai pre-qualify concealed systems before construction permits issue, embedding cisterns within wall frames during structural phase.
- Renovation:Legacy masonry assessment requirements complicate sales conversion in older Delhi NCR towers, limiting penetration to buildings with adequate structural clearance.
- Retrofitting:Thin-profile kits enable installation within existing wall cavities without structural modification, opening demand outside permit-driven new build cycles.
- Modular:Pre-assembled frame-and-cistern units reduce on-site skilled labor requirements, addressing installer scarcity concentrated in Gujarat and Tamil Nadu.
New Construction commands the established base. The steepest expansion runs through Retrofitting.
Design Style:
Customer type differentiation separates architect-specified aesthetic projects from developer-standardized efficiency mandates, with custom fabrication serving boutique hospitality.
- Modern:Flush plates with geometric actuation surfaces dominate premium residential specification where minimalist bathroom architecture drives procurement.
- Minimalist:Concealed actuation panels with no visible hardware serve luxury hospitality projects in Hyderabad where design differentiation commands specification.
- Traditional:Lever-actuated flush plates with ornamental surfacing persist in heritage hotel renovations seeking period-appropriate fixtures.
- Custom:Bespoke ceramic casting and plate finishing for individual architect specifications, volume-limited but margin-accretive for manufacturers with captive molding capabilities.
Modern commands the established base. Minimalist specification is expanding most quickly through design-led hospitality procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor and Eastern Dedicated Freight Corridor rail networks underwrite industrial distribution across India's concealed cistern supply chain, connecting Gujarat manufacturing clusters to consumption centers in Maharashtra and Delhi NCR.
Maharashtra
Mumbai and Pune municipal corporations enforce mandatory three-six liter discharge ratings for all new residential construction permits. The state's urban development authority aligns with BIS watermark certification protocols, compressing supplier qualification timelines. Thane and Navi Mumbai tower developments embed concealed systems during structural wall framing, pulling procurement toward pre-certified vendors.
Delhi NCR
Legacy high-rise stock in Gurgaon and Noida drives renovation demand as aging masonry requires structural assessment before in-wall installation. The Delhi Jal Board enforces water efficiency mandates for commercial building permits. Faridabad and Ghaziabad distribution hubs serve as secondary logistics nodes for northern India retrofit kit penetration.
Gujarat
Ahmedabad and Surat manufacturing bases leverage captive ceramic casting and HDPE molding capabilities to supply western India. The state's industrial corridor incentives under PLI scheme frameworks reduce production cost disadvantages. Vadodara testing laboratories compress BIS certification cycles versus competitors dependent on third-party facilities.
Karnataka
Bengaluru smart city infrastructure contracts specify sensor-actuated concealed systems for public restroom automation. The state's urban development department mandates water fixture efficiency scoring for commercial building approvals. Mysuru and Hubli residential developments represent emerging demand pockets outside the capital's permit concentration.
Tamil Nadu
Chennai coastal hospitality installations drive stainless steel cistern specifications where saline exposure degrades polymer bodies. State municipal corporations enforce dual-flush standards parallel to Maharashtra regulations. Coimbatore and Madurai fabrication clusters supply southern India distribution networks with ceramic-bodied units.
India Concealed Cistern Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and distribution reach, creating a tiered structure where scale advantages meet regional agility. The vendor base separates into three strategic archetypes: integrated manufacturers with captive molding, design-led specification houses, and import-dependent assemblers. Capacity expansion and backward integration into ceramic casting represent the dominant competitive moves as stakeholders defend margin positions against resin cost volatility.
Among India-based fabricators, Cera, Jaquar, and Hindware occupy distinct positioning within this structure. Cera anchors the integrated manufacturing archetype through its Gujarat production base. Jaquar exemplifies the design-led specification house model with sustained intensity across flush plate development. Hindware represents backward integration strategy through captive ceramic casting capabilities. Kohler India sits within the multinational premium tier, competing on design specifications for luxury hospitality projects without domestic manufacturing scale.
| Leading Market Players |
|---|
| Cera |
| Jaquar |
| Hindware |
| Kohler |
| Parryware Limited |
| Toto India Industries Pvt. Ltd. |
| Duravit India |
| Roca |
| H&R Johnson (India) Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Maharashtra developers and Gujarat-based manufacturers lock in ceramic cistern supply while fixing HDPE resin exposure through quarterly price adjustment clauses. This contract structure compresses margin volatility for integrated producers while exposing import-dependent assemblers to forex swings on European flush valve procurement.
Pricing Analysis
Volume-discount tiering structures separate premium ceramic-bodied units specified by Mumbai luxury developers from mass-market polyethylene variants stocked by e-commerce platforms. Pricing stratifies across BIS watermark certification grades, with captive laboratory access compressing compliance cost differentials. Cost compression in plastic cisterns is intensifying because petrochemical feedstock fluctuations tether margins to crude benchmarks. Renovation channel buyers exhibit highest price sensitivity, while five-star hotel chains prioritize automation integration over unit cost.
Supply Chain Analysis
Container availability constraints on the Nhava Sheva-Jebel Ali trade lane inflate inbound logistics costs for pneumatic valve assemblies sourced from Germany and Italy. Domestic production draws from Gujarat ceramic casting clusters, Tamil Nadu stainless steel fabrication, and Maharashtra HDPE molding capacity. Single-source vulnerability concentrates in European flush valve suppliers, with tariff exposure minimal under existing trade agreements. Distribution runs through regional distributor networks anchored by Faridabad and Ghaziabad logistics nodes serving northern India retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India concealed cistern market is cycling through a recovery phase as municipal water conservation mandates under BIS standards force replacement pull in aging Delhi NCR high-rise stock.
For Market Incumbents: Compound defensive positioning through backward integration into ceramic casting and captive BIS testing laboratory accreditation. European flush valve dependency threatens margin stability; securing alternative pneumatic assembly suppliers from East Asian fabrication clusters reduces forex exposure. Priority investment targets automation-ready sensor platforms specified by Bengaluru smart city contracts. For New Entrants and Emerging Players: BIS watermark fast-track partnerships with Vadodara testing facilities compress product launch cycles versus third-party laboratory competitors. White-space concentration sits in Jaipur, Lucknow, and Kochi Tier-2 residential markets lacking concealed cistern penetration. Go-to-market execution through thin-profile retrofit kit e-commerce distribution bypasses new construction permit dependencies. For Investors and Strategic Acquirers: Regional distributor networks with established municipal corporation relationships represent the most defensible acquisition archetype. Long-term viability hinges on PLI scheme continuity for ceramic sanitaryware capacity expansion. Monitor state urban development authority mandate evolution as the primary inflection signal for compliance-driven replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Casting Capacity Expansion | Captive vitreous firing capability defends margin positions against HDPE resin volatility under PLI incentives. |
| BIS Watermark Fast-Track Certification | In-house testing laboratory accreditation compresses product launch timelines versus third-party dependent competitors. |
| Sensor-Actuated Platform Development | IoT-enabled flush mechanisms capture Bengaluru and Hyderabad smart city infrastructure contract specifications. |
| Tier-2 City Distribution Partnership | Regional distributor relationships in Jaipur and Lucknow secure first-mover positioning outside metro permit concentration. |
| European Valve Supplier Diversification | Alternative pneumatic assembly sourcing from East Asian clusters mitigates forex exposure and lead time volatility. |
Research Methodology
Initial hypotheses were tested against primary input from sanitaryware plant managers, municipal corporation plumbing inspectors, luxury hotel procurement directors, and ceramic casting R&D leads and refined through secondary validation against BIS certification records, PLI scheme disbursement filings, state urban development authority mandate documents, and customs import data for pneumatic valve assemblies. Bottom-up volume estimates from construction permit filings were triangulated with top-down market sizing from sanitaryware production capacity assessments.
Variance decomposition across product type, material grade, installation context, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate aggregation weighted by base-year volume shares. Forecast inputs incorporated municipal mandate enforcement timelines, PLI scheme capacity addition schedules, and smart city infrastructure contract award pipelines.
Underlying assumptions cover sustained BIS watermark certification stringency and PLI scheme continuity, with deviation risk concentrated in European valve supply disruption and state-level mandate adoption delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Roof Cover Boards Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Sprayed Concrete Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Thin Brick Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Global FRP Rebar Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Fiber Cement Market
Building Materials
Basalt Rock Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Concrete and Cement Market