
 UK Residential Construction Market | 2026-2036
UK Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
UK Residential Construction Market Outlook
A capital-intensity divergence between volume housebuilders and boutique developers is bifurcating competitive dynamics across the UK. Barratt Redrow plc leverages its merged land bank and standardized product range to sustain margin control at scale. Vistry Group plc anchors its strategy in partnerships with housing associations, competing on tenure mix rather than pure sales velocity.
UK residential construction encompasses the design, assembly, and finishing of dwellings for private occupation, typically involving reinforced concrete foundations, cavity wall insulation to U-values of 0.18 W/m²K, and timber or light-gauge steel superstructures. Its primary purpose is creating habitable, mortgageable assets that satisfy Building Regulations and lender valuation criteria. Single-family homes occupy the largest share of output value, though modular construction is expanding fastest as factory-based panelization compresses build programs and reduces on-site waste. Multi-family units concentrate margin pools in urban regeneration zones where land values justify density premiums.
The Future Homes Standard, Building Regulations Part L, and the Environment Agency's flood risk guidance collectively shape product specifications, site viability, and planning consent timelines. Homes England grant funding ties subsidy release to zero-carbon-ready performance thresholds, redirecting developer R&D toward heat pumps and fabric-first efficiency. Stakeholders must monitor local plan housing land supply calculations, as undersupply designations trigger presumption-in-favor policies that accelerate permissioning but intensify competition for developable plots.
Market Dynamics
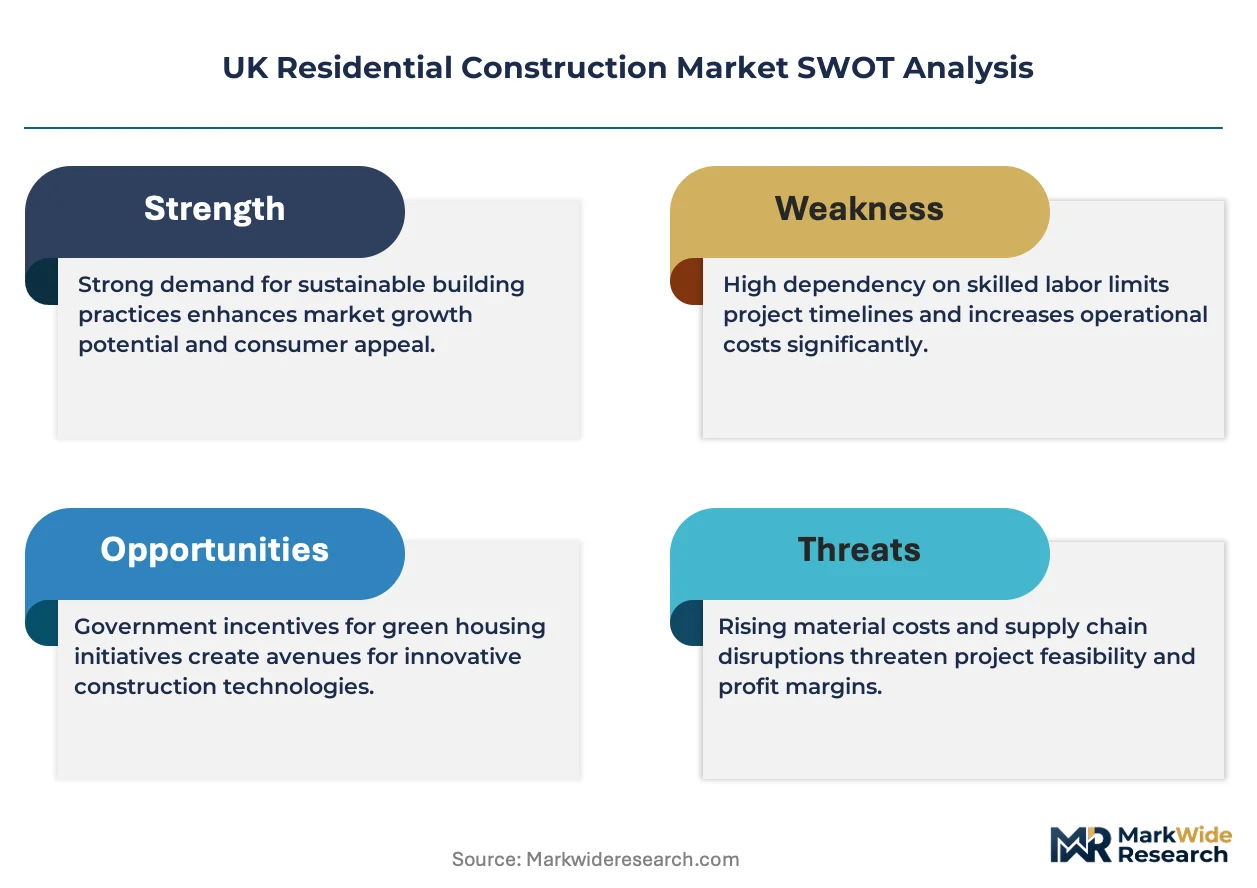
The Future Homes Standard is compressing build programs and recalibrating material specifications across UK residential construction, forcing developers to front-load thermal efficiency investments before 2025 compliance deadlines.
Growth Catalysts
- Help to Buy successor schemes:Government equity loan programs sustain first-time buyer purchasing power, particularly in Greater London and the South East where deposit requirements outpace wage growth.
- Heat pump technology maturation:Air-source and ground-source systems achieve cost parity with gas boilers at scale, enabling zero-carbon-ready compliance without prohibitive retrofit penalties.
- Shared ownership pathway expansion:Housing associations deepen partnership structures with developers, unlocking tenure mix flexibility that pure market-sale projects cannot replicate.
Market Restraints
- Land supply concentration:Developable plots cluster in fewer volume housebuilder land banks, inflating option premiums and squeezing boutique developer viability in constrained sub-markets.
- Timber frame input volatility:Cross-laminated timber and engineered wood product prices fluctuate with Nordic supply chain disruptions, compressing margin predictability for offsite construction specialists.
- Planning permission timelines:Local authority capacity constraints extend determination periods beyond 26 weeks, carrying costs that erode project IRRs before ground breaks.
Strategic Opportunities
- Urban brownfield densification:Former industrial sites in Manchester, Birmingham, and Bristol offer planning presumption advantages under housing land supply shortfall designations.
- Homes England grant leverage:Zero-carbon-ready performance thresholds unlock subsidy release mechanisms that de-risk speculative development in affordable housing segments.
- Modular-manufacturing convergence:Factory-based panelization integrates with light-gauge steel framing to compress build programs from 40 weeks to 16 weeks in multi-family schemes.
Industry Challenges
- Retrofit skill scarcity:Heat pump installation and fabric-first efficiency detailing outpace vocational training pipeline output, constraining compliance execution at volume.
- Building Control capacity bottlenecks:Approved Inspector resource constraints delay Part L sign-offs, cascading program slippage into sales completion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Residential Construction Market |
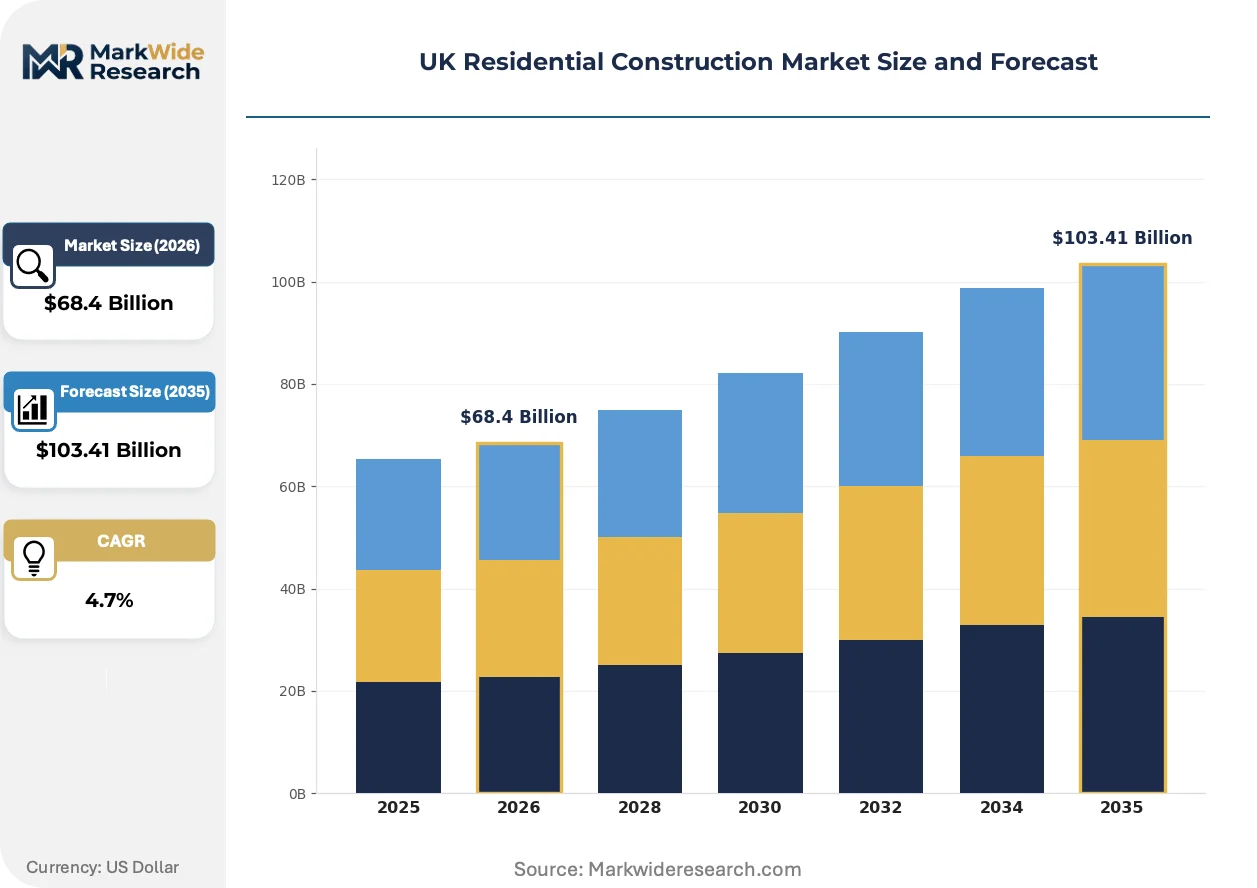
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Condominiums, Townhouses Construction Method: Traditional Brick, Wood Frame, Steel Frame, Modular Construction End User: First-Time Buyers, Investors, Homeowners, Renters Financing Type: Mortgages, Cash Purchases, Government Grants, Investment Loans |
| Companies Covered | Barratt Redrow plc, Vistry Group plc, Persimmon plc, Taylor Wimpey, Bellway, Berkeley Group Holdings, Crest Nicholson, Redrow, Gleeson Homes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Residential Construction Market Strategic Shifts
Digital design-to-manufacture workflows are collapsing traditional procurement boundaries, while regulatory carbon budgets and buyer tenure preferences force simultaneous adaptation across product specification and sales channel strategy.
Modular offsite construction is fragmenting the conventional site-based assembly model. Factory-based volumetric and panelized systems achieve 30% waste reduction against stick-build baselines. SME developers and housing associations adopt these methods fastest, compressing capital deployment cycles and reducing weather-dependent program risk.
The Future Homes Standard mandates 75-80% carbon emission reductions against 2013 Part L baselines from 2025. Fabric-first efficiency requirements push U-value targets to 0.18 W/m²K for walls, forcing insulation specification upgrades. Volume housebuilders with standardized product ranges adapt fastest; bespoke developers face per-project engineering cost inflation.
First-time buyer tenure preferences are tilting toward shared ownership and leasehold structures that lower deposit barriers. Traditional outright purchase channels lose share to housing association partnership routes and institutional build-to-rent platforms. Greater London and the South East exhibit this shift most acutely, where absolute price levels exclude mortgage-dependent buyers from open-market competition.
UK Residential Construction Market Segmentation
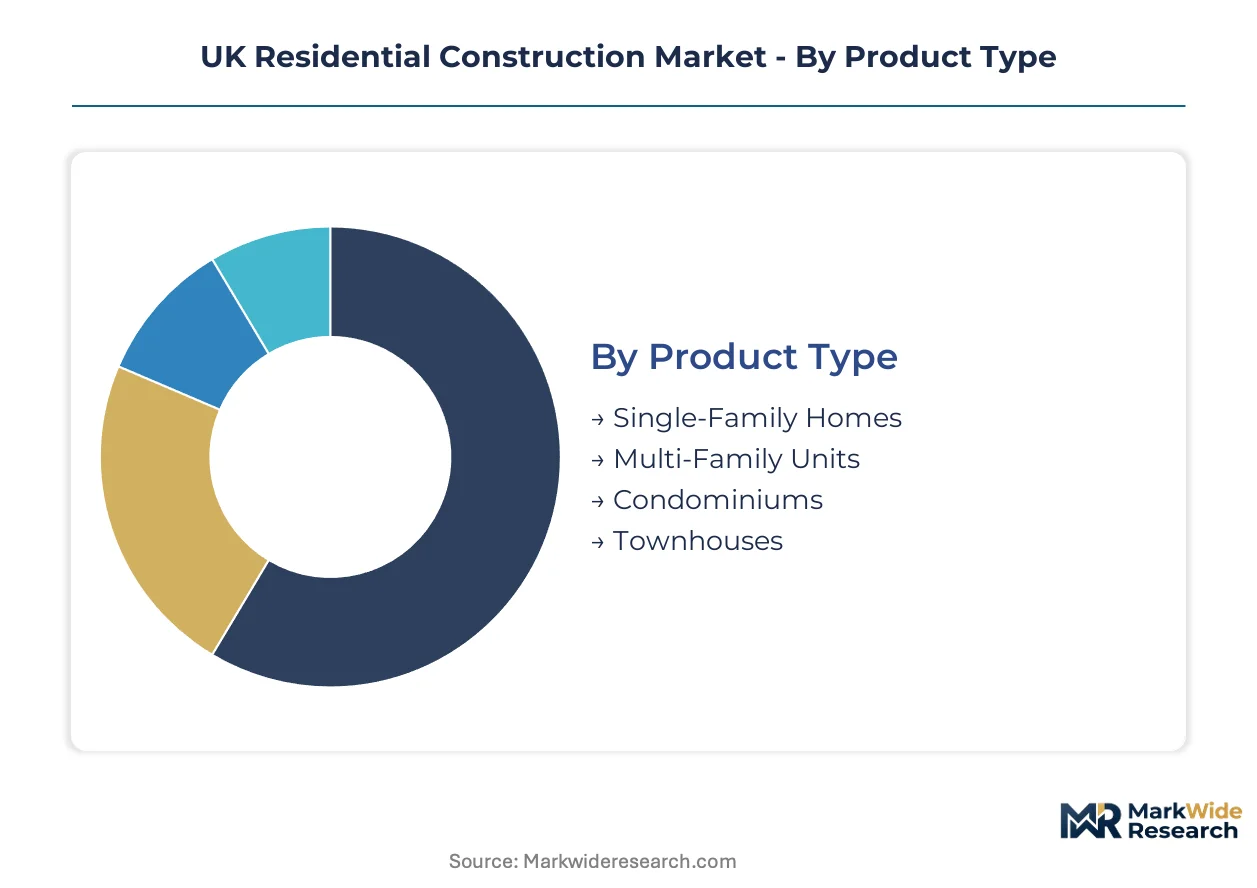
Segmentation in UK residential construction reveals how regulatory pressure and tenure preferences redistribute capital across product types and delivery methods. Developers calibrate land acquisition and construction technology choices against distinct margin profiles within each category.
Product Type:
Margin pools concentrate in multi-family schemes where land value density justifies vertical construction premiums in Greater London and the South East.
- Single-Family Homes:Detached and semi-detached dwellings dominate output value through standardized product ranges that volume housebuilders replicate across greenfield sites. Demand clusters in commuter belts outside Greater London where Help to Buy successor schemes sustain first-time buyer purchasing power against deposit barriers.
- Multi-Family Units:Purpose-built apartments and flats concentrate development activity in urban regeneration zones where brownfield land scarcity commands density premiums. Manchester, Birmingham, and Bristol exhibit steepest expansion trajectories as housing land supply shortfall designations accelerate planning presumption advantages.
- Condominiums:Strata-titled apartment ownership structures appeal to equity-rich downsizers and investor purchasers in prime central London sub-markets.
- Townhouses:Terraced and mews-style medium-density housing bridges the gap between apartment living and detached suburban stock in constrained urban sites.
The dominant share belongs to Single-Family Homes, while Multi-Family Units is closing the gap fastest.
Construction Method:
Cost tier differentiation separates premium bespoke developments from volume production, with factory-based systems compressing program risk for capital-constrained operators.
- Traditional Brick:Cavity wall construction with clay or concrete masonry remains the baseline specification for mainstream housebuilders serving mortgage lender valuation criteria. South East England maintains deepest penetration where planning authorities favor vernacular aesthetic compliance and thermal mass performance.
- Modular Construction:Factory-based volumetric and panelized systems achieve 30% waste reduction against stick-build baselines while compressing build programs from 40 weeks to 16 weeks. SME developers and housing associations adopt these methods most aggressively to reduce weather-dependent program risk and accelerate capital deployment cycles.
- Wood Frame:Timber superstructures dominate Scottish residential construction and rural English markets where supply chain proximity to Nordic sources moderates input volatility.
- Steel Frame:Light-gauge steel framing integrates with modular panelization for multi-family schemes requiring long structural spans and fire resistance ratings.
Traditional Brick retains the largest installed base, though Modular Construction is gaining share fastest among tenure-mix developers.
End User:
Customer type determines sales channel strategy, with institutional purchasers demanding different specification packages than individual owner-occupiers.
- First-Time Buyers:Deposit-constrained purchasers drive shared ownership pathway expansion and equity loan scheme uptake, particularly in Greater London where absolute price levels exclude open-market competition.
- Investors:Buy-to-let and build-to-rent institutional capital targets yield-stabilized assets in employment-dense urban cores with rental growth visibility.
- Homeowners:Equity-rich movers and downsizers commission bespoke developments or premium volume product in established commuter locations.
- Renters:Build-to-rent platforms and housing association leasehold structures absorb households excluded from mortgage access by stress-test criteria.
First-Time Buyers command the deepest policy attention, while Renters are expanding most quickly as tenure patterns shift.
Financing Type:
Funding source shapes project risk profiles, with government-backed mechanisms de-risking affordable housing segments that private capital avoids.
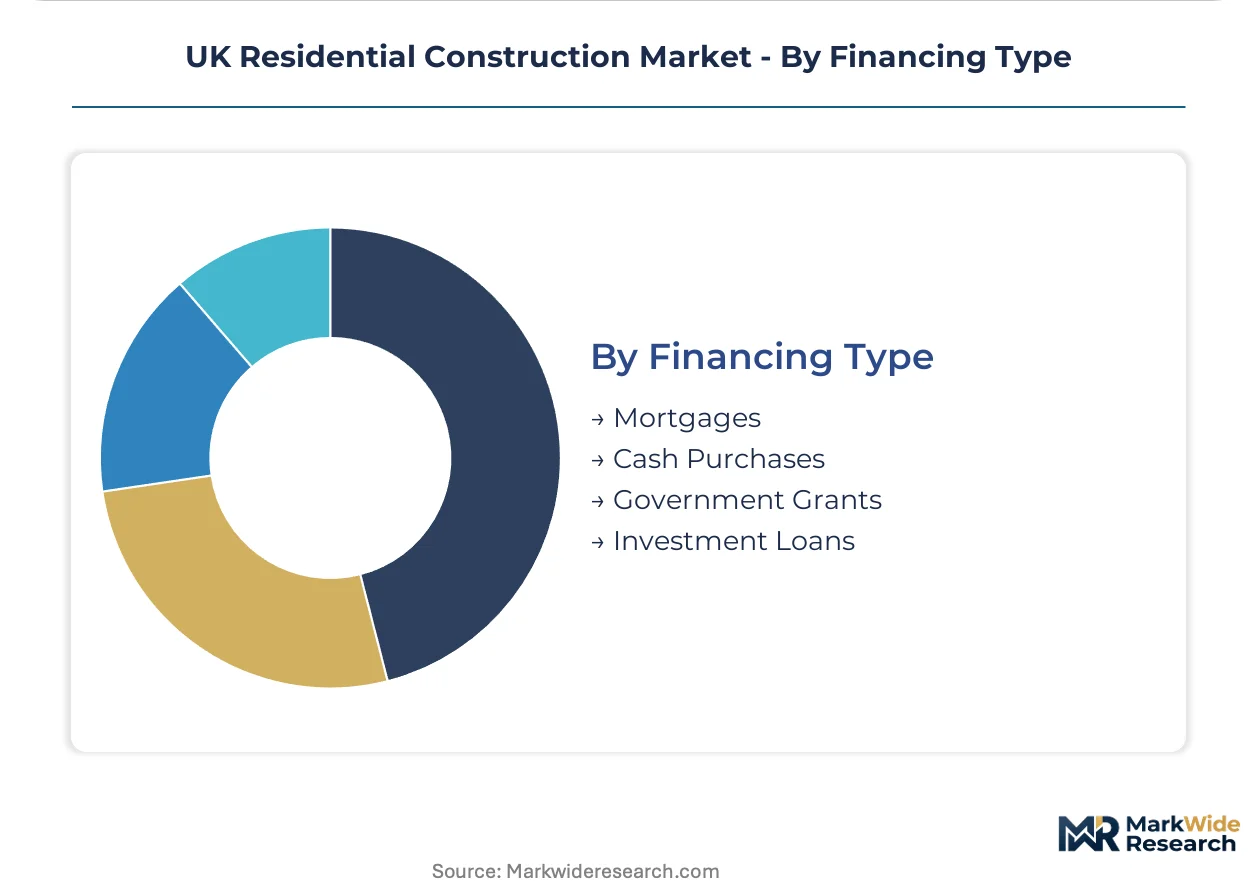
- Mortgages:High loan-to-value products from mainstream lenders dominate owner-occupier purchases, with criteria tightening around interest rate stress tests and cladding remediation disclosures.
- Government Grants:Homes England funding ties subsidy release to zero-carbon-ready performance thresholds, redirecting developer R&D toward heat pump compliance and fabric-first efficiency.
- Cash Purchases:Unleveraged equity from domestic downsizers and international capital flows concentrates in prime central London and trophy asset acquisitions.
- Investment Loans:Development finance from specialist lenders and institutional debt funds underwrites speculative construction with profit participation structures.
Mortgages fund the majority of transactions, though Government Grants are climbing fastest as Homes England deepens affordable housing commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction demand concentrates differently across England's sub-regions, with Greater London absorbing high-density multi-family schemes while the Midlands and North favor lower-rise single-family development on more abundant land.
London and the South East
Land scarcity sustains premium pricing for vertical construction, with brownfield densification dominating output. The Greater London Authority's housing targets accelerate planning presumption in Opportunity Areas. Build-to-rent institutional capital clusters in Nine Elms, Stratford, and Old Oak Common regeneration zones.
Midlands
First-time buyer purchasing power stretches further across Birmingham, Coventry, and Leicester commuter belts. West Midlands Combined Authority devolution deals unlock infrastructure funding tied to housing delivery. Modular construction specialists establish factory capacity near Derby and Nottingham to serve regional volume housebuilders.
North England
Manchester and Liverpool city regions exhibit steepest shared ownership pathway expansion as housing association partnerships deepen. Homes England grant funding de-risks affordable housing development on former industrial land in Salford and Trafford. Timber frame construction maintains share against brick in Yorkshire's rural markets.
Scotland
Timber superstructures dominate residential construction, leveraging Nordic supply chain proximity and Scottish Building Standards thermal efficiency requirements. Edinburgh and Glasgow greenbelt constraints push development toward brownfield infill. Heat pump deployment leads UK regions due to earlier gas boiler phase-out commitments.
Wales
South Wales valleys regeneration and Cardiff capital region expansion concentrate development activity. Welsh Government planning policy prioritizes affordable housing quotas on major sites. Coastal constraints and flood risk guidance from Natural Resources Wales shape site viability assessments in western counties.
UK Residential Construction Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with merged land banks and standardized product ranges enabling margin control at scale. Volume housebuilders compete on tenure mix flexibility and partnership structures with housing associations, while boutique developers occupy niche premium segments. Strategic moves center on land bank consolidation through merger activity and modular manufacturing partnerships that compress build programs.
Within the merged-scale tier, Barratt Redrow plc occupies a position exemplifying land bank consolidation advantages, while Vistry Group plc represents partnership-driven tenure diversification. Persimmon plc anchors the volume-production archetype with standardized greenfield execution. These three entities collectively illustrate how competitive positioning bifurcates between scale-driven standardization and tenure-mix specialization across the UK market.
| Leading Market Players |
|---|
| Barratt Redrow plc |
| Vistry Group plc |
| Persimmon plc |
| Taylor Wimpey |
| Bellway |
| Berkeley Group Holdings |
| Crest Nicholson |
| Redrow |
| Gleeson Homes |
| Others |
Value Chain & Pricing Dynamics
Heat pump technology displacement of gas boiler infrastructure simultaneously redraws procurement geography toward Nordic and East Asian manufacturing clusters and compresses installed-cost economics through scale learning curves. This substitution dynamic concentrates pricing power among volume housebuilders with standardized product ranges capable of absorbing front-loaded thermal efficiency investments, while boutique developers face per-project engineering cost inflation.
Pricing Analysis
After-sales service revenue from heat pump maintenance contracts and fabric-first efficiency warranties now drives lifetime value capture for developers pivoting toward zero-carbon-ready compliance. Three-tier pricing structure across premium, standard, and economy levels separates equity-rich downsizers from first-time buyers leveraging shared ownership pathways and institutional build-to-rent platforms. Pricing pressure stems from Building Regulations Part L compliance deadlines forcing material specification upgrades before cost parity achievement. First-time buyers exhibit highest price sensitivity, constrained by deposit barriers and mortgage stress-test criteria, while cash purchasers in prime central London sub-markets remain least sensitive.
Supply Chain Analysis
Inbound logistics costs through Felixstowe and Southampton port congestion, combined with Baltic Sea container availability constraints on the Gothenburg-Immingham trade lane, elevate landed costs for cross-laminated timber and engineered wood products. Supply concentrates in Sweden, Finland, and Germany for timber frame inputs, with China and South Korea dominating heat pump compressor manufacturing. Raw material dependencies span Nordic spruce and pine feedstocks, aluminum extrusions for window systems, and lithium-ion battery components for residential storage integration. Single-source vulnerability around approved inspector capacity for Part L sign-offs cascades program slippage risk. Distribution runs through regional builder merchant networks serving volume housebuilders, with direct-to-site factory delivery for modular panelization specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK residential construction market functions as a defensive-moat story anchored in regulatory entrenchment: the Future Homes Standard creates compliance barriers that favor incumbents with established Building Control relationships and standardized product platforms.
For Market Incumbents: Compound land bank consolidation advantages through strategic plot acquisitions in housing land supply shortfall designations, particularly across Manchester, Birmingham, and Bristol urban regeneration zones. Deepen vertical integration into modular manufacturing partnerships that compress build programs from 40 weeks to 16 weeks, neutralizing weather-dependent program risk that erodes boutique developer viability.
For New Entrants and Emerging Players: Future Homes Standard certification fast-track through Homes England grant leverage unlocks affordable housing segments where subsidy release mechanisms de-risk speculative development. White-space targets concentrate in urban brownfield densification schemes and heat pump installation service provision, where retrofit skill scarcity constrains volume housebuilder execution. Prioritize partnership structures with housing associations over pure market-sale competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular construction specialists and regional land assembly platforms across the Midlands and North England. Long-term viability over the projection horizon favors tenure-mix developers with institutional build-to-rent pipelines and zero-carbon-ready compliance capabilities. Monitor local plan housing land supply calculations as inflection indicator: undersupply designations trigger presumption-in-favor policies that accelerate permissioning but intensify plot competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Land Bank Consolidation | Merged land banks enable margin control at scale across standardized product ranges. |
| Modular Manufacturing Partnership | Factory-based panelization compresses build programs and reduces weather-dependent program risk. |
| Housing Association Partnership | Tenure mix flexibility unlocks subsidy release mechanisms that pure market-sale projects cannot replicate. |
| Zero-Carbon-Ready Certification | Future Homes Standard compliance creates regulatory entrenchment favoring incumbents with established Building Control relationships. |
| Urban Brownfield Densification | Former industrial sites in designated housing land supply shortfall areas accelerate planning presumption advantages. |
Study Parameters
The analysis maps single-family homes, multi-family units, modular construction methods, and first-time buyer segments, each validated through land acquisition directors, housing association development officers, Building Control approved inspectors, and modular manufacturing operations managers. Primary interviews with volume housebuilder strategy executives and boutique developer principals combined with secondary validation from Homes England grant disbursement records, local authority planning portal determinations, and Building Regulations Part L compliance databases. Bottom-up plot-level pipeline analysis and top-down regional output value triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled encompass product type, construction method, end-user category, and financing source, with regional sub-market granularity for Greater London, South East, Midlands, and North England. CAGRs derived from plot absorption rate trajectories, planning permission pipeline velocity, and tenure mix shift assumptions. Forecast inputs incorporated Future Homes Standard compliance cost curves and heat pump technology maturation timelines.
Underlying assumptions cover Help to Buy successor scheme continuity, Nordic timber supply chain stability, and approved inspector capacity expansion, with deviation risk concentrated in interest rate stress-test tightening and local authority planning resource constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Prefabricated Homes Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Japan Residential Construction Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Residential Construction Market
Residential Construction
US Residential Construction Market
Residential Construction
US Residential Remodeling Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Saudi Arabia Residential Construction Market