
 Global Pozzolan Market | 2026-2036
Global Pozzolan Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pozzolan Market Foresight
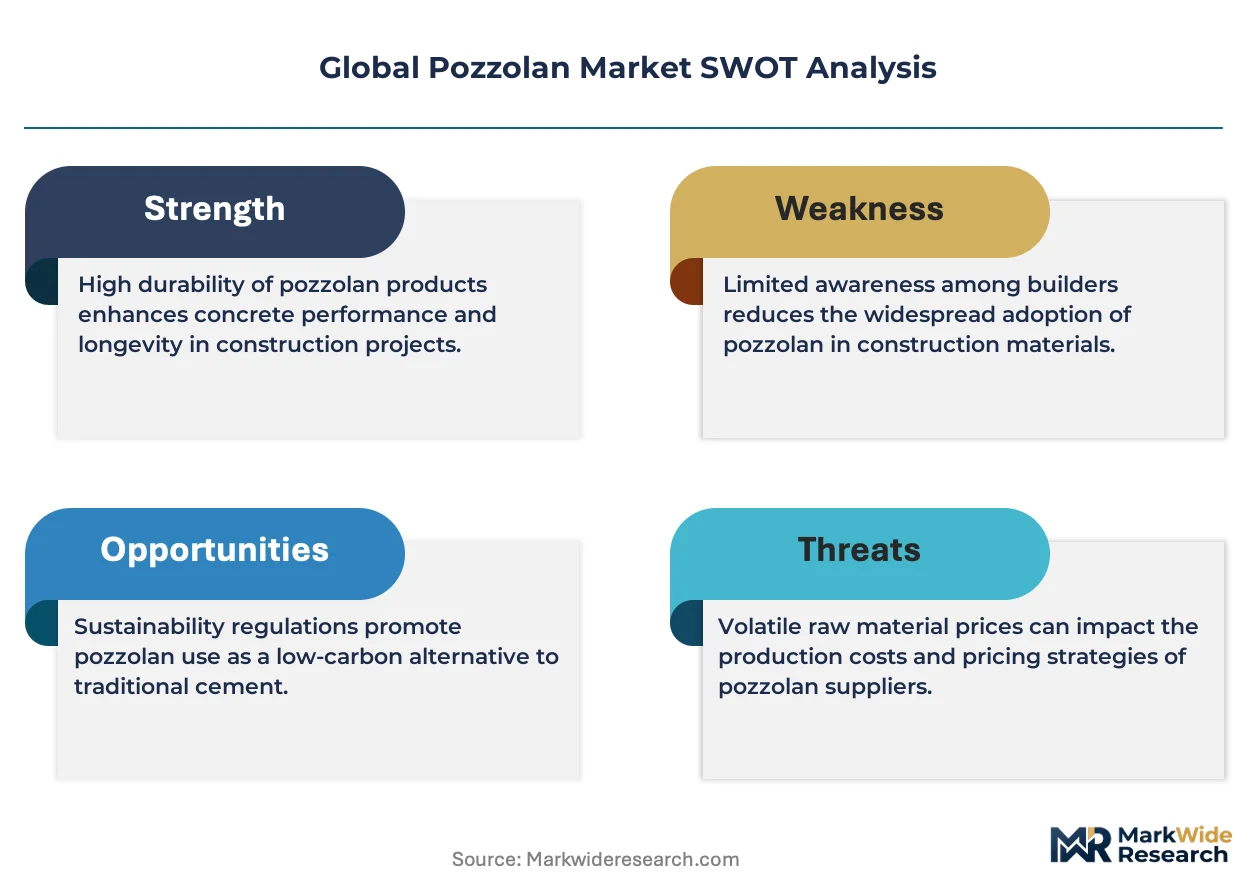
Performance-based supply contracts for consistent reactivity indices is recalibrating how pozzolan suppliers monetize material value beyond tonnage. CEMEX S.A.B. de C.V. leverages its captive fly ash sourcing from power sector partnerships to secure long-term reactivity guarantees. IMERYS anchors its position through calcined clay production networks spanning multiple geographies. Charah Solutions, Inc. specializes in beneficiation services that upgrade lower-grade ash into specification-grade pozzolan for ready-mix suppliers.
Pozzolan encompasses siliceous or siliceous-aluminous materials that react with calcium hydroxide in the presence of moisture to form cementitious compounds, with specific surface area typically ranging from 300 to 600 square meters per kilogram for silica fume variants. These materials primarily serve to reduce Portland cement content, improve sulfate resistance, and lower the embodied carbon of concrete and mortar systems. Fly ash dominates volume flows owing to its proximity to coal power generation infrastructure, though calcined clay is gaining specification momentum in markets seeking alternatives to declining fly ash availability. Metakaolin commands premium positioning in precast architectural applications where whiteness and refined particle distribution justify higher input costs against performance requirements.
The EPA regulates coal combustion residual disposal under subtitle D of the Resource Conservation and Recovery Act, directly influencing fly ash supply economics and material classification for beneficial use. REACH registration requirements in Europe govern the import and formulation of synthetic pozzolans, while India's BIS certification mandates IS 3812 compliance for fly ash utilization in concrete production. Stakeholders must monitor regulatory divergence between jurisdictions on waste-derived material classification, as this determines whether pozzolan qualifies for green procurement credits or faces disposal-cost headwinds.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing specification windows for Portland cement, forcing infrastructure developers to requalify binder formulations around verified pozzolanic substitution rates.
Growth Catalysts
- EU Green Deal thresholds:Construction material procurement in Germany, France, and the Netherlands now mandates lifecycle carbon accounting that rewards high-volume pozzolan substitution.
- Hydropower concrete specifications:Dam and reservoir projects across Vietnam, Indonesia, and the Philippines require sulfate-resistant binders with proven pozzolanic reactivity indices.
- Coastal resilience infrastructure:Sea wall and port expansion programs in the Philippines prioritize chloride-resistant concrete formulations using fly ash and calcined clay blends.
Market Restraints
- Fly ash supply concentration:Beneficiated material availability clusters around legacy coal power regions in the US, India, and China, creating geographic supply asymmetries.
- Calcined clay capital intensity:Rotary kiln retrofitting and quality control infrastructure demands sustained capex commitments that marginal producers cannot absorb.
- Natural pozzolan deposit depletion:High-reactivity volcanic ash reserves in Italy, Greece, and Turkey face extraction limits and environmental permitting delays.
Strategic Opportunities
- Underpenetrated African markets:Nigeria, Kenya, and Egypt lack domestic beneficiation capacity but possess substantial construction growth trajectories requiring imported specification-grade material.
- Metakaolin in architectural precast:Whiteness and refined particle distribution commands premium positioning in facade and cladding applications across Middle Eastern commercial developments.
- Performance-based supply contracting:Reactivity-guaranteed pricing models allow suppliers to capture value beyond tonnage through verified compressive strength contributions.
Industry Challenges
- Reactivity testing standardization:Divergent national protocols for pozzolanic activity index measurement create cross-border certification friction and specification mismatches.
- Beneficiation workforce scarcity:Specialized technicians capable of operating electrostatic separation and thermal activation equipment remain concentrated in mature markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pozzolan Market |
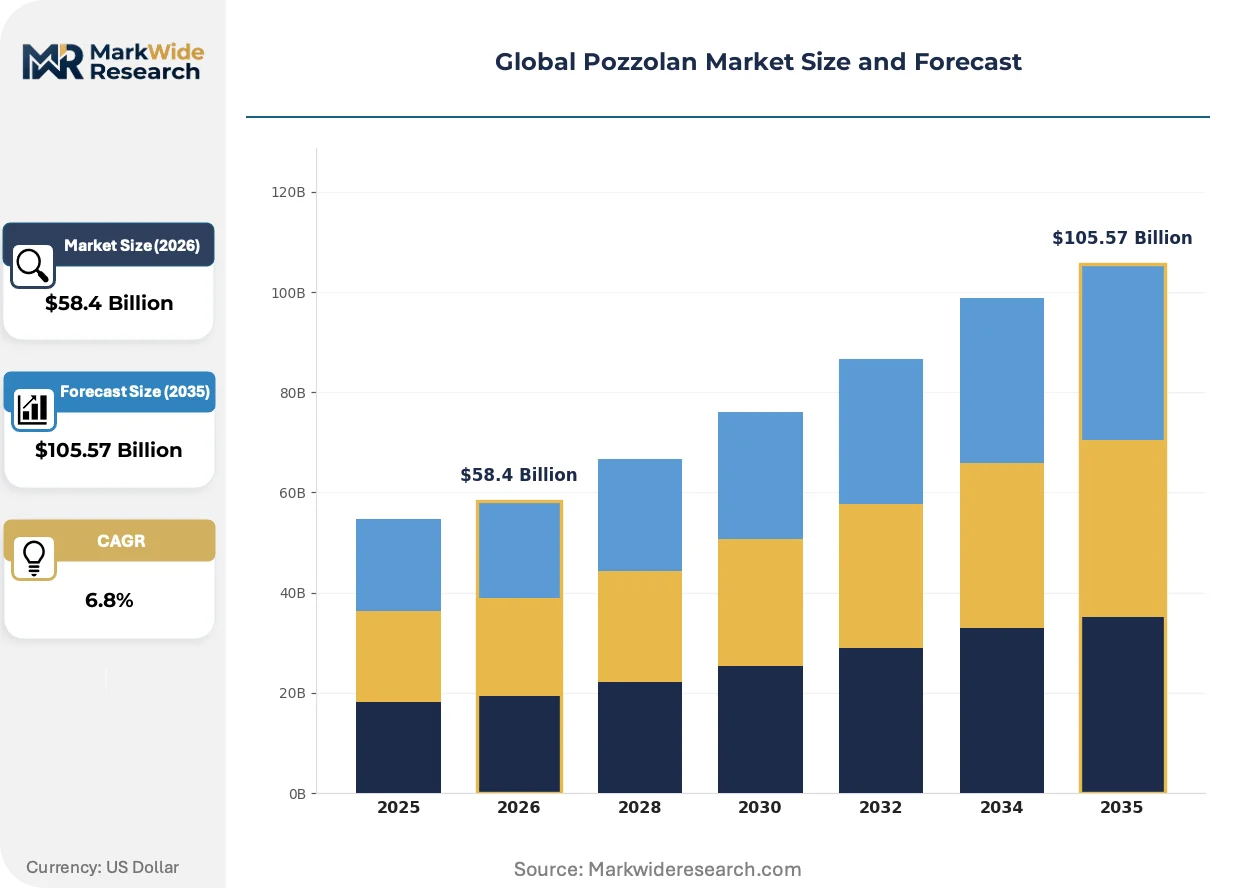
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Pozzolan, Fly Ash, Calcined Clay, Silica Fume, Metakaolin Application: Concrete Production, Cement Additive, Soil Stabilization, Wastewater Treatment, Asphalt Modification End User Industry: Construction Contractors, Infrastructure Developers, Precast Manufacturers, Ready-mix Suppliers, Road Builders Packaging Type: Bulk, Bagged, Loose Powder, Jumbo Bags, Sacks |
| Companies Covered | CEMEX S.A.B. de C.V., Charah Solutions, Inc., IMERYS, CR Minerals Company LLC, Hess Pumice Incorporated, CARBO Ceramics Inc., Burgess Pigment Company, Nevada Cement Company, Vulcan Ceramics Co Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pozzolan Market Shifts & Advancements
Calcined clay activation technologies are redefining supply economics by unlocking lower-grade kaolin deposits for specification-grade pozzolan production. Three convergent developments are compressing traditional fly ash dependency.
Flash calcination systems using suspension-based thermal processing are expanding into commercial-scale deployment across European and Southeast Asian production networks. Infrastructure developers in Vietnam and Indonesia are specifying activated clay blends at substitution rates previously reserved for fly ash. This technology is expanding into markets historically dependent on coal power byproduct sourcing.
REACH registration requirements in Europe are tightening import documentation for synthetic pozzolan formulations, forcing non-EU suppliers to establish EU-based testing and certification infrastructure. The regulation compresses time-to-market for new material entrants while elevating compliance costs. Beneficiation specialists serving ready-mix concrete producers are absorbing these overheads through dedicated European laboratory partnerships.
Long-term offtake agreements indexed to reactivity performance rather than delivered tonnage are displacing spot-market procurement in mega-project concrete supply chains. Engineering-procurement-construction firms in the Philippines and Indonesia now contract directly with beneficiation providers for guaranteed compressive strength contributions. This contractual evolution is most visible in hydropower and bridge construction verticals where durability warranties extend across multi-decade operational horizons.
Global Pozzolan Market Segmentation
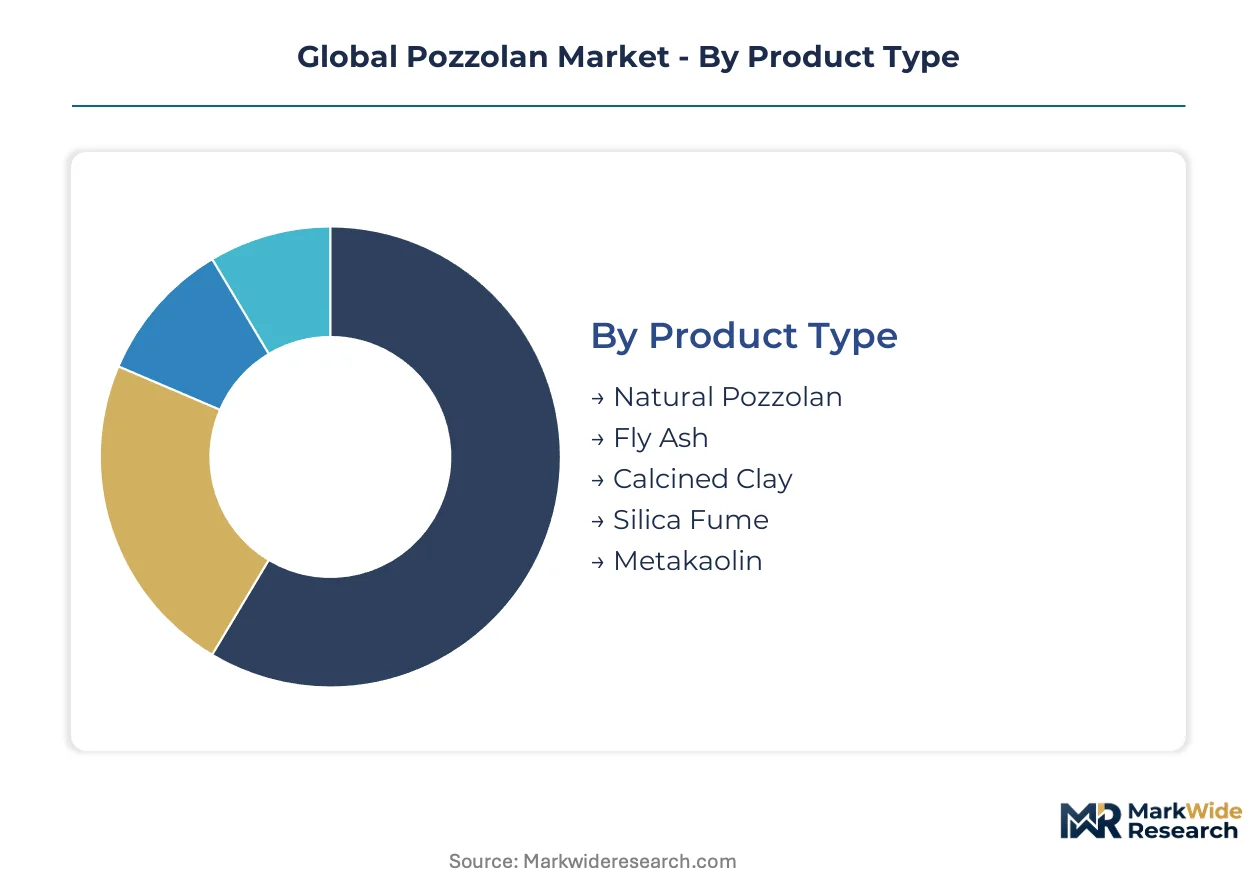
Pozzolan procurement decisions hinge on material reactivity, logistics configuration, and end-use performance requirements. Segmentation reveals how specification-grade supply chains diverge from commodity-grade flows across product categories and customer interfaces.
Product Type:
Upgrade cycles in concrete formulation are compressing specification windows for traditional pozzolan sources, forcing substitution decisions across reactivity tiers.
- Fly Ash:Coal combustion byproduct with pozzolanic activity index typically exceeding 75 percent. Infrastructure developers in Vietnam and Indonesia specify beneficiated fly ash for hydropower concrete requiring sulfate resistance under prolonged immersion conditions.
- Calcined Clay:Thermally activated kaolin or illitic clays processed at 700-850°C. Demand is concentrating in Germany and the Netherlands where EU Green Deal thresholds reward high-volume Portland cement substitution with verified embodied carbon reductions.
- Natural Pozzolan:Volcanic ash deposits with inherent siliceous-aluminous composition. Italian and Greek extraction sites face environmental permitting constraints limiting volume scalability.
- Silica Fume:Ferrosilicon smelting byproduct with specific surface area exceeding 15,000 square meters per kilogram. High-performance precast applications in the Middle East absorb premium pricing for compressive strength gains.
- Metakaolin:Dehydroxylated kaolin with refined particle distribution and controlled whiteness. Architectural facade producers in Saudi Arabia and the UAE specify material for aesthetic consistency alongside mechanical performance.
Volume placements concentrate in Fly Ash; the faster expansion belongs to Calcined Clay.
Application:
Cost-tier differentiation separates specification-grade applications commanding reactivity guarantees from commodity-grade uses tolerating broader quality variance.
- Concrete Production:Ready-mix and site-batched concrete incorporating pozzolan at 15-35 percent cement replacement rates. Coastal resilience projects in the Philippines mandate chloride-resistant formulations with proven pozzolanic contribution to durability warranties.
- Cement Additive:Inter-grinding or blending operations at integrated cement plants. Blended cement producers in France and Germany optimize clinker factors to meet EU Green Deal procurement thresholds for public infrastructure.
- Soil Stabilization:Lime-pozzolan mixtures for subgrade modification in road construction. Nigerian and Kenyan road builders import specification-grade material lacking domestic beneficiation capacity.
- Wastewater Treatment:Adsorptive applications leveraging pozzolan surface chemistry for heavy metal removal. Industrial effluent treatment facilities in India deploy fly ash for cost-sensitive filtration media.
- Asphalt Modification:Filler applications in bituminous mixtures for rut resistance and moisture damage mitigation. Highway maintenance contractors in Indonesia specify activated clay for tropical climate performance.
Concrete Production commands the dominant share of material flows; Cement Additive is climbing the fastest as regulatory thresholds tighten.
End User Industry:
Customer-type fragmentation creates divergent procurement patterns between project-specific contracting and continuous manufacturing operations.
- Infrastructure Developers:Mega-project sponsors contracting for multi-decade durability warranties. Hydropower and bridge consortia in Vietnam and Indonesia source reactivity-guaranteed supply through performance-indexed offtake agreements.
- Ready-mix Suppliers:Batch plant operators serving dispersed construction sites with just-in-time delivery requirements. Urban concrete producers in the Philippines balance inventory costs against specification compliance for coastal infrastructure bids.
- Construction Contractors:General builders procuring pozzolan through distributor channels for smaller-scale commercial and residential pours.
- Precast Manufacturers:Factory-cured element producers requiring consistent material properties for automated casting cycles.
- Road Builders:Specialized contractors focused on pavement and subgrade applications with less stringent reactivity verification.
Material volumes flow predominantly through Ready-mix Suppliers; Infrastructure Developers are gaining share fastest as performance contracting displaces spot procurement.
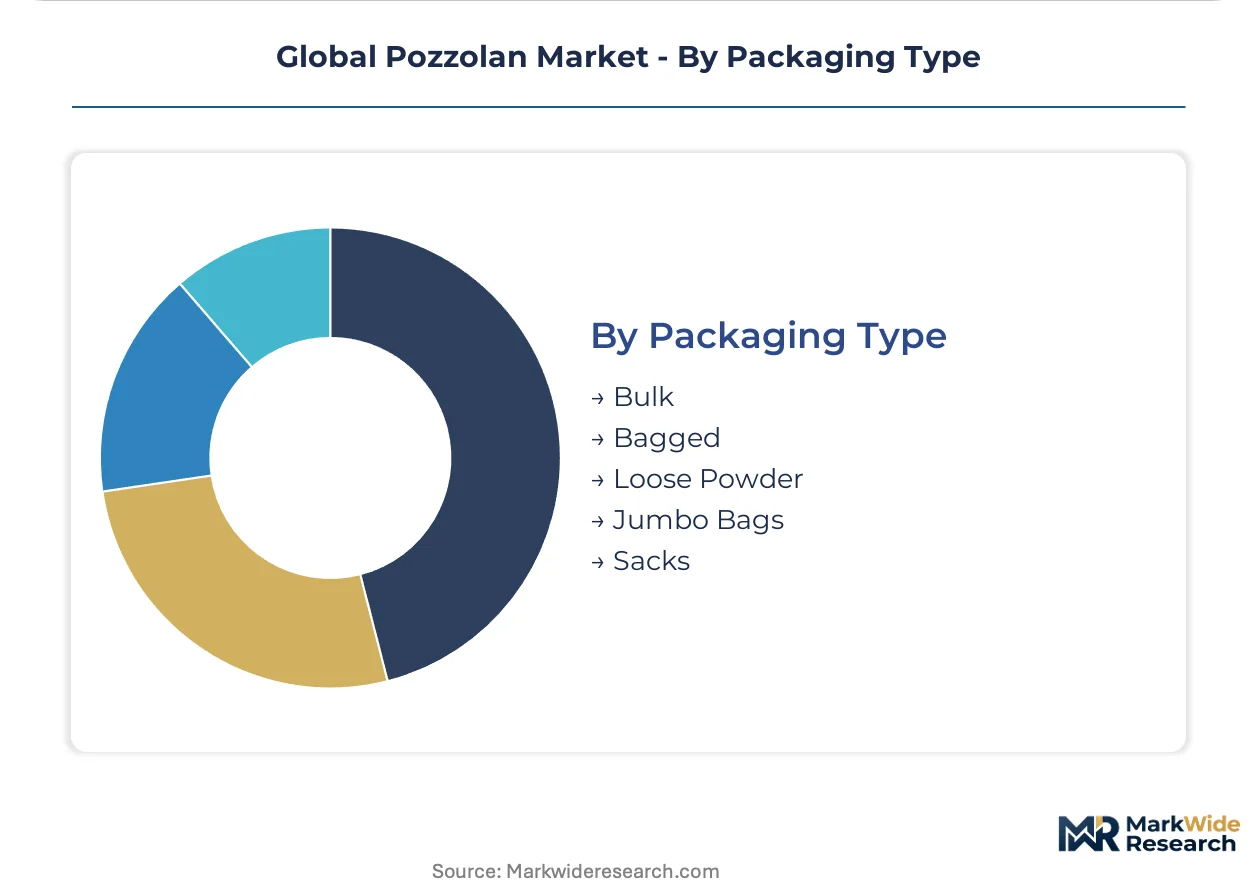
Packaging Type:
Supply concentration in bulk logistics shapes pricing architecture, while bagged formats serve fragmented demand nodes lacking pneumatic handling infrastructure.
- Bulk:Pneumatic tanker delivery to ready-mix plants and cement grinding stations. Integrated producers in India and China optimize logistics costs through direct power-plant-to-plant fly ash transfer.
- Jumbo Bags:One-tonne flexible intermediate bulk containers for mid-scale precast operations. Precast manufacturers in Egypt and Kenya rely on containerized jumbo bag imports where bulk handling is unavailable.
- Bagged:25-50 kilogram multi-wall paper or woven polypropylene sacks. Retail construction supply channels in Nigeria distribute bagged material to small contractors without silo storage.
- Loose Powder:Uncovered or minimally contained storage for non-specification applications. Soil stabilization contractors in Indonesia accept loose powder for cost-driven subgrade projects.
- Sacks:Smaller-format packaging for specialty applications and laboratory sampling. Metakaolin suppliers to architectural precast producers in the UAE utilize branded sacks for quality differentiation.
Bulk handling dominates volume economics; Jumbo Bags are expanding most quickly as import-dependent markets scale beneficiation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in coal-power corridors while consumption gravitates toward coastal infrastructure hotspots. This geographic asymmetry forces long-haul logistics or import dependency across major construction markets.
United States
Beneficiated fly ash supply clusters around legacy coal basins in the Ohio River Valley and Powder River Basin. EPA regulations under subtitle D of RCRA classify coal combustion residuals for beneficial use, stabilizing material recovery economics. Houston and Miami ready-mix corridors absorb volumes for coastal resilience concrete specifications.
Germany
EU Green Deal embodied carbon thresholds compress Portland cement specification windows for public infrastructure procurement. REACH registration requirements tighten import documentation for synthetic pozzolan formulations. The Rhine-Ruhr industrial corridor hosts calcined clay activation facilities serving Dutch and Belgian cross-border demand.
China
Dual carbon goals accelerate clinker factor reduction mandates across integrated cement plants. GB standards govern fly ash utilization rates in concrete production for hydropower and transport infrastructure. The Yangtze River Delta cement grinding cluster imports specification-grade material from domestic power-plant networks.
Vietnam
Hydropower dam specifications mandate sulfate-resistant binders with verified pozzolanic reactivity indices for reservoir immersion conditions. National infrastructure budgets prioritize durable concrete for Mekong Delta flood control systems. Ho Chi Minh City batch plants contract directly with beneficiation providers for performance-guaranteed supply.
India
BIS certification under IS 3812 mandates fly ash utilization compliance for concrete production in government-funded construction. The Delhi-Mumbai Industrial Corridor drives bulk material flows to ready-mix plants lacking domestic beneficiation capacity. Gujarat cement producers inter-grind imported specification-grade pozzolan to optimize clinker factors for export markets.
Global Pozzolan Market Competitive Landscape
Top-tier vendors anchor multi-geography production networks, while regional specialists occupy beneficiation and upgrade niches. The vendor base stratifies across integrated cement producers with captive ash sourcing, minerals processors with calcination expertise, and third-party beneficiation services. Three archetypes dominate: power-sector-integrated suppliers, clay calcination specialists, and performance-contracting service providers. Capacity expansion and reactivity-guaranteed offtake agreements represent the dominant competitive vectors.
Among vertically integrated construction material producers, CEMEX S.A.B. de C.V. and IMERYS occupy positions spanning multiple geographies and reactivity tiers. Charah Solutions, Inc. exemplifies the service-provider archetype, anchoring beneficiation capabilities that upgrade lower-grade material into specification-grade supply. These three entities collectively represent the competitive spectrum from captive resource control through third-party value-add processing.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Charah Solutions, Inc. |
| IMERYS |
| CR Minerals Company LLC |
| Hess Pumice Incorporated |
| CARBO Ceramics Inc. |
| Burgess Pigment Company |
| Nevada Cement Company |
| Vulcan Ceramics Co Pvt Ltd |
| Others |
Supply & Pricing Matrix
Flash calcination technology adoption in Vietnam and Indonesia is compressing production costs for specification-grade calcined clay while fragmenting supply concentration away from legacy coal-power corridors. This dual effect rewards early technology adopters with pricing power while forcing traditional fly ash suppliers into reactive cost positioning.
Pricing Analysis
Margin tightening in beneficiated fly ash reflects declining coal-power generation in the US and India that constrains raw material availability. Three-tier pricing structure across premium metakaolin, standard calcined clay, and economy fly ash segments tracks reactivity certification tiers and volume scale. Pricing pressure intensifies in standard-tier calcined clay as European kiln operators expand capacity into Southeast Asian markets. Infrastructure developers in the Philippines exhibit lowest price sensitivity due to durability warranty requirements, while road builders in Nigeria show highest sensitivity given limited domestic beneficiation alternatives.
Supply Chain Analysis
Single-source vulnerability sits with legacy coal-power regions in the US, India, and China where beneficiated fly ash availability clusters around aging generation assets. Raw material flows draw from coal combustion residuals, kaolin deposits, and volcanic ash reserves. Supply chain risk centers on regulatory reclassification of coal ash under EPA subtitle D and REACH registration barriers for non-EU synthetic pozzolan suppliers. Distribution runs through pneumatic bulk tanker networks to ready-mix plants, with jumbo bag formats serving import-dependent African markets lacking pneumatic handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as capital intensity for rotary kiln retrofitting and REACH compliance overhead forces marginal producers toward exit or acquisition.
For Market Incumbents: Extend reactivity-guaranteed offtake agreements into multi-decade hydropower and coastal infrastructure contracts to lock out emerging calcined clay entrants. Anchor backward integration into captive fly ash sourcing from power sector partnerships before coal plant retirements accelerate. Defend position by absorbing European laboratory partnerships to neutralize REACH compliance cost advantages for regional specialists. For New Entrants and Emerging Players: Ready-mix suppliers in Nigeria, Kenya, and Egypt represent the most penetrable channel partner type given absent domestic beneficiation capacity and construction growth trajectories requiring imported specification-grade material. Target soil stabilization and road-building verticals where reactivity verification requirements remain less stringent than hydropower specifications. Establish jumbo bag distribution partnerships with containerized import logistics to bypass bulk handling infrastructure gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated cement producers seeking captive pozzolan supply to optimize clinker factors for EU Green Deal compliance. Long-term viability favors calcined clay activation specialists with proven kiln retrofitting capabilities and multi-geography production networks. Watch for BIS certification expansion beyond IS 3812 fly ash mandates toward calcined clay standards as the inflection signal for technology transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rotary Kiln Retrofitting | Unlocks lower-grade kaolin deposits for specification-grade pozzolan production in Vietnam and Indonesia. |
| REACH Registration Compliance | Establishes EU market access for non-European synthetic pozzolan suppliers through certified testing infrastructure. |
| Reactivity-Guaranteed Offtake Agreements | Replaces spot-market procurement in Philippine and Indonesian hydropower concrete supply chains. |
| Power Sector Ash Partnerships | Secures long-term fly ash supply ahead of coal plant retirements in the US Ohio River Valley. |
| European Laboratory Partnerships | Absorbs REACH compliance overhead for beneficiation specialists serving ready-mix producers. |
Research Methodology
Independent corroboration across cement plant technical directors, ready-mix procurement managers, beneficiation equipment operators, and infrastructure project engineers underwrites the qualitative findings. Primary interviews with rotary kiln specialists and REACH compliance consultants combined with secondary validation from BIS certification records, EPA RCRA filings, EU ECHA registration databases, and customs trade data for pozzolan imports. Bottom-up volume estimates from individual production facility capacities triangulate against top-down cement consumption projections across the analysis window.
Rate-of-change decomposition separates volume growth into clinker substitution rate expansion, infrastructure project pipeline acceleration, and regulatory threshold tightening effects. Segmentation dimensions modeled include product type tier, application reactivity requirement, end-user procurement pattern, and regional production-consumption asymmetry. CAGRs derive from logistic curve fitting to historical substitution rates and scenario-weighted regulatory implementation timelines. Industry-specific inputs incorporate EU Green Deal embodied carbon threshold schedules and hydropower concrete specification evolution in Southeast Asia.
Caveats apply where EPA coal ash reclassification, REACH substance evaluation updates, or flash calcination technology cost breakthroughs could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation pace and infrastructure budget execution that remain sensitive to political and macroeconomic discontinuities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Exterior Doors Market
Building Materials
Construction Materials Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Foam Bricks Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Mass Timber Construction Market
Building Materials
Solar Control Window Film Market
Building Materials
North America Architectural Coatings Market
Building Materials
West Africa Cement Market
Building Materials
Steel Products Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Long Steel Market
Building Materials
Dry Mix Mortar Market
Building Materials
Facade Gasket Market
Building Materials
Construction Glass Market