
 Basalt Rock Market | 2026-2036
Basalt Rock Market Size, Share, and Industry Trends Forecast 2026-2036
Basalt Rock Market Outlook
The EU Green Deal's embodied carbon benchmarks for construction materials is hardening procurement criteria across European public infrastructure tenders. Kamenny Vek leverages its integrated quarry-to-fiber operation in Russia's northwest to sustain cost leadership in continuous basalt fiber. Mafic SA anchors its position through captive mining assets in Ireland and specialized furnace technology. Sichuan Fiberglass Group dominates Chinese basalt fiber output with state-backed capacity expansions.
Basalt rock is a fine-grained volcanic igneous material formed from rapidly cooled lava, with silica content typically ranging from 45% to 52% and density near 2.9 g/cm³, valued for compressive strength exceeding 400 MPa and alkali resistance in engineered applications. Crushed stone and aggregate occupy the volume core of the market, serving road base and concrete feedstock where specification-grade uniformity commands premium pricing. Fiber segments are recording the fastest structural expansion as manufacturers displace E-glass and steel rebar in corrosive environments. Tile and decorative grades retain margin concentration in bespoke architectural and landscaping projects.
REACH compliance in Europe and China's GB standards for construction materials are tightening allowable thresholds for heavy metal leachate and volatile emissions in processed basalt products. The US EPA and state-level DOT specifications influence aggregate certification for federally funded infrastructure, while India's BIS grading protocols for dimensional stone govern export eligibility. Stakeholders must monitor regulatory divergence between carbon accounting frameworks and material performance standards as specification authority fragments across jurisdictions.
Market Dynamics
Steel rebar displacement by basalt fiber reinforcement is restructuring specification authority across construction procurement, as embodied carbon accounting migrates from voluntary reporting to mandatory tender thresholds in public infrastructure.
Growth Catalysts
- EU Green Deal benchmarks:Embodied carbon limits in construction materials are redirecting public tender specifications toward low-carbon reinforcement alternatives in Germany, France, and the Netherlands.
- Corrosive environment demand:Marine infrastructure and chemical processing facilities are specifying alkali-resistant basalt fiber over conventional steel in coastal China and the US Gulf Coast.
- Dual carbon policy framework:China's national carbon peak and neutrality targets are accelerating substitution mandates in state-backed infrastructure projects.
Market Restraints
- Energy-intensive fusion processing:Electric furnace operations for continuous basalt fiber require sustained high-temperature energy inputs vulnerable to industrial electricity tariff volatility.
- Feedstock geographic concentration:Quarry-grade basalt with optimal silica-to-iron ratios concentrates in specific volcanic formations across Russia's northwest and Sichuan province.
- E-glass price competition:Established fiberglass supply chains and amortized manufacturing assets in Owens Corning's legacy infrastructure maintain cost advantages in non-corrosive applications.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and metro rail projects in Maharashtra and Gujarat are converging with domestic basalt quarry development in Deccan Trap formations.
- Automotive lightweighting mandates:Electric vehicle platform engineering teams are evaluating basalt fiber composites for battery enclosure thermal management and structural reinforcement.
- Green public procurement directives:The EU's revised Clean Vehicles Directive and Construction Products Regulation are embedding lifecycle carbon thresholds that favor regional basalt fiber suppliers.
Industry Challenges
- Continuous fiber furnace engineering scarcity:Specialized refractory design and process control expertise for platinum-rhodium bushing operations remains concentrated among a limited technical workforce.
- Multi-jurisdiction certification timelines:Securing CE marking under Construction Products Regulation, US DOT aggregate certification, and India's BIS dimensional stone grading requires sequential testing protocols.
- Downstream integration complexity:Composite manufacturers face re-tooling costs for resin systems and molding equipment when transitioning from E-glass to basalt fiber reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basalt Rock Market |
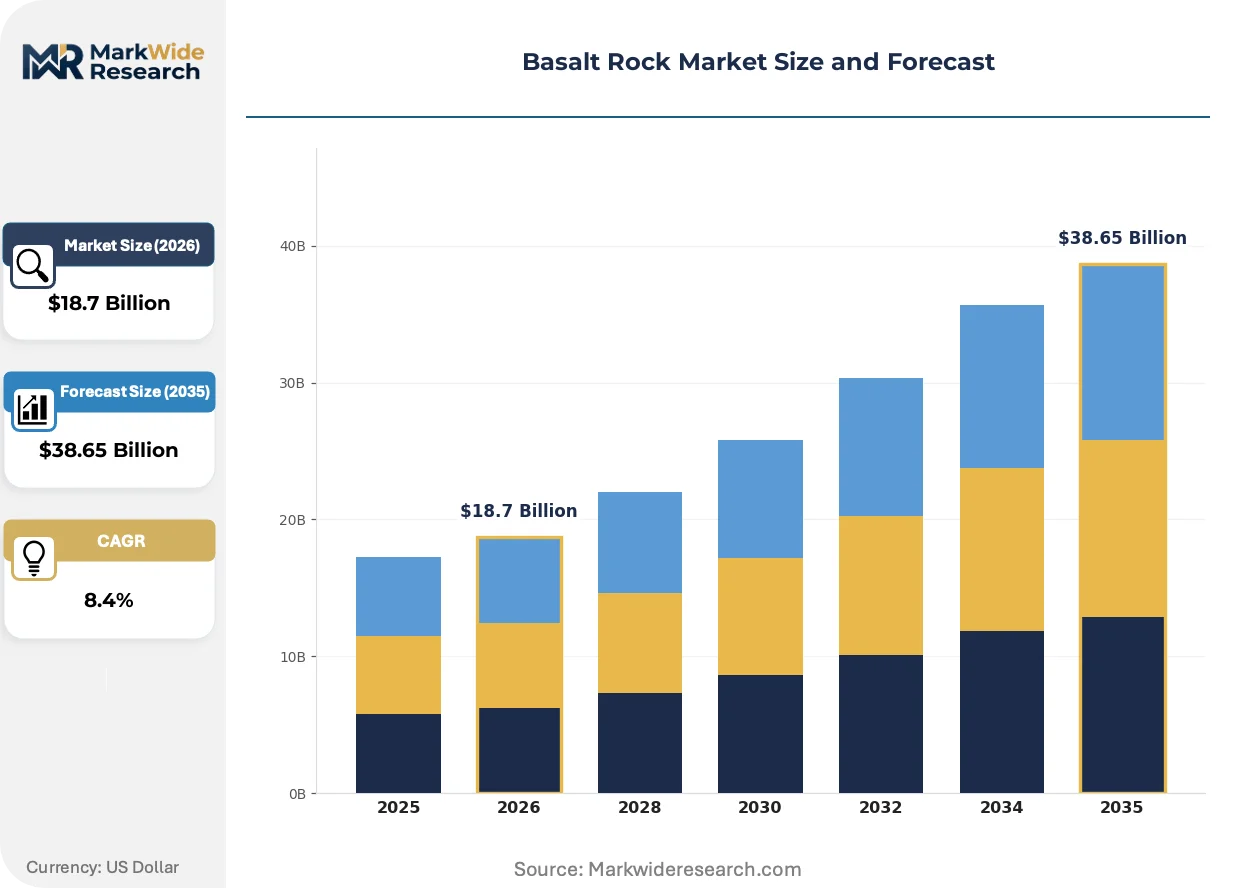
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Stone, Aggregate, Fiber, Tile Application: Construction, Road Infrastructure, Landscaping, Decorative End Use Industry: Building, Manufacturing, Mining, Energy Distribution Channel: Direct Sales, Distributors, Retailers, Online |
| Companies Covered | Kamenny Vek, Deutsche Basalt Faser GmbH, Technobasalt Invest LLC, Arab Basalt Fiber Company, Aravali India Marbles & Granites, Sichuan Fiberglass Group, Basaltex NV, Mafic SA, Zhejiang GBF Basalt Fiber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basalt Rock Market Strategic Shifts
Process intensification in fiber manufacturing and carbon-accounting integration across supply chains are compressing the cost-performance gap between basalt and conventional reinforcement materials.
Platinum-rhodium bushing furnace technology is unifying temperature control and filament diameter precision in continuous basalt fiber production. European composite manufacturers are adopting these systems for specification-grade automotive and wind energy components. The technology is unifying quality consistency across batch production runs that previously required extensive post-processing.
REACH authorization requirements for chromium compounds in refractory materials are forcing furnace lining substitutions in European basalt fiber operations. Manufacturers are trialing alumina-zirconia-silica formulations that maintain thermal shock resistance without hexavalent chromium exposure. German and Polish production facilities face the steepest compliance timelines under ECHA's sunset date enforcement.
Buyers in municipal infrastructure are consolidating specification authority through framework agreements that bundle aggregate supply, fiber reinforcement, and technical certification services. Engineering procurement departments in Dutch water management and French transport infrastructure are displacing fragmented spot purchasing with multi-year performance contracts. This concentration is most visible in North Sea coastal protection and Rhône-Alpes tunneling projects where lifecycle cost guarantees override unit price competition.
Basalt Rock Market Segmentation
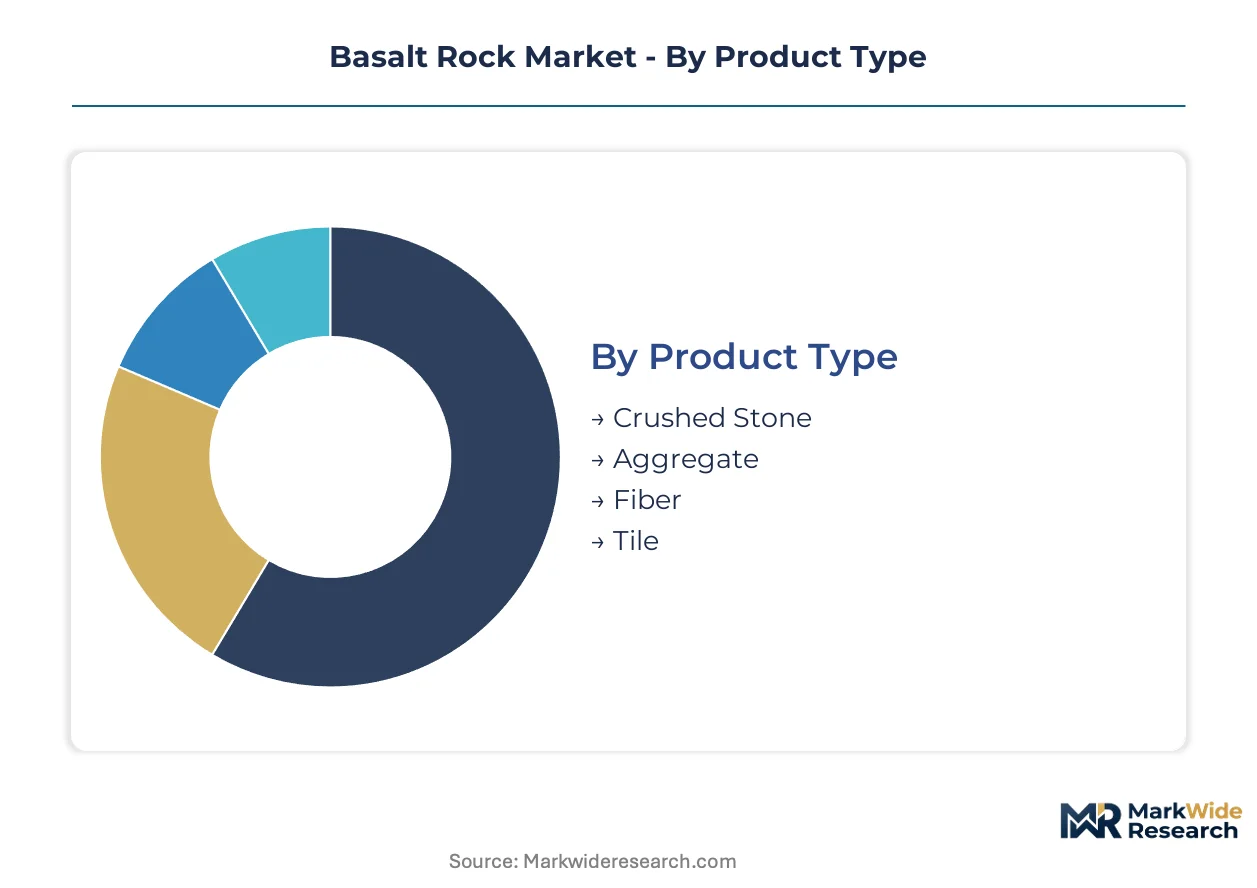
Basalt rock market segmentation reveals divergent capital requirements and margin profiles across product categories. Specification-grade fiber production demands furnace infrastructure investments that aggregate crushing operations avoid entirely. Understanding these structural differences clarifies where value capture concentrates and where volume flows.
Product Type:
Continuous basalt fiber manufacturing requires the heaviest upfront capital commitment among all segments, with platinum-rhodium bushing furnaces and precision temperature control systems representing multi-million dollar installations. Quarry operations for crushed stone and aggregate demand less specialized equipment but face escalating environmental compliance costs.
- Crushed Stone:This segment supplies road base and concrete feedstock where compressive strength specifications govern procurement decisions. German and Dutch public infrastructure tenders now embed embodied carbon thresholds that favor regional basalt over limestone alternatives in North Sea coastal protection projects.
- Fiber:Continuous filament production transforms quarry-grade basalt into alkali-resistant reinforcement through electric furnace fusion at temperatures exceeding 1400°C. Marine infrastructure specifications in coastal China and the US Gulf Coast are displacing steel rebar with basalt fiber in corrosion-critical applications.
- Aggregate:Specification-grade uniformity commands premium pricing in high-performance concrete applications. Indian Deccan Trap formations are expanding output to serve national highway expansion in Maharashtra and Gujarat.
- Tile:Decorative dimensional stone serves bespoke architectural and landscaping projects where aesthetic grading determines value. REACH compliance for heavy metal leachate shapes European export eligibility.
Most installed capacity flows through Crushed Stone. Expansion is steepest in Fiber.
Application:
Construction applications dominate volume throughput while road infrastructure commands the most standardized specification regimes. Landscaping and decorative segments operate at lower volumes but retain pricing power through aesthetic differentiation.
- Construction:Building reinforcement and structural concrete represent the core demand sink for both aggregate and fiber grades. China's dual carbon policy framework accelerates substitution mandates in state-backed infrastructure projects.
- Road Infrastructure:Highway base layers and asphalt modification consume the largest tonnage of crushed basalt. US state DOT specifications influence aggregate certification requirements for federally funded projects.
- Landscaping:Decorative aggregate and dimensional stone serve commercial and residential outdoor design. Premium pricing attaches to color consistency and surface finish uniformity.
- Decorative:Architectural cladding and interior stone applications demand precise cutting and polishing capabilities. India's BIS grading protocols govern dimensional stone export eligibility.
Construction absorbs the majority of tonnage. Road Infrastructure is climbing the fastest as national highway programs accelerate.
End Use Industry:
Building sector procurement patterns are restructuring as embodied carbon accounting migrates from voluntary reporting to mandatory tender thresholds. Manufacturing applications for fiber reinforcement are expanding most quickly despite smaller current volume bases.
- Building:Commercial and residential construction drives aggregate demand while green building certifications redirect reinforcement specifications toward low-carbon alternatives. EU Green Deal benchmarks harden procurement criteria across European public tenders.
- Manufacturing:Composite fabrication for automotive, wind energy, and industrial equipment represents the emerging demand frontier. Electric vehicle platform engineering teams evaluate basalt fiber for battery enclosure thermal management.
- Mining:Mine backfill and tailings management consume lower-specification aggregate grades. Volume contracts dominate procurement with limited premium differentiation.
- Energy:Geothermal well casing and drilling fluid additives utilize specialized basalt formulations. Technical specification requirements limit supplier pools.
Building sector offtake remains dominant. Manufacturing is gaining share fastest as automotive lightweighting mandates proliferate.
Distribution Channel:
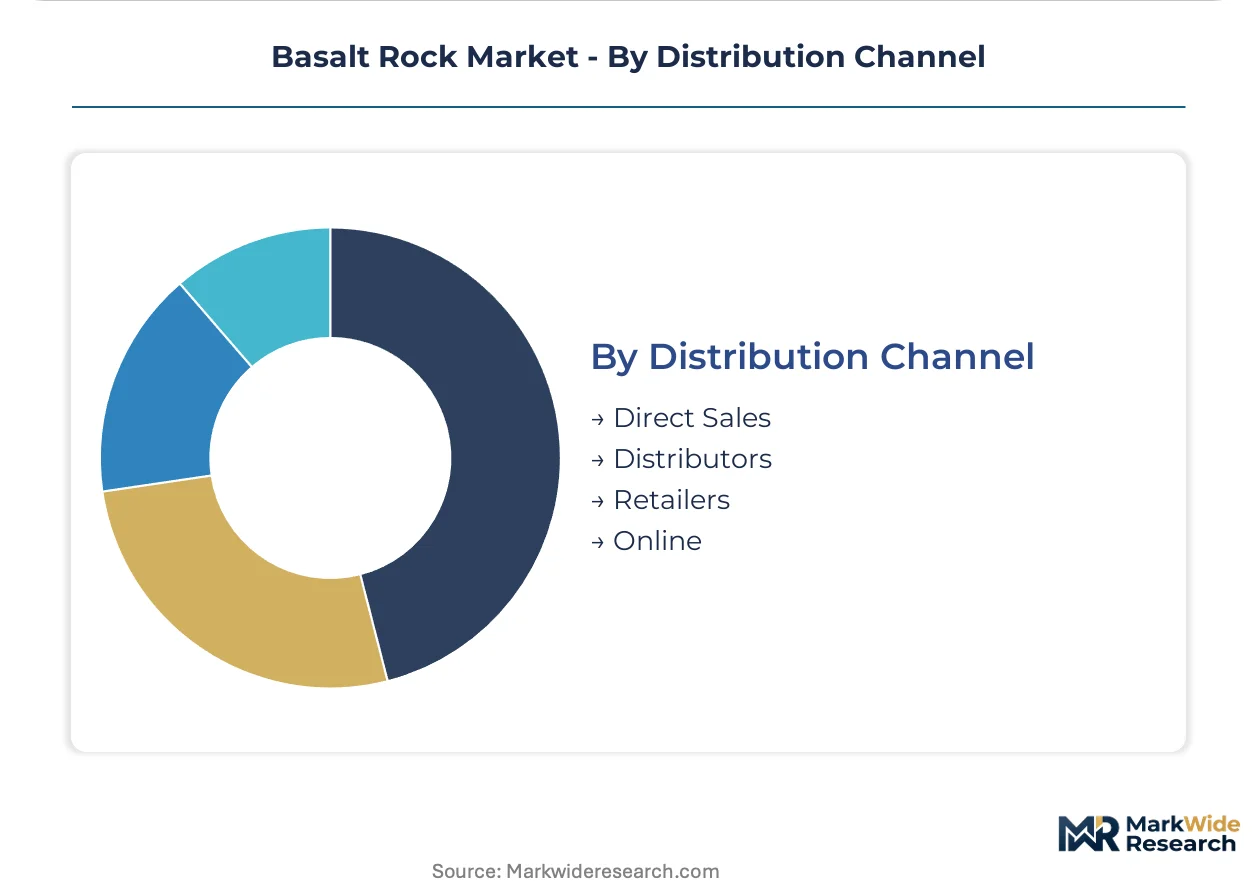
Direct sales relationships concentrate in fiber segments where technical certification and application engineering support justify dedicated account management. Aggregate and crushed stone flow through more fragmented channel structures.
- Direct Sales:Continuous basalt fiber producers maintain direct relationships with composite manufacturers and major infrastructure contractors. Framework agreements bundle supply, certification, and technical services.
- Distributors:Regional aggregate and dimensional stone distributors aggregate quarry output for construction material yards. Inventory positioning near major metropolitan markets determines competitive position.
- Retailers:Landscaping and decorative tile segments reach end-users through building material retailers and specialty stone showrooms. Visual merchandising and sample availability influence selection.
- Online:Digital channels serve small-volume decorative and specialty aggregate purchases. Specification-grade fiber and large construction contracts remain offline.
Direct Sales captures the highest value per ton. Distributors handle the largest aggregate volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basalt fiber manufacturing originated in the Soviet Union's military-industrial complex during the Cold War, with Russia's northwest volcanic formations supplying the first continuous filament production. Quarry-grade basalt extraction now spans volcanic belts across three continents.
China
Sichuan province hosts the densest concentration of basalt fiber capacity, with state-backed expansions serving coastal marine infrastructure projects. MIIT's dual carbon policy framework mandates low-carbon reinforcement in state-backed construction tenders. Chongqing-based furnace operations supply alkali-resistant fiber for chemical processing facilities along the Yangtze River Delta.
Russia
The northwest Leningrad Oblast and Karelia region contain volcanic formations with optimal silica-to-iron ratios for continuous fiber production. Domestic producers leverage captive quarry access to sustain cost leadership in export markets. St. Petersburg industrial clusters process raw basalt into specification-grade reinforcement for EU-bound shipments.
India
Maharashtra and Gujarat infrastructure buildouts converge with Deccan Trap quarry expansion in western states. BIS grading protocols for dimensional stone govern export eligibility to Middle Eastern construction markets. Mumbai-Pune industrial corridors anchor composite manufacturing clusters targeting automotive lightweighting applications.
Germany
Rhine-Ruhr metropolitan infrastructure tenders embed EU Green Deal embodied carbon thresholds that favor regional basalt over steel reinforcement. ECHA's REACH sunset dates for chromium compounds force furnace lining substitutions at production facilities. North Rhine-Westphalia engineering procurement departments consolidate specification authority through multi-year performance contracts.
United States
Gulf Coast marine infrastructure specifications displace steel rebar with basalt fiber in corrosion-critical applications from Texas to Florida. EPA and state-level DOT aggregate certification requirements govern federally funded highway projects. Appalachian basin quarry operations supply road base material for southeastern interstate expansion programs.
Basalt Rock Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the basalt rock value chain. Quarry operators with captive mineral rights face off against specialized fiber manufacturers lacking backward integration. The structure fragments across three strategic archetypes: integrated quarry-to-fiber operators, captive-mining specialists, and toll-processing fabricators. Dominant competitive moves include capacity expansion in volcanic formation proximity and strategic partnerships with composite end-users.
Among Russia-based integrated operators, Kamenny Vek exemplifies the quarry-to-fiber archetype through its northwest mineral rights position. Sichuan Fiberglass Group represents state-backed scale concentration in Chinese basalt fiber. Mafic SA occupies a position among European captive-mining specialists with Irish geological assets.
| Leading Market Players |
|---|
| Kamenny Vek |
| Deutsche Basalt Faser GmbH |
| Technobasalt Invest LLC |
| Arab Basalt Fiber Company |
| Aravali India Marbles & Granites |
| Sichuan Fiberglass Group |
| Basaltex NV |
| Mafic SA |
| Zhejiang GBF Basalt Fiber |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal embodied carbon thresholds in public infrastructure tenders are forcing procurement departments toward low-carbon reinforcement alternatives, compelling fiber producers to absorb furnace energy costs while quarry operators capture premium pricing for specification-grade aggregate. This demand-side pressure reshapes margin distribution across the value chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, separating CE-marked continuous fiber from industrial-grade aggregate and unprocessed quarry run. Price differentiation hinges on certification grade under EU Construction Products Regulation and volume scale in highway contracts. Cost compression in standard-grade fiber is intensifying because E-glass producers leverage amortized assets. Municipal infrastructure buyers exhibit highest price sensitivity, while automotive engineering teams prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EU framework agreement holders mandate qualified backup suppliers for critical reinforcement, stretching procurement timelines. Geographic supply concentration centers on Russia's northwest volcanic formations, Sichuan province in China, and Ireland's captive mining assets. Raw material dependencies include platinum-rhodium bushings, alumina-zirconia-silica refractory linings, and quarry-grade basalt with precise silica-to-iron ratios. Single-source vulnerability in furnace engineering expertise concentrates risk. Distribution runs through direct sales for fiber and regional distributors for aggregate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in specification-grade fiber as furnace energy efficiency improvements and automotive qualification premiums shift the cost-performance frontier. The analysis window favors producers with backward integration into quarry assets.
For Market Incumbents: Lock in quarry access through mineral rights consolidation in Russia's northwest and Deccan Trap formations. Invest in platinum-rhodium bushing furnace upgrades to meet REACH chromium compound sunset deadlines. E-glass price competition threatens standard-grade fiber margins; defend through automotive lightweighting certification with OEM engineering teams. For New Entrants and Emerging Players: Begin with toll-processing arrangements for Indian Deccan Trap quarry output, supplying Maharashtra highway expansion without furnace capital burden. Target decorative tile export to Middle Eastern construction markets governed by BIS grading protocols. Pursue technical partnership route with European composite manufacturers seeking non-Chinese fiber sources. For Investors and Strategic Acquirers: Asymmetric upside sits with captive-mining specialists possessing integrated quarry-to-fiber operations. Long-term viability rests on carbon-accounting integration across construction supply chains. Watch for EU Green Deal threshold tightening in German and Dutch public tenders as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive basalt supply locks in feedstock quality and insulates against Sichuan price volatility. |
| Platinum-Rhodium Bushing Furnace Upgrade | Precision temperature control meets automotive specification requirements for battery enclosure composites. |
| CE Marking Pathway Investment | Construction Products Regulation compliance opens EU public infrastructure framework agreements. |
| Long-term Supply Agreement with OEMs | Electric vehicle platform engineering teams require qualified fiber sources for thermal management. |
| Joint Venture in Deccan Trap Region | Maharashtra quarry development pairs with domestic infrastructure buildout for cost-competitive aggregate. |
Study Parameters
Bottom-up construction sector modeling reconciled against top-down quarry capacity tracking forms the analytical core of this study. Primary interviews with furnace operations engineers, infrastructure procurement managers, composite manufacturing R&D directors, and quarry development executives were validated against secondary sources including EU ECHA REACH filings, US EPA aggregate certification records, Indian BIS dimensional stone protocols, and Chinese MIIT dual carbon policy documents. Trade data from customs authorities and construction tender databases provided volume cross-checks.
Historical trendline analysis of fiber production capacity and aggregate extraction rates informed the projection framework across the analysis window. Segmentation modeling incorporated product type, application, end-use industry, and distribution channel dimensions. CAGRs were derived from regression analysis of installed capacity expansion and substitution elasticity in reinforcement markets. Forecast inputs included EU Green Deal implementation timelines and automotive lightweighting mandate proliferation.
Caveats apply where furnace energy tariff volatility or REACH authorization delays could materially shift the outlook. Deviation in EU carbon border adjustment mechanisms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
UK Aluminum Door and Window Market
Building Materials
Europe Fiber Cement Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
US Facade Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
HDG Steel Pipe Market
Building Materials
Latin America Facade Market
Building Materials
Construction Repair Composites Market
Building Materials
India Concealed Cistern Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Brick Adhesive Market