
 Gypsum Concrete Market | 2026-2036
Gypsum Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum Concrete Market Outlook
Portland cement is repositioning within floor underlayment specifications as gypsum concrete gains share on thermal performance and installation speed metrics. USG Corporation leverages captive gypsum reserves and integrated board-to-pour manufacturing to sustain cost leadership. Hacker Industries, Inc. anchors its position through specialized acoustic formulations that dominate multi-family and hospitality verticals. MAXXON, INC. differentiates via lightweight gypsum systems that reduce structural dead loads in mid-rise construction.
Gypsum concrete comprises calcined gypsum plaster, sand, and water mixed to a flowable consistency that self-levels across substrates, typically achieving compressive strengths between 2,000 and 3,000 psi for residential and commercial underlayment applications. Its primary purpose is to create flat, sound-attenuated, fire-resistant floor assemblies over wood or concrete substrates. Self-leveling formulations command the largest volume share due to labor savings in large-format commercial pours, while lightweight variants represent the fastest-expanding category as structural engineers prioritize mass reduction in Type III and V construction. Direct sales channels capture the highest margin pools by bypassing distributor markups on specification-grade projects.
ASTM C317 governs gypsum concrete physical requirements in the United States, while the International Building Code (IBC) mandates fire-resistance ratings that gypsum underlayment satisfies through inherent crystalline water content. EPA emissions standards for stationary sources constrain calcination plant siting, tightening regional supply availability. Stakeholders must monitor specification shifts toward mass timber construction, where gypsum concrete's compatibility with CLT and nail-laminated timber floor decks creates adjacent demand pools.
Market Dynamics
Multi-family housing construction cycles and embodied carbon regulations are redirecting specification flows toward gypsum concrete, compressing traditional Portland cement underlayment volumes as developers prioritize speed-to-occupancy and fire-rated assemblies.
Growth Catalysts
- EPA embodied carbon mandates:Federal procurement guidelines now weight lower-carbon materials in building specifications, elevating gypsum concrete's crystalline water content as a passive fire-resistance advantage over cementitious alternatives.
- Mass timber construction compatibility:Cross-laminated timber and nail-laminated timber floor decks require compatible underlayment systems, creating adjacent demand pools where gypsum concrete's bond strength and dimensional stability satisfy structural engineering requirements.
- Acoustic performance premiums:Multi-family developers in dense urban corridors specify STC-rated assemblies to meet lease-up velocity targets, driving specification toward gypsum formulations engineered for impact sound attenuation.
Market Restraints
- Calcination energy costs:Natural gas price volatility directly compresses manufacturing margins for gypsum plaster production, constraining price competitiveness against cement-based alternatives in cost-sensitive renovation segments.
- Regional supply concentration:Captive gypsum reserves cluster in specific geologic formations, creating freight-cost penalties for projects sited beyond 500-mile radii of major production facilities.
- Moisture sensitivity limitations:Gypsum concrete's hygroscopic properties restrict below-grade and wet-area applications, ceding specification share to epoxy and polymer-modified cement systems in basement and utility room flooring.
Strategic Opportunities
- Lightweight formulation expansion:Structural engineers in mid-rise Type III construction increasingly specify reduced dead-load systems, opening specification pathways for expanded polystyrene-aggregate gypsum concrete with densities below 100 pcf.
- Direct sales channel penetration:Large-format commercial projects bypass distributor markups through specification-grade direct relationships, capturing margin pools unavailable in residential retrofit channels.
- Self-leveling automation integration:Pumping and screeding equipment convergence with flowable gypsum formulations reduces skilled labor requirements, compressing installation timelines for hospitality and healthcare renovation cycles.
Industry Challenges
- Specialized applicator certification gaps:ASTM C317 compliance and fire-rated assembly documentation require trained installation crews, creating bottlenecks in markets where gypsum concrete penetration outpaces workforce development.
- Legacy substrate compatibility testing:Adhesion failures on contaminated or sealed concrete slabs necessitate pre-installation moisture and bond testing, extending project timelines and increasing specification risk for general contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum Concrete Market |
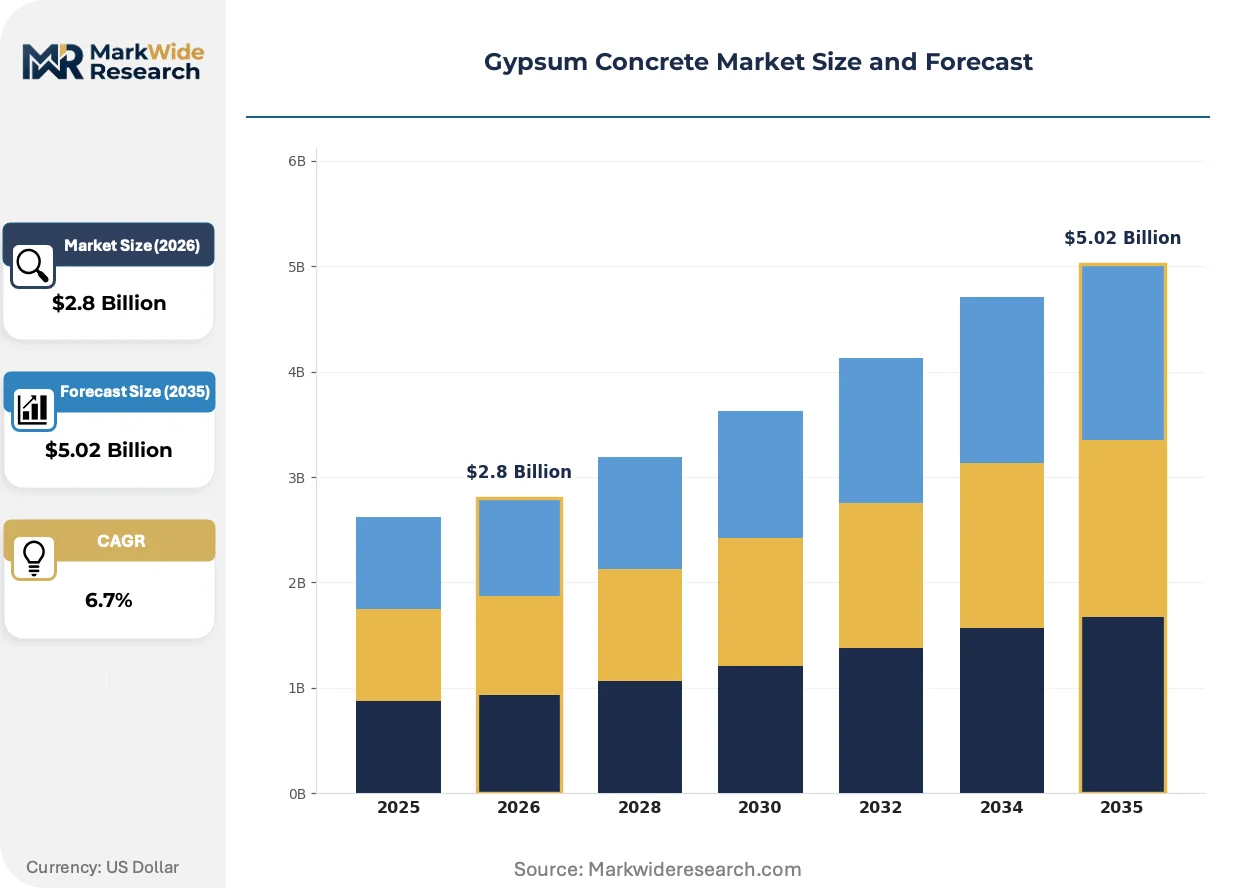
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Leveling, Pre-Mixed, Lightweight, Decorative Application: Commercial Buildings, Residential Properties, Industrial Facilities, Flooring Distribution Channel: Direct Sales, Retail Suppliers, Online Marketplaces, Distributors End User: Contractors, Architects, Builders, Homeowners |
| Companies Covered | USG Corporation, Hacker Industries, Inc., MAXXON, INC., Accu-Crete, ACG Materials, ARDEX Group, Janes Gypsum Floors Inc., Formglas Products Ltd, MAPEI SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum Concrete Market Strategic Shifts
Formulation chemistry and installation mechanization are compressing project timelines while expanding gypsum concrete's addressable substrate range beyond traditional wood-framed assemblies.
Lightweight gypsum systems incorporating pre-foamed gypsum or expanded mineral aggregates are unifying structural efficiency with acoustic performance in a single pour. Mid-rise developers in seismic zones specify these formulations to reduce mass without sacrificing STC ratings. The technology is unifying previously separate trades—structural, acoustic, and fireproofing—into consolidated underlayment specifications.
The EPA's ongoing stationary source emissions standards constrain calcination plant siting and expansion, tightening regional supply availability. Manufacturers respond by optimizing kiln efficiency and exploring synthetic gypsum feedstocks from flue gas desulfurization. Western US markets face the tightest compliance timelines, accelerating consolidation among producers with permitted capacity.
General contractors increasingly bundle underlayment scope with framing and MEP rough-in, compressing traditional subcontractor tiers. This consolidated procurement model displaces standalone flooring contractors on commercial projects over 50,000 square feet. The shift is most visible in hospitality and senior housing verticals where speed-to-certificate-of-occupancy drives incentive structures.
Gypsum Concrete Market Segmentation
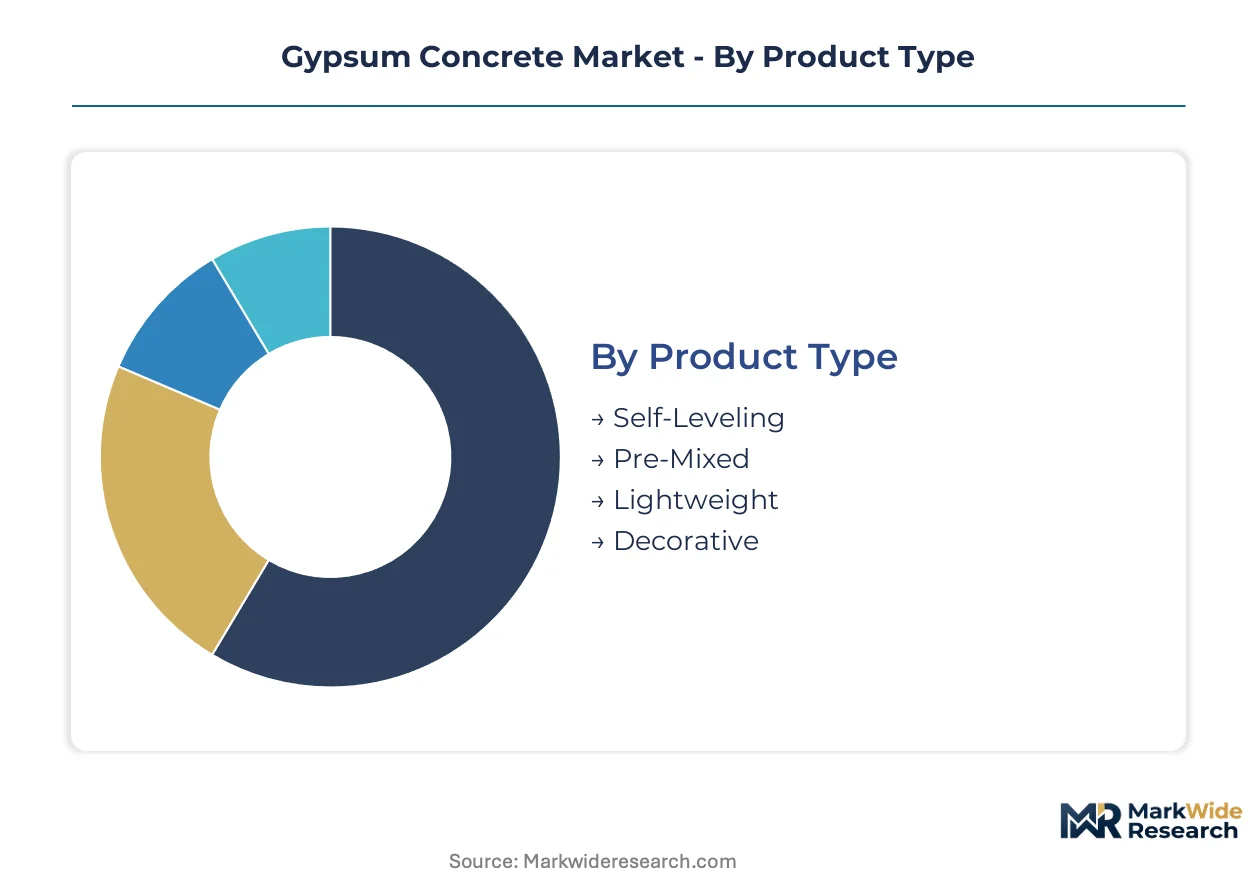
Gypsum concrete specification flows diverge sharply across project scales and procurement sophistication. Product chemistry, application environment, and channel economics each create distinct margin pools and competitive dynamics that suppliers must navigate simultaneously.
Product Type:
Buyers differentiate primarily by labor cost sensitivity versus structural performance requirements.
- Self-Leveling:Flowable formulations achieve surface flatness tolerances of 1/8 inch over 10 feet without mechanical screeding. Demand concentrates in hospitality and healthcare renovation across the United States, where compressed construction schedules reward pumping automation that eliminates skilled finishing crews.
- Lightweight:Expanded polystyrene or mineral aggregate additives reduce densities below 100 pounds per cubic foot while maintaining compressive strengths above 2,000 psi. Mid-rise Type III construction in seismic zones specifies these systems to cut structural dead loads without sacrificing fire ratings or acoustic performance.
- Pre-Mixed:Factory-blended bags ensure consistent water-to-gypsum ratios for small-scale residential retrofits where on-site batching quality varies.
- Decorative:Pigmented and polished surface finishes serve architectural exposed-floor applications in retail and gallery spaces.
Self-leveling formulations lead volumes today; lightweight systems are gaining share fastest.
Application:
Project scale and occupancy type reshape specification priorities across end-use environments.
- Commercial Buildings:Office, hospitality, and institutional projects specify gypsum concrete for fire-rated assemblies and STC-rated floor systems. Demand clusters in urban renovation corridors where acoustic lease-up premiums justify material cost differentials over cement-based alternatives.
- Residential Properties:Multi-family wood-framed construction drives specification for sound attenuation between stacked units. Single-family retrofits favor gypsum underlayment for radiant floor heating compatibility and thermal mass distribution.
- Industrial Facilities:Manufacturing and warehouse applications remain limited by moisture sensitivity and point-load constraints that favor polymer-modified cement systems.
- Flooring:Dedicated underlayment applications span substrate preparation for resilient, carpet, and hardwood finishes across all building types.
Commercial buildings dominate revenue contribution; residential properties expand most quickly.
Distribution Channel:
Project size and specification complexity determine whether buyers value convenience or margin capture.
- Direct Sales:Large-format commercial projects above 50,000 square feet bypass distributor markups through specification-grade manufacturer relationships. General contractors bundle underlayment scope with framing and MEP rough-in, consolidating procurement tiers.
- Distributors:Regional building material wholesalers serve mid-tier commercial and multi-family developers with stocked inventory and technical support.
- Retail Suppliers:Big-box and specialty flooring retailers capture residential retrofit volume through contractor loyalty programs and same-day availability.
- Online Marketplaces:E-commerce platforms penetrate small-project and DIY segments with pre-mixed bag shipments and installation tutorial content.
Direct sales channels capture the highest margin pools; online marketplaces are expanding fastest.
End User:
Technical sophistication and liability exposure separate specification influencers from procurement executors.
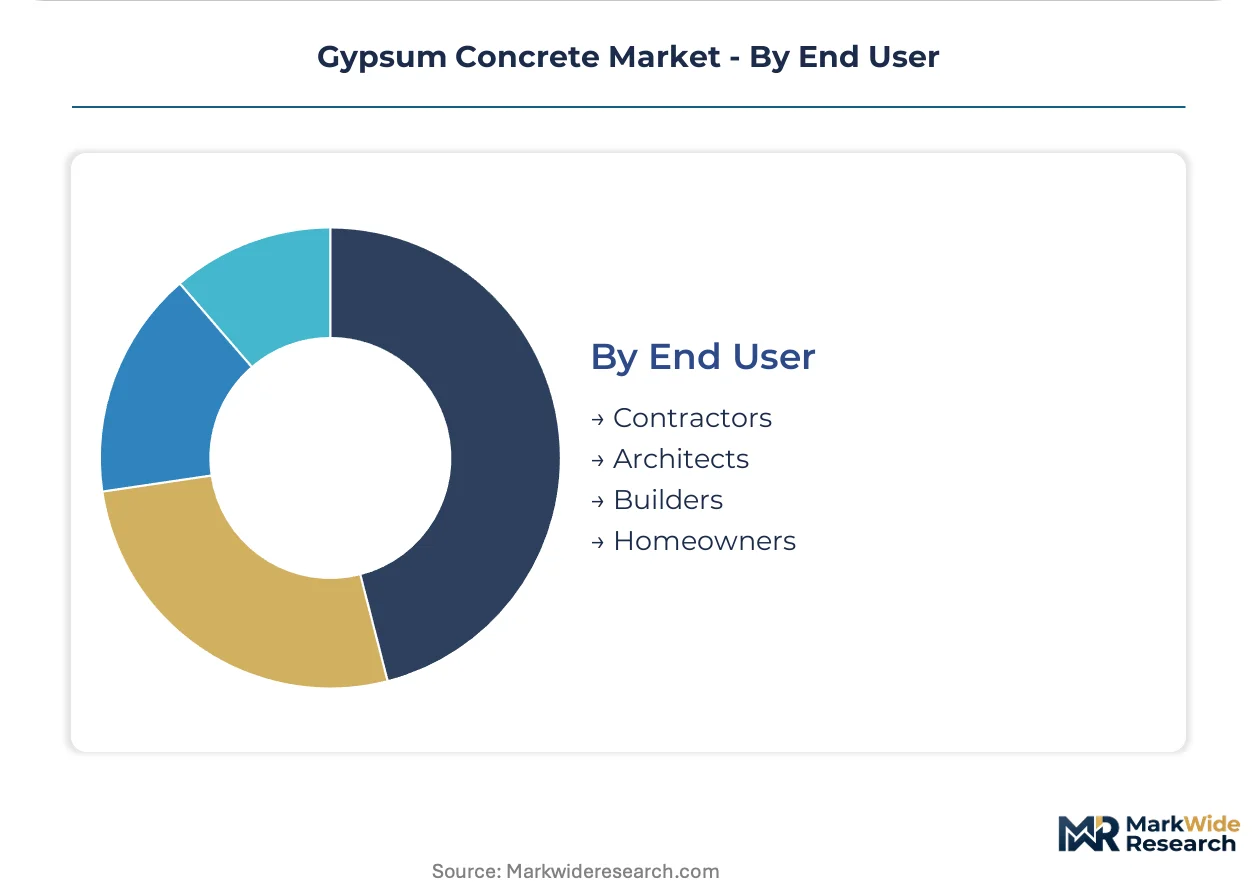
- Contractors:Flooring and general contracting firms control installation scope and material selection on renovation and tenant improvement projects. Their crews require ASTM C317 certification and fire-rated assembly documentation.
- Architects:Design professionals specify gypsum concrete for acoustic, fire, and sustainable design credits in institutional and multi-family work. Their drawings determine substrate preparation and thickness requirements.
- Builders:Production homebuilders and commercial developers prioritize speed-to-occupancy and warranty risk management in material selection.
- Homeowners:End consumers influence retrofit decisions through contractor selection and finish material preferences, rarely specifying gypsum concrete directly.
Contractors drive procurement volume; architects steer specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates gypsum concrete specification flows through multi-family housing construction corridors and commercial renovation cycles concentrated in Texas, Florida, and California metropolitan areas.
United States
Multi-family housing starts in Dallas-Fort Worth and Miami-Dade County drive specification volume for sound-attenuated floor assemblies. EPA stationary source emissions standards constrain calcination plant siting in Western states, tightening regional supply availability. Production clusters concentrate along the I-35 corridor from Oklahoma through Texas where captive gypsum reserves support integrated manufacturing.
Germany
Mass timber construction adoption in Bavaria and Baden-Württemberg creates adjacent demand for gypsum underlayment compatible with CLT floor decks. REACH chemical safety regulations govern additive formulations in self-leveling compounds, elevating compliance costs for imported products. Industrial clusters around Leipzig and Dresden host specialized applicator training centers serving Central European renovation markets.
China
Urban renewal projects in Shanghai and Beijing specify fire-rated assemblies for high-rise residential retrofits. MIIT building materials standards establish compressive strength minimums that domestic producers must satisfy for public procurement eligibility. Manufacturing gravity centers on Shandong Province where flue gas desulfurization gypsum feedstocks support synthetic plaster production at scale.
Canada
Radiant floor heating installations in Toronto and Vancouver single-family retrofits favor gypsum concrete for thermal mass distribution. Health Canada indoor air quality guidelines influence low-emission formulation preferences in institutional specifications. Quebec's construction material recycling mandates accelerate synthetic gypsum utilization in Montreal-area production facilities.
United Kingdom
Cross-laminated timber office developments in London and Manchester require compatible underlayment systems for fire-resistance ratings. Building Regulations Part E acoustic performance standards mandate minimum impact sound reduction in multi-family construction. Industrial concentration in the East Midlands supplies flowable formulations to Southeast England renovation corridors.
Gypsum Concrete Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to regional supply constraints and specification shifts toward lightweight formulations. The vendor base separates into integrated reserve-holders, specialized acoustic formulators, and regional applicator networks. Three archetypes define competitive positioning: captive gypsum producers with backward integration into mining, formulation specialists engineering STC-rated systems, and installation-service bundlers consolidating subcontractor tiers. M&A activity concentrates on regional distributors with specification-grade relationships, while technology licensing agreements spread self-leveling automation across mid-tier contractors.
Among North American integrated producers, USG Corporation anchors the reserve-backed tier through captive mineral holdings and board-to-pour manufacturing integration. Hacker Industries, Inc. occupies the acoustic specialization vector with formulations targeting multi-family and hospitality verticals. MAXXON, INC. exemplifies the lightweight systems archetype, reducing structural dead loads for mid-rise Type III construction specifications. These three entities represent distinct competitive positions rather than overlapping market contests.
| Leading Market Players |
|---|
| USG Corporation |
| Hacker Industries, Inc. |
| MAXXON, INC. |
| Accu-Crete |
| ACG Materials |
| ARDEX Group |
| Janes Gypsum Floors Inc. |
| Formglas Products Ltd |
| MAPEI SpA |
| Others |
Value Chain & Pricing Dynamics
Certified gypsum concrete applicator pools concentrate in Texas, Oklahoma, and California, where labor-cost differentials between union and non-union crews drive pricing-tier spreads across specification-grade and retrofit segments.
Pricing Analysis
Natural gas cost pass-through dominates gypsum plaster production economics, compressing margins when fuel prices spike and forcing selective price adjustments across product tiers. Pricing stratifies across premium STC-rated acoustic systems, standard self-leveling formulations, and economy-grade pre-mixed bags, with differentiation anchored in fire-resistance certification level and volume scale. Pricing pressure stems from Portland cement underlayment competition in cost-sensitive renovation segments. Single-family residential retrofits exhibit highest price sensitivity, while hospitality developers prioritize speed-to-occupancy over material cost differentials.
Supply Chain Analysis
Gypsum feedstock supply rests on captive mineral reserves in the United States, synthetic flue gas desulfurization output in China, and natural gypsum extraction in Germany and Canada. Key inputs span calcined gypsum plaster, expanded polystyrene aggregate for lightweight variants, and specialty additives for flow control and set retardation. Single-source vulnerability concentrates around I-35 corridor production facilities serving Western US markets beyond 500-mile freight radii. Distribution runs through specification-grade direct sales for large commercial projects, regional building material wholesalers for mid-tier developers, and retail channels for residential retrofit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by developer prioritization of STC-rated acoustic assemblies in dense urban multi-family construction.
For Market Incumbents: Cement reserve-backed cost leadership through captive gypsum mining integration in Oklahoma and Texas production corridors. Invest in ASTM C317 certification programs to address applicator workforce bottlenecks constraining specification capacity. Counter polymer-modified cement substitution threats in below-grade segments by developing moisture-resistant formulation extensions.
For New Entrants and Emerging Players: E-commerce platform routes into residential retrofit segments bypass entrenched distributor relationships and capture DIY-adjacent contractor loyalty. Target single-family radiant floor heating retrofits in Toronto and Vancouver corridors where thermal mass specifications favor gypsum compatibility. Pursue white-label partnerships with mass timber engineering firms seeking bundled underlayment procurement for CLT floor deck projects.
For Investors and Strategic Acquirers: Regional distributors with specification-grade relationships to hospitality and senior housing developers are the most active acquirer category in this space. Five-to-ten year viability hinges on embodied carbon regulatory tailwinds sustaining gypsum concrete's procurement advantage over Portland cement alternatives. Acquisition target archetype: lightweight formulation specialists with EPS-aggregate IP and mid-rise Type III construction specification track records. Monitor EPA stationary source permit issuance timelines as inflection indicator for regional supply availability constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gypsum Mining | Captive mineral reserves in Texas and Oklahoma insulate USG Corporation from feedstock cost volatility. |
| Lightweight Formulation R&D Expansion | EPS-aggregate systems reduce structural dead loads for seismic-zone Type III construction specifications. |
| Direct Sales Channel Penetration | Bypassing distributor markups captures margin pools on hospitality projects exceeding 50,000 square feet. |
| Applicator Certification Program Investment | ASTM C317-trained crews address workforce bottlenecks constraining specification-grade installation capacity. |
| Synthetic Gypsum Feedstock Transition | Flue gas desulfurization sourcing mitigates EPA stationary source constraints on calcination plant expansion. |
Study Parameters
Coverage spans the United States, Germany, China, Canada, and the United Kingdom, with primary inputs from each market informing demand and supply dynamics. The research combines structured interviews with gypsum concrete plant managers, multi-family developer procurement leads, acoustic engineering consultants, and general contractor superintendents with secondary validation from EPA emissions filings, ASTM standards documentation, and building permit databases. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts.
Granularity-level modeling disaggregates volume and value outputs across product type, application environment, distribution channel, and end-user sophistication tier. Self-leveling, lightweight, pre-mixed, and decorative formulations each carry distinct labor-cost and performance-assumption profiles. CAGRs derive from regression analysis of historical construction starts correlated with specification penetration rates. Industry-specific inputs include multi-family housing permit data, mass timber project development pipelines, and embodied carbon procurement guideline adoption curves.
The model assumes a particular technology adoption path; alternative pathways for moisture-resistant gypsum chemistry or polymer-hybrid systems would alter the outlook for below-grade application expansion. Forecasts reflect assumptions about EPA regulatory enforcement continuity, natural gas price stability, and mass timber construction penetration rates. A small set of triggers—calcination plant permit denials, Portland cement carbon intensity breakthroughs, and CLT structural code amendments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Quarry Tiles Market