
 East Africa White Cement Market | 2026-2036
East Africa White Cement Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa White Cement Market Intelligence
Kenya's National Construction Authority performance grading for contractors is shifting procurement toward certified white cement for landmark facades and public buildings. Mombasa Cement Limited leverages its coastal clinker access to sustain export flexibility across the Indian Ocean rim. Bamburi Cement anchors supply security through its integrated Mombasa operations. Dangote Cement Plc competes on scale economics from its Tanzania grinding assets.
East Africa white cement is a high-purity calcium aluminate clinker product fired below iron-oxide thresholds to achieve reflectance values exceeding 80 percent, serving architectural finishing and decorative concrete where aesthetic uniformity matters. Ultra-White product grade commands premium positioning due to limited regional kiln capacity capable of maintaining the requisite low-iron chemistry. Infrastructure application leads volume offtake as government contractors specify white cement for visually exposed structural elements in transport hubs and civic buildings. Direct Sales channel dominates project-based procurement while Wholesale retains importance for mid-size construction firms lacking bulk storage.
Kenya's National Environment Management Authority, Tanzania's Vice President's Office for Environment, and Ethiopia's Environmental Protection Authority each enforce emissions thresholds that constrain kiln retrofit economics and filter market entrants by capital intensity. Product standards harmonization under the East African Community Technical Committee for cement specifications is tightening quality verification protocols at border points. Stakeholders must monitor clinker import duty adjustments and carbon border deliberations that could restructure cost competitiveness between integrated and grinding-only operations.
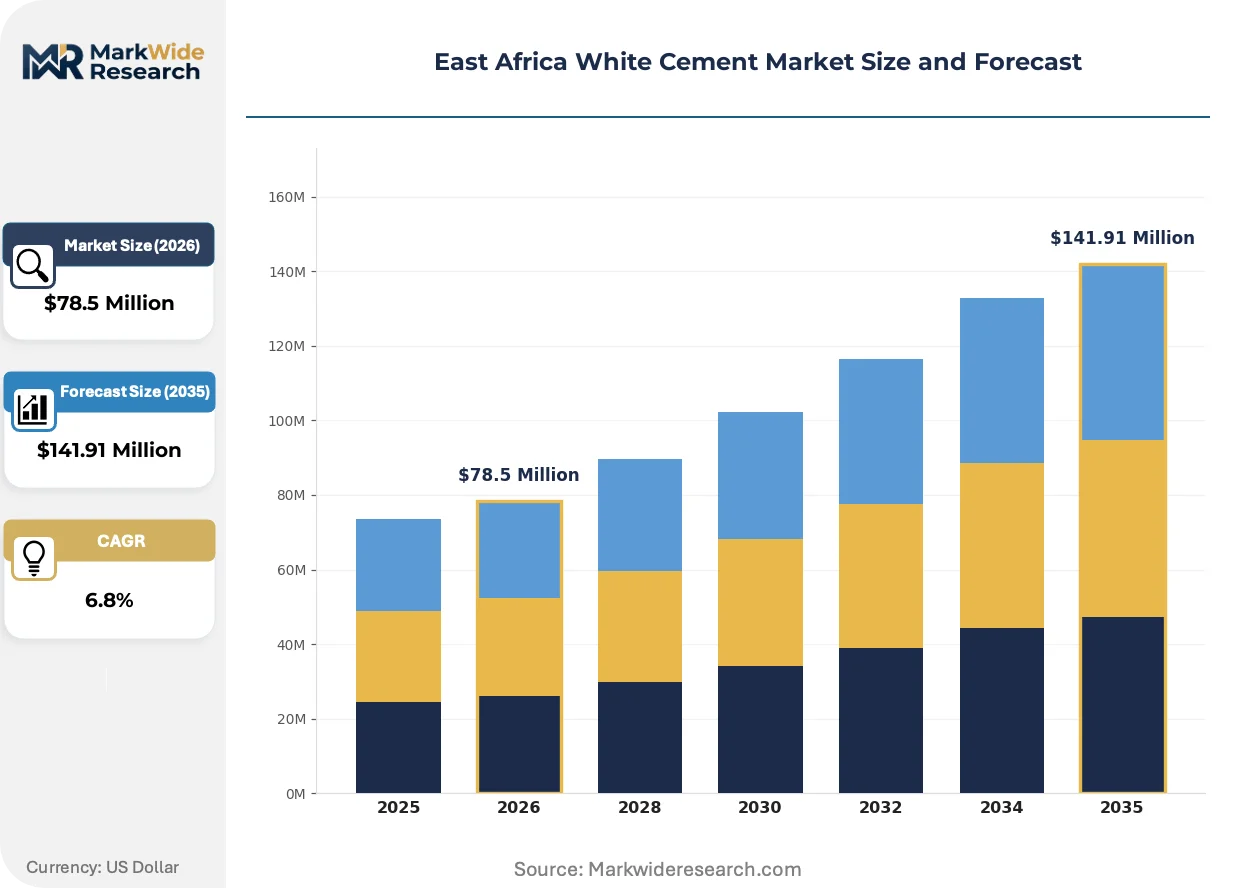
Market Dynamics
Kenya's National Construction Authority performance grading is redirecting contractor procurement toward certified white cement for landmark facades, compressing informal supply channels and elevating specification discipline across the region.
Growth Catalysts
- Kenya's infrastructure build-out:Road and bridge contractors are lifting bulk procurement volumes for visually exposed structural elements in transport hubs.
- Ethiopia's updated building code:Mandates for higher-grade binders in public structures are accelerating specification upgrades for government buildings.
- Tanzania's commercial corridor:Construction activity linking Dar es Salaam to Dodoma is concentrating demand in mid-size commercial developments.
Market Restraints
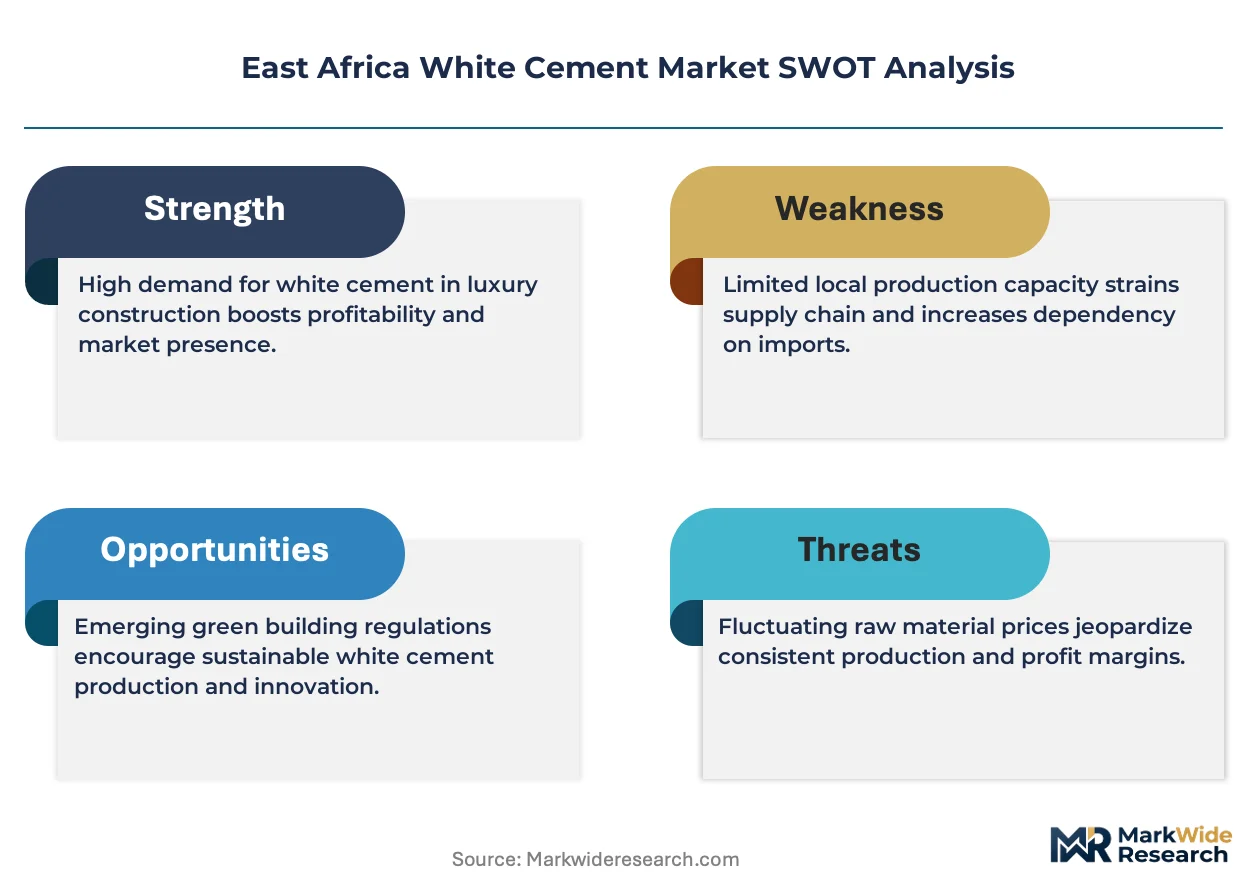
- Low-iron clinker scarcity:Limited regional kiln capacity capable of maintaining requisite chemistry constraints supply elasticity and inflates input costs.
- Emissions threshold compliance:Kenya's National Environment Management Authority, Tanzania's Vice President's Office for Environment, and Ethiopia's Environmental Protection Authority each enforce constraints that filter market entrants by capital intensity.
- Import duty exposure:Clinker import duty adjustments under East African Community protocols create margin volatility for grinding-only operations.
Strategic Opportunities
- Product standards harmonization:East African Community Technical Committee for cement specifications is tightening quality verification protocols, creating first-mover advantage for certified producers.
- Carbon border deliberations:Emerging frameworks could restructure cost competitiveness between integrated and grinding-only operations, favoring coastal clinker access.
- Ultra-White grade premiumization:Limited regional kiln capacity for high-purity calcium aluminate clinker creates pricing power for qualified producers.
Industry Challenges
- Certification timeline compression:National Construction Authority performance grading requires contractors to demonstrate material traceability, stretching documentation capabilities.
- Skilled applicator shortage:Decorative concrete finishing demands specialized craft knowledge that outpaces vocational training output in Kenya and Tanzania.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa White Cement Market |
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $141.91 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-mixed, Hydraulic, Ultra-White, Specialty End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Direct Sales, Wholesale, Retail, Online Application: Construction, Architectural, Decorative, Repair |
| Companies Covered | Mombasa Cement Limited, East African Portland Cement Company, Bamburi Cement, Savannah Cement, Dangote Cement Plc, Lafarge South Africa, PPC Ltd, Sephaku Cement, Ohorongo Cement, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa White Cement Market Strategic Shifts & Innovations
Specification digitization and clinker chemistry control systems are reconfiguring how white cement quality is verified and procured across East African project sites.
Advanced spectroscopic analysis for iron-oxide detection is overtaking traditional wet chemistry methods in quality assurance protocols. Large infrastructure contractors in Kenya are adopting inline monitoring systems to verify batch consistency before site delivery. This technology compression is enabling real-time certification that satisfies National Construction Authority grading requirements without laboratory delays.
East African Community Technical Committee harmonization is tightening border-point quality verification protocols for cross-border cement shipments. Industrial consequence includes elevated documentation burdens for grinding operations sourcing clinker from multiple origins. Tanzania-based suppliers are responding by consolidating toward single-source coastal clinker to streamline customs clearance.
Direct project-based procurement is displacing traditional wholesale channels for bulk white cement offtake. Mid-size construction firms lacking storage infrastructure are aggregating purchasing through contractor consortiums rather than independent distributors. This channel restructuring is most visible in Kenya's public building segment where National Construction Authority grading concentrates buying power among certified contractor pools.
East Africa White Cement Market Segmentation
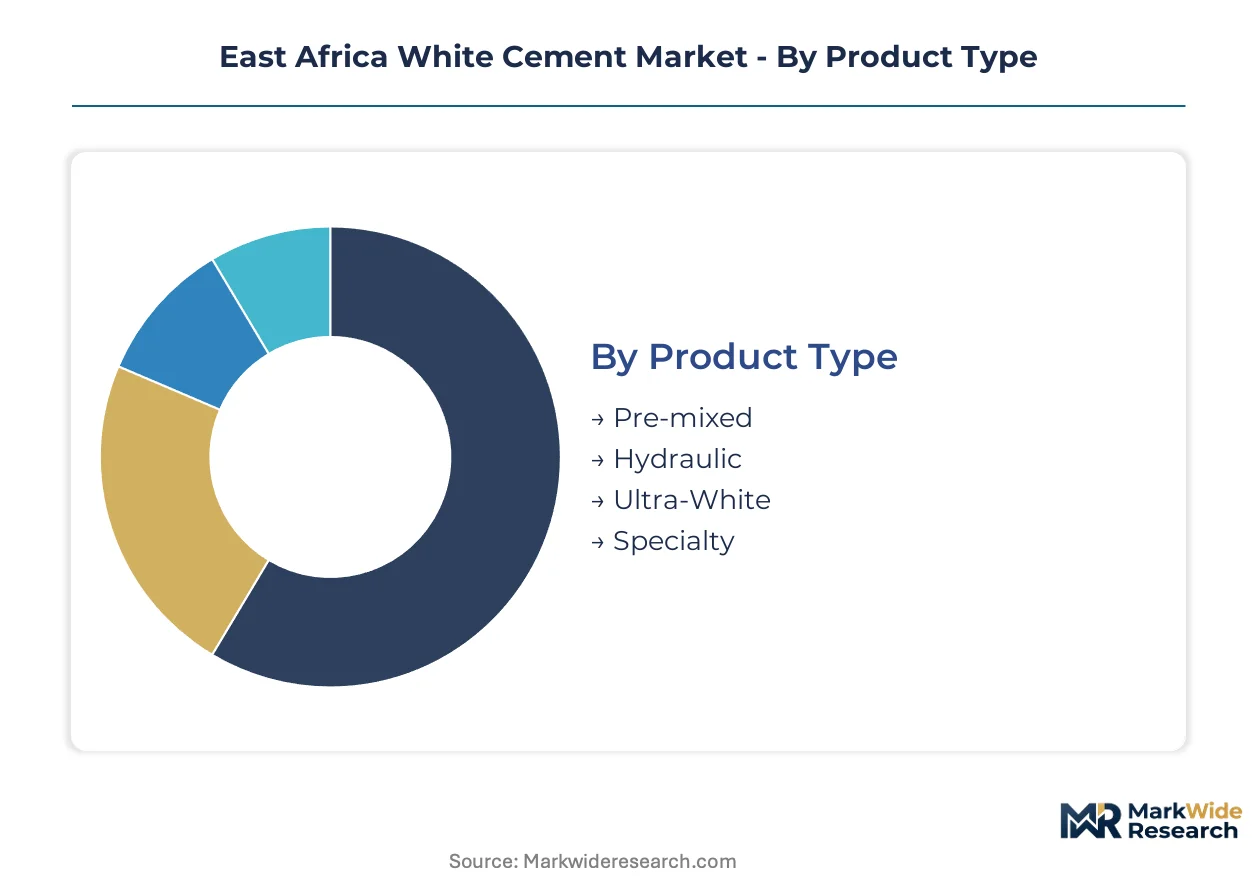
East Africa's white cement market fragments across technical grades, buyer sophistication, and project scale. Specification discipline from Kenya's National Construction Authority and Tanzania's commercial corridor development are reshaping how segments interact and which capture margin.
Product Type:
Buyer selection hinges on reflectance thresholds and iron-oxide chemistry tolerances for exposed architectural elements.
- Ultra-White:Fired below stringent iron-oxide thresholds to exceed 80 percent reflectance. Demand concentrates in Kenya's landmark facade contracts where National Construction Authority grading mandates certified material traceability.
- Hydraulic:Standard white Portland chemistry with controlled C3A content for structural applications. Tanzania's Dar es Salaam-Dodoma commercial corridor drives bulk procurement for visually exposed transport infrastructure.
- Pre-mixed:Factory-blended formulations with polymer modifiers for decorative finishing. Mid-size Kenyan contractors favor bagged convenience over site mixing.
- Specialty:Custom calcium aluminate blends for repair mortars and heritage restoration. Ethiopian public building codes are accelerating specification for higher-grade binders in historic structure rehabilitation.
Volume sits with Hydraulic; growth tilts toward Ultra-White.
End User:
Project ownership structure determines procurement channel access and certification burden tolerance.
- Infrastructure:Government contractors dominate bulk offtake for transport hubs and civic buildings. Kenya's road and bridge build-out lifts procurement volumes through direct sales channels.
- Commercial:Mid-size developments along Tanzania's commercial corridor concentrate demand for standard grades. Developer consolidation is compressing informal supply relationships.
- Residential:Individual homeowners and small builders drive retail fragmentation. Ethiopian urban expansion is expanding the addressable base for decorative finishing.
- Industrial:Manufacturing facility construction and maintenance represents niche specification. Food processing plants require high-purity flooring systems.
Procurement scale peaks with Infrastructure; margin capture favors Commercial.
Distribution Channel:
Storage infrastructure ownership separates channel participants and determines landed cost structures.
- Direct Sales:Project-based bulk procurement from certified contractor pools. Kenya's National Construction Authority grading concentrates buying power among performance-graded firms.
- Wholesale:Regional distributors serving mid-size construction firms lacking silo capacity. Tanzania's corridor geography rewards consolidated coastal clinker sourcing.
- Retail:Bagged product through construction material yards. Ethiopian building code enforcement is elevating documentation requirements at this channel.
- Online:Emerging platform aggregation for small-lot specification comparison. Kenya's digitization of contractor certification is enabling remote verification.
Channel share concentrates in Direct Sales; Online is climbing fastest.
Application:
Surface exposure visibility dictates chemistry purity requirements and applicator skill thresholds.
- Construction:Structural elements with aesthetic exposure in transport hubs and civic buildings. Kenya's infrastructure build-out specifies white cement for visually prominent concrete.
- Architectural:Precast facade panels and cladding systems demanding batch uniformity. Tanzania's commercial corridor developments favor unitized panel systems.
- Decorative:Stamped concrete, terrazzo, and exposed aggregate finishing. Skilled applicator shortage in Kenya and Tanzania constrains segment expansion.
- Repair:Heritage restoration and structural rehabilitation mortars. Ethiopia's updated building code mandates higher-grade binders for public structure maintenance.
Volume anchors in Construction; Decorative is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dar es Salaam anchors East African white cement demand through its port infrastructure and corridor linkages to Dodoma, the administrative capital under construction. Coastal clinker access determines supply security across the Indian Ocean rim. National construction authorities in Kenya, Ethiopia, and Tanzania are tightening specification protocols that reshape procurement geography.
Kenya
Road and bridge contractors in Nairobi and Mombasa are lifting bulk procurement volumes for visually exposed structural elements. The National Construction Authority performance grading mandates certified material traceability for landmark facades. Mombasa Cement Limited leverages its coastal clinker position to sustain export flexibility across the Indian Ocean rim.
Ethiopia
Public building construction in Addis Ababa is accelerating specification upgrades for higher-grade binders. The updated national building code mandates premium white cement for government structures and historic rehabilitation. Industrial activity concentrates around the capital corridor where cement demand is outpacing domestic kiln capacity.
Tanzania
Commercial development linking Dar es Salaam to Dodoma is concentrating mid-size construction demand. Dangote Cement Plc competes on scale economics from its domestic grinding assets positioned along this corridor. The Vice President's Office for Environment enforces emissions thresholds that constrain new kiln investments.
Uganda
Infrastructure rehabilitation around Kampala is expanding the addressable base for decorative finishing applications. The country's national environment regulator applies emissions constraints that filter grinding-only entrants by capital intensity. Cross-border procurement from Kenyan suppliers dominates given limited domestic white cement production.
Rwanda
Public building construction in Kigali is specifying white cement for civic architecture and transport hub aesthetics. Regional trade protocols under the East African Community enable clinker import flows that supplement domestic supply gaps. Quality verification at border points is tightening under harmonized product standards.
East Africa White Cement Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification grade and coastal clinker access. The market structures around integrated manufacturers with captive kiln capacity and grinding specialists dependent on imported clinker. Three archetypes dominate: coastal integrated producers, inland grinding operations, and regional trading specialists. Competitive moves concentrate on single-source clinker consolidation and certification documentation automation.
Among Kenya-based integrated producers, Mombasa Cement Limited and Bamburi Cement occupy positions defined by coastal clinker access and export flexibility. Dangote Cement Plc represents the scale-driven grinding specialist archetype with Tanzania-based assets. East African Portland Cement Company and Savannah Cement exemplify mid-tier competitors navigating specification digitization requirements. Sephaku Cement and Ohorongo Cement anchor southern African supply positions with potential northward expansion exposure.
| Leading Market Players |
|---|
| Mombasa Cement Limited |
| East African Portland Cement Company |
| Bamburi Cement |
| Savannah Cement |
| Dangote Cement Plc |
| Lafarge South Africa |
| PPC Ltd |
| Sephaku Cement |
| Ohorongo Cement |
| Others |
Cost & Logistics Intelligence
Family-owned coastal producers with captive clinker kilns command pricing discipline that grinding-only competitors cannot match, while sovereign-backed infrastructure procurement concentrates buyer power around certification-traceable supply pools. Kenya's National Construction Authority grading requirements and Tanzania's Vice President's Office emissions enforcement together compress margin elasticity for entrants lacking integrated coastal assets.
Pricing Analysis
Reflectance-based value anchoring ties Ultra-White grade premiums to batch-verified aesthetic outcomes in landmark facade contracts. Three-tier pricing structure across premium, standard, and economy levels separates certified Ultra-White from Hydraulic grades and unbranded commodity alternatives. Price differentiation rests on National Construction Authority certification tier and coastal clinker access rather than brand alone. Cost compression in economy-grade grinding operations is intensifying because clinker import duty volatility under East African Community protocols erodes margin buffers. Mid-size Tanzanian contractors exhibit highest price sensitivity due to silo storage constraints, while Kenyan infrastructure primes accept certified-premium pricing for traceability compliance.
Supply Chain Analysis
Single-source vulnerability sits with Indian Ocean coastal clinker access concentrated in Kenya and Tanzania, where Mombasa and Dar es Salaam port infrastructure determines regional supply security. Low-iron limestone and high-purity kaolin clay feed from select Kenyan coastal quarries and Ethiopian highland deposits. Tariff exposure on cross-border clinker movements under East African Community customs protocols threatens grinding-only operations in Rwanda and Uganda. Distribution runs through direct project-based procurement for certified contractor pools, with wholesale channels serving silo-constrained mid-tier builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa white cement functions as a cost-of-compliance market where Kenya's National Construction Authority performance grading erects capital-intensive barriers that protect incumbent positions. Regulatory enforcement of material traceability creates a sustainable moat for certified producers against informal supply channels.
For Market Incumbents: Anchor coastal clinker security through long-term quarry lease negotiations and kiln retrofit investments that satisfy Tanzania's Vice President's Office emissions thresholds. Threat from Ethiopian grinding-only entrants with duty-advantaged clinker access demands preemptive certification documentation automation. Backward integration into captive low-iron limestone quarries secures chemistry control for Ultra-White grade production.
For New Entrants and Emerging Players: Begin with decorative finishing applicator training partnerships in Rwanda and Uganda, where skilled craft shortages constrain segment expansion and first-mover certification builds contractor loyalty. Most penetrable white-space sits with mid-size commercial developments along Tanzania's Dar es Salaam-Dodoma corridor lacking direct sales channel access. Go-to-market angle centers on bagged Pre-mixed convenience for consortium-aggregated procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor coastal grinding assets with single-source clinker relationships in Kenya, where carbon border deliberations may restructure cost competitiveness against inland competitors. Long-term viability over a multi-year horizon rests on regulatory compliance infrastructure rather than commodity scale. Signal to watch: East African Community Technical Committee harmonization enforcement intensity at border verification points.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Iron Quarry Assets | Captive chemistry control secures Ultra-White grade eligibility under Kenya's National Construction Authority protocols. |
| Certification Documentation Automation | Real-time batch traceability satisfies contractor grading requirements without laboratory verification delays. |
| Single-Source Clinker Consolidation | Streamlined customs clearance under East African Community harmonization reduces margin volatility for grinding operations. |
| Applicator Training Consortium Formation | Vocational pipeline investment in Kenya and Tanzania addresses skilled craft shortages constraining decorative segment expansion. |
| Coastal Export Infrastructure Expansion | Mombasa and Dar es Salaam port access enables Indian Ocean rim market penetration beyond domestic demand saturation. |
Research Approach
Trade statistics from Kenya Revenue Authority, Tanzania Revenue Authority, and Ethiopian Customs Commission formed the secondary backbone, supplemented by East African Community tariff schedules and National Environment Management Authority emissions filings. Primary interviews with cement plant operations managers, National Construction Authority certification officers, infrastructure procurement leads at Kenyan road contractors, and Dar es Salaam-Dodoma corridor project developers validated supply-demand balances. Bottom-up clinker capacity modeling and top-down construction spend allocation triangulated volume estimates.
Bottom-up segment sizing across product type, end user, distribution channel, and application dimensions fed into top-down macro constraint checks from infrastructure budget disclosures. CAGRs were derived from trend extrapolation of contractor certification growth and commercial corridor completion schedules, with cross-validation against clinker import duty elasticity assumptions. Forecast inputs incorporated National Construction Authority grading rollout pace and Ethiopia's building code enforcement intensity.
Underlying measurement precision varies by segment; Infrastructure and Direct Sales carry tighter precision than Residential and Online channels where data fragmentation persists. Forecasts embed assumptions regarding East African Community harmonization timeline and carbon border mechanism adoption that could materially revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Germany Aluminum Door and Window Market
Building Materials
North America Architectural Coatings Market
Building Materials
East Africa Cement Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Brick Adhesive Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
France Architectural Coatings Market
Building Materials
Foam Bricks Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Pozzolana Cement Market
Building Materials
Exterior Doors Market
Building Materials
Cement Tiles Market
Building Materials
Dutch Brick Market