
 Italy Architectural Coatings Market | 2026-2036
Italy Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Architectural Coatings Market Foresight
Buyer fragmentation across Italy's small-scale contractor base is repositioning distribution power toward regional building-material chains with direct jobsite logistics. AkzoNobel N.V. leverages its decorative coatings portfolio to dominate specification channels in northern commercial projects. San Marco Group anchors its position through Venetian plaster heritage and color-matching services for restoration work. ICA SpA specializes in wood coatings for Italy's furniture manufacturing clusters, sustaining export-linked volume through captive technical support.
Architectural coatings encompass pigmented liquid or powder systems formulated with binders, solvents or water carriers, and functional additives that cure to protective and decorative films on building substrates, typically specified at dry-film thicknesses of 25–150 microns for durability and aesthetic performance. Exterior Paints command the largest volume share given Italy's heritage building stock requiring cyclical maintenance against Mediterranean UV and salt exposure. Water-based formulations are displacing solvent-based alternatives fastest as contractors adapt to tightened VOC limits on jobsites. Acrylic binders lead residential interior specification for color retention and low-odor application in occupied renovations.
Italy's Ministry of Environment enforces EU REACH and F-Gas Regulation transpositions that restrict hazardous substance content and mandate eco-label compliance for public procurement eligibility. The National Institute for Insurance against Accidents at Work (INAIL) influences jobsite safety standards that affect application methods and contractor training requirements. Stakeholders must monitor how upcoming EU Green Deal building-renovation mandates reshape specification criteria for embodied carbon and circular material content in public tenders.
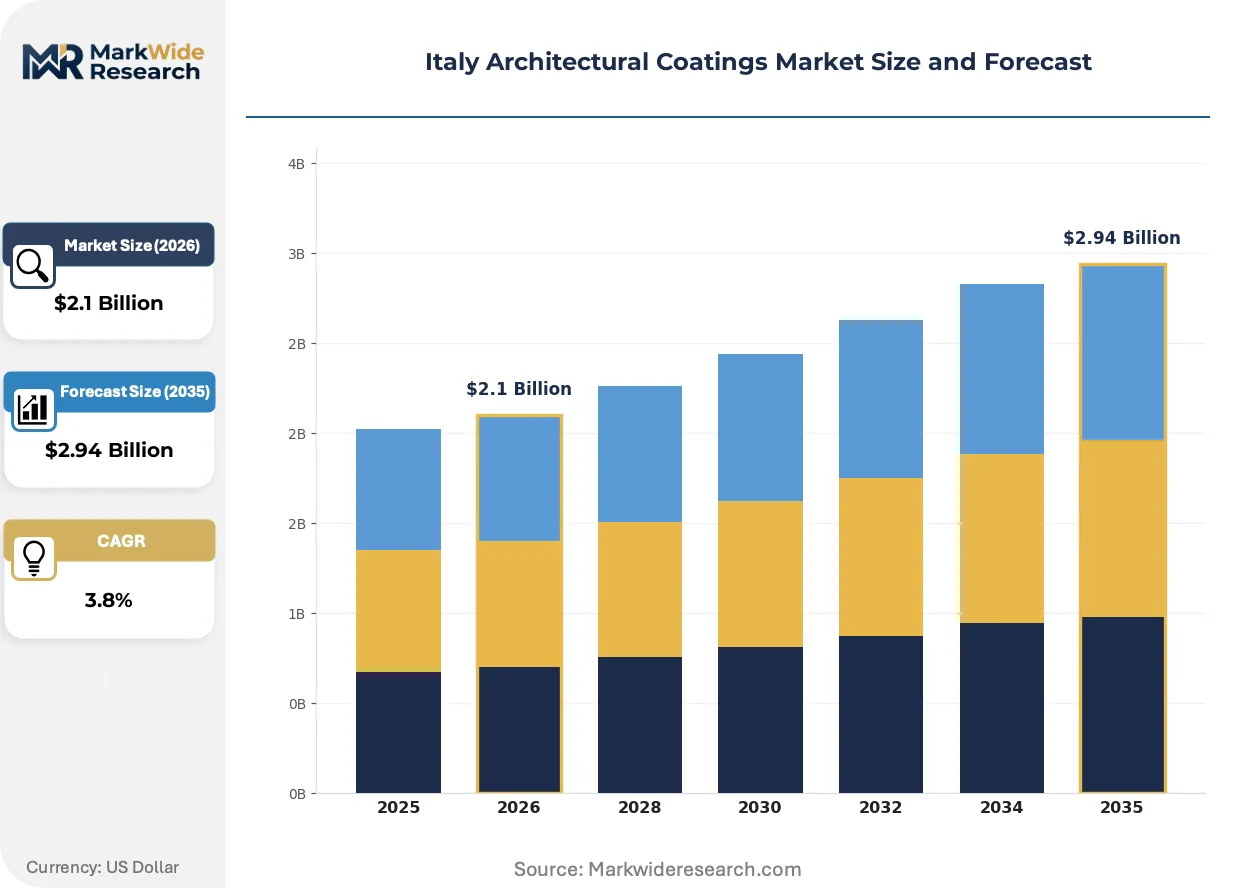
Market Dynamics
EU REACH transposition on VOC content is forcing wholesale formulation migration across Italy's contractor base, compressing solvent-based product lifecycles and redistributing supply chain leverage toward water-based resin suppliers with compliant portfolios.
Growth Catalysts
- EU Green Deal building-renovation mandates:Public procurement eligibility now ties to embodied carbon thresholds, pulling specification-grade volume toward low-VOC and bio-based alternatives in Milan and Turin commercial pipelines.
- Heritage restoration clusters:Venetian plaster and lime-based specialty demand concentrates in Veneto and Tuscany, where conservation-grade color-matching services command premium positioning.
- Acrylic binder technology maturation:Improved scrub resistance and low-odor profiles in occupied residential renovations are displacing alkyd alternatives in Lombardy's high-end apartment sector.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin predictability for mid-tier decorative producers without backward integration into mineral sourcing.
- Solvent-based legacy infrastructure:Northern Italy's installed production assets face stranded risk as water-based capacity expansion requires capital redeployment.
- REACH registration burdens:Small-scale formulators confront compliance cost barriers that favor larger competitors with dedicated regulatory affairs functions.
Strategic Opportunities
- Sicily and Calabria underpenetration:Southern residential markets lack specification-grade distribution density, creating whitespace for regional building-material chains with direct logistics investment.
- Photocatalytic exterior coatings:Titanium dioxide-activated self-cleaning formulations align with urban air-quality mandates in Rome and Naples municipal procurement.
- Digital color-matching kiosks:Retail channel innovation in hardware-store networks reduces contractor specification friction for custom heritage restoration projects.
Industry Challenges
- Applicator skill stratification:Water-based formulation handling demands retraining Italy's aging plasterer workforce, stretching INAIL-mandated certification timelines.
- Multi-substrate specification complexity:Historic buildings combining stone, brick, and render require layered compatibility testing that extends project approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Architectural Coatings Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior Paints, Interior Paints, Wood Coatings, Spray Paints Formulation: Acrylics, Alkyds, Water-based, Solvent-based Application: Residential, Commercial, Industrial, Institutional End User: Contractors, Homeowners, Architects, Designers |
| Companies Covered | AkzoNobel N.V., PPG Industries Inc., The Sherwin-Williams Company, Jotun, ICA SpA, San Marco Group, Brillux GmbH & Co. KG, DAW SE, Nippon Paint Holdings Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Architectural Coatings Market Shifts & Advancements
Formulation chemistry and distribution logistics are converging to reshape how coatings reach Italy's fragmented contractor base, with digital tools and regulatory compliance acting as the primary vectors of change.
Photocatalytic titanium dioxide surface treatments are electrifying exterior specification channels by enabling self-cleaning and NOx-reducing functionality on urban building envelopes. Municipal procurement offices in Rome and Milan are specifying these systems for public facade restoration at accelerating rates. The technology is compressing maintenance-cycle economics for heritage structures exposed to Mediterranean pollution loads.
Italy's Ministry of Environment enforcement of EU F-Gas Regulation transpositions is restricting fluorinated solvent content in specialty coatings formulations. Industrial consequence includes accelerated R&D spend on hydrofluoroether alternatives among wood-coating suppliers serving furniture export clusters. The furniture manufacturing vertical around Brianza is most affected, with ICA SpA and comparable specialists reformulating export-compliant portfolios.
Specification behavior among Lombardy commercial contractors is fragmenting across direct-from-manufacturer digital portals and traditional distributor relationships. Regional building-material chains with integrated color-lab services are capturing share from independent paint retailers. This rotation is most visible in Milan's high-rise residential pipeline, where architects specify through chain-affiliated specification consultants rather than standalone decor outlets.
Italy Architectural Coatings Market Segmentation
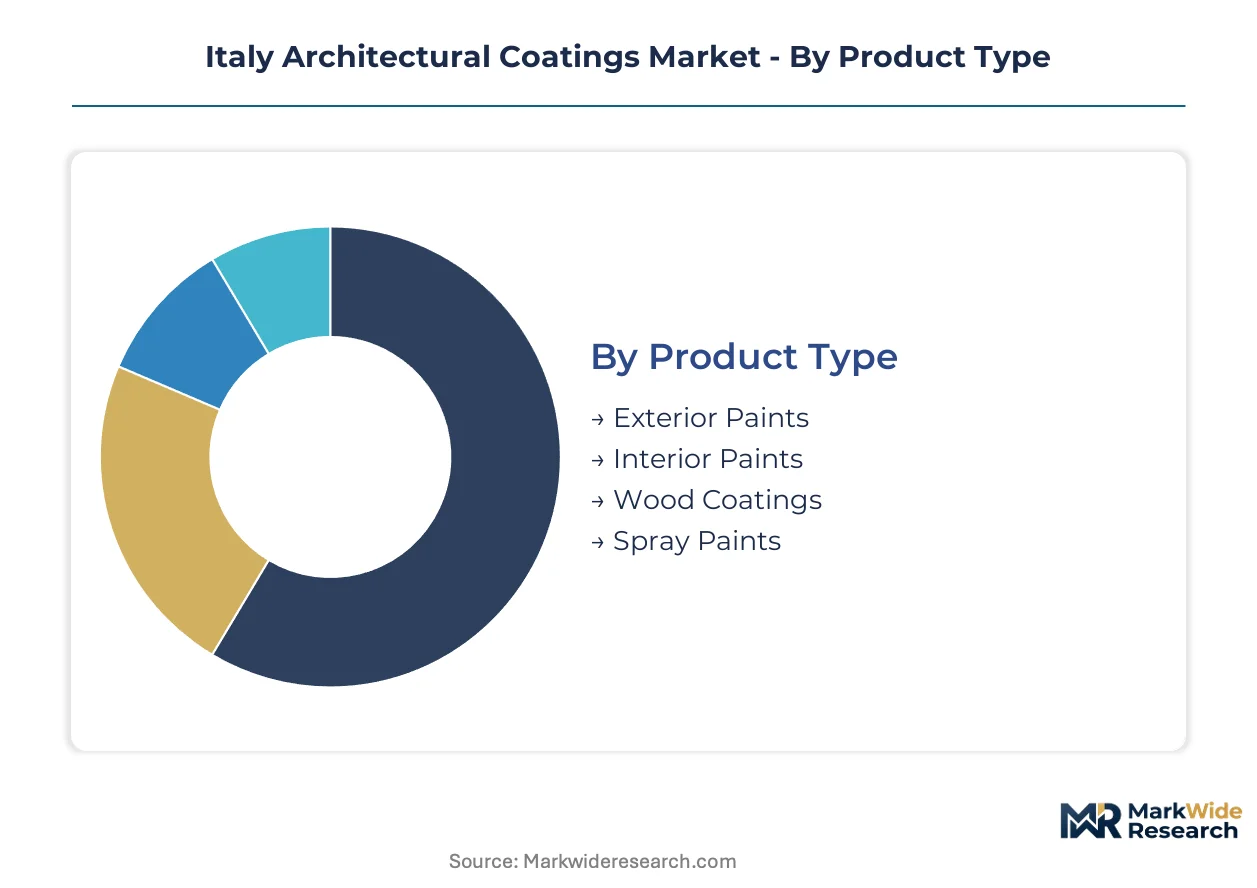
Segmentation in Italy's architectural coatings market reveals how regulatory pressure and application complexity split procurement behavior. Specification-grade projects in Lombardy demand entirely different formulation portfolios than cost-sensitive residential renovation in southern regions.
Product Type:
Technology maturity and substrate compatibility define competitive positioning across product categories.
- Exterior Paints:Formulated with UV-resistant binders and titanium dioxide pigments to withstand Mediterranean salt and solar degradation. Demand concentrates in Lombardy's commercial pipeline and Venice's lagoon-facing heritage structures where cyclical maintenance cycles drive recurring volume.
- Interior Paints:Low-VOC acrylic systems dominate specification for occupied renovations in Milan's high-end residential sector. Scrub resistance and color retention properties command premium positioning among contractors serving design-conscious homeowners.
- Wood Coatings:Penetrating oils and film-forming varnishes protect Italy's furniture manufacturing clusters around Brianza. ICA SpA and comparable specialists anchor technical support for export-compliant formulations.
- Spray Paints:Aerosol formats serve touch-up applications and artistic restoration work. Limited volume but critical for color-matched heritage repair in Tuscany and Veneto conservation zones.
Exterior Paints leads on scale; Interior Paints leads on momentum.
Formulation:
Regulatory transposition of EU REACH VOC limits is redistributing supply chain leverage across chemistry types.
- Acrylics:Water-dispersible polymer systems offering rapid dry times and low odor profiles. Milan's residential renovation contractors specify these for occupied apartment projects where alkyd solvent odors are prohibitive.
- Alkyds:Oil-modified polyester resins retain share in exterior trim and metal applications requiring hardness and gloss retention. Solvent-based variants face declining shelf space as REACH compliance costs escalate.
- Water-based:Emulsion technologies now dominate new product development pipelines across AkzoNobel and San Marco Group portfolios. INAIL-mandated jobsite safety standards accelerate contractor conversion away from flammable solvent systems.
- Solvent-based:Legacy nitrocellulose and urethane formulations cling to specialty wood finishing and industrial maintenance. Northern Italy's installed production assets confront stranded capacity risk as public procurement eligibility tightens.
Water-based leads on momentum; Acrylics leads on specification density.
Application:
Project scale and procurement channel fragmentation create divergent margin profiles across end-use segments.
- Residential:Single-family and multi-unit renovation drives volume through regional building-material chains. Color-matching services and direct jobsite logistics determine contractor loyalty in fragmented demand.
- Commercial:Office and retail specification in Milan and Turin pulls premium-grade volume through architect-led procurement. EU Green Deal embodied carbon thresholds now filter tender eligibility.
- Industrial:Manufacturing facility maintenance requires chemical-resistant epoxy and polyurethane systems. Lower margin but higher volume consistency through facility management contracts.
- Institutional:School, hospital, and public building tenders mandate eco-label compliance and extended durability warranties. Procurement offices in Rome and Naples specify photocatalytic exterior systems for air-quality co-benefits.
Residential leads on volume; Commercial leads on value capture.
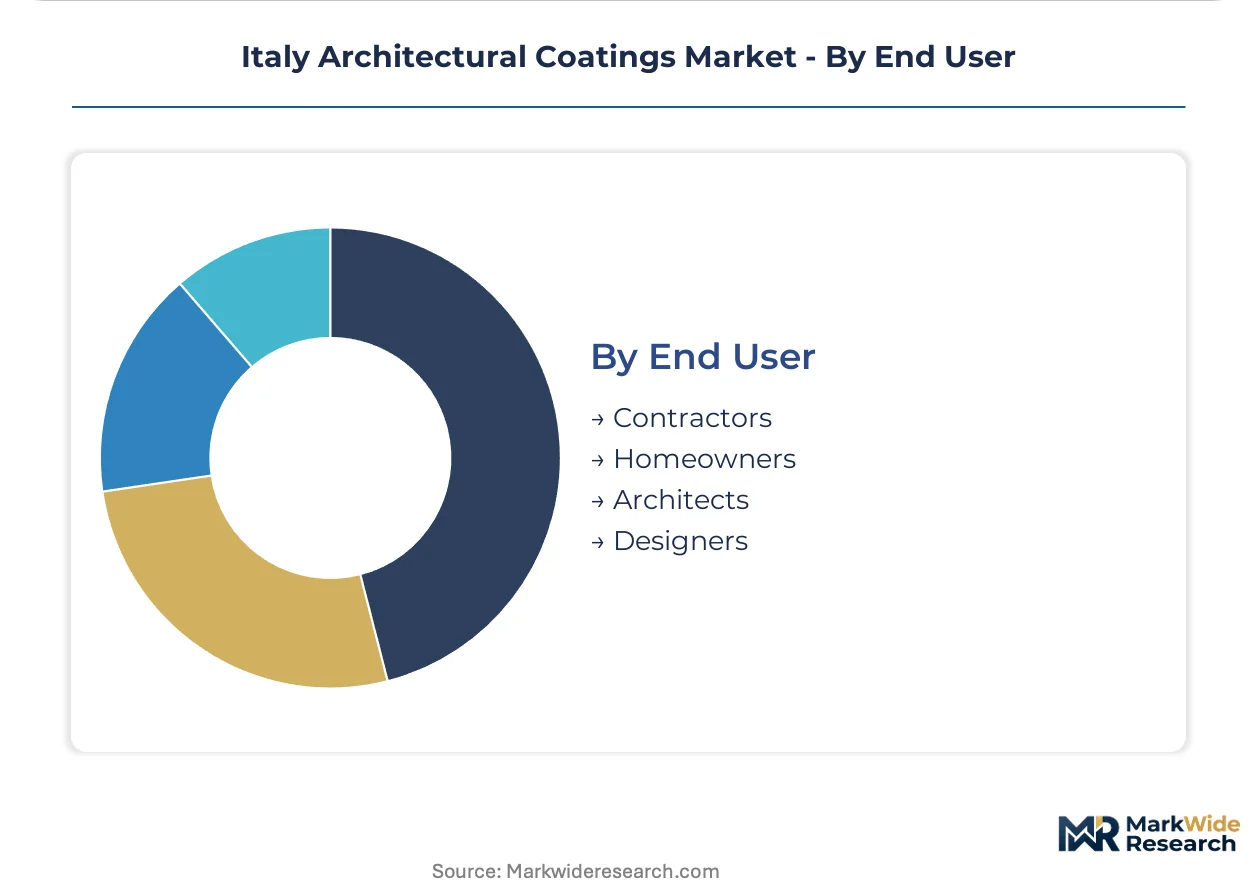
End User:
Decision authority and technical sophistication stratify the buyer base across specification influence tiers.
- Contractors:Small-scale plastering and painting crews dominate volume procurement through trade distributors. INAIL certification requirements and water-based retraining needs reshape workforce composition.
- Homeowners:Retail channel selection driven by color visualization tools and heritage restoration guidance. Digital kiosks in hardware networks reduce specification friction for custom projects.
- Architects:Specification-grade influence concentrated in Lombardy commercial and high-end residential pipelines. Sustainability criteria and circular material content increasingly filter product selection.
- Designers:Venetian plaster and lime-based specialty demand in Veneto and Tuscany conservation clusters. Premium positioning through color-matching expertise and artisan applicator networks.
Contractors leads on transaction volume; Architects leads on specification value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's skilled plasterer workforce concentrates in Lombardy and Veneto, anchoring specification-grade application capacity for heritage restoration and high-end residential finishing across the peninsula.
Lombardy
Milan's construction pipeline drives premium interior coatings demand through architect-led procurement channels. INAIL certification requirements for water-based application training reshape contractor workforce composition in the metropolitan area. The Brianza furniture manufacturing cluster sustains specialized wood coatings volume through export-linked technical support services.
Veneto
Venetian plaster heritage anchors conservation-grade color-matching demand across restoration projects in Venice and Verona. EU REACH VOC transpositions accelerate lime-based specialty formulation adoption among artisan applicator networks. The regional building-material chain density concentrates specification influence in Padua and Treviso procurement corridors.
Piedmont
Turin's commercial renovation pipeline pulls low-VOC and bio-based alternatives through Green Deal-mandated public tenders. The Ministry of Environment enforcement of eco-label compliance filters municipal procurement eligibility. Industrial coatings demand clusters around automotive supplier facilities in the metropolitan periphery.
Tuscany
Florence and Siena heritage restoration zones command premium positioning for lime-based breathable systems on historic stone and render substrates. Regional conservation regulations mandate compatibility testing that extends project approval cycles. Artisan plasterer networks in Chianti and Val d'Orcia sustain traditional application technique transmission.
Lazio
Rome's municipal procurement offices specify photocatalytic exterior systems for urban air-quality co-benefits on public facade restoration. The concentration of institutional tenders drives extended durability warranty requirements. Suburban residential development in the metropolitan periphery channels volume through regional distributor networks with direct jobsite logistics.
Italy Architectural Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's architectural coatings market, producing a tiered structure where multinational resin portfolios confront heritage-rooted regional formulators. The vendor base stratifies across specification-grade premium positions, mid-tier trade distribution, and cost-driven private-label supply. Three archetypes dominate: water-based technology leaders, Venetian plaster heritage specialists, and wood coatings technical service providers. Competitive moves concentrate on water-based capacity expansion and regional distribution partnerships with direct logistics integration.
Among Dutch-origin diversified chemical conglomerates, AkzoNobel N.V. occupies a position exemplifying specification-channel dominance in northern commercial projects. San Marco Group represents the Venetian plaster heritage archetype, anchoring regional color-matching expertise for conservation work. ICA SpA sits within the wood coatings specialization tier, sustaining export-linked volume through captive technical support presence in furniture manufacturing clusters.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| Jotun |
| ICA SpA |
| San Marco Group |
| Brillux GmbH & Co. KG |
| DAW SE |
| Nippon Paint Holdings Co. Ltd. |
| Others |
Supply & Pricing Matrix
Backward integration into titanium dioxide sourcing anchors margin predictability for specification-grade producers serving Lombardy's architect-led procurement channels, while mid-tier decorative suppliers without captive mineral feedstock confront compressed pricing power amid pigment cost volatility.
Pricing Analysis
Capacity additions in water-based resin production across northern Italy are reshaping price floors for compliant formulations as solvent-based alternatives face REACH-driven shelf-space reduction. Three-tier pricing structure across specification-grade, trade-standard, and private-label economy levels stratifies the market, with certification tier and volume scale as the primary differentiation drivers. Pricing pressure stems from titanium dioxide feedstock swings that compress margins for non-integrated formulators. Small-scale contractors in southern regions exhibit highest price sensitivity, whereas Milan commercial architects prioritize performance warranties over unit cost.
Supply Chain Analysis
Italy's National Recovery and Resilience Plan domestic-content provisions are reshaping sourcing patterns for public procurement eligibility, tilting specification-grade volume toward EU-sourced resin and additive suppliers. The supply chain draws from Germany for acrylic polymer feedstock, Belgium for specialty additives, and domestic Lombardy production for water-based emulsion capacity. Single-source vulnerability concentrates in titanium dioxide pigment supply from a limited producer base. Distribution runs through regional building-material chains with integrated color-lab services and direct jobsite logistics, displacing independent paint retailers in high-value specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based formulation conversion costs are declining as scale economies mature, opening margin expansion for producers who capture premium-tier positioning in Milan's Green Deal-mandated commercial pipeline.
For Market Incumbents: Anchor specification influence through captive color-matching infrastructure and architect-affiliated specification consultant relationships, defending against emerging water-based specialists with leaner cost structures. Prioritize backward integration into titanium dioxide sourcing to buffer pigment volatility and sustain margin predictability in decorative coatings. For New Entrants and Emerging Players: Capture whitespace in Sicily and Calabria residential markets where specification-grade distribution density remains underdeveloped, leveraging direct logistics investment to outflank incumbent reliance on fragmented trade distributors. Lead with digital color-matching kiosks in hardware-store networks to reduce contractor specification friction. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration burdens and water-based capacity redeployment costs strain small-scale formulators without dedicated regulatory affairs functions. Target mid-tier regional producers with established artisan applicator networks in Veneto and Tuscany heritage restoration clusters. Watch for inflection when EU Green Deal embodied carbon thresholds tighten tender eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Capacity Expansion | REACH compliance and INAIL safety standards accelerate solvent-to-water conversion in Lombardy production assets. |
| Backward Integration into Pigment Supply | Titanium dioxide cost volatility rewards captive mineral sourcing for margin-stable decorative coatings production. |
| Digital Color-Matching Infrastructure | Hardware-store kiosk networks reduce contractor specification friction in fragmented southern residential markets. |
| Heritage Restoration Specialist Acquisition | Venetian plaster expertise and artisan applicator networks command premium positioning in conservation-grade procurement. |
| Direct Logistics Partnership | Regional building-material chains with jobsite delivery capture share from independent paint retailers in Milan high-rise pipeline. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with coating formulators, procurement leads at regional building-material chains, architect specification consultants, and INAIL certification officers with secondary validation against EU REACH regulatory filings, Italian Ministry of Environment enforcement bulletins, and customs trade data for resin and pigment imports. Bottom-up volume estimates from product-category shipments triangulated against top-down construction activity indices.
Segment-weighted modeling applied formulation type, application end-use, and regional procurement channel as the primary stratification dimensions across the analysis window. CAGRs derived from trend extrapolation of water-based adoption curves, heritage restoration project pipelines, and Green Deal procurement mandate implementation timelines. Forecast inputs included contractor workforce composition shifts and municipal photocatalytic specification uptake rates.
Titanium dioxide supply disruptions, EU Green Deal threshold acceleration, and INAIL certification backlog extensions are the dominant revision risks that could compress or extend projected value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Shotcrete Market
Building Materials
Global Metal Cladding Market
Building Materials
Mass Timber Construction Market
Building Materials
Fireproof Cladding Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Concrete Admixtures Market
Building Materials
Engineered Wood Product Market
Building Materials
North America Cement Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Refractory Cement Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
US Facade Market
Building Materials
Roof Cover Boards Market