
 East Africa Wall Putty Market | 2026-2036
East Africa Wall Putty Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Wall Putty Market Intelligence
Kenya's cement and coatings manufacturing base is reconfiguring supply dynamics across East Africa. UltraTech Cement Ltd. anchors its regional position through integrated clinker-to-putty production near Mombasa. Sika AG leverages its construction chemicals portfolio to compete in high-performance exterior putty segments. Asian Paints Ltd. extends distribution reach through wholesaler networks penetrating secondary cities in Tanzania and Uganda.
East Africa wall putty comprises a cement-based or acrylic filler compound applied to plastered surfaces before painting, typically formulated with white cement, polymers, and mineral fillers to achieve smoothness between 0.5mm and 3mm thickness. The material eliminates surface porosity, prevents paint flaking, and reduces finishing coats in residential and commercial buildings. Interior putty dominates current volume flows due to standardized housing specifications across Kenyan and Tanzanian urban developments, while exterior putty commands margin premiums where tropical rainfall resistance matters. The contractor end-user channel sustains bulk procurement patterns, though retail stores are capturing incremental DIY volumes in Nairobi and Dar es Salaam.
Kenya's KEBS, Tanzania's Tanzania Bureau of Standards, and Uganda's Uganda National Bureau of Standards enforce cement product standards that determine wall putty import eligibility and local manufacturing compliance. These frameworks shape formulation requirements, testing protocols, and cross-border trade documentation burdens for suppliers. Builders and contractors must monitor evolving national standards divergence as each country deepens local-content preferences in public construction procurement.
Market Dynamics
KEBS enforcement of cement-based building material specifications is compressing formulation flexibility and redrawing competitive boundaries across Kenya, Tanzania, and Uganda. This regulatory tightening is forcing suppliers to reconfigure product portfolios and local manufacturing footprints.
Growth Catalysts
- Urban housing stock expansion:Residential construction across Nairobi, Dar es Salaam, and Kampala is absorbing rising volumes of interior putty as middle-class housing developments multiply.
- KEBS compliance mandates:Kenya's Bureau of Standards specifications for cement-based materials are eliminating substandard imports and clearing shelf space for certified domestic production.
- Polymer-modified formulations:Acrylic-enhanced putty variants are penetrating exterior applications where tropical rainfall resistance commands sustained demand.
Market Restraints
- White cement input volatility:Regional dependence on clinker imports from the Middle East and Asia exposes margins to shipping cost fluctuations and currency depreciation.
- Supply concentration in Mombasa:Kenya's coastal manufacturing corridor controls bulk distribution logistics, creating bottleneck risks for landlocked Tanzania and Uganda.
- Substitution by skim coats:Gypsum-based finishing compounds are capturing price-sensitive interior segments in Kenyan mass housing projects.
Strategic Opportunities
- Uganda's secondary city buildout:Jinja and Mbarara construction corridors remain underpenetrated by organized putty distribution, favoring early wholesale network establishment.
- DIY retail channel emergence:Nairobi and Dar es Salaam hardware stores are capturing incremental homeowner volumes previously served exclusively by contractor procurement.
- Tanzania Bureau of Standards alignment:Harmonization with Kenyan specifications would streamline cross-border formulation approvals and reduce compliance duplication costs.
Industry Challenges
- Skilled applicator scarcity:Consistent surface preparation and putty application technique remains uneven across informal construction labor pools in all three markets.
- Multi-jurisdiction certification timelines:Divergent testing protocols between KEBS, TBS, and UNBS are extending product launch cycles for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Wall Putty Market |
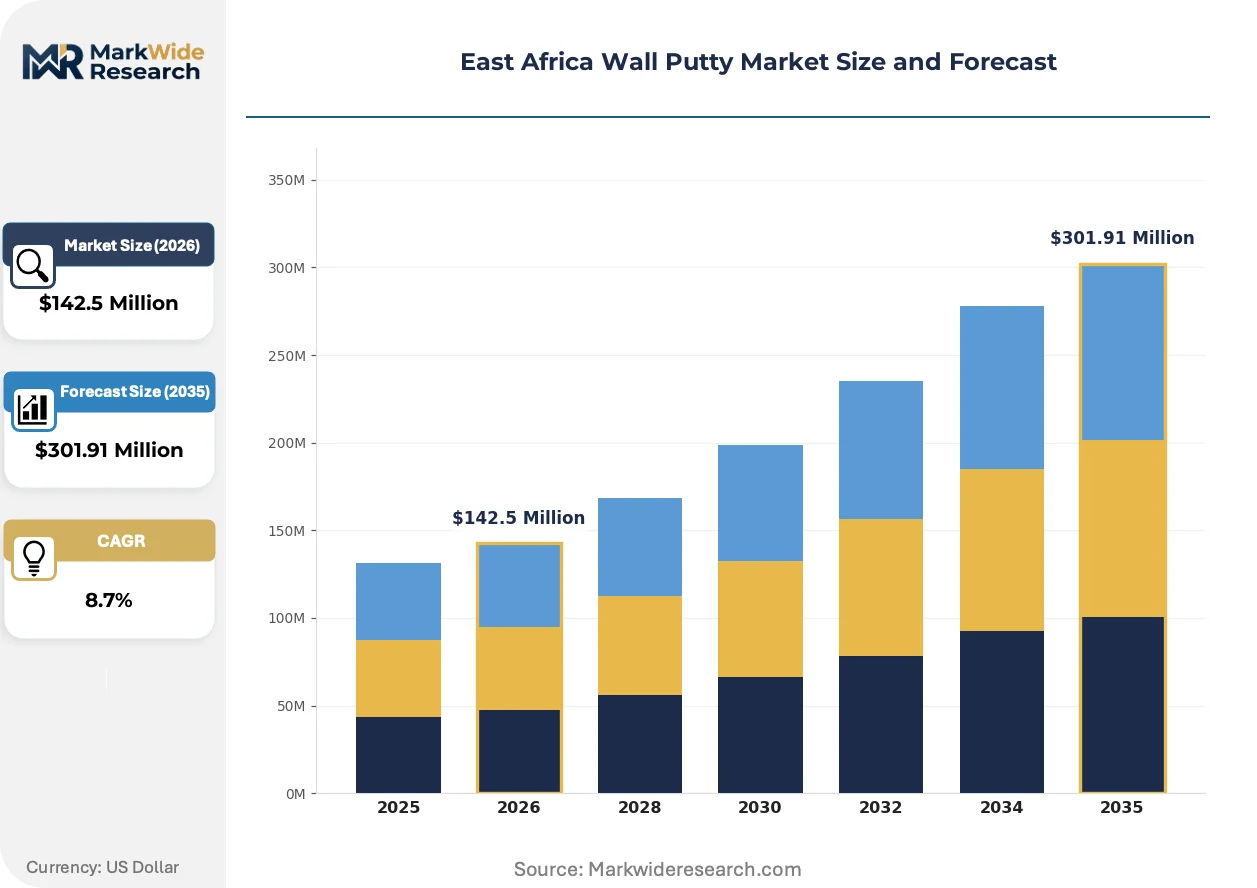
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Putty, Exterior Putty, Textured Putty, Priming Putty Application: Residential, Commercial, Institutional, Industrial Distribution Channel: Direct Sales, Wholesalers, Retail Stores, Online Channels End User: Contractors, DIY Enthusiasts, Architects, Builders |
| Companies Covered | Nippon Paint India Pvt. Ltd., UltraTech Cement Ltd., Asian Paints Ltd., Walplast Products Pvt. Ltd., Akzo Nobel NV, Berger Paints India Ltd., Sika AG, Pidilite Industries Limited, JK Cement Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Wall Putty Market Strategic Shifts & Innovations
Formulation chemistry and procurement patterns are diverging as climate resilience requirements intensify and buyer sophistication matures across East African construction markets.
Polymer-modified cement putty is collapsing the performance gap between traditional white cement formulations and premium acrylic systems. Nairobi commercial developers are specifying these hybrid products for high-rise exterior facades. The technology is collapsing the historical three-tier product architecture into a streamlined premium-standard segmentation.
KEBS cement product standards are tightening contaminant thresholds and mandating third-party laboratory verification for all imported putty consignments. This enforcement is elevating compliance costs for informal traders while accelerating formal distributor consolidation. Kenyan contractors are responding by consolidating procurement relationships with certified domestic manufacturers.
Builder purchasing patterns are fragmenting as project-scale contractors in Tanzania experiment with direct mill sourcing while smaller Kenyan residential developers retreat to retail hardware channels. Dar es Salaam's commercial construction segment is driving volume commitments to manufacturer-direct accounts. Uganda's market lags this bifurcation, with distributor intermediaries retaining dominant channel positions.
East Africa Wall Putty Market Segmentation
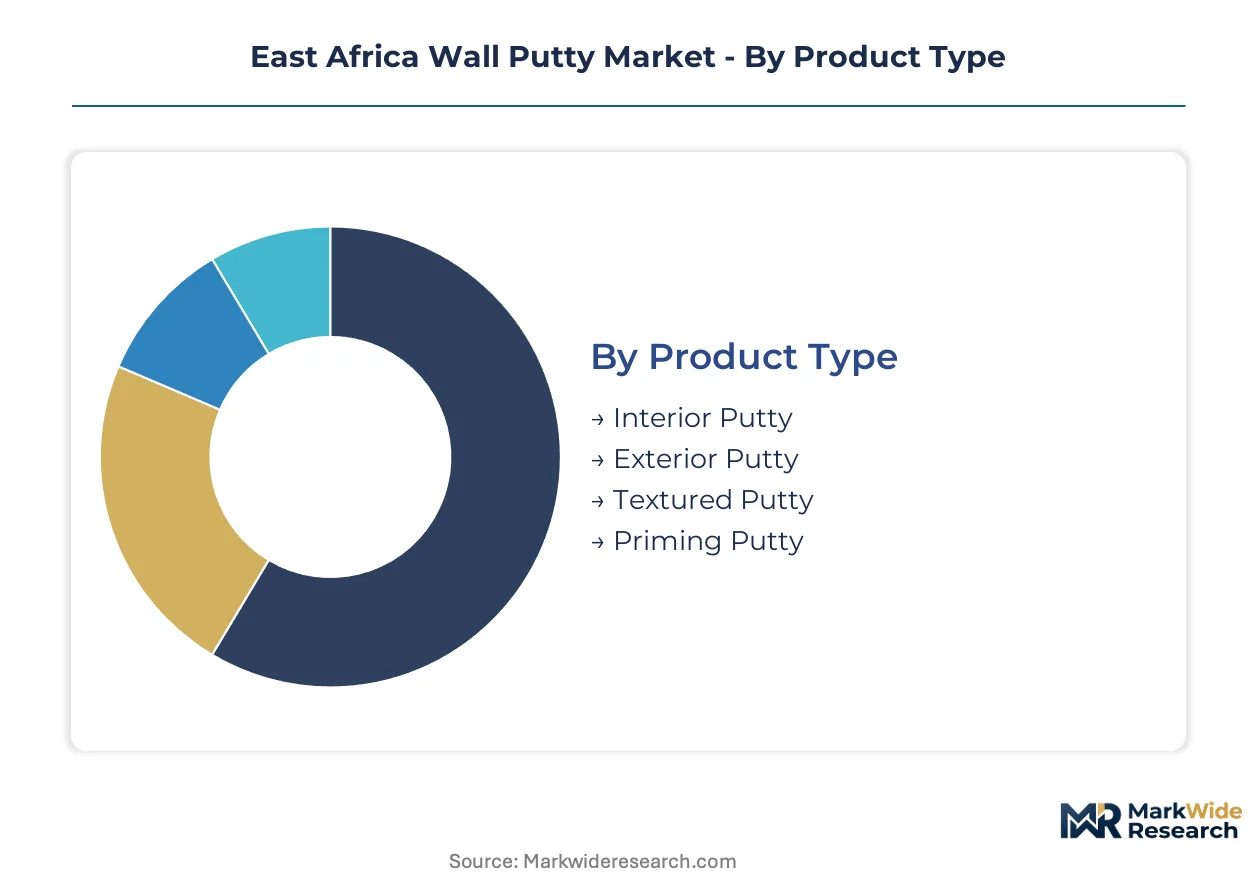
East Africa wall putty demand fragments across four structural dimensions that determine formulation chemistry, volume scale, and margin capture. Product type dictates raw material intensity and weather resistance specifications. Application and end-user profiles shape procurement channel preferences across Kenya, Tanzania, and Uganda.
Product Type:
Application environment and surface finish requirements separate these formulations by polymer loading, cement grade, and thickness tolerance.
- Interior Putty:White cement-based compounds with minimal polymer modification achieve 0.5mm to 1.5mm smoothness on plastered drywall and concrete. Nairobi and Dar es Salaam residential towers specify this grade for cost-efficient surface preparation before emulsion coating. Standardized housing developments across Kenyan urban corridors absorb bulk volumes through contractor procurement channels.
- Exterior Putty:Acrylic-modified or SBR latex-enhanced formulations withstand tropical rainfall, thermal cycling, and UV exposure on building facades. Coastal Mombasa commercial projects and high-rise Kampala developments specify these grades despite 40-60% cost premiums over interior alternatives.
- Textured Putty:Coarse mineral-aggregate blends create decorative surface finishes for feature walls and commercial lobbies.
- Priming Putty:Thin-coat sealant formulations reduce substrate porosity before final paint application in renovation projects.
Interior putty commands the established base. The steepest expansion runs through exterior putty as climate resilience specifications tighten across East African commercial construction.
Application:
Building typology determines putty consumption intensity per square meter and specification stringency.
- Residential:Single-family homes and multi-unit apartments in Nairobi's satellite towns and Dar es Salaam's Kinondoni district drive standardized interior putty volumes. Kenyan mortgage finance expansion and Tanzanian middle-class housing programs sustain this segment's scale dominance.
- Commercial:Office towers, retail complexes, and hospitality projects in Kampala's Nakasero corridor and Mombasa's Nyali business district specify premium exterior and textured putty grades. Developer procurement committees enforce KEBS and TBS certification requirements that filter informal suppliers.
- Institutional:Schools, hospitals, and government facilities in Uganda's secondary cities generate sporadic large-lot tenders.
- Industrial:Manufacturing plant finishing requirements remain marginal in current East African construction patterns.
Residential applications anchor volume flows. Commercial projects are climbing the fastest as foreign direct investment concentrates in Nairobi and Dar es Salaam office markets.
Distribution Channel:
Supply chain configuration determines price transparency, technical support access, and payment terms for different buyer scales.
- Direct Sales:Manufacturer-to-contractor relationships dominate large-scale commercial and residential developments in Kenya's Nairobi-Mombasa corridor. UltraTech Cement and Sika AG field technical teams support specification writing and batch consistency verification for projects exceeding 10,000 square meters.
- Wholesalers:Regional distributors with Mombasa warehousing and cross-border logistics capabilities serve Tanzanian and Ugandan contractors. These intermediaries aggregate fragmented demand from secondary cities including Arusha, Jinja, and Mbarara.
- Retail Stores:Nairobi and Dar es Salaam hardware stores capture homeowner DIY volumes and small renovation contractors.
- Online Channels:E-commerce penetration remains nascent for construction chemicals in East African markets.
Direct sales channels lock in the largest commercial projects. Retail store penetration is expanding most quickly as Nairobi's homeowner renovation market matures.
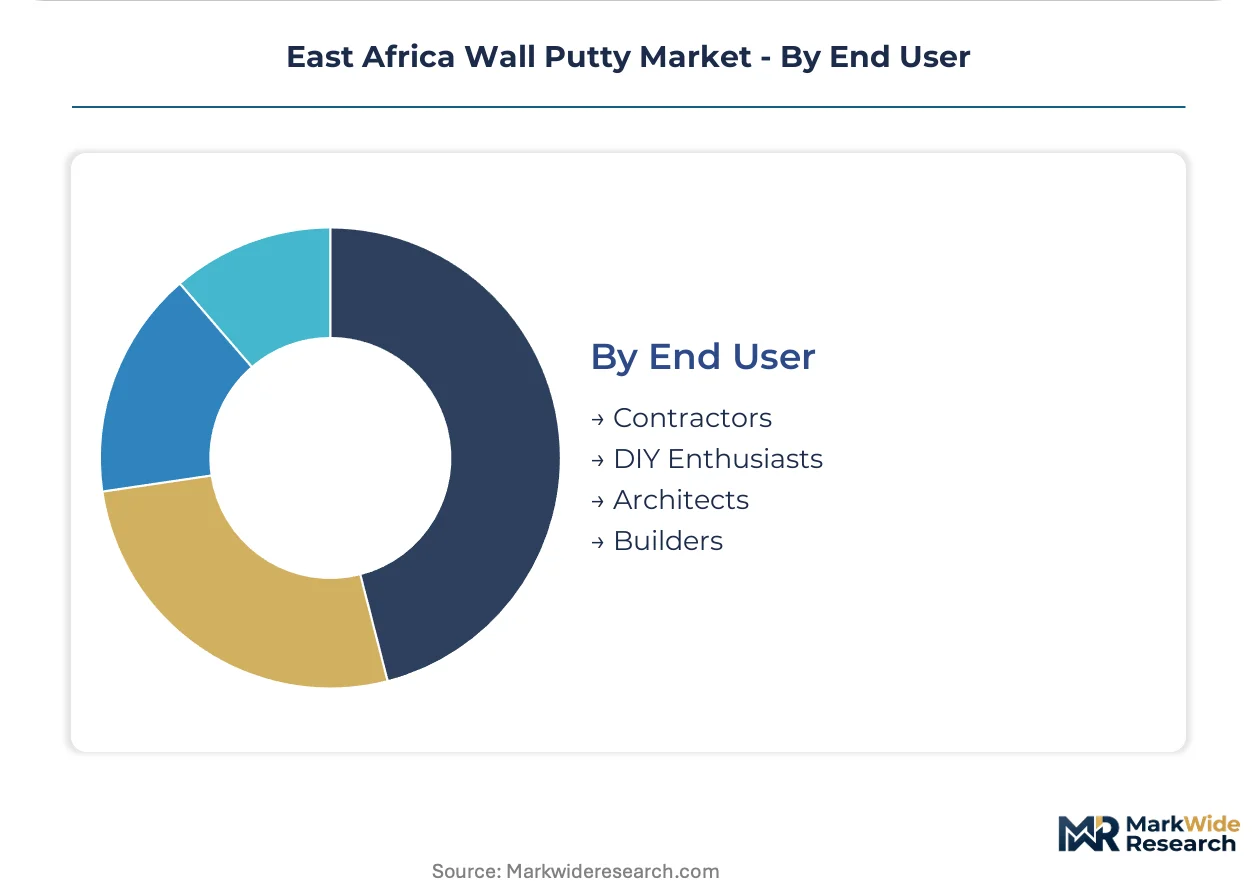
End User:
Technical sophistication and procurement authority separate these buyer categories across project scales.
- Contractors:General construction and specialized finishing firms in Kenya's Kiambu and Tanzania's Ilala districts specify putty grades, manage applicator crews, and negotiate volume pricing with manufacturers. These actors control 70-80% of current East African putty procurement decisions.
- DIY Enthusiasts:Nairobi's upper-middle-class homeowners purchasing through retail channels for interior renovation projects represent an emerging demand layer with distinct brand sensitivity and technical support requirements.
- Architects:Specification influence varies by project type and client sophistication.
- Builders:Developer-procurement integration limits independent builder authority in major urban markets.
Contractors retain procurement dominance. DIY enthusiasts are gaining share fastest as retail hardware formats proliferate in Kenyan and Tanzanian capital cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal manufacturing clusters in Kenya control bulk putty distribution logistics, creating dependency patterns that shape procurement economics across the broader East African region. Mombasa's port infrastructure and cement milling capacity concentrate formulation expertise and import channels. Landlocked markets in Tanzania and Uganda absorb supply chain premiums as they route through this coastal bottleneck.
Kenya
Nairobi's satellite towns and the Mombasa-Nairobi corridor drive residential putty consumption as mortgage finance expansion accelerates middle-class housing stock. Kenya Bureau of Standards (KEBS) cement product specifications are tightening contaminant thresholds and mandating third-party laboratory verification for imported consignments. Kiambu County manufacturing zones host integrated clinker-to-putty production facilities serving domestic and re-export demand.
Tanzania
Dar es Salaam's Kinondoni district and Ilala construction corridors absorb rising interior putty volumes from commercial high-rise developments. Tanzania Bureau of Standards alignment with Kenyan specifications remains incomplete, extending cross-border formulation approval timelines. Arusha's secondary city buildout remains underpenetrated by organized distribution networks.
Uganda
Kampala's Nakasero commercial corridor and emerging residential zones in Entebbe generate exterior putty demand for climate-resilient facades. Uganda National Bureau of Standards (UNBS) cement product standards diverge from Kenyan frameworks, complicating regional supplier compliance. Jinja and Mbarara construction corridors lack established wholesale infrastructure.
Rwanda
Kigali's urban densification programs and government-backed affordable housing initiatives are creating nascent putty demand from formalized construction sectors. The country's national standards body is developing construction material specifications that reference regional benchmarks. Rubavu and Musanze secondary cities show early contractor procurement patterns.
Ethiopia
Addis Ababa's state-led housing programs and infrastructure expansion generate bulk cement product demand including finishing compounds. The Ethiopian Conformity Assessment Enterprise maintains import inspection regimes for construction chemicals. Hawassa's industrial park construction has introduced modern building material specifications to regional contractors.
East Africa Wall Putty Market Key Industry Players
Integrated cement majors and construction chemical specialists split the market between volume-scale production and performance-formulation expertise. Kenyan coastal manufacturing assets confer logistics advantages for regional distribution. Three archetypes dominate: vertically integrated cement producers with captive raw material access, diversified coatings conglomerates leveraging brand equity, and construction chemical specialists commanding premium exterior segments. Competitive moves center on distributor network consolidation and polymer-modified formulation licensing.
Among India-based coatings and cement conglomerates, Asian Paints Ltd., UltraTech Cement Ltd., and Berger Paints India Ltd. occupy positions that exemplify the diversified-manufacturer archetype. These entities anchor regional supply through Mombasa logistics corridors and Nairobi distribution infrastructure. Their presence reflects the broader pattern of South Asian capital and technical expertise penetrating East African construction material sectors. Sika AG represents the construction chemical specialist tier, sitting within the premium-formulation segment where acrylic-modified systems command sustained demand.
| Leading Market Players |
|---|
| Nippon Paint India Pvt. Ltd. |
| UltraTech Cement Ltd. |
| Asian Paints Ltd. |
| Walplast Products Pvt. Ltd. |
| Akzo Nobel NV |
| Berger Paints India Ltd. |
| Sika AG |
| Pidilite Industries Limited |
| JK Cement Ltd. |
| Others |
Cost & Logistics Intelligence
Mombasa-Nairobi freight corridors transmit white cement cost volatility into tiered pricing power across Kenya, Tanzania, and Uganda. Coastal manufacturing concentration enables premium capture for polymer-modified exterior grades while landlocked markets absorb logistics premiums through distributor markups.
Pricing Analysis
KEBS cement product specifications dictate the pricing tier structure by mandating third-party laboratory verification for imported consignments. Three-tier pricing separates certified polymer-modified exterior grades from standard interior formulations and uncertified economy alternatives. Price differentiation centers on certification compliance and polymer loading levels. Pricing pressure stems from white cement input volatility as Kenyan shilling depreciation against dollar-denominated clinker imports compresses margins. Contractor procurement committees demonstrate lowest price sensitivity, while retail DIY channels in Nairobi and Dar es Salaam exhibit highest elasticity to unit cost shifts.
Supply Chain Analysis
White cement feedstock draws from Middle Eastern and Asian clinker sources through Mombasa port infrastructure. Regional manufacturing concentrates in Kenya's coastal corridor, with Tanzania and Uganda dependent on cross-border distribution networks. Raw material dependencies span white cement, SBR latex polymers, and mineral fillers including calcium carbonate. Supply chain risk centers on single-source port congestion at Mombasa creating bottleneck exposure for landlocked markets. Distribution runs through manufacturer-direct channels for large commercial projects, wholesaler networks serving secondary cities, and retail hardware stores capturing homeowner volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa wall putty markets approach a platform-economics inflection as KEBS-TBS-UNBS regulatory interoperability creates ecosystem consolidation incentives. Standard harmonization across Kenyan, Tanzanian, and Ugandan bureaus of standards will reshape competitive boundaries.
For Market Incumbents: Pre-empt distributor consolidation by locking exclusive wholesale agreements in Arusha, Jinja, and Mbarara corridors before regional competitors establish presence. Secure backward integration into white cement supply through long-term offtake contracts with Middle Eastern clinker suppliers to defend margin position against currency volatility. Gypsum-based skim coat substitution represents the priority threat requiring polymer-modified formulation investment to maintain specification relevance. For New Entrants and Emerging Players: Establish a beachhead in Uganda's secondary city buildout where organized distribution remains underdeveloped and UNBS certification requirements create lower barriers than Kenyan equivalents. Target DIY retail channel expansion in Nairobi's satellite towns where homeowner renovation volumes outpace contractor-served new construction. Deploy technical service teams as the primary go-to-market differentiator against established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors construction chemical specialists with polymer formulation capabilities over commodity white cement producers. Long-term viability hinges on climate resilience specification adoption across commercial facades and regulatory harmonization reducing multi-jurisdiction compliance burdens. Acquisition targets should demonstrate established KEBS certification and Mombasa logistics access. Monitor Tanzania Bureau of Standards alignment with Kenyan specifications as the critical inflection signal for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into White Cement Supply | Captive clinker access insulates margins against Mombasa port cost volatility and currency depreciation. |
| Polymer-Modified Formulation Licensing | Acrylic-enhanced technology commands exterior application premiums where tropical rainfall resistance determines specification. |
| Wholesaler Network Consolidation | Exclusive distribution agreements in Arusha and Jinja corridors preempt competitor secondary city penetration. |
| KEBS Certification Investment | Third-party laboratory verification compliance clears shelf space as informal imports face enforcement elimination. |
| DIY Retail Channel Expansion | Nairobi and Dar es Salaam hardware store penetration captures homeowner renovation volumes outside contractor procurement. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with construction material stakeholders and secondary source triangulation. Primary interviews encompassed cement plant managers, coatings procurement leads at commercial developers, wholesale distribution partners, and KEBS regulatory affairs specialists. Secondary validation drew from Kenya Bureau of Standards technical specifications, Tanzania Bureau of Standards draft harmonization documents, UNBS cement product frameworks, and regional customs trade data. Bottom-up volume modeling from project pipeline databases was cross-checked against top-down market sizing from manufacturer capacity disclosures.
Forecast inputs incorporated product type segmentation across interior, exterior, textured, and priming putty grades; application splits between residential, commercial, institutional, and industrial construction; and channel dynamics spanning direct sales, wholesale, retail, and emerging online formats. End-user archetypes including contractor procurement committees, DIY enthusiasts, architect specifications, and builder-developer integration patterns were modeled separately. CAGRs were derived from elasticity-adjusted volume projections against macroeconomic housing stock expansion assumptions. White cement price trajectories and polymer additive cost curves provided industry-specific forecast anchors.
Stress conditions across Kenyan shilling depreciation rates, Mombasa port throughput capacity, and KEBS enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and housing finance expansion trajectories. Quarterly review of KEBS-TBS specification alignment progress and clinker import cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Door Frame Metal Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
North America Construction Aggregates Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Masonry Cement Market
Building Materials
HDG Steel Pipe Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Low-E Construction Glass Market
Building Materials
Drywall Joint Tape Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Aluminum Door and Window Market
Building Materials
Pozzolana Cement Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Canada Architectural Coatings Market