
 Vacuum Degreasers Market | 2026-2036
Vacuum Degreasers Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Degreasers Market Insights
REACH is restructuring the cost-of-entry calculus for solvent-based vacuum degreaser suppliers across European manufacturing hubs. Baron Blakeslee Serec leverages its heritage in vapor degreasing to sustain a defensible position in aerospace-certified equipment. Pero Corporation anchors its competitiveness through integrated solvent-recovery systems that reduce operational compliance burdens. Dürr Ecoclean competes via modular platform architectures that adapt to shifting regulatory thresholds without full equipment replacement.
Vacuum degreasers are hermetically sealed industrial cleaning systems that operate at reduced pressure to lower solvent boiling points, typically achieving cleaning temperatures between 35°C and 80°C depending on the chemistry employed, with the primary purpose of removing oils, particulates, and residues from precision-engineered components without thermal damage or oxidation. Automated vacuum degreasers command the technology premium in this landscape, as their programmable cycles and reduced solvent exposure align with tightening workplace-safety mandates and labor-cost pressures across developed manufacturing economies. Water-based cleaning technology within vacuum systems is gaining structural traction where plasma-sensitive substrates or multi-stage finishing requirements dominate end-user specifications, particularly in electronics assembly applications where ionic contamination thresholds are narrowing.
The EPA governs solvent emissions through National Emission Standards for Hazardous Air Pollutants, while OSHA sets permissible exposure limits for chlorinated and fluorinated chemistries in metal fabrication facilities; in parallel, the EU F-Gas Regulation phases down hydrofluorocarbon use in industrial processes, compelling equipment redesign toward alternative vacuum chemistries and closed-loop architectures. Japan's METI promotes energy-efficient manufacturing equipment through its Top Runner program, indirectly shaping vacuum degreaser efficiency benchmarks in Asian precision-manufacturing supply chains. Stakeholders must monitor the divergence between regional chemical-approval pathways and equipment-certification timelines, as misalignment here will determine which suppliers can deploy unified product platforms versus fragmented national offerings.
Market Dynamics
REACH compliance deadlines and EPA solvent-emission thresholds are compressing equipment replacement cycles across precision-manufacturing clusters, forcing capital allocation toward closed-loop vacuum architectures before legacy systems reach end-of-life.
Growth Catalysts
- Aerospace precision mandates:Commercial aviation suppliers in Germany and Japan are procuring automated vacuum degreasers to meet NADCAP cleaning specifications for turbine components. Equipment orders from Hamburg and Nagoya manufacturing hubs are accelerating replacement timelines.
- EU F-Gas phase-down:The regulation is compelling fluorinated solvent users toward alternative vacuum chemistries, expanding addressable demand for equipment redesigned around hydrofluorocarbon alternatives.
- Electronics ionic contamination thresholds:Semiconductor packaging facilities in the United States are specifying multi-stage vacuum cleaning to satisfy IPC-1601 standards, pulling capital into advanced solvent-recovery systems.
Market Restraints
- Specialized steel and corrosion-resistant alloy costs:Vacuum chamber fabrication depends on nickel-based alloys and precision-machined stainless steel grades subject to commodity volatility and limited supplier concentration in German and Japanese metallurgical sectors.
- Fluorinated solvent supply concentration:Three chemical producers control the majority of aerospace-qualified chlorinated and fluorinated cleaning chemistries, creating input bottleneck risk for equipment OEMs dependent on validated solvent pairings.
- Water-based technology performance ceiling:Plasma-sensitive substrates and certain oxide-prone alloys remain incompatible with aqueous vacuum processes, limiting substitution potential in medical implant and optical component segments.
Strategic Opportunities
- India precision-manufacturing scale-up:PLI scheme beneficiaries in aerospace components and medical devices represent underpenetrated demand for REACH-compliant vacuum degreasing as export certification requirements tighten.
- Remanufacturing and circular economy mandates:The EU Green Deal's industrial sustainability targets are creating specification pull for solvent-recovery-integrated equipment in automotive powertrain remanufacturing facilities.
- Convergence of vacuum drying and cleaning:Combined thermal-vacuum processing units that consolidate cleaning and moisture removal into single-chamber workflows are gaining specification in electronics assembly lines seeking footprint reduction.
Industry Challenges
- Vacuum system engineering talent scarcity:Specialized knowledge of hermetic sealing, pressure-vessel design, and solvent thermodynamics concentrates among aging workforces in Stuttgart and Nagoya equipment manufacturing clusters.
- Extended aerospace certification timelines:NADCAP and OEM-specific process approvals require 18-36 month validation cycles, compressing revenue recognition and straining working capital for equipment suppliers targeting aviation supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Degreasers Market |
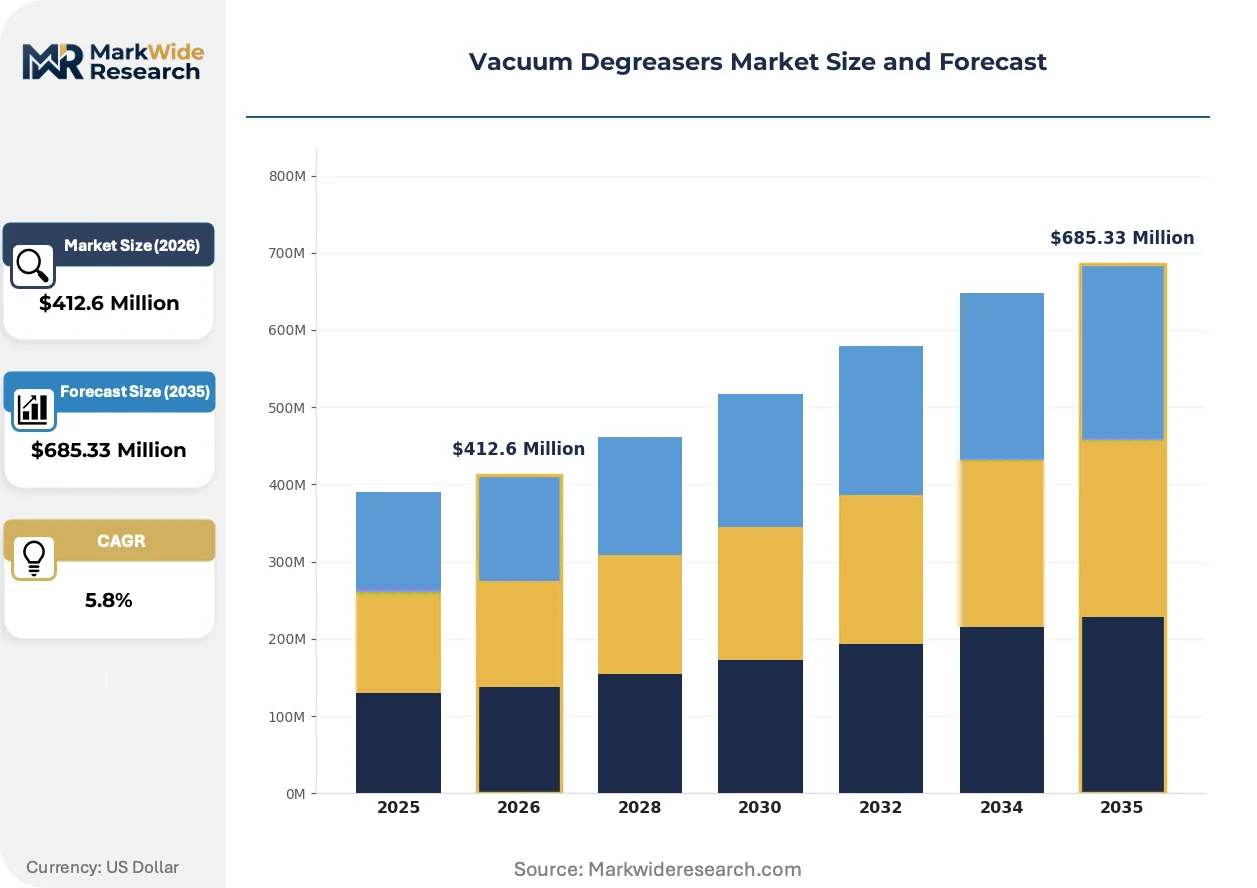
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Vacuum Degreasers, Custom Vacuum Degreasers, Automated Vacuum Degreasers, Industrial Vacuum Degreasers End User: Aerospace Manufacturers, Automotive OEMs, Electronics Assembly, Metal Fabrication Technology: Solvent-Based Cleaning, Water-Based Cleaning, Ultrasonic Cleaning, Plasma Cleaning Application: Parts Cleaning, Surface Preparation, Oil Removal, Final Cleaning |
| Companies Covered | Baron Blakeslee Serec, VAC AERO, Pero Corporation, Utitec Inc, IHI Machinery and Furnace, Ralsonics, NGCT Cleansys, ILSA-MC Srl, Dürr Ecoclean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Degreasers Market Trends and Innovations
Equipment architectures are converging around closed-loop solvent management and programmable automation, driven by regulatory pressure on emissions and labor economics in high-wage manufacturing economies.
Ultrasonic-assisted vacuum degreasing is electrifying precision-cleaning workflows by combining cavitation energy with reduced-pressure solvent physics. Medical device manufacturers in Switzerland and Minnesota are specifying these hybrid systems for complex orthopedic implant geometries. The technology is compressing cycle times and reducing solvent consumption rates in validated production environments.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is tightening permissible solvent loss rates from vapor degreasing operations. Metal fabrication facilities in Ohio and Michigan are retrofitting existing equipment with enhanced refrigeration coils and automated cover systems to capture fugitive emissions. The regulatory pressure is accelerating capital migration from open-top to hermetically sealed vacuum architectures in general metalworking segments previously served by conventional vapor equipment.
Outcome-based equipment performance contracts are displacing traditional capital purchase models in automotive tier-one supply chains. German powertrain suppliers in Baden-Württemberg are negotiating cleaning-cost-per-component agreements that transfer operational risk to equipment vendors. The contracting shift is visible most acutely in high-volume transmission manufacturing where process consistency directly impacts downstream assembly yields.
Vacuum Degreasers Market Segmentation
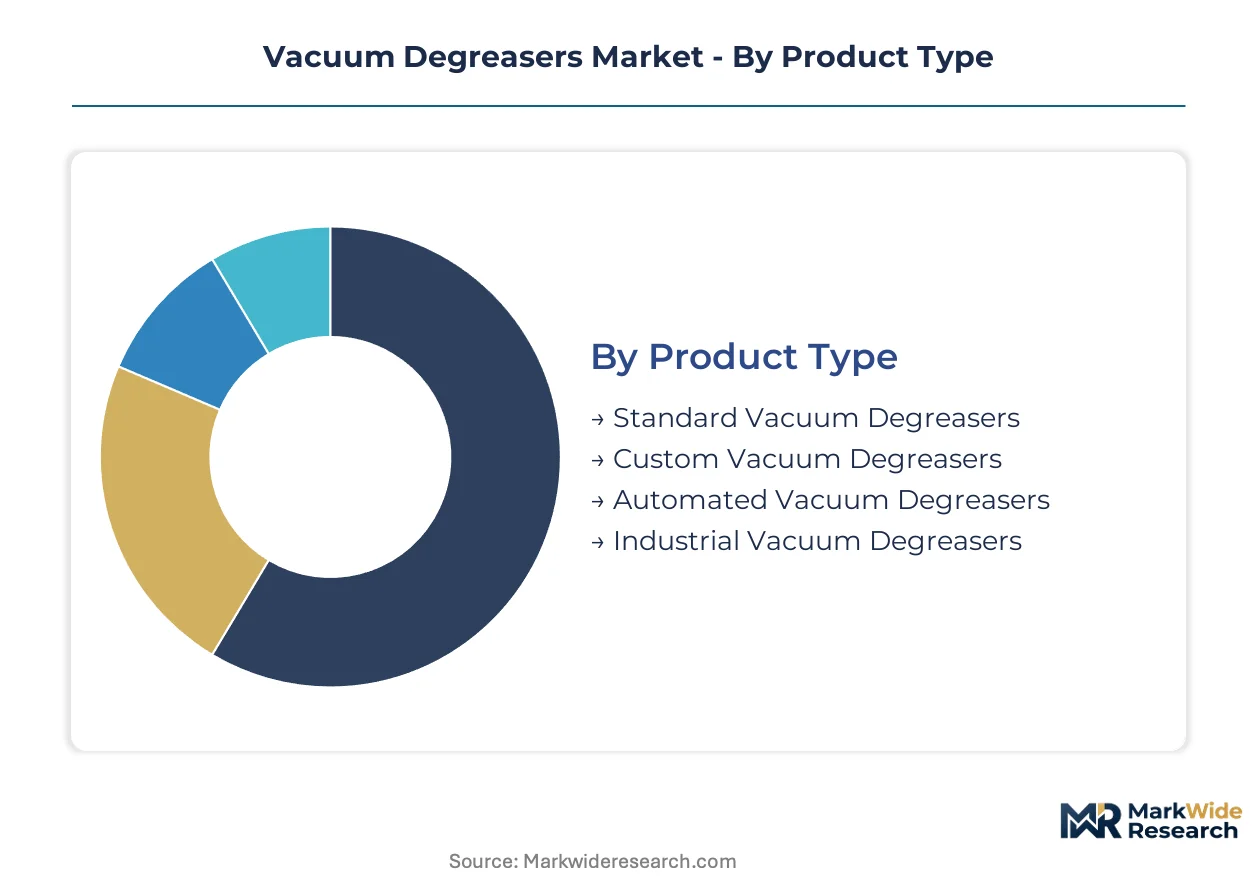
Vacuum degreaser procurement decisions split sharply between validated process requirements and cost-driven standardization. Aerospace and medical device supply chains demand engineered-to-order configurations, while general metalworking tolerates catalog specifications. Understanding these fault lines clarifies where technology premiums command pricing power versus where commodity competition dominates.
Product Type:
Customization intensity varies dramatically across this spectrum, from mass-produced units for job shops to NADCAP-validated systems requiring 18-36 month qualification cycles.
- Automated Vacuum Degreasers:Programmable cycle control and robotic loading interfaces define this category. German powertrain suppliers in Baden-Württemberg are specifying these systems under outcome-based cleaning-cost-per-component contracts that transfer operational risk to equipment vendors.
- Custom Vacuum Degreasers:Engineered around specific component geometries, solvent chemistries, and regulatory jurisdictions. Swiss orthopedic implant manufacturers specify these for complex geometries where standard chamber configurations risk incomplete cleaning validation.
- Standard Vacuum Degreasers:Catalog configurations serving general metal fabrication with minimal reconfiguration. Ohio and Michigan metalworking facilities deploy these for batch production of non-critical components.
- Industrial Vacuum Degreasers:High-throughput architectures for continuous production environments. Japanese automotive suppliers specify these for transmission manufacturing lines requiring sub-ppm contamination thresholds.
Leading the category by volume: Industrial Vacuum Degreasers. Growing fastest: Automated Vacuum Degreasers.
End User:
Customer sophistication and validation burden create tiered pricing power, with aerospace and medical segments absorbing technology premiums unavailable in general fabrication.
- Aerospace Manufacturers:NADCAP cleaning specifications for turbine components mandate hermetically sealed architectures with solvent-recovery integration. Hamburg and Nagoya manufacturing hubs are accelerating replacement timelines as OEM-specific process approvals tighten.
- Electronics Assembly:Semiconductor packaging facilities in the United States specify multi-stage vacuum cleaning to satisfy IPC-1601 ionic contamination standards. Plasma-sensitive substrates in advanced packaging drive solvent-based system preference over aqueous alternatives.
- Automotive OEMs:Powertrain remanufacturing facilities under EU Green Deal circular economy mandates are specifying solvent-recovery-integrated equipment. High-volume transmission manufacturing prioritizes process consistency over cleaning sophistication.
- Metal Fabrication:General metalworking segments previously served by open-top vapor equipment are retrofitting to hermetically sealed vacuum architectures under EPA National Emission Standards enforcement.
Deepest technology penetration: Aerospace Manufacturers. Fastest specification upgrade: Electronics Assembly.
Technology:
Chemistry selection locks equipment architecture and regulatory compliance trajectory, with fluorinated solvent phase-downs forcing platform redesigns.
- Solvent-Based Cleaning:Reduced-pressure operation lowers boiling points to 35°C-80°C, enabling precision cleaning without thermal damage. EU F-Gas Regulation phase-down is compelling hydrofluorocarbon users toward alternative vacuum chemistries and closed-loop architectures.
- Water-Based Cleaning:Aqueous chemistry gaining structural traction where plasma-sensitive substrates or multi-stage finishing requirements dominate. Electronics assembly applications with narrowing ionic contamination thresholds specify these for post-solder flux removal.
- Ultrasonic Cleaning:Cavitation energy combined with reduced-pressure solvent physics compresses cycle times. Minnesota medical device manufacturers specify hybrid ultrasonic-vacuum systems for complex orthopedic implant geometries.
- Plasma Cleaning:Dry chemistry processing for oxide-sensitive substrates and ultra-high purity requirements. Limited deployment outside semiconductor front-end manufacturing due to capital intensity and throughput constraints.
Widest installed base: Solvent-Based Cleaning. Steepest expansion trajectory: Ultrasonic Cleaning.
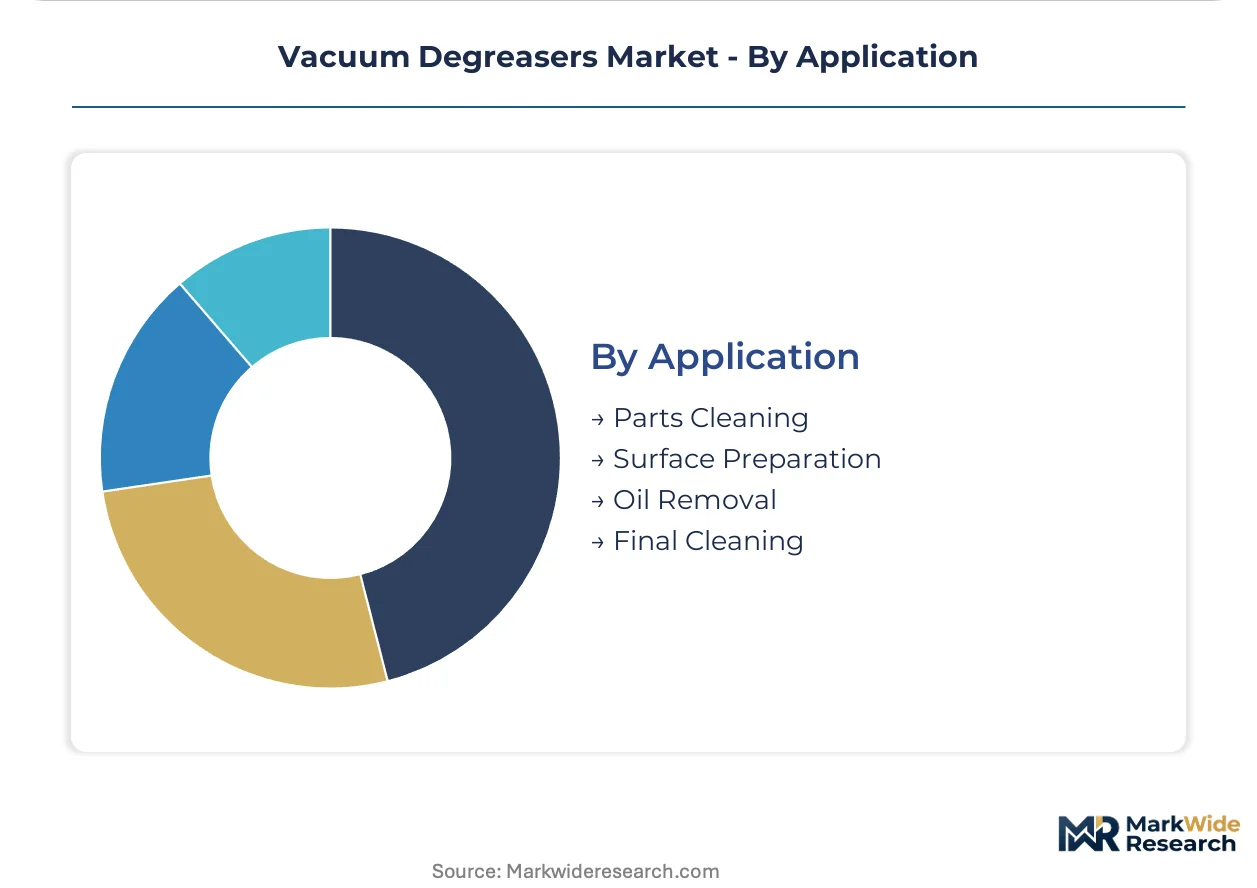
Application:
Process position in manufacturing workflow determines contamination tolerance and validation stringency, with final cleaning commanding premium specifications.
- Final Cleaning:Last-stage processing before assembly, coating, or sterilization where residue thresholds are tightest. Medical implant and optical component segments specify vacuum architectures here where aqueous processes risk oxidation or ionic contamination.
- Parts Cleaning:Intermediate processing of machined components before subsequent operations. General metal fabrication deploys standard vacuum configurations for bulk oil and particulate removal.
- Surface Preparation:Pre-treatment for coating, bonding, or plating operations. Automotive tier-one suppliers specify automated systems here where surface energy consistency impacts downstream adhesion performance.
- Oil Removal:Heavy-duty extraction of cutting fluids and protective lubricants from as-machined components. Job shop metalworking prioritizes throughput and solvent economy over precision specifications.
Highest specification intensity: Final Cleaning. Fastest volume growth: Surface Preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in precision-manufacturing corridors concentrate vacuum degreaser procurement. Tax incentives in aerospace and electronics clusters accelerate capital deployment toward REACH-compliant and NADCAP-validated equipment architectures.
Germany
Baden-Württemberg powertrain suppliers specify automated vacuum degreasers under outcome-based cleaning contracts. REACH compliance deadlines compress replacement cycles for solvent-based systems. Hamburg aerospace manufacturing hubs accelerate procurement of hermetically sealed architectures for turbine component cleaning.
United States
Semiconductor packaging facilities in Arizona and Texas specify multi-stage vacuum cleaning for IPC-1601 ionic contamination standards. EPA National Emission Standards for Hazardous Air Pollutants enforcement tightens permissible solvent loss rates. Ohio and Michigan metal fabrication facilities retrofit open-top vapor equipment to sealed vacuum architectures.
Japan
Nagoya manufacturing hubs drive replacement timelines for NADCAP-validated aerospace cleaning systems. METI Top Runner program shapes energy-efficiency benchmarks for precision-manufacturing equipment. Kanto region electronics assembly lines specify combined thermal-vacuum processing units for footprint reduction.
India
PLI scheme beneficiaries in aerospace components and medical devices represent underpenetrated demand for REACH-compliant equipment. Export certification requirements tighten as European OEMs audit Indian supplier facilities. Karnataka and Tamil Nadu precision-manufacturing clusters initiate technology upgrade cycles.
Switzerland
Orthopedic implant manufacturers specify custom vacuum degreasers for complex geometries requiring validated cleaning protocols. Swissmedic medical device regulations mandate residue thresholds that favor solvent-based vacuum architectures over aqueous alternatives. Basel and Zurich medical technology clusters concentrate procurement of hybrid ultrasonic-vacuum systems.
Vacuum Degreasers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base fragments between catalog-standard fabricators and engineered-to-order specialists serving aerospace and medical validation requirements. Three archetypes dominate: heritage vapor-degreasing specialists with aerospace certification track records, integrated solvent-recovery platform builders, and modular architecture designers enabling regulatory adaptation without full replacement. Competitive moves concentrate on geographic expansion into Indian PLI scheme zones and portfolio diversification toward water-based vacuum technologies.
Among heritage specialists, Baron Blakeslee Serec and VAC AERO occupy positions anchored in vapor-degreasing lineage. Pero Corporation exemplifies the integrated solvent-recovery archetype, while Dürr Ecoclean represents modular platform architecture approaches. These three companies span the strategic spectrum from validation-intensive aerospace supply chains to adaptable general metalworking segments.
| Leading Market Players |
|---|
| Baron Blakeslee Serec |
| VAC AERO |
| Pero Corporation |
| Utitec Inc |
| IHI Machinery and Furnace |
| Ralsonics |
| NGCT Cleansys |
| ILSA-MC Srl |
| Dürr Ecoclean |
| Others |
Pricing and Supply Chain Analysis
Captive supply of nickel-based alloys and precision-machined stainless steel grades anchors both the cost structure and the pricing power of vacuum degreaser OEMs serving aerospace and medical validation requirements. Equipment vendors with backward integration into German and Japanese metallurgical networks command premium positioning, while spot-market dependent fabricators absorb commodity volatility that compresses margins on standard catalog units.
Pricing Analysis
Short lead-time premiums separate NADCAP-validated custom systems from spot-available standard configurations, with aerospace procurement teams paying substantial markups for 12-week versus 26-week delivery windows. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, with automated solvent-recovery systems commanding the top tier and batch-loaded job shop units populating the bottom. Cost compression in standard vacuum degreasers is intensifying because Chinese fabricators are penetrating general metalworking segments with REACH-approximate specifications. General metal fabrication buyers exhibit highest price sensitivity, while Swiss orthopedic implant manufacturers absorb technology premiums without volume negotiation.
Supply Chain Analysis
NADCAP and OEM-specific process approvals gate supplier qualification, creating 18-36 month onboarding timelines that protect incumbent positions in aerospace supply chains. Vacuum chamber fabrication draws from concentrated German and Japanese metallurgical sectors for corrosion-resistant alloys, with secondary sourcing from South Korean specialty steel producers. Hermetic sealing components and precision refrigeration coils represent critical single-source vulnerabilities for equipment OEMs dependent on validated sub-tier suppliers. Distribution runs through direct sales engineering teams for aerospace and medical segments, while general metalworking channels move through regional industrial equipment distributors with aftermarket service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacuum degreasers market sits in a technology-transition phase where automated closed-loop architectures are displacing conventional open-top vapor equipment under regulatory pressure. Water-based vacuum cleaning platforms are gaining specification in electronics assembly as plasma-sensitive substrate requirements multiply.
For Market Incumbents: Anchor defensible positioning through captive supply agreements with German and Japanese nickel-alloy suppliers, insulating against commodity volatility that threatens margin structures. Accelerate NADCAP validation investments to compress 18-36 month qualification timelines before emerging solvent-recovery specialists achieve aerospace certification. Prioritize R&D in ultrasonic-vacuum hybrid architectures where Minnesota and Swiss medical device manufacturers are consolidating procurement specifications.
For New Entrants and Emerging Players: Enter via India's PLI scheme aerospace component zones where European OEM audits are tightening REACH compliance requirements among underpenetrated supplier bases. Target Karnataka and Tamil Nadu precision-manufacturing clusters with solvent-recovery-integrated standard systems priced below German incumbent levels. Pursue outcome-based cleaning-cost-per-component contracting models that transfer operational risk and differentiate from capital-purchase competitors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking aerospace certification assets and Indian market access. Long-term viability favors equipment OEMs with demonstrated NADCAP track records and modular platform architectures enabling regulatory adaptation without full replacement cycles. Watch for inflection signals in EPA enforcement intensity around National Emission Standards for Hazardous Air Pollutants, which would accelerate capital migration from open-top to hermetically sealed vacuum architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Alloy Supply | Captive sourcing from German metallurgical networks insulates margin structures against commodity volatility. |
| NADCAP Validation Acceleration | Compressed qualification timelines defend incumbent positioning against emerging solvent-recovery specialists. |
| Water-Based Vacuum Platform Development | Electronics assembly specifications for plasma-sensitive substrates pull capital into aqueous alternatives. |
| Indian PLI Zone Market Entry | Karnataka aerospace clusters under European OEM audit pressure create specification upgrade demand. |
| Outcome-Based Performance Contracting | Baden-Württemberg powertrain suppliers transfer operational risk through cleaning-cost-per-component agreements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with maintenance directors at aerospace manufacturing facilities, plant engineers in automotive powertrain operations, procurement leads at semiconductor packaging facilities, and aftermarket service heads at industrial equipment distributors. Secondary validation drew from EPA National Emission Standards enforcement records, EU ECHA REACH compliance databases, Japan METI Top Runner program disclosures, and SEC filings from diversified industrial conglomerates with vacuum degreaser exposure. Bottom-up equipment shipment tallies and top-down precision-manufacturing capital expenditure estimates were reconciled through iterative triangulation.
Data-stream reconciliation across equipment OEM order backlogs, solvent chemistry shipment records, and end-user facility certification databases informed the analytical framework. Segmentation dimensions modeled include product type intensity, end-user validation burden, technology chemistry trajectory, and application position in manufacturing workflow. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory deadline impacts. Industry-specific forecast inputs incorporated NADCAP validation timeline distributions and EU F-Gas phase-down implementation schedules.
Revisions become necessary when EPA enforcement intensity shifts, REACH compliance deadlines are extended, or aerospace OEM process approval requirements materially change. Forecasts reflect assumptions around solvent chemistry availability, metallurgical supply continuity, and precision-manufacturing capital expenditure stability. A model refresh is warranted upon material change in regulatory enforcement patterns or qualification timeline structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Europe Molecular Sieve Market