
 Europe Microspheres Market | 2026-2036
Europe Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microspheres Market Intelligence
A shift from single-source resin supply toward qualified multi-source networks is pivoting procurement strategy across European microsphere converters. Nouryon leverages its integrated alkoxide chemistry chain to secure hollow glass precursor supply. Evonik Industries anchors high-performance polymer microsphere output from its German manufacturing base. Momentive competes on silicone resin microsphere formulations for thermal management applications.
Europe microspheres are spherical particles typically ranging from one to one thousand micrometers in diameter, engineered from glass, polymer, ceramic, or metallic matrices via spray drying, emulsion polymerization, or sol-gel processes, serving functions of weight reduction, controlled release, opacity, or mechanical reinforcement across industrial and life-science systems. Polymer microspheres command the widest formulation flexibility and margin pool in drug delivery and cosmetics, while glass microspheres dominate volume in automotive lightweighting and construction fillers where density reduction drives specification. Ceramic microspheres occupy a narrower but defensible niche in high-temperature coatings and thermal barrier applications.
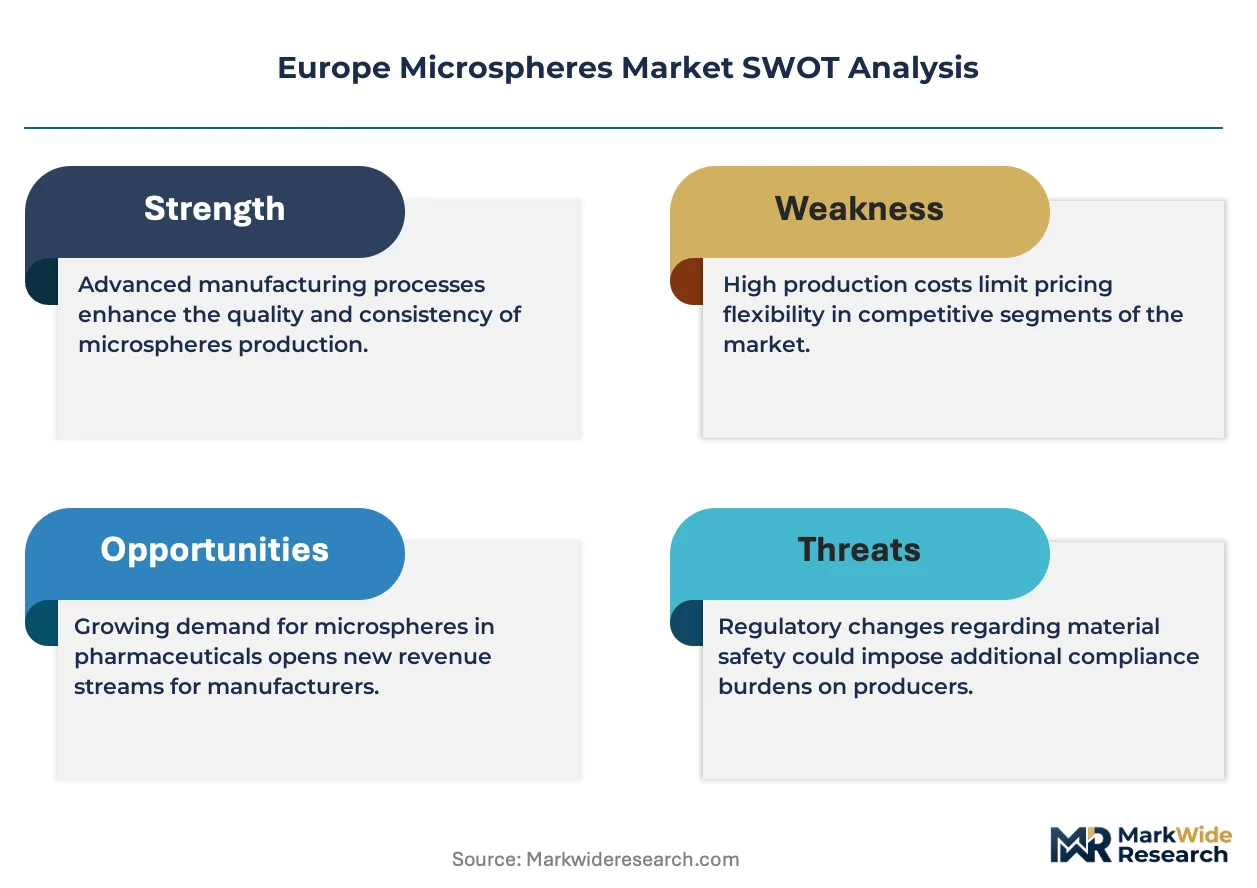
EMA medical device regulations, REACH substance restrictions, and the EU Green Deal sustainable chemistry framework collectively elevate purity standards, restrict legacy additives, and mandate lifecycle transparency for microsphere formulations entering European commerce. ECHA substance evaluation dossiers now require expanded toxicity data for nanoscale and sub-micron spherical particles, extending compliance timelines and R&D cost structures for suppliers. Stakeholders must monitor pending MDR amendments and delegated acts on implantable particulate materials, as these will determine which microsphere grades retain market access versus face requalification or withdrawal.
Market Dynamics
REACH substance restrictions and the EU Green Deal are forcing European microsphere suppliers to requalify legacy formulations and accelerate bio-based polymer substitution across pharmaceutical and automotive supply chains.
Growth Catalysts
- EMA medical device regulations:Tighter purity standards for implantable particulate materials are creating premium demand for certified polymer microspheres in controlled-release drug delivery systems.
- Automotive lightweighting mandates:German OEM procurement specifications for density reduction in structural composites are pulling hollow glass microsphere volumes into electric vehicle battery enclosures.
- Sol-gel process advancement:Improved ceramic microsphere uniformity is opening thermal barrier coating applications in aerospace propulsion systems across French and Italian manufacturing clusters.
Market Restraints
- Alkoxide precursor concentration:Hollow glass microsphere production depends on concentrated sodium silicate supply chains centered in the Netherlands and Belgium, creating single-source vulnerability for European converters.
- ECHA nanoscale toxicity dossiers:Expanded data requirements for sub-micron spherical particles are extending compliance timelines by 18-24 months and inflating R&D cost structures for new grade introductions.
- Silica fume substitution:Construction sector buyers in Southern Europe are partially displacing microsphere fillers with lower-cost pozzolanic alternatives in non-structural concrete applications.
Strategic Opportunities
- Polish pharmaceutical manufacturing expansion:Warsaw and Krakow clusters are attracting contract development organizations seeking qualified microsphere suppliers for oral dosage form projects.
- EU Green Deal sustainable chemistry incentives:Bio-based PLA and PHA microsphere development qualifies for Horizon Europe funding streams targeting circular material transitions.
- Digital therapeutics convergence:Microsphere-encapsulated sensor platforms combining controlled release with real-time biomarker monitoring are entering early-stage development partnerships with Nordic health technology firms.
Industry Challenges
- MDR requalification timelines:Existing microsphere grades for implantable applications face 12-18 month recertification cycles under amended medical device regulations, freezing inventory positions.
- Cross-functional formulation expertise:Shortage of chemists combining polymer science with pharmaceutical process engineering is constraining scale-up velocity for complex drug-device combination products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microspheres Market |
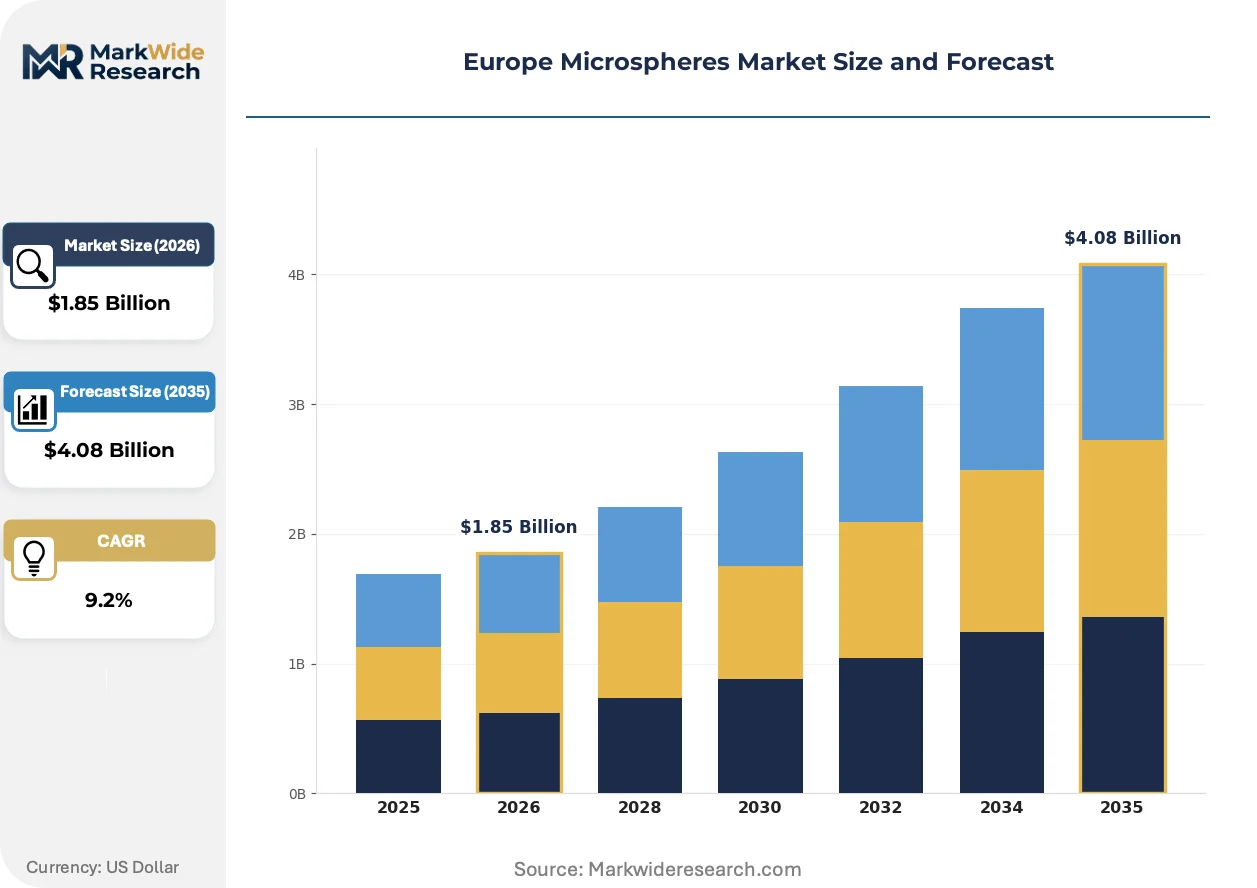
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.08 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Microspheres, Polymer Microspheres, Ceramic Microspheres, Metallic Microspheres End Use Industry: Biomedical, Cosmetics, Automotive, Construction Application: Drug Delivery, Coatings, Additives, Fillers Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Nouryon, 3M, Merck KGaA, Evonik Industries, Sigmund Lindner, Momentive, Potters Industries, Trelleborg, Omya, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microspheres Market Strategic Shifts & Innovations
European microsphere development is pivoting from commodity filler optimization toward functional surface engineering and bio-integrated material platforms that satisfy tightening lifecycle transparency mandates.
Surface-functionalized polymer microspheres with stimuli-responsive release kinetics are expanding into oncology drug delivery protocols. French and Swiss pharmaceutical formulators are adopting these systems for targeted chemotherapy payload delivery. The technology is expanding into companion diagnostic applications where controlled degradation enables synchronized imaging agent release.
REACH candidate list expansion for microplastic additives is accelerating bio-based polymer microsphere qualification programs. ECHA restriction proposals on intentionally added microplastics are forcing cosmetics and personal care formulators to substitute conventional PMMA microspheres with cellulose-derived alternatives. German and Dutch suppliers are scaling fermentation-based PHA microsphere pilot lines to capture switching demand ahead of 2027 enforcement timelines.
Automotive tier-one suppliers are consolidating microsphere procurement under single qualified-source contracts with volume guarantees. This pattern concentrates negotiating leverage among German and French OEM engineering teams while squeezing margin structures for secondary converters. The shift is most visible in battery pack thermal management applications where silicone resin microsphere specifications are locking in 36-month supply agreements.
Europe Microspheres Market Segmentation
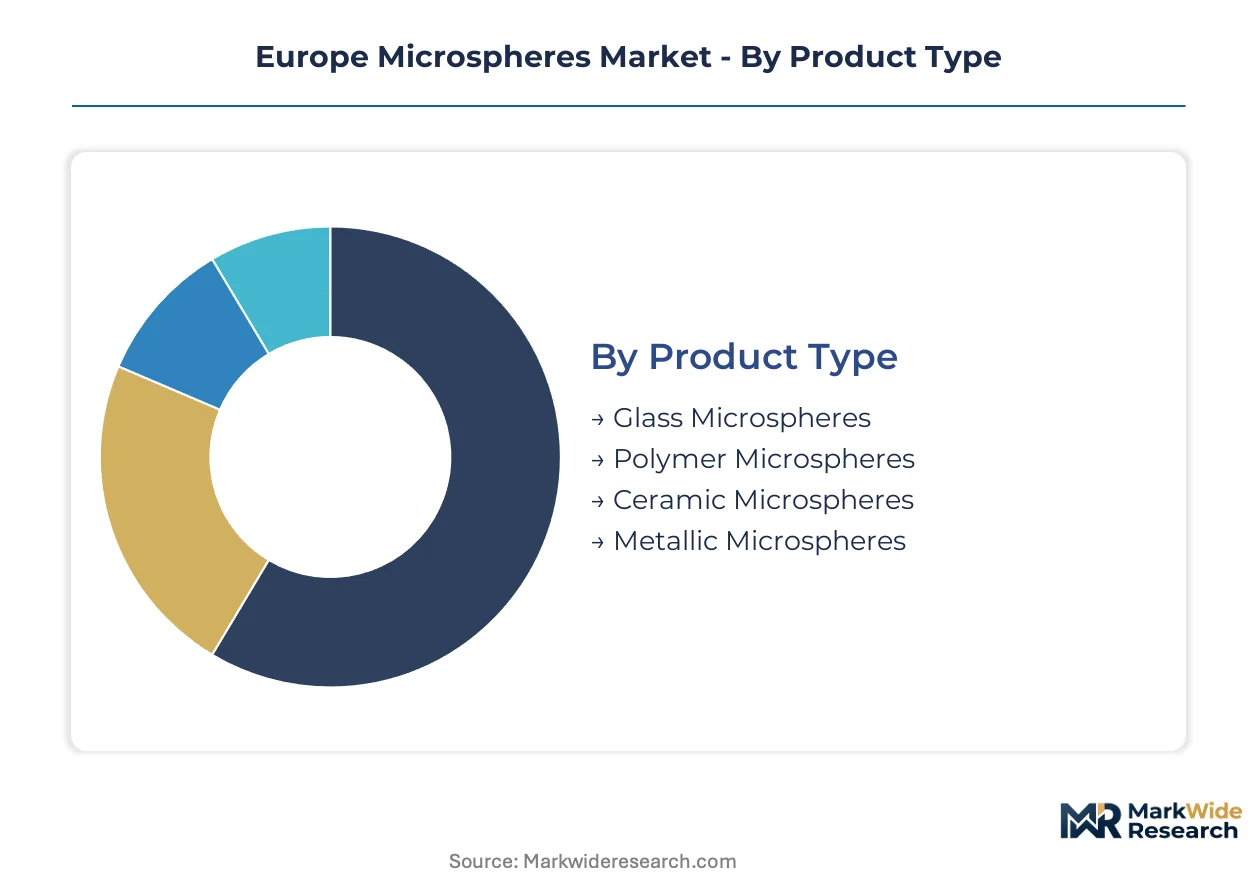
Microsphere procurement in Europe fragments across performance requirements, regulatory exposure, and supply chain proximity. Buyers select grades based on density targets, purity thresholds, and REACH compliance status rather than commodity pricing alone.
Product Type:
Material selection separates buyers by density reduction targets and thermal performance requirements.
- Glass Microspheres:Hollow borosilicate or soda-lime glass spheres engineered for density reduction in structural composites. German automotive OEMs specify these for electric vehicle battery enclosures where mass reduction extends range without compromising crash integrity.
- Polymer Microspheres:PMMA, PLA, or PHA matrices offering tunable degradation rates and surface functionalization. EMA medical device regulations and REACH microplastic restrictions are accelerating substitution toward bio-based grades in pharmaceutical and cosmetic formulations.
- Ceramic Microspheres:Alumina or zirconia-based spheres for thermal barrier coatings in aerospace propulsion systems.
- Metallic Microspheres:Aluminum or nickel alloys serving conductive and electromagnetic shielding applications in specialized electronics.
Glass microspheres lead volumes today; polymer microspheres are gaining share fastest.
End Use Industry:
Regulatory stringency and specification complexity determine margin capture across verticals.
- Biomedical:Controlled-release drug delivery systems and implantable particulate materials face MDR recertification timelines. EMA purity standards for sub-micron spheres concentrate procurement among qualified German and Swiss suppliers with validated manufacturing lines.
- Automotive:Lightweighting mandates under EU CO2 regulations pull hollow glass microspheres into composite body panels and battery housings. French and German OEM engineering teams consolidate procurement under single-source contracts with volume guarantees.
- Cosmetics:ECHA restrictions on intentionally added microplastics force substitution of conventional PMMA with cellulose-derived alternatives ahead of enforcement timelines.
- Construction:Hollow glass and ceramic microspheres reduce density in insulation panels and non-structural concrete, though silica fume substitution pressures margins in Southern European markets.
Automotive applications anchor volume demand; biomedical segments command the steepest expansion trajectory.
Application:
Functional performance requirements separate premium grades from commodity fillers.
- Drug Delivery:Surface-engineered polymer microspheres with stimuli-responsive release kinetics enable targeted chemotherapy protocols. French and Swiss formulators adopt these for synchronized imaging agent release in companion diagnostic applications.
- Coatings:Ceramic microspheres provide thermal barrier protection in aerospace propulsion systems manufactured across French and Italian clusters.
- Additives:Functional microspheres modify viscosity, opacity, or mechanical properties in industrial formulations.
- Fillers:Density-reduction applications in construction and automotive composites where cost-per-unit-volume drives specification.
Fillers dominate current volumes; drug delivery applications are expanding most quickly.
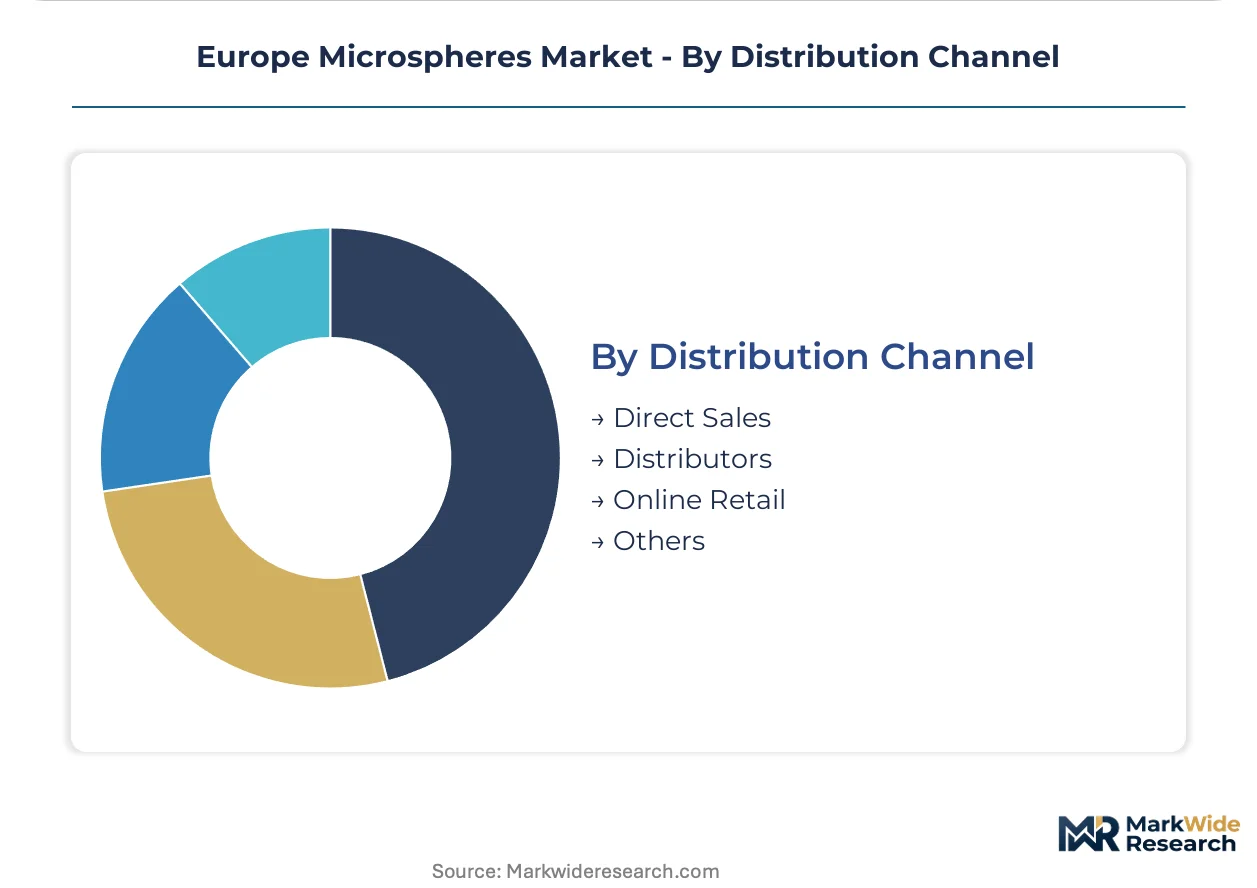
Distribution Channel:
Supply chain configuration reflects buyer scale, technical support needs, and regulatory documentation requirements.
- Direct Sales:Large pharmaceutical and automotive manufacturers negotiate qualified-source contracts with technical service agreements and 36-month supply guarantees. German converters anchor this channel through integrated supply relationships.
- Distributors:Regional stocking points serve mid-tier cosmetics and construction formulators requiring smaller lot sizes and faster turnaround.
- Online Retail:Catalog sales for research-grade microspheres and pilot-scale quantities in academic and early-stage development settings.
- Others:Agent-based representation in emerging Eastern European markets where local regulatory navigation accelerates market entry.
Direct sales channels capture the largest revenue share; distributor networks are climbing the fastest as Polish and Czech manufacturing clusters expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical and automotive clusters anchor procurement volumes across the European microsphere value chain. REACH compliance costs and MDR recertification timelines are redrawing supplier qualification maps. Warsaw and Krakow manufacturing bases are capturing contract development organization demand.
Germany
Automotive OEM lightweighting mandates and pharmaceutical formulator clusters drive hollow glass and polymer microsphere procurement. ECHA nanoscale toxicity dossiers extend compliance timelines for sub-micron grades. The Rhine-Main and Stuttgart engineering corridors concentrate qualified-source contracts with 36-month supply guarantees.
France
Aerospace propulsion thermal barrier coatings and oncology drug delivery systems pull ceramic and surface-engineered polymer microspheres. EMA medical device regulations tighten purity standards for implantable particulate materials. The Lyon-Saint-Étienne manufacturing belt advances sol-gel ceramic uniformity for coating applications.
Netherlands
Concentrated sodium silicate supply chains for hollow glass precursor chemistry create single-source leverage. EU Green Deal sustainable chemistry incentives accelerate bio-based PLA microsphere pilot scaling. Rotterdam-Antwerp chemical corridor infrastructure supports alkoxide chemistry integration.
Switzerland
Companion diagnostic applications and controlled-release oncology protocols command premium polymer microsphere grades. Swissmedic device regulations align with EMA standards for sub-micron spherical particle purity. Basel pharmaceutical formulation clusters adopt stimuli-responsive release kinetics for synchronized imaging.
Poland
Warsaw and Krakow contract development organizations attract oral dosage form microsphere suppliers seeking qualified manufacturing partners. REACH registration requirements for imported grades filter supplier entry. Distribution networks are climbing fastest as Eastern European pharmaceutical manufacturing expands.
Europe Microspheres Market Key Industry Players
Global majors compete with regional champions across qualified-source contract structures and REACH-compliant manufacturing footprints. The supplier base organizes into three tiers: integrated chemical conglomerates with captive precursor supply, specialized polymer microsphere formulators, and hollow glass converters dependent on external alkoxide feedstock. Strategic moves concentrate on M&A for manufacturing scale and technology licensing for surface-functionalization capabilities.
Among integrated chemical conglomerates, Nouryon anchors hollow glass precursor supply through alkoxide chemistry chain control. Evonik Industries exemplifies high-performance polymer microsphere manufacturing from German production bases. Momentive occupies a position within silicone resin microsphere formulations for thermal management applications. These three represent distinct competitive archetypes: upstream-integrated, performance-polymer focused, and application-specific thermal solutions.
| Leading Market Players |
|---|
| Nouryon |
| 3M |
| Merck KGaA |
| Evonik Industries |
| Sigmund Lindner |
| Momentive |
| Potters Industries |
| Trelleborg |
| Omya |
| Others |
Cost & Logistics Intelligence
EU Green Deal sustainable chemistry mandates gate qualified supply and premium-tier pricing access for European microsphere suppliers, as REACH-compliant bio-based polymer grades command price premiums while legacy formulations face margin compression from recertification costs. German automotive OEMs and Swiss pharmaceutical formulators now require ECHA-validated toxicity dossiers and lifecycle transparency documentation as table stakes for contract eligibility.
Pricing Analysis
Alkoxide precursor cost pass-through from concentrated sodium silicate supply chains in the Netherlands and Belgium directly shapes hollow glass microsphere pricing tiers. Three-tier pricing structure across REACH-certified premium, MDR-compliant standard, and economy filler grades reflects certification burden and purity thresholds. Cost compression in construction filler segments intensifies because silica fume substitution pressures spot-market pricing. Automotive battery enclosure specifications show least price sensitivity, while Southern European construction buyers exhibit highest elasticity to unit-volume quotes.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Hamburg anchor hub-and-spoke patterns for hollow glass and polymer microsphere fulfillment across European converter networks. Manufacturing gravity centers on Germany, the Netherlands, and France, with Polish distribution nodes climbing fastest for Eastern European pharmaceutical clusters. Raw material dependencies draw from concentrated sodium silicate feedstock, fermentation-based PHA biopolymer precursors, and sol-gel ceramic precursors. Single-source vulnerability in alkoxide chemistry creates structural exposure for converters without backward integration into precursor supply. Distribution runs through qualified-source direct contracts for automotive and pharmaceutical tiers, with regional distributors serving mid-scale cosmetics and construction formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration cost differentials between established Western European suppliers and emerging Polish manufacturing bases create geographic-arbitrage potential for qualified microsphere production capacity.
For Market Incumbents: Extend qualified-source contract coverage into 36-month supply guarantees with German and French automotive OEMs to lock out fermentation-based PHA entrants from bio-based substitution windows. Deepen captive alkoxide chemistry integration to neutralize single-source precursor vulnerability threatening hollow glass margin structures. For New Entrants and Emerging Players: Capture oral dosage form contract development organization demand in Warsaw and Krakow pharmaceutical clusters where REACH registration requirements filter incumbent supplier entry. Prioritize bio-based PLA microsphere pilot scaling with Horizon Europe funding qualification as the fastest penetration vector ahead of microplastic restriction enforcement. For Investors and Strategic Acquirers: Valuations sit cheapest among hollow glass converters without backward integration into alkoxide supply, presenting distressed manufacturing asset opportunities. Long-term viability favors performance-polymer formulators with EMA-validated MDR dossiers and stimuli-responsive release technology platforms. Watch ECHA delegated acts on implantable particulate materials as the critical regulatory inflection signal determining which microsphere grades retain market access versus face withdrawal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxide Precursor Supply | Nouryon's integrated chemistry chain eliminates sodium silicate single-source vulnerability for hollow glass production. |
| Bio-Based Polymer Qualification Program | PHA microsphere pilot scaling captures cosmetics switching demand ahead of ECHA microplastic restriction timelines. |
| EMA Medical Device Regulation Recertification | Swiss and German suppliers with validated MDR dossiers consolidate implantable particulate procurement share. |
| Long-Term Qualified-Source Supply Agreement | French and German OEM engineering teams lock 36-month silicone resin microsphere contracts for battery thermal management. |
| Joint Venture with Polish Contract Development Organization | Warsaw and Krakow manufacturing partnerships accelerate oral dosage form microsphere market entry with REACH-compliant local production. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer chemists at German and Swiss pharmaceutical formulators, procurement leads at French automotive OEMs, plant managers at Dutch alkoxide production facilities, and regulatory affairs specialists navigating ECHA dossier requirements. Secondary validation drew from EMA medical device submission databases, ECHA substance evaluation dossiers, Cefic chemical industry reports, and customs trade records for hollow glass and polymer microsphere flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates against qualified-source contract disclosures.
Segment-weighting approaches distributed value and volume projections across material type, end-use industry, application function, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis against automotive lightweighting mandate timelines, pharmaceutical pipeline progression, and construction sector filler substitution patterns. Industry-specific inputs included EMA MDR amendment schedules, EU Green Deal funding allocation trajectories, and ECHA restriction proposal enforcement calendars.
Underlying measurement precision varies by segment; biomedical drug delivery and automotive battery enclosure applications carry tighter precision than construction filler volumes where silica fume substitution creates demand elasticity. Forecasts reflect documented assumptions on regulatory timelines, funding program continuity, and OEM procurement consolidation behavior. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Polyester Medical Films Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global PE Films Market
Specialty Materials
Carbon Mold Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Hornbeam Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Electrode Paste Market