
 Tall Oil Fatty Acid Market | 2026-2036
Tall Oil Fatty Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Tall Oil Fatty Acid Market Analysis
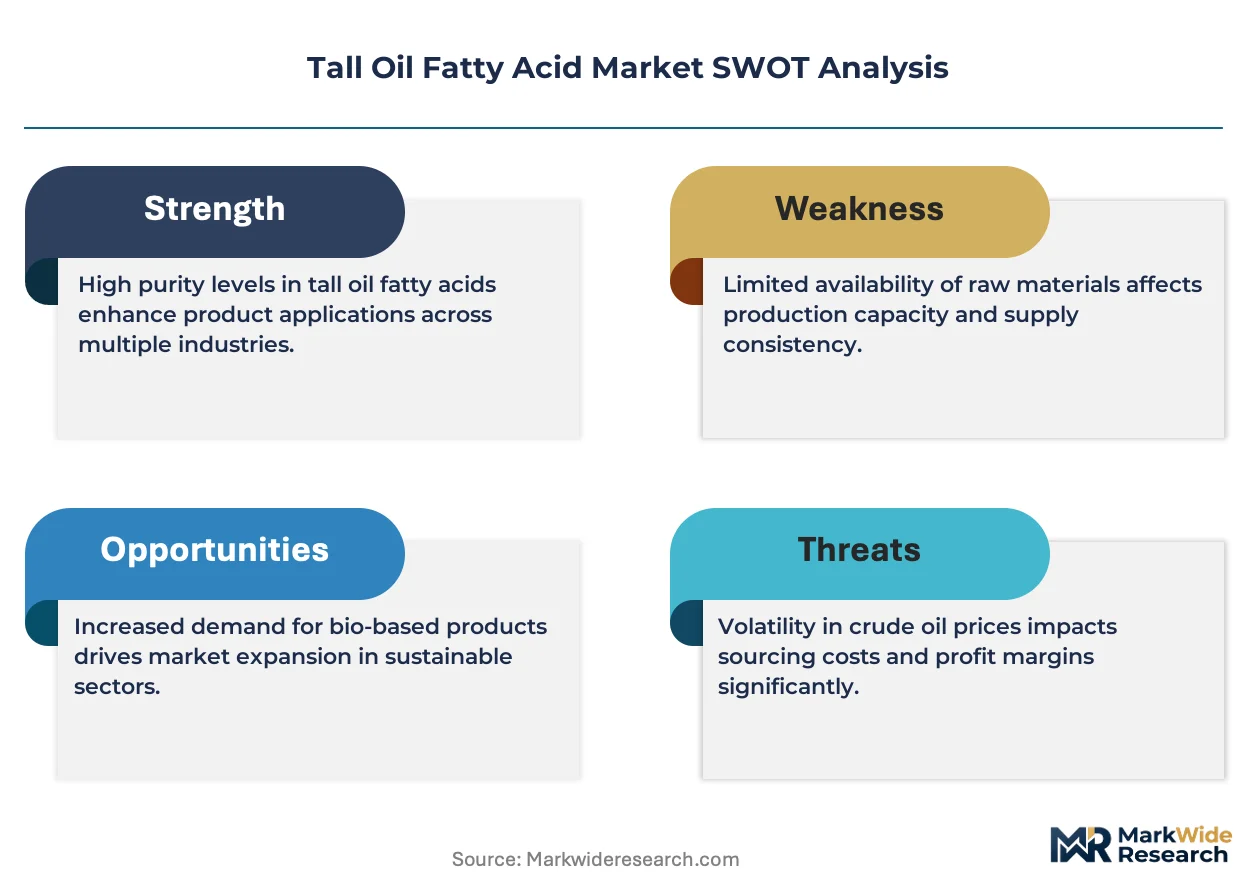
Coatings sector demand is hardening as architectural and industrial formulators shift toward alkyd resins with tall oil fatty acid backbones. Kraton Corporation leverages its integrated pine chemicals platform to sustain supply continuity across North American and European coatings customers. Eastman Chemical Company anchors its position through backward integration into kraft pulping operations, while Forchem Oyj competes via specialized distilled fatty acid grades for high-performance coating applications.
Tall oil fatty acid comprises a mixture of oleic, linoleic, and conjugated linoleic acids recovered from the black liquor of sulfate kraft pulping, typically containing 90-97% fatty acid content after distillation. These acids serve primarily as building blocks for alkyd resins, dimer acids, and surfactant intermediates where petrochemical displacement offers both cost and sustainability advantages. Distilled fatty acids dominate volume flows due to established supply chains and broad formulation compatibility, while refined fatty acids capture concentrated margin pools in personal care and food-grade applications. The emulsifiers segment within the application dimension is outpacing detergents as clean-label cosmetic formulations gain traction among European and North American brands.
The EPA governs effluent discharge from kraft pulping facilities under the Cluster Rule, directly constraining tall oil crude availability and extraction economics. REACH registration requirements in Europe mandate full substance characterization for imported fatty acid streams, creating compliance barriers for non-European suppliers. FDA food-contact regulations and FSSC 22000 certification standards shape qualification pathways for food processing and personal care end uses. Stakeholders must monitor pulp mill capacity decisions in the United States Southeast and Nordic regions, as these determine crude tall oil feedstock liquidity and subsequent fatty acid derivative pricing dynamics.
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across architectural and industrial applications, tightening specifications for tall oil fatty acid feedstocks while concentrating procurement around integrated pulp-to-chemical complexes.
Growth Catalysts
- REACH compliance mandates:European ECHA registration requirements for substance characterization are filtering out non-compliant imports and consolidating qualified supplier pools.
- Alkyd resin demand:Coatings formulators in the United States Gulf Coast cluster are expanding waterborne alkyd production lines to serve VOC-reduction targets.
- Kraft pulping integration:Backward integration into sulfate pulping operations secures captive crude tall oil supply and stabilizes extraction economics.
Market Restraints
- Crude tall oil concentration:United States Southeast pulp mill capacity decisions control feedstock liquidity and create pricing volatility for non-integrated processors.
- EPA Cluster Rule constraints:Effluent discharge limits on kraft pulping facilities directly cap crude tall oil availability and raise extraction costs.
- Petrochemical substitution:Soybean and rapeseed fatty acids compete on price in surfactant and dimer acid applications where sustainability premiums are weak.
Strategic Opportunities
- Clean-label cosmetics:European and North American personal care brands are qualifying refined tall oil fatty acids for emulsifier applications.
- Food-contact certification:FDA food-contact regulations and FSSC 22000 standards open qualification pathways for distilled fatty acid grades in packaging applications.
- Dual carbon alignment:China's MIIT dual carbon goals and EU Green Deal bio-based content mandates are elevating tall oil fatty acids in procurement specifications.
Industry Challenges
- REACH dossier preparation:Full substance characterization for imported fatty acid streams demands specialized regulatory affairs capacity and extended timelines.
- Pulp mill coordination:Extraction economics depend on sulfate pulping schedules, creating feedstock scheduling complexity for standalone fatty acid refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tall Oil Fatty Acid Market |
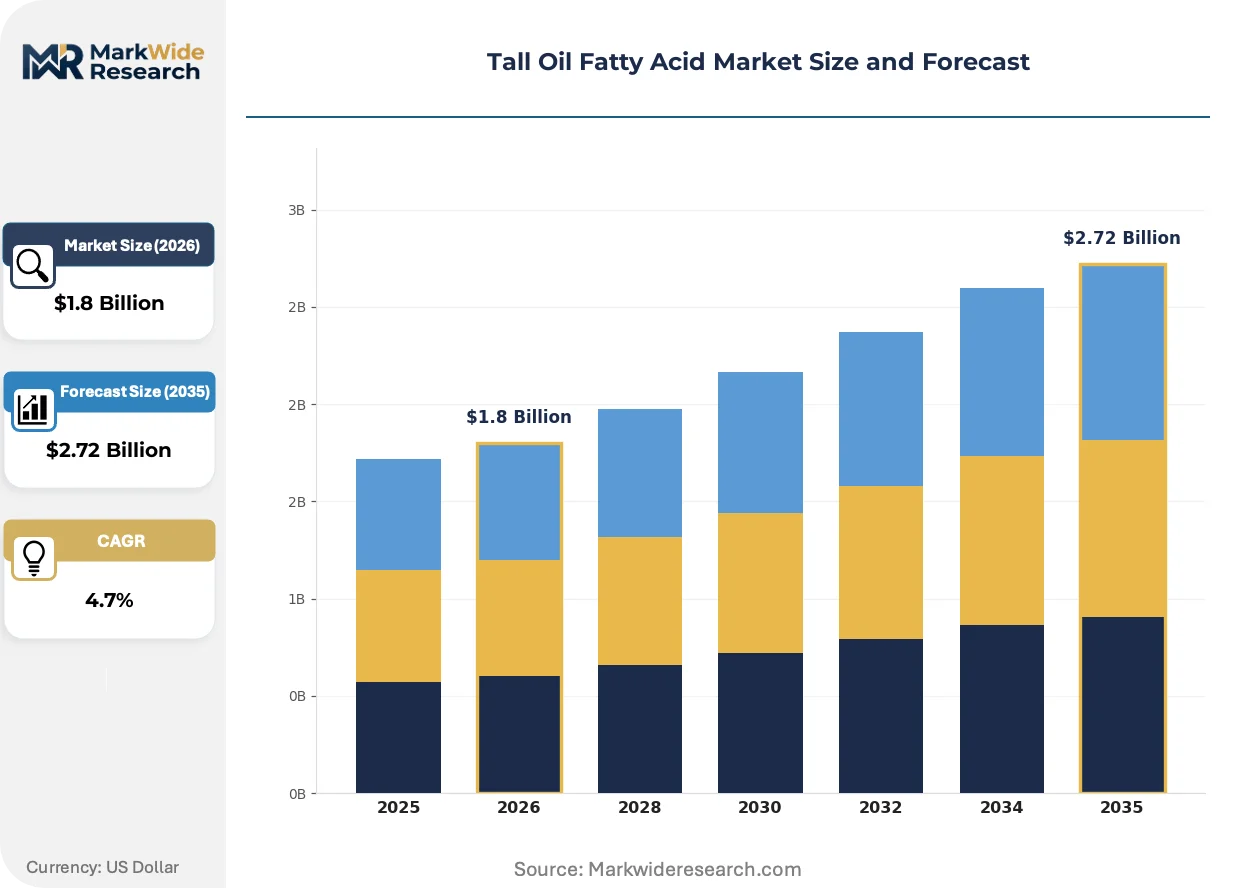
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fatty Acids, Distilled Fatty Acids, Crude Fatty Acids, Fatty Alcohols End User: Personal Care, Automotive, Food Processing, Coatings Application: Emulsifiers, Surfactants, Detergents, Lubricants Manufacturing Stage: Primary Processing, Secondary Processing, Refining, Blending |
| Companies Covered | NINGBO INNO PHARMCHEM CO.,LTD., Harima Chemicals Group, Inc., Kraton Corporation, Arizona Chemical Co., Eastman Chemical Company, Ingevity, Lascaray S.A., Segezha Group, Forchem Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tall Oil Fatty Acid Market Emerging Trajectories
Process intensification and regulatory stringency are reshaping competitive positioning across the tall oil fatty acid value chain, with sustainability verification and supply security emerging as primary differentiation vectors.
Membrane filtration technology for crude tall oil pretreatment is electrifying extraction efficiency at Scandinavian and United States Gulf Coast facilities. Kraft pulping complexes adopting ceramic membrane systems are reducing energy consumption in fatty acid recovery while improving distillate yields. This technology is compressing cost structures for integrated operators and widening the margin gap with non-integrated refiners.
The EU Green Deal bio-based content thresholds are mandating renewable feedstock shares in coatings and surfactant formulations. REACH registration deadlines for imported fatty acid streams are accelerating compliance investments among Asian exporters. European coatings formulators are responding by tightening supplier qualification protocols and favoring ECHA-registered domestic sources.
Direct mill-to-refiner contracting is displacing spot market procurement for crude tall oil across North American and Nordic supply chains. Coatings manufacturers are unbundling after-sales technical service from material supply agreements to secure formulation support independently. This pattern is most visible in Germany and the Netherlands, where alkyd resin producers are building dedicated technical service partnerships separate from feedstock purchasing.
Tall Oil Fatty Acid Market Segmentation
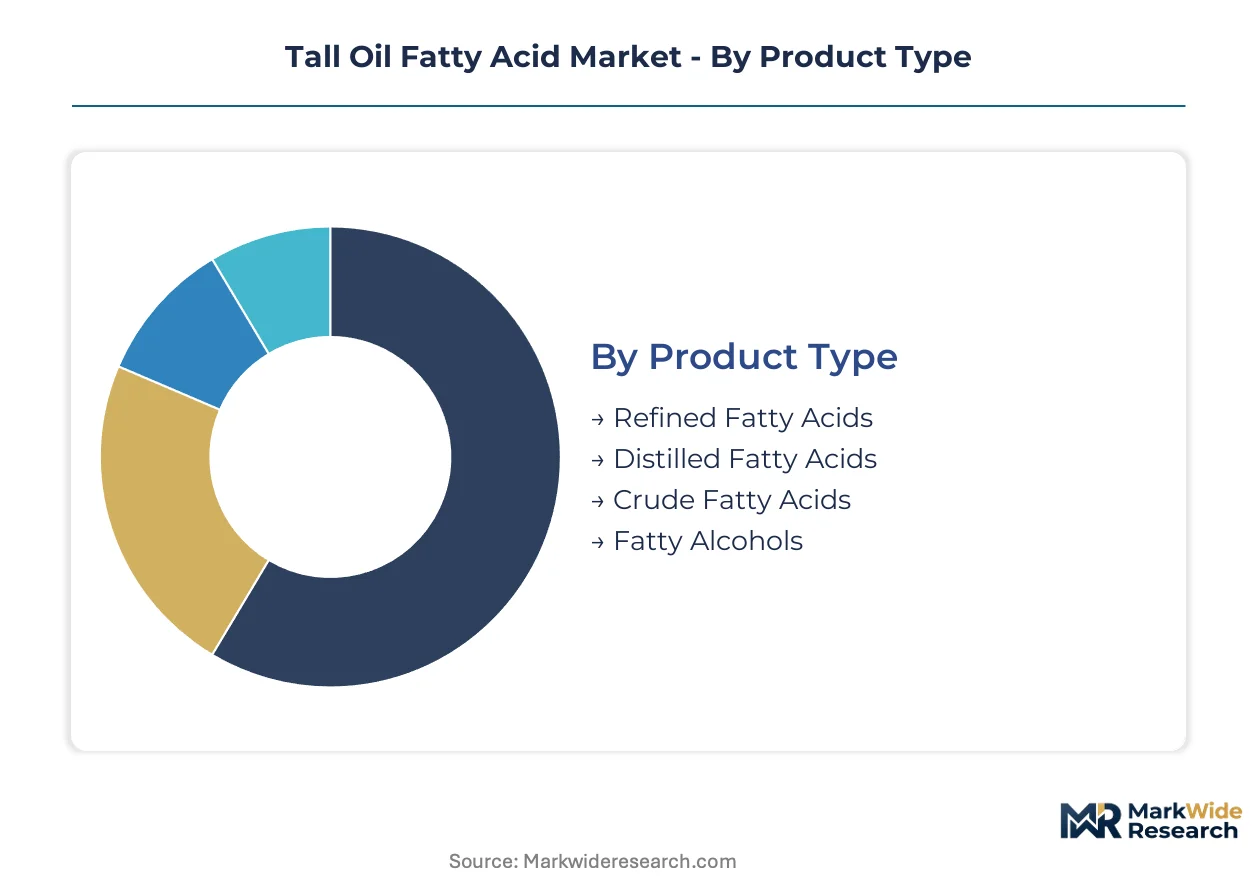
Segmentation in tall oil fatty acids reveals how procurement decisions split between specification-driven coatings buyers and cost-sensitive surfactant formulators. Product purity tiers and end-use certification requirements create distinct margin pools that reshape competitive positioning across the value chain.
Product Type:
Buyers select product grades based on formulation tolerance thresholds and regulatory compliance burdens rather than price alone.
- Distilled Fatty Acids:These grades contain 90-97% fatty acid content after vacuum distillation of crude tall oil, serving as the workhorse input for alkyd resin production. Demand concentrates among United States Gulf Coast coatings manufacturers who require consistent oleic/linoleic ratios for waterborne formulation stability.
- Refined Fatty Acids:Further purification removes rosin acids and unsaponifiables to meet food-contact and personal care specifications. European emulsifier producers in Germany and the Netherlands are qualifying these grades for clean-label cosmetic applications under REACH-registered supply chains.
- Crude Fatty Acids:Unfractionated streams with higher rosin content serve intermediate processors with in-house distillation capacity.
- Fatty Alcohols:Hydrogenated derivatives feed surfactant and detergent applications where petrochemical displacement commands sustainability premiums.
Distilled fatty acids lead on scale; refined fatty acids lead on momentum.
End User:
Application-specific certification requirements fragment procurement patterns across customer verticals.
- Coatings:Architectural and industrial formulators drive specification tightening as VOC regulations accelerate waterborne alkyd adoption. United States Gulf Coast clusters anchor volume concentration.
- Personal Care:Clean-label cosmetic brands in France and the United States are qualifying tall oil-derived emulsifiers as alternatives to petrochemical surfactants.
- Automotive:Specialty lubricant and coating applications demand consistent fatty acid profiles for thermal stability in underhood environments.
- Food Processing:FDA food-contact regulations and FSSC 22000 certification constrain supplier pools to refined grades with full traceability documentation.
Coatings commands volume concentration; personal care captures the steepest expansion trajectory.
Application:
Functional performance requirements determine grade selection more than raw material cost differentials.
- Emulsifiers:Refined tall oil fatty acids enable stable oil-in-water systems for cosmetics and food applications. European formulators are expanding procurement of bio-based emulsifiers under EU Green Deal content mandates.
- Surfactants:Dimer acids and their derivatives serve industrial cleaning and oilfield applications where petrochemical substitution offers both cost and sustainability positioning.
- Detergents:Price competition from soybean and rapeseed fatty acids constrains tall oil penetration in commodity laundry applications.
- Lubricants:Ester derivatives from distilled grades provide biodegradability advantages in marine and agricultural equipment.
Surfactants anchor established revenue; emulsifiers gain share fastest.
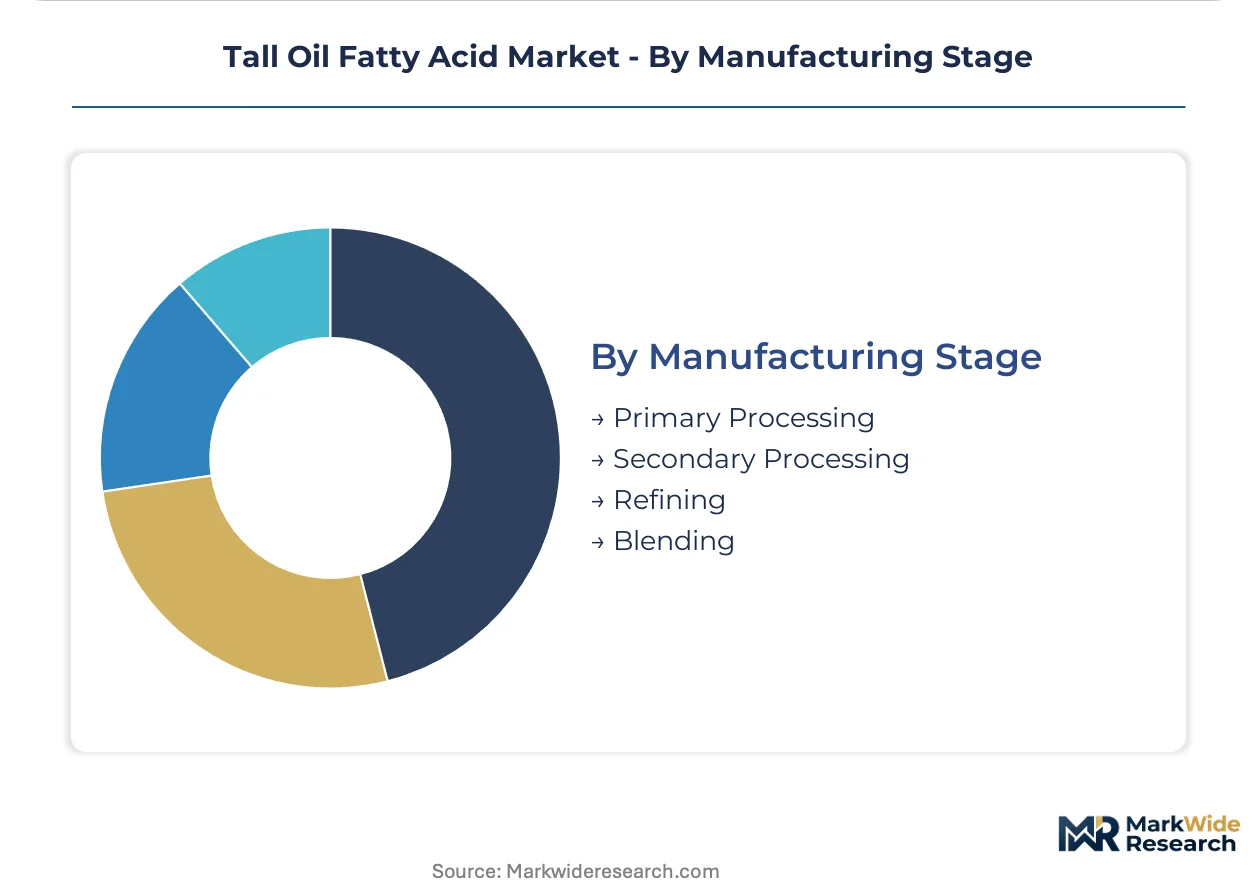
Manufacturing Stage:
Integration depth into kraft pulping operations determines cost position and supply security.
- Primary Processing:Crude tall oil extraction from black liquor at sulfate pulp mills represents the highest-margin captive position for integrated operators.
- Secondary Processing:Distillation and fractionation separate fatty acids from rosin and pitch fractions, requiring capital-intensive vacuum equipment.
- Refining:Bleaching, hydrogenation, and purification steps achieve food-contact and personal care specifications with batch processing economics.
- Blending:Final formulation with additives and diluents serves just-in-time delivery requirements for coatings and surfactant customers.
Primary processing captures margin concentration; refining offers the fastest value-add expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting investment toward jurisdictions where EPA Cluster Rule compliance costs remain manageable and kraft pulping capacity offers captive feedstock security. Producers face divergent compliance burdens across major manufacturing zones.
United States
Waterborne alkyd resin demand from Gulf Coast coatings manufacturers is tightening specifications for distilled fatty acid grades. EPA Cluster Rule effluent limits constrain crude tall oil extraction economics at Southeast pulp mills. Integrated pulp-to-chemical complexes in Louisiana and Texas anchor supply security for domestic formulators.
Finland
EU Green Deal bio-based content mandates are elevating tall oil fatty acids in coatings procurement specifications. REACH registration requirements filter non-compliant imports and consolidate qualified supplier pools around ECHA-registered domestic sources. Forchem Oyj's distillation facilities in Rauma exemplify specialized grade production for high-performance applications.
Sweden
Membrane filtration adoption at sulfate pulping complexes is electrifying extraction efficiency and improving distillate yields. ECHA substance characterization protocols extend timelines for imported fatty acid stream qualification. Segezha Group's integrated operations leverage Scandinavian pulp mill coordination for feedstock scheduling stability.
Germany
Clean-label cosmetic brands in North Rhine-Westphalia are qualifying refined tall oil fatty acids for emulsifier applications. REACH dossier preparation demands specialized regulatory affairs capacity from suppliers serving personal care formulators. Alkyd resin producers in the Ruhr region are building dedicated technical service partnerships separate from feedstock purchasing.
Japan
Specialty lubricant applications demand consistent fatty acid profiles for thermal stability in automotive underhood environments. METI industrial standards shape qualification pathways for refined grades in precision manufacturing. Harima Chemicals Group's positioning reflects regional emphasis on high-purity derivative production.
Tall Oil Fatty Acid Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-chemical operators commanding margin concentration while standalone refiners compete on grade flexibility. Three to five vertically integrated entities anchor supply security through captive crude tall oil access. Strategic archetypes include kraft pulping-integrated chemical producers, specialized distillation refiners, and regional formulation service providers. Dominant competitive moves encompass backward integration into sulfate pulping operations and membrane filtration technology licensing for extraction efficiency gains.
Among North American integrated operators, Kraton Corporation and Eastman Chemical Company exemplify the pulping-integrated archetype that secures captive feedstock and stabilizes extraction economics. Forchem Oyj represents the specialized distillation tier competing via high-purity grades for coatings and personal care applications where REACH-registered supply chains command premium positioning. These three entities anchor the competitive structure across distinct geographic and specification vectors.
| Leading Market Players |
|---|
| NINGBO INNO PHARMCHEM CO.,LTD. |
| Harima Chemicals Group, Inc. |
| Kraton Corporation |
| Arizona Chemical Co. |
| Eastman Chemical Company |
| Ingevity |
| Lascaray S.A. |
| Segezha Group |
| Forchem Oyj |
| Others |
Supply Flow & Price Mechanics
Waterborne alkyd resin procurement specifications from United States Gulf Coast coatings manufacturers are tightening fatty acid purity requirements and compressing acceptable cost bands for non-integrated refiners. This specification hardening forces supply consolidation around kraft pulping-integrated operators with captive crude tall oil access, elevating their pricing power against standalone processors dependent on spot feedstock markets.
Pricing Analysis
Direct mill-to-refiner contracting eliminates distributor margins for volume coatings buyers, while spot market premiums persist for non-integrated refiners serving specialty emulsifier applications. Three-tier pricing structure across food-contact certified, REACH-registered, and standard industrial grades reflects compliance burden differentials. Pricing pressure stems from soybean and rapeseed fatty acid substitution in commodity surfactant segments. Surfactant formulators exhibit highest price sensitivity; personal care brands accepting sustainability premiums show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale coatings demand from United States Gulf Coast formulators, while specialty distributors serve European personal care and food-contact customers. Supply concentrates in the United States, Finland, and Sweden where kraft pulping complexes anchor feedstock security. Crude tall oil, sulfuric acid for acidulation, and hydrogenation catalysts constitute critical input dependencies. Single-source vulnerability runs through United States Southeast pulp mill capacity decisions. Distribution runs through integrated chemical producers with in-house distillation and regional formulation service partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration deadlines and EPA Cluster Rule compliance milestones are systematically filtering supplier pools and consolidating demand around qualified integrated operators.
For Market Incumbents: Deepen backward integration into sulfate pulping operations to secure captive crude tall oil supply against Southeast pulp mill capacity volatility. Expand membrane filtration licensing to non-integrated refiners, converting competitive threat into royalty revenue while preserving margin concentration in high-specification grades. For New Entrants and Emerging Players: E-commerce qualification platforms for REACH-registered specialty grades offer the lowest barrier entry path. Clean-label cosmetic emulsifiers in Germany and the Netherlands present the most penetrable white space, with food-contact certification services as the differentiated go-to-market anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized distillation refiners possessing ECHA-registered supply chains and established personal care customer relationships. Long-term viability favors operators with dual access to United States and Nordic pulp mill networks. Pulp mill capacity expansion announcements in the United States Southeast serve as the critical inflection signal for feedstock liquidity and derivative pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulping | Captive crude tall oil supply insulates Kraton and Eastman from Southeast pulp mill volatility. |
| Membrane Filtration Technology Licensing | Ceramic membrane adoption at Scandinavian facilities compresses energy costs and widens yield advantages. |
| REACH Registration Acceleration | ECHA-compliant dossiers filter Asian imports and consolidate European supplier pools around domestic sources. |
| Food-Contact Certification Investment | FDA and FSSC 22000 pathways open packaging applications for refined grades with full traceability documentation. |
| Long-Term Supply Agreements with Coatings Formulators | Direct contracting with Gulf Coast alkyd producers displaces spot procurement and stabilizes volume commitments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with kraft pulping operations managers, coatings procurement leads at Gulf Coast formulators, personal care R&D directors, and specialty chemical distribution partners with secondary validation from customs trade data, AF&PA pulp production statistics, ECHA registration databases, and SEC filings from integrated chemical producers. Bottom-up volume builds across product grades and end-use applications were cross-checked against top-down market sizing from trade flow analysis.
Historical reference periods spanning installed capacity utilization, pulp mill operating rates, and fatty acid derivative trade volumes anchored the projection framework across the analysis window. Segmentation modeling captured product type tiers, end-user industry verticals, application functional categories, and manufacturing stage integration depth. CAGRs were derived from trend extrapolation of specification-driven demand shifts and regulatory compliance timelines, with inputs from waterborne coatings adoption curves and bio-based content mandate implementation schedules.
Pulp mill capacity closures, REACH enforcement intensity variations, and petrochemical fatty acid price volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory implementation consistency and substitution elasticity in surfactant applications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Wood Preservative Market