
 Global Alkylated Naphthalene Market | 2026-2036
Global Alkylated Naphthalene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alkylated Naphthalene Market Foresight
Buyer concentration in the lubricant blending sector is shifting as multinational oil companies consolidate supplier lists while independent specialty blenders fragment procurement across regional alkylated naphthalene producers. ExxonMobil Corporation leverages integrated refining and synthesis capabilities to anchor supply contracts with major industrial OEMs. Huntsman Corporation competes through specialized high-purity grades for aerospace and marine applications. King Industries Inc. differentiates via custom additive packages that incorporate alkylated naphthalene bases for niche metalworking segments.
Alkylated naphthalene denotes a class of synthetic aromatic hydrocarbons produced through Friedel-Crafts alkylation of naphthalene with olefins, yielding products with viscosity indices exceeding 120 and pour points below minus 40 degrees Celsius for high-performance lubricant formulations. The monoalkylated naphthalene category dominates current volume as the preferred base stock for transformer oils requiring oxidative stability and low gas evolution. Polyalkylated naphthalene represents the fastest-growing structural segment as industrial machinery operators seek extended drain intervals under severe operating temperatures. Marine equipment applications concentrate margin pools where classification society approvals command formulation premiums.
EPA fuel economy and emissions standards in the United States, REACH chemical registration requirements in Europe, and China's GB standards for transformer oil performance collectively shape product specifications and market access conditions for alkylated naphthalene suppliers. ECHA substance evaluation protocols are tightening purity thresholds for long-chain alkylated naphthalene isomers used in metalworking fluid formulations. Stakeholders must monitor evolving lubricant sustainability certifications and regional carbon border adjustments to align product portfolios with procurement criteria that industrial end users are embedding into supplier qualification frameworks.
Market Dynamics
OEM fill-for-life lubricant specifications are compressing reformulation cycles and forcing base stock suppliers to pre-certify alkylated naphthalene grades against multiple industrial standards simultaneously. This specification tightening is concentrating procurement authority among lubricant blenders with in-house testing capabilities.
Growth Catalysts
- REACH substance evaluation protocols:ECHA purity mandates for metalworking fluid formulations are redirecting European demand toward high-grade alkylated naphthalene variants with verified isomer profiles.
- Transformer oil performance standards:China's GB standards for power infrastructure renewal are mandating oxidative stability thresholds that monoalkylated naphthalene base stocks uniquely satisfy.
- Marine classification society approvals:Lloyd's Register and DNV vessel equipment specifications command formulation premiums for polyalkylated naphthalene in severe-temperature marine applications.
Market Restraints
- Naphthalene feedstock volatility:Coal tar and petroleum-derived naphthalene supply fluctuations in China create input cost instability for integrated producers.
- Long-chain isomer purification limits:Current fractional distillation technologies face technical ceilings separating targeted alkylated naphthalene isomers from residual olefin contaminants.
- PAO and ester synthetic base stock substitution:Polyalphaolefin and diester formulations compete for high-temperature automotive lubricant applications with comparable viscosity index performance.
Strategic Opportunities
- Bio-based alkylated naphthalene variants:EU Green Deal carbon intensity rules are creating procurement preference for renewable feedstock-derived aromatic base stocks in German industrial lubricant blending.
- Extended drain interval formulations:Severe-duty mining and construction equipment operators in Australia are adopting polyalkylated naphthalene blends to reduce maintenance downtime.
- Additive package integration:Custom alkylated naphthalene-incorporating metalworking fluid systems offer margin expansion for specialty chemical distributors serving precision manufacturing clusters.
Industry Challenges
- Friedel-Crafts alkylation process engineering expertise:Limited availability of chemical engineers with specialized aromatic hydrocarbon synthesis experience constrains capacity expansion timelines.
- Multi-jurisdiction certification synchronization:Lubricant blenders must align EPA fuel economy, REACH registration, and GB transformer oil standards simultaneously for global OEM supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alkylated Naphthalene Market |
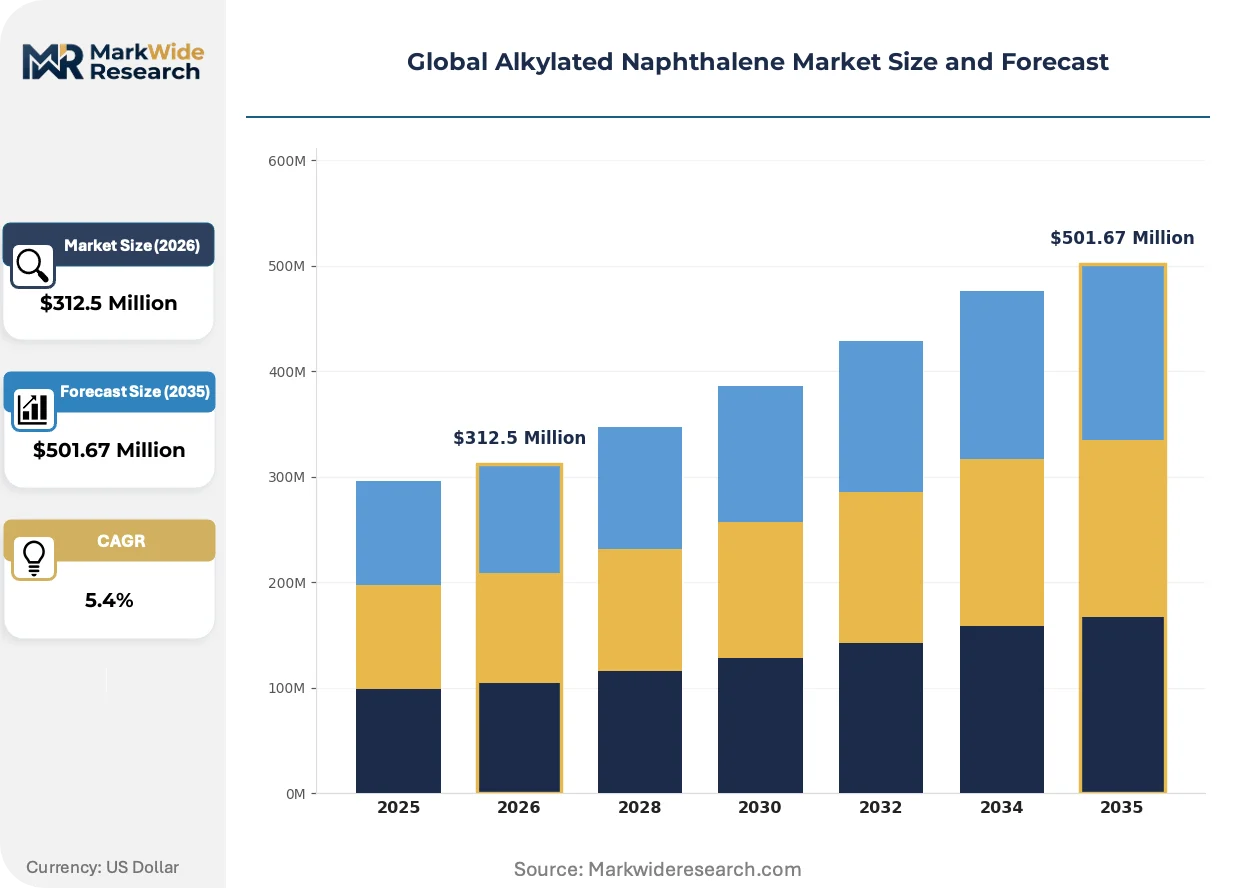
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoalkylated Naphthalene, Dialkylated Naphthalene, Trialkylated Naphthalene, Polyalkylated Naphthalene Application: Lubricants, Transformer Oils, Hydraulic Fluids, Metalworking Fluids, Greases End User Industry: Power Generation, Marine Equipment, Aerospace Manufacturing, Industrial Machinery Packaging Type: Drums, Intermediate Bulk Containers, Bulk Tankers, Pails |
| Companies Covered | ExxonMobil Corporation, Huntsman Corporation, Quaker Chemical Corporation, King Industries Inc., Kao Corporation, Akzo Nobel N.V., NACO Corporation, Nease Performance Chemicals, NOVITAS CHEM SOLUTIONS, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alkylated Naphthalene Market Shifts & Advancements
Continuous catalytic alkylation process intensification is compressing production economics while bio-based feedstock substitution is opening parallel supply pathways. These dual technical trajectories are fragmenting competitive advantage sources across the value chain.
Membrane-assisted reactive distillation for alkylated naphthalene purification is decentralizing high-purity production away from integrated refinery complexes. Independent specialty chemical producers in the United States and Germany are adopting modular membrane units to achieve pharmaceutical-grade isomer separation without billion-dollar capital commitments. This technology diffusion is enabling regional producers to challenge established supply relationships with precision manufacturing end users.
EU Green Deal carbon border adjustment mechanisms are tightening embodied carbon documentation requirements for imported synthetic base stocks. European lubricant formulators are now demanding cradle-to-gate lifecycle assessments from alkylated naphthalene suppliers, with German automotive OEMs embedding carbon intensity thresholds into supplier qualification frameworks. This regulatory pressure is accelerating capital allocation toward bio-based naphthalene feedstock development.
Industrial end users are consolidating lubricant procurement under outcome-based performance contracts rather than volume-based supply agreements. Mining operators in Western Australia and power utilities in Texas are shifting payment structures toward guaranteed equipment uptime metrics, forcing alkylated naphthalene suppliers to co-develop application-specific formulations with lubricant blenders. This contractual evolution is compressing supplier margins while extending technical service obligations upstream.
Global Alkylated Naphthalene Market Segmentation
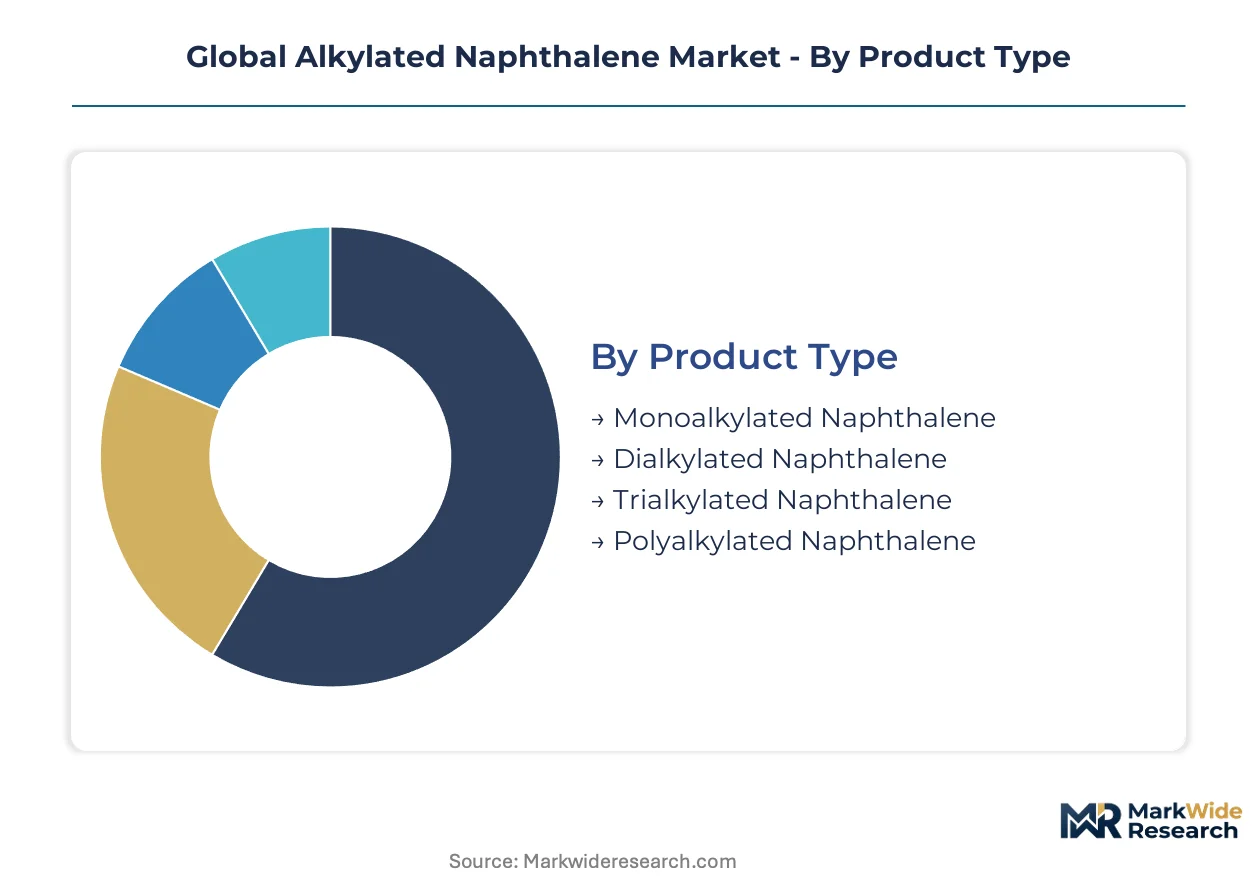
Alkylated naphthalene procurement patterns diverge sharply between standalone base stock purchases and fully formulated lubricant systems. Understanding these integration pathways clarifies where suppliers capture margin versus where they cede value to downstream blenders.
Product Type:
Integration depth varies substantially across alkylation degrees, with monoalkylated grades dominating direct base stock sales while polyalkylated variants embed primarily in finished formulations.
- Monoalkylated Naphthalene:Single-olefin substitution yields products with exceptional oxidative stability and minimal gas evolution under electrical stress. Procurement concentrates in Chinese power infrastructure renewal programs where GB transformer oil standards mandate these specifications.
- Polyalkylated Naphthalene:Multiple olefin attachments create higher viscosity index base stocks with pour points below minus 40 degrees Celsius. Mining operators in Western Australia specify these grades for extended drain interval contracts in severe-temperature hydraulic systems.
- Dialkylated Naphthalene:Dual-substitution structures occupy intermediate performance tiers in marine lubricant formulations requiring Lloyd's Register thermal stability certification.
- Trialkylated Naphthalene:Triple-alkylation produces specialized grades for aerospace manufacturing where MIL-PRF-23699 turbine oil specifications apply.
Volume placements concentrate in monoalkylated naphthalene for electrical applications; the faster expansion belongs to polyalkylated naphthalene in severe-duty industrial lubricants.
Application:
Cost tier differentiation separates commodity-grade transformer oils from premium-formulated metalworking systems, with pricing spreads reflecting certification burden and technical service intensity.
- Lubricants:Automotive and industrial lubricant formulators specify alkylated naphthalene base stocks for OEM fill-for-life programs. German automotive OEMs embed carbon intensity thresholds into supplier qualification frameworks for these applications.
- Metalworking Fluids:Precision manufacturing clusters demand custom additive packages incorporating alkylated naphthalene bases for high-pressure cutting operations. ECHA substance evaluation protocols are tightening purity thresholds for long-chain isomer profiles in these formulations.
- Transformer Oils:Electrical insulation applications prioritize oxidative stability and low gas evolution under thermal cycling stress.
- Hydraulic Fluids:Construction and mining equipment operators seek extended drain intervals under high-pressure operating conditions.
- Greases:Thickener compatibility requirements limit alkylated naphthalene penetration in conventional lithium-complex formulations.
Revenue concentration sits in lubricant base stocks; metalworking fluid systems are climbing the fastest as precision manufacturing reshoring accelerates.
End User Industry:
Customer type fragmentation separates consolidated utility procurement from fragmented industrial maintenance budgets, with contract structures varying from volume-based supply to outcome-based performance guarantees.
- Power Generation:State Grid Corporation of China and Texas utilities consolidate transformer oil procurement under multi-year framework agreements. GB standards for oxidative stability and EPA spill prevention requirements shape specification compliance simultaneously.
- Industrial Machinery:Fragmented maintenance departments across German precision manufacturing clusters purchase through specialty chemical distributors. EU Green Deal carbon border adjustment mechanisms are tightening embodied carbon documentation requirements for these buyers.
- Marine Equipment:Classification society approvals from Lloyd's Register and DNV command formulation premiums in vessel equipment specifications.
- Aerospace Manufacturing:MIL-PRF-23699 and AS5780 standards constrain supplier qualification to pre-certified base stock producers.
Contract value concentrates in power generation procurement; aerospace manufacturing specifications are expanding most quickly as supply chain security concerns intensify.
Packaging Type:
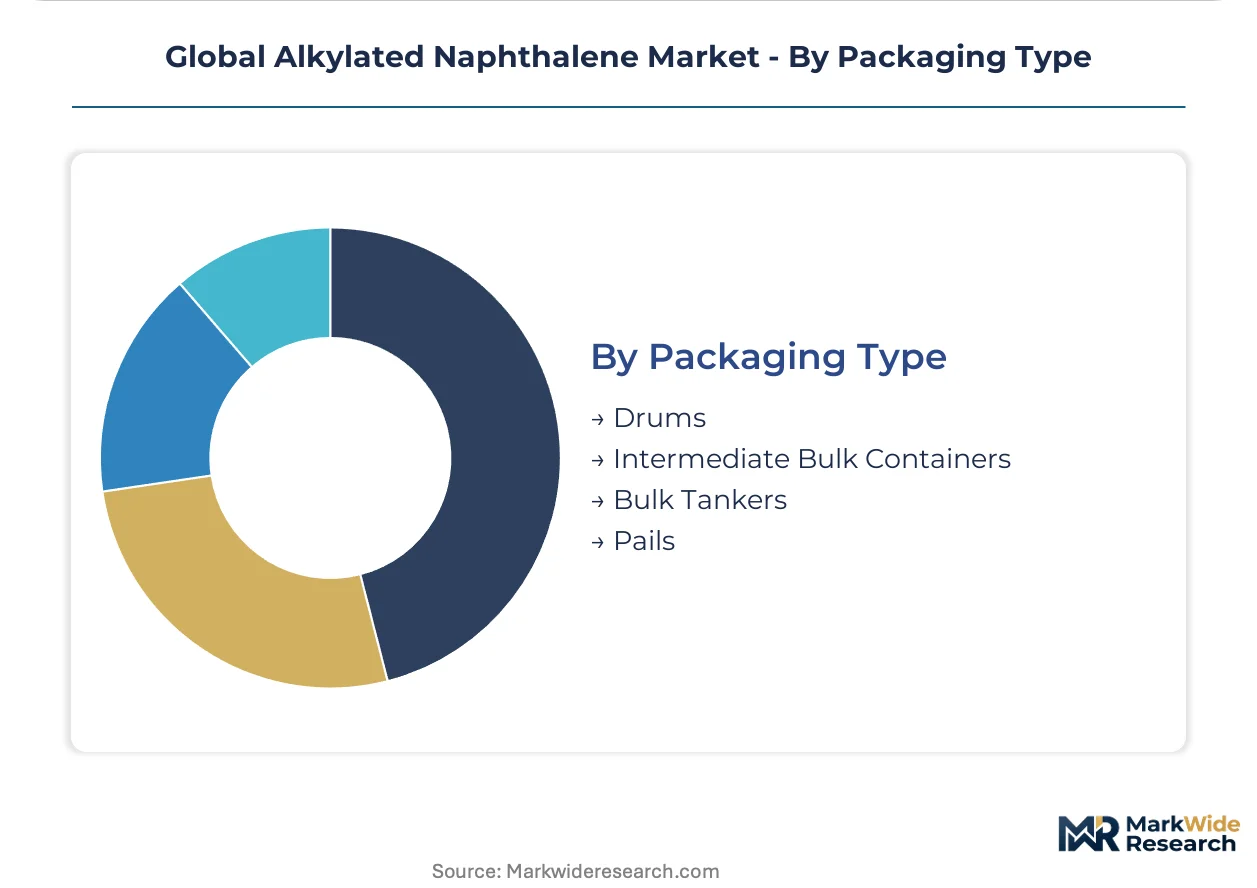
Supply concentration in integrated refinery complexes favors bulk logistics, while membrane-assisted purification technology is enabling regional drum and IBC distribution from decentralized production units.
- Bulk Tankers:Integrated producers like ExxonMobil leverage captive refining and synthesis capabilities for direct-to-blender bulk delivery. Marine terminal access in Houston and Rotterdam anchors these supply relationships.
- Intermediate Bulk Containers:Modular membrane purification units in the United States and Germany enable regional specialty producers to serve precision manufacturing clusters without billion-dollar capital commitments.
- Drums:Standard 200-liter packaging serves fragmented metalworking fluid compounders in secondary industrial zones.
- Pails:Small-volume packaging addresses niche aerospace maintenance, repair, and overhaul operations.
Shipment volumes concentrate in bulk tanker logistics; IBC formats are gaining share fastest as decentralized high-purity production diffuses across regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal tar naphthalene availability in Shanxi Province anchors Chinese production economics. Petroleum-derived feedstock corridors in the US Gulf Coast and Rotterdam-Antwerp refining clusters supply integrated European and North American alkylated naphthalene synthesis.
China
State Grid Corporation of China procures monoalkylated naphthalene base stocks for transformer oil specifications under GB standards mandating oxidative stability. MEE dual carbon goals tighten embodied carbon thresholds for imported synthetic base stocks. Shanghai and Jiangsu province lubricant blenders concentrate procurement authority for industrial OEM fill-for-life programs.
Germany
Automotive OEMs in Stuttgart and Munich embed carbon intensity thresholds into supplier qualification frameworks for lubricant formulators. EU Green Deal carbon border adjustment mechanisms redirect procurement toward bio-based alkylated naphthalene variants. REACH substance evaluation protocols from ECHA tighten purity mandates for metalworking fluid formulations in the Ruhr industrial cluster.
United States
Texas power utilities consolidate transformer oil procurement under multi-year framework agreements requiring EPA spill prevention compliance. Houston marine terminal access anchors integrated refinery supply relationships with industrial lubricant blenders. EPA fuel economy standards compress reformulation cycles for automotive lubricant base stock pre-certification.
Japan
METI industrial standards shape precision manufacturing lubricant specifications for alkylated naphthalene metalworking fluid systems. Kansai region specialty chemical distributors serve fragmented maintenance departments across Osaka and Kyoto manufacturing clusters. JIS standards constrain supplier qualification for high-purity isomer grades in aerospace applications.
Australia
Mining operators in Western Australia adopt polyalkylated naphthalene blends for extended drain interval contracts under severe-temperature hydraulic system demands. TGA chemical registration requirements align with OECD guidelines for industrial lubricant base stock import documentation. Perth-based equipment maintenance contractors consolidate procurement under outcome-based performance guarantees.
Global Alkylated Naphthalene Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock differentiation and modular purification technology licensing. The supplier base concentrates around integrated petroleum refiners with captive aromatic hydrocarbon synthesis capabilities and independent specialty chemical producers with regional membrane-assisted distillation units. Three archetypes dominate: integrated oil majors with backward refining control, mid-cap specialty chemical houses with custom formulation expertise, and technology-focused independents with decentralized high-purity production. Competitive moves center on multi-jurisdiction certification synchronization and strategic partnerships with lubricant blenders for co-developed application-specific formulations.
Within the integrated petroleum refining tier, ExxonMobil Corporation anchors supply relationships through captive naphthalene feedstock access and direct-to-blender bulk logistics. Huntsman Corporation exemplifies the specialty chemical archetype with positioning around high-purity grades for regulated aerospace and marine applications. King Industries Inc. occupies the additive package integration segment, incorporating alkylated naphthalene bases into custom metalworking fluid systems for niche precision manufacturing end users.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Huntsman Corporation |
| Quaker Chemical Corporation |
| King Industries Inc. |
| Kao Corporation |
| Akzo Nobel N.V. |
| NACO Corporation |
| Nease Performance Chemicals |
| NOVITAS CHEM SOLUTIONS, LLC. |
| Others |
Supply & Pricing Matrix
Chemical engineers with Friedel-Crafts alkylation expertise in the US Gulf Coast and Germany command wage premiums that compress margins on standard-grade monoalkylated naphthalene while widening spreads for pharmaceutical-isomer grades. Labor-cost differentials between integrated refinery complexes and modular membrane-assisted purification units in regional markets stratify pricing tiers across the value chain.
Pricing Analysis
Volume placements in monoalkylated transformer oil grades generate thin margins through bulk contract structures, while polyalkylated naphthalene for marine and aerospace certification commands premium pricing. Three-tier pricing structure across pharmaceutical-isomer, industrial-grade, and commodity transformer oil levels separates buyers by certification burden and technical service intensity. Pricing pressure stems from PAO and diester substitution in high-temperature automotive applications. Power utilities in China and Texas exhibit lowest price sensitivity due to multi-year framework agreements, while fragmented metalworking fluid compounders in secondary industrial zones face acute cost compression.
Supply Chain Analysis
Direct-to-blender channels handle integrated producer volumes from Houston and Rotterdam refinery complexes, while specialty distributors serve precision manufacturing clusters through IBC and drum formats. Production concentrates in China, the United States, and Germany where coal tar naphthalene availability, petroleum-derived feedstock corridors, and membrane purification technology clusters anchor supply. Raw material dependencies rest on naphthalene from coal tar distillation and petroleum refining, olefin feedstocks for alkylation, and catalyst systems for Friedel-Crafts synthesis. Single-source vulnerability around Chinese coal tar naphthalene supply creates input cost instability. Distribution runs through bulk marine terminals, regional chemical distributors, and direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alkylated naphthalene sector sits in a technology-transition phase as membrane-assisted reactive distillation displaces conventional fractional distillation for high-purity isomer separation. Bio-based feedstock pathways are replacing petroleum-derived naphthalene in European procurement frameworks under EU Green Deal carbon intensity rules.
For Market Incumbents: Extend certification synchronization capabilities across EPA fuel economy, REACH registration, and GB transformer oil standards simultaneously to defend against emerging modular producers. Anchor supply relationships through captive feedstock access and direct-to-blender bulk logistics. Invest in backward integration into bio-based naphthalene feedstock development to preempt EU carbon border adjustment mechanisms. For New Entrants and Emerging Players: Membrane-assisted purification technology licensing offers entry into pharmaceutical-grade isomer segments without billion-dollar refinery capital commitments. White-space targets include precision manufacturing clusters in Germany and aerospace maintenance operations requiring MIL-PRF-23699 certified grades. Pursue joint development agreements with lubricant blenders for co-formulated extended drain interval systems. For Investors and Strategic Acquirers: Re-rating potential sits with technology-focused independents possessing decentralized high-purity production capabilities given accelerating procurement preference for regional supply security. Long-term viability favors producers with dual petroleum and bio-based feedstock pathways. Monitor ECHA substance evaluation protocol tightening for metalworking fluid purity thresholds as inflection indicator for high-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstock | EU Green Deal carbon intensity rules redirect German automotive OEM procurement toward renewable aromatic base stocks. |
| Membrane Purification Technology Licensing | Modular units in the United States and Germany enable regional producers to challenge integrated refinery supply relationships. |
| Multi-Jurisdiction Certification Synchronization | Simultaneous EPA, REACH, and GB standard compliance secures global OEM fill-for-life lubricant supply contracts. |
| Joint Development with Lubricant Blenders | Co-formulated extended drain interval systems capture outcome-based performance contracts from Western Australian mining operators. |
| Capacity Expansion in High-Purity Isomer Grades | ECHA purity mandates for metalworking fluids redirect European demand toward verified long-chain alkylated naphthalene profiles. |
Research Methodology
Document review covered trade flow databases, ECHA substance evaluation protocols, and SEC filings from integrated petroleum refiners, complemented by interviews with lubricant formulation chemists, procurement leads at power utilities, specialty chemical distributors, and plant managers at alkylated naphthalene synthesis facilities. Secondary validation drew from customs records, GB standards documentation, and Lloyd's Register classification society specifications. Bottom-up volume modeling across alkylation degrees and application segments triangulated against top-down market sizing from feedstock capacity analysis.
Segment-level projections incorporate alkylation degree, end-use industry, packaging format, and regional production hub across the modeling period. CAGRs derive from elasticity-adjusted demand curves calibrated to OEM fill-for-life specification tightening and power infrastructure renewal program timelines. Forecast inputs include naphthalene feedstock cost trajectories, membrane technology diffusion rates, and carbon border adjustment mechanism implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under coal tar naphthalene supply disruptions or accelerated PAO substitution in automotive applications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Global Industrial Separators Market