
 Sample Preparation Market | 2026-2036
Sample Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Sample Preparation Market Intelligence
Automated liquid handling is tilting sample preparation from bench-scale manual protocols to integrated robotic workstations. Thermo Fisher Scientific leverages its end-to-end platform breadth to anchor high-throughput proteomics workflows. Danaher Corporation sustains competitive density through its life sciences operating companies spanning filtration, centrifugation, and consumables. Agilent Technologies specializes in chromatography-coupled sample prep, occupying a defensible position in analytical method standardization.
Sample preparation encompasses the physical and chemical processing of raw specimens to render them compatible with downstream analytical techniques, typically involving homogenization, extraction, purification, and concentration steps that achieve defined purity thresholds and matrix compatibility for instruments such as mass spectrometers and sequencers. Centrifuges and filtration units retain the largest installed base, though microfluidics represents the fastest-expanding technology segment as labs miniaturize reaction volumes and reduce reagent costs. Automated systems command premium pricing relative to manual techniques, with margin pools deepest in pharmaceutical companies and clinical laboratories where throughput requirements and regulatory compliance burdens are most acute.
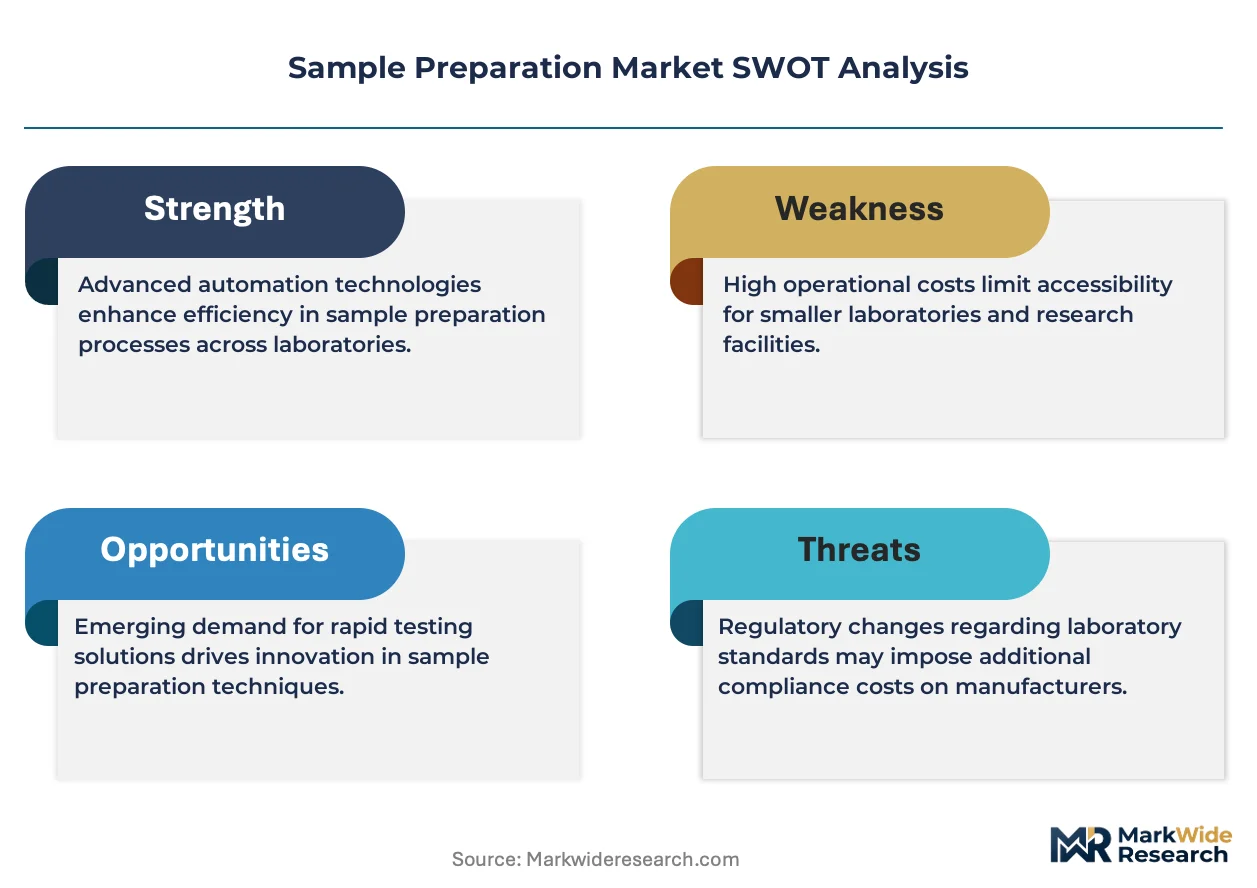
The FDA enforces Current Good Manufacturing Practice standards that govern sample integrity and traceability in drug development, while the EPA mandates specific preparation protocols for environmental contaminant analysis under Clean Water Act frameworks. ISO 17025 accreditation requirements for testing laboratories further shape equipment procurement decisions by embedding reproducibility and calibration standards into vendor selection. Stakeholders must monitor how evolving regulatory stringency around data integrity and chain-of-custody documentation influences capital allocation between manual upgrades and full automation replacements.
Market Dynamics
Automated liquid handling is compressing manual bench-scale protocols into integrated robotic workstations, forcing capital reallocation across pharmaceutical quality control and clinical diagnostic laboratories. This technological displacement is tightening performance thresholds for filtration, extraction, and purification modules while embedding traceability requirements into every processing step.
Growth Catalysts
- EMA bioanalytical guidance updates:European pharmaceutical manufacturers are upgrading chromatography-coupled sample prep systems to meet tightened method validation standards for pharmacokinetic studies.
- CRISPR-based sample prep:Gene editing workflows are driving specialized nucleic acid extraction protocols in academic research centers and biotech startups.
- United States biopharma R&D concentration:Deep venture capital pools and CRO infrastructure density in Boston and San Diego are sustaining premium equipment procurement cycles.
Market Restraints
- Fluoropolymer supply concentration:Specialized filtration membrane feedstocks face sourcing constraints from limited Japanese and German chemical suppliers.
- ISO 17025 calibration burdens:Testing laboratories face recurring audit costs and documentation overhead that extend equipment replacement timelines.
- Microfluidic fabrication complexity:Miniaturized reaction chamber production requires cleanroom infrastructure that constrains vendor scaling.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are modernizing quality control labs with automated extraction platforms.
- Single-use consumables pivot:Biopharma contamination control mandates are displacing reusable glassware with pre-sterilized plasticware in cell therapy production.
- AI-driven protocol optimization:Machine learning algorithms are converging with liquid handling robotics to reduce reagent waste and compress method development cycles.
Industry Challenges
- Cross-disciplinary automation expertise:Laboratories struggle to recruit personnel fluent in both analytical chemistry and robotic system programming.
- Legacy LIMS integration friction:New robotic workstations face data format incompatibilities with established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sample Preparation Market |
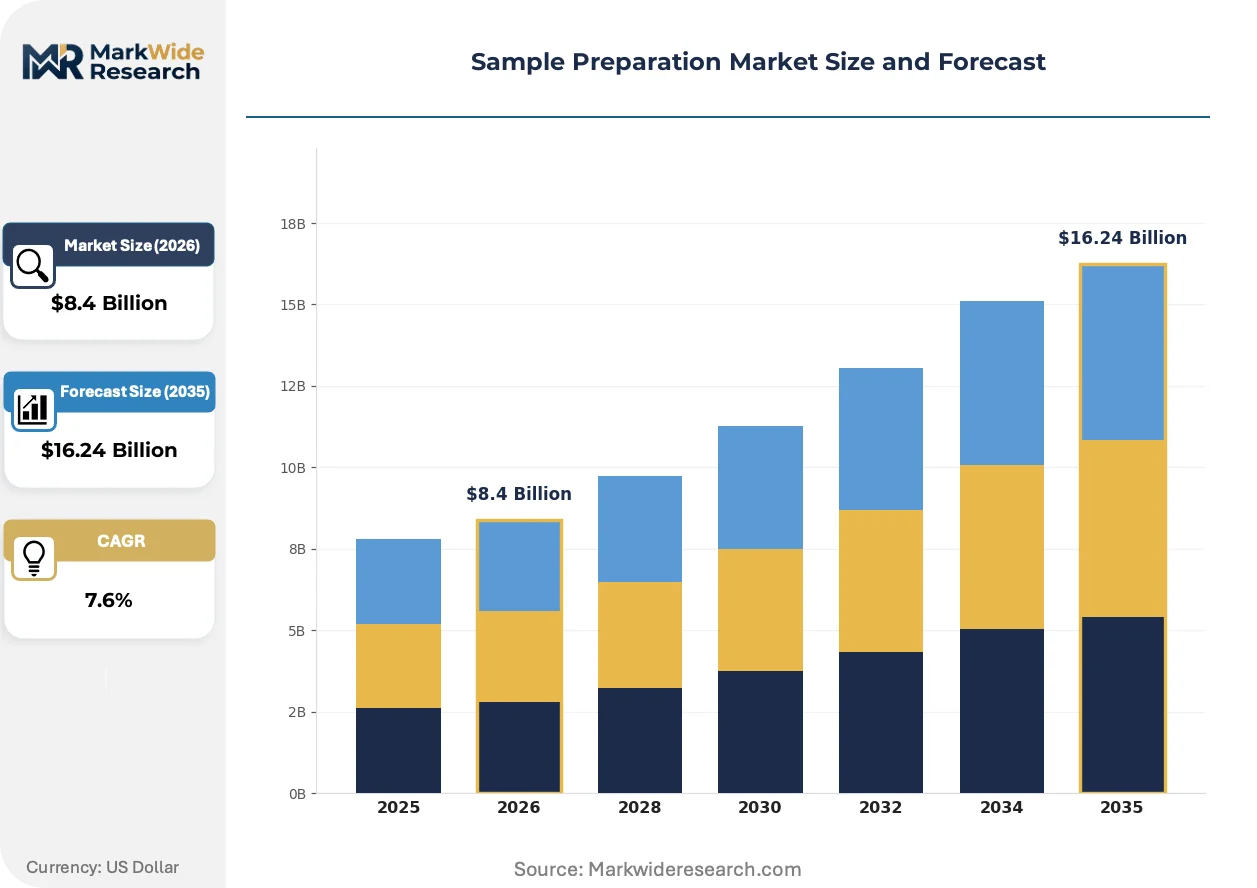
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifuges, Pipettes, Homogenizers, Filtration Units Application: Biological Sample Processing, Chemical Analysis, Environmental Testing, Food Safety Analysis End User: Pharmaceutical Companies, Academic Research Institutes, Clinical Laboratories, Environmental Agencies Technology: Manual Techniques, Automated Systems, Microfluidics, Robotics |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Agilent Technologies Inc., Danaher Corporation, QIAGEN N.V., Bio-Rad Laboratories Inc., Tecan Group Ltd., Hamilton Company, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sample Preparation Market Strategic Shifts & Innovations
Digitalization of laboratory workflows is embedding sensors and predictive analytics into sample preparation equipment, transforming standalone instruments into connected nodes within broader quality management ecosystems. This connectivity shift is compressing downtime and enabling remote diagnostics.
Microfluidic sample preparation is hybridizing acoustic wave separation with electrochemical detection to achieve label-free analyte concentration. Pharmaceutical toxicology groups are piloting these platforms for high-throughput screening. The technology is hybridizing manual pipetting steps with fully enclosed cartridge-based processing, reducing cross-contamination risk in regulated environments.
REACH chemical substance restrictions are forcing solvent substitution in European environmental testing laboratories, accelerating adoption of aqueous-based extraction protocols. EPA methods 8270 and 8260 are being adapted to accommodate greener alternatives. Environmental consultancies in Germany and the Netherlands are retrofitting automated solid-phase extraction systems to handle modified elution chemistries.
Consolidated procurement through group purchasing organizations is compressing vendor margins and extending equipment replacement cycles in hospital laboratories. Integrated delivery networks in the United States are centralizing capital planning for diagnostic platforms. Academic medical centers in Texas and Florida are negotiating multi-site service contracts that bundle reagent supply with preventive maintenance.
Sample Preparation Market Segmentation
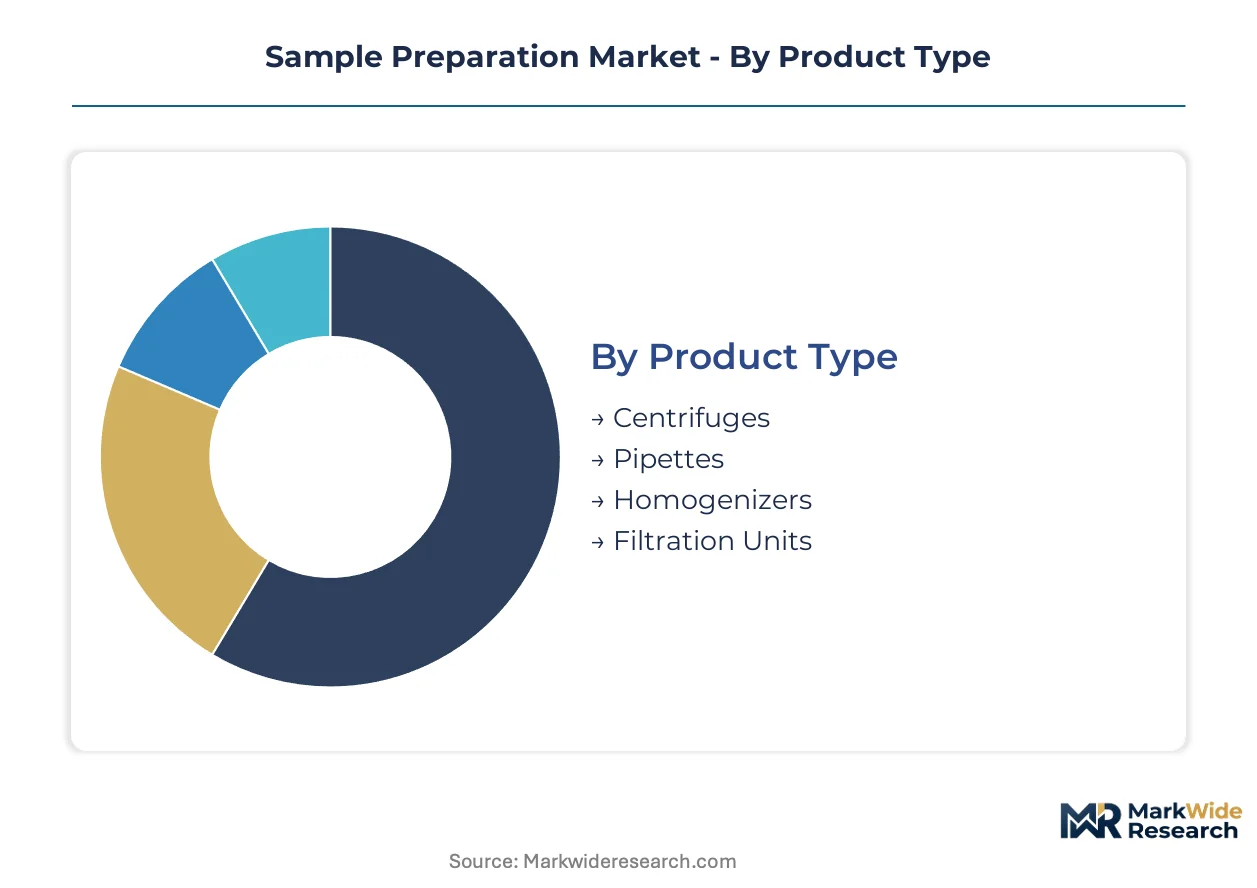
Sample preparation equipment spans divergent performance requirements across research, regulatory compliance, and industrial quality control workflows. Segmentation reveals how technology tiers and end-use constraints fragment procurement patterns and margin structures.
Product Type:
Centrifuges and filtration units anchor high-throughput bioprocessing, while homogenizers and pipettes serve precision-demanding analytical workflows.
- Centrifuges:Rotor-based separation systems achieve density-gradient purification and pelleting across biochemistry and clinical diagnostics. Pharmaceutical companies in the United States deploy ultracentrifuges for viral vector manufacturing, with rotor material specifications tightening under FDA Current Good Manufacturing Practice traceability mandates.
- Filtration Units:Membrane-based systems execute sterile filtration and particle removal through pore-size-selective barriers. Environmental agencies in Germany and the Netherlands retrofit automated solid-phase extraction platforms to accommodate REACH-compliant aqueous elution chemistries, replacing legacy solvent-heavy protocols.
- Pipettes:Liquid handling instruments deliver calibrated volume transfer for serial dilutions and reagent addition.
- Homogenizers:Mechanical disruption devices reduce tissue and cellular matrices to uniform suspensions for downstream nucleic acid or protein extraction.
Established volume favors centrifuges; emerging adoption favors filtration units.
Application:
Regulatory stringency varies sharply across domains, with pharmaceutical and food safety applications commanding premium equipment specifications.
- Biological Sample Processing:Nucleic acid extraction, protein purification, and cell lysis protocols prepare specimens for sequencing and mass spectrometry. CRISPR-based gene editing workflows in academic research centers and Boston-area biotech startups are driving specialized extraction chemistries and automated nucleic acid isolation platforms.
- Chemical Analysis:Chromatography-coupled preparation renders complex matrices compatible with quantitative detection. EMA bioanalytical guidance updates are compelling European pharmaceutical manufacturers to upgrade sample prep systems for tightened pharmacokinetic method validation standards.
- Environmental Testing:Contaminant extraction and concentration for EPA and ECHA compliance monitoring.
- Food Safety Analysis:Pathogen detection and residue screening for regulatory enforcement and supply chain verification.
Biological sample processing captures the deepest margin pools; environmental testing faces the steepest price compression from consolidated procurement.
End User:
Capital availability and regulatory burden intensity diverge across institutional categories, shaping automation penetration rates.
- Pharmaceutical Companies:Integrated drug development organizations require high-throughput, validated platforms for quality control and clinical sample analysis. Deep venture capital pools and CRO infrastructure density in Boston and San Diego sustain premium equipment procurement cycles with compressed replacement timelines.
- Clinical Laboratories:Diagnostic service providers process patient specimens under ISO 17025 and CLIA accreditation frameworks. Hospital laboratory consolidation through United States group purchasing organizations extends equipment replacement cycles while compressing vendor margins.
- Academic Research Institutes:University and government laboratories pursuing fundamental discovery with grant-funded capital constraints.
- Environmental Agencies:Government and contract laboratories executing mandated contaminant monitoring programs.
Pharmaceutical companies anchor premium pricing; clinical laboratories concentrate procurement leverage.
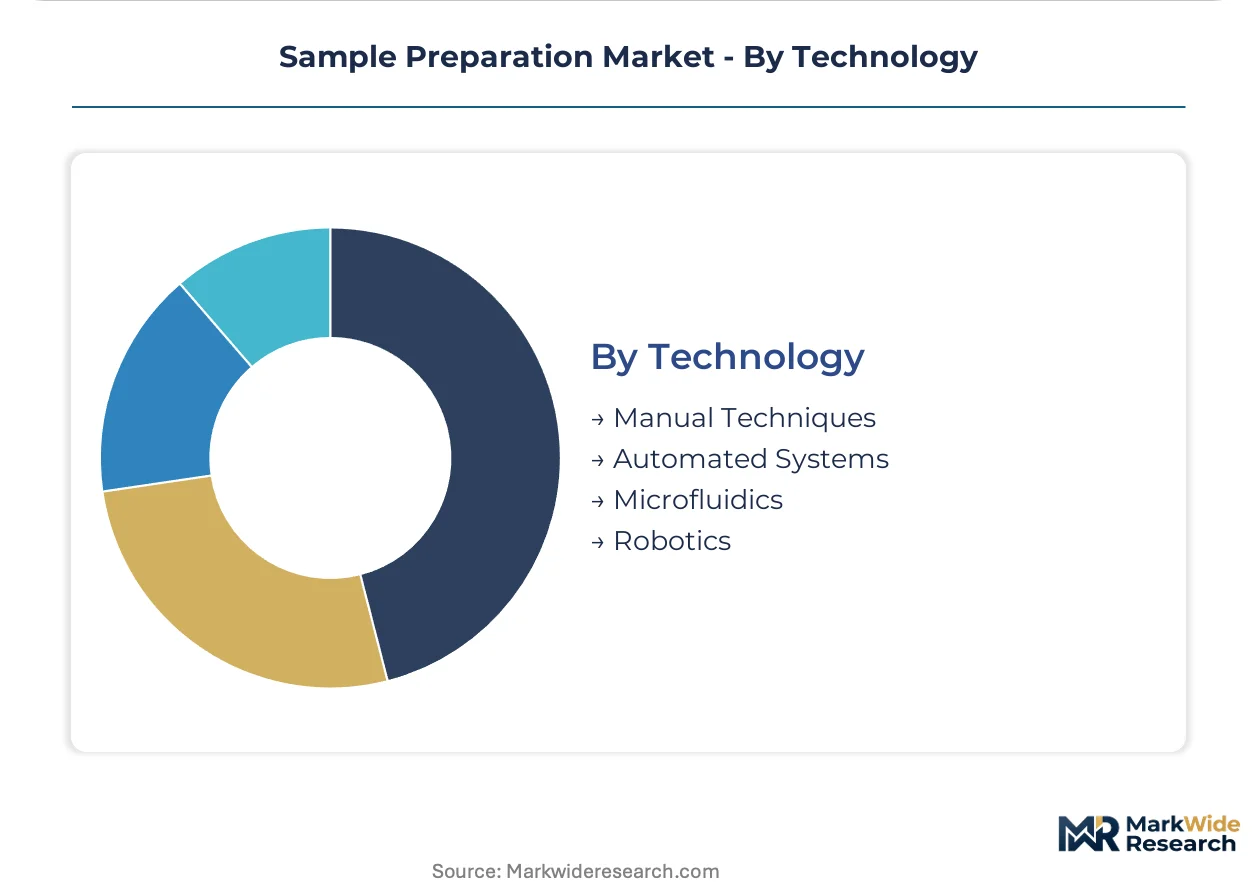
Technology:
Automation depth separates capital-intensive integrated platforms from maintenance-light manual alternatives.
- Automated Systems:Robotic liquid handling workstations execute programmed pipetting, mixing, and incubation sequences with traceable audit trails. Pharmaceutical quality control laboratories absorb premium pricing to satisfy FDA data integrity requirements and compress method development cycles through AI-driven protocol optimization.
- Microfluidics:Miniaturized reaction chambers manipulate nanoliter-scale volumes for reagent cost reduction and parallel processing. Cleanroom fabrication constraints in Japan and Germany limit vendor scaling, though acoustic wave separation hybridization is gaining traction in pharmaceutical toxicology screening.
- Manual Techniques:Operator-dependent pipetting and processing with minimal capital investment.
- Robotics:Articulated arm systems integrating multiple preparation modules into continuous workflows.
Automated systems dominate pharmaceutical spend; microfluidics climbs fastest on miniaturization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical companies and clinical diagnostic laboratories concentrate equipment procurement in markets with deep biopharma R&D infrastructure and stringent regulatory frameworks. Capital allocation patterns track FDA, EMA, and national health authority enforcement intensity.
United States
Venture capital pools in Boston and San Diego sustain premium automated liquid handling procurement cycles for CRISPR-based gene editing workflows. FDA Current Good Manufacturing Practice mandates tighten rotor material traceability specifications for ultracentrifuges in viral vector manufacturing. The FDA's updated bioanalytical method validation guidance is raising chromatography-coupled system performance thresholds across pharmaceutical quality control laboratories.
Germany
Environmental consultancies in Munich and Hamburg retrofit automated solid-phase extraction platforms to accommodate REACH-compliant aqueous elution chemistries. ECHA substance restrictions are forcing solvent substitution in contaminant monitoring protocols. The EMA bioanalytical guidance updates compel pharmaceutical manufacturers to upgrade sample prep systems for tightened pharmacokinetic validation standards.
Japan
Cleanroom fabrication constraints limit microfluidic reaction chamber scaling from specialized chemical suppliers in Osaka and Tokyo clusters. METI industrial standards govern equipment calibration documentation for ISO 17025-accredited testing laboratories. PMDA pharmaceutical manufacturing regulations embed data integrity requirements into automated workstation procurement decisions.
India
Contract development and manufacturing organizations in Hyderabad and Bangalore modernize quality control labs with automated extraction platforms for biopharma export compliance. CDSCO pharmaceutical manufacturing standards align with FDA and EMA benchmarks for method validation. The PLI scheme for pharmaceuticals incentivizes domestic production of specialized filtration consumables.
China
NMPA pharmaceutical registration requirements drive adoption of traceable robotic liquid handling systems in Shanghai and Suzhou biotech clusters. SAMR enforcement of GB standards for laboratory equipment shapes vendor qualification protocols. Dual carbon goals accelerate aqueous-based extraction chemistry adoption in environmental testing laboratories.
Sample Preparation Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement channels in academic and industrial laboratories. The vendor base spans diversified life sciences conglomerates, precision instrumentation specialists, and regional consumables suppliers. Two strategic archetypes dominate: integrated platform providers bundling hardware, software, and consumables; and modular specialists commanding niches in chromatography-coupled or microfluidic preparation. Competitive moves concentrate on portfolio diversification through adjacent technology acquisition and geographic expansion into CDMO-dense markets.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify channel-controlling scale, while Agilent Technologies Inc. occupies a defensible position in analytical method standardization. These three anchors represent divergent approaches to pharmaceutical and clinical laboratory procurement—end-to-end workflow integration versus chromatography-specialized precision. German-based Merck KGaA and Swiss-listed Tecan Group Ltd. sit within the European precision instrumentation cluster, reflecting regional concentration in automated liquid handling engineering expertise.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Agilent Technologies Inc. |
| Danaher Corporation |
| QIAGEN N.V. |
| Bio-Rad Laboratories Inc. |
| Tecan Group Ltd. |
| Hamilton Company |
| Promega Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific container freight corridors connecting Osaka and Tokyo chemical clusters to pharmaceutical manufacturing hubs in Boston and San Diego transmit fluoropolymer membrane cost volatility directly into automated workstation pricing tiers. Supply concentration in Japanese and German specialty chemical suppliers amplifies procurement leverage for high-purity filtration feedstocks, while downstream buyers face differentiated pricing based on certification tier and volume commitment scale.
Pricing Analysis
Cost-plus contracts with fluoropolymer resin indexation dominate consumables procurement between filtration membrane vendors and pharmaceutical quality control laboratories. Pricing stratifies across FDA-validated premium tiers, ISO 17025-compliant standard tiers, and unvalidated economy tiers for research use. Cost compression in the economy tier is intensifying because academic grant funding constraints extend replacement cycles for manual equipment. Pharmaceutical companies show the least price sensitivity due to GMP compliance mandates, while environmental testing laboratories exhibit acute sensitivity from consolidated group purchasing organization leverage.
Supply Chain Analysis
Export control restrictions on semiconductor-grade cleanroom equipment limit microfluidic fabrication capacity expansion from Japanese and German suppliers into Indian and Chinese manufacturing zones. Geographic supply concentration centers on Japan, Germany, and the United States for precision instrumentation, with China and India emerging for consumables molding. Raw material dependencies include fluoropolymer resins, borosilicate glass, and precision ceramics. Single-source vulnerability pervades ultracentrifuge rotor forging capabilities. Distribution runs through direct field service organizations for automated platforms and distributor networks for manual consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of personnel fluent in both analytical chemistry and robotic system programming constrains laboratory automation deployment velocity. This capability gap widens competitive moats for vendors with embedded training ecosystems.
For Market Incumbents: Entrench market position by acquiring microfluidic cartridge fabrication specialists in Japan and Germany to secure cleanroom capacity. Invest in ISO 17025 certification support programs for customer laboratories facing audit documentation burdens. CRISPR workflow standardization threatens chromatography-coupled sample prep incumbents; preempt displacement by embedding gene editing protocol libraries into liquid handling software. For New Entrants and Emerging Players: Mid-market CDMO quality control laboratories in Hyderabad and Bangalore represent the most penetrable entry point for automated extraction platforms. Academic research centers in Boston lacking capital for integrated workstations present secondary opportunity for modular microfluidic systems. Go-to-market through reagent rental programs that bundle consumables with equipment access reduces upfront adoption friction. For Investors and Strategic Acquirers: Niche filtration membrane developers with captive fluoropolymer sourcing relationships offer the strongest acquisition profile for vertical integration plays. Long-term viability hinges on regulatory compliance automation rather than hardware commoditization. Watch for FDA data integrity guidance updates as inflection signal for traceability software premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Supply | Captive feedstock sourcing insulates margin from Japanese and German chemical supplier pricing power. |
| AI-Driven Protocol Optimization Platform Launch | Machine learning compression of method development cycles differentiates automated workstations for pharmaceutical quality control. |
| CDSCO-Aligned Certification Pathway Investment | Indian regulatory alignment accelerates CDMO market penetration in Hyderabad and Bangalore clusters. |
| Single-Use Consumables Manufacturing Scale-Up | Pre-sterilized plasticware capacity expansion captures biopharma contamination control mandate displacement of glassware. |
| Academic Research Center Partnership Program | Grant-funded capital constraint accommodation through reagent rental bundles expands addressable market for modular systems. |
Research Approach
A spread of perspectives from pharmaceutical quality control directors, clinical laboratory accreditation managers, CDMO procurement leads, and automated liquid handling field engineers converged on the working assumptions. Primary interview insights combined with secondary validation from FDA guidance documents, EMA bioanalytical method validation updates, ISO 17025 accreditation databases, and SEC filings from listed life sciences conglomerates. Bottom-up equipment shipment tracking and top-down R&D spending allocation models triangulated market sizing.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology automation depth. CAGRs derived from weighted regression of historical replacement cycles against regulatory enforcement intensity and venture capital deployment patterns. Forecast inputs incorporated CRISPR workflow adoption curves and REACH solvent substitution timelines.
Practitioners should monitor EMA bioanalytical guidance enforcement intensity, fluoropolymer supply allocation shifts, and AI protocol optimization commercialization rates for early signals. Forecasts reflect assumptions on regulatory stringency continuity and CDMO geographic expansion velocity. Material shifts in FDA data integrity documentation requirements or export control expansion to microfluidic fabrication equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Durometers Market
Testing Equipment
Material Testing Market