
 Power Steering Fluids Market | 2026-2036
Power Steering Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Power Steering Fluids Market Outlook
China is fragmenting power steering fluid production as domestic blenders scale capacity to serve Asia-Pacific vehicle assembly. Exxon Mobil Corporation leverages integrated base oil refining to control feedstock costs across multiple viscosity grades. FUCHS anchors European aftermarket distribution through specialized hydraulic fluid portfolios tied to German OEM specifications. Lucas Oil Products Inc. competes in North American retail channels with high-performance formulations targeting classic and performance vehicle segments.
Power steering fluids are hydraulic transmission media formulated with refined base oils, anti-foam agents, corrosion inhibitors, and seal conditioners, typically operating within viscosity ranges of 5 to 15 cSt at operating temperature to transmit force from the steering pump to the rack-and-pinion or recirculating-ball mechanism while lubricating internal components and preventing elastomer degradation. Synthetic fluid formulations command premium positioning due to extended thermal stability and broader temperature operating windows compared with mineral oil counterparts. Aftermarket Providers represent the dominant end-user channel as vehicle aging extends beyond OEM warranty periods and independent service centers capture routine maintenance volume. Fleet Operators constitute the fastest-growing demand segment as commercial vehicle operators centralize fluid procurement through contracted maintenance programs to minimize downtime.
EPA regulations on petroleum-based lubricant disposal and REACH restrictions on certain additive chemistries are compelling reformulation investments across North American and European suppliers. China's SAMR enforces GB standards for automotive lubricants that foreign blenders must meet for market access, creating compliance barriers for imported products. Japan's METI maintains JIS specifications that govern OEM approval processes for steering system fluids. Stakeholders must monitor evolving chemical restriction schedules and regional certification reciprocity to align product portfolios with diverging compliance requirements.
Market Dynamics
Electrification of passenger vehicle powertrains is compressing demand for hydraulic steering systems while simultaneously extending replacement intervals for remaining fluid-dependent fleets. This structural tension between declining OEM fitment and aging aftermarket parc defines current competitive positioning.
Growth Catalysts
- REACH chemical safety standards:European OEM compliance mandates are accelerating reformulation toward synthetic bases with broader temperature stability, creating upgrade cycles across service networks.
- Fleet operator centralization:Commercial vehicle operators are consolidating fluid procurement through contracted maintenance programs to minimize downtime across aging hydraulic steering systems.
- Independent repair channel expansion:Aftermarket service centers in Brazil and China are capturing routine maintenance volume as vehicle parc ages beyond warranty coverage.
Market Restraints
- Base oil feedstock volatility:Refined petroleum input costs fluctuate with crude pricing, compressing blender margins on mineral oil formulations.
- Electric power steering substitution:EPS systems eliminate hydraulic fluid entirely, structurally capping long-term addressable market in new vehicle production.
- GB standards compliance barriers:China's SAMR certification requirements create friction for imported products lacking local testing documentation.
Strategic Opportunities
- Classic and performance vehicle segments:North American retail channels show sustained demand for high-viscosity formulations serving enthusiast maintenance.
- Extended-drain synthetic formulations:Thermal stability advantages enable premium positioning against mineral alternatives in commercial fleet applications.
- Recirculating-ball mechanism longevity:Heavy-duty truck steering systems require specialized seal conditioners, creating niche formulation white space.
Industry Challenges
- Additive chemistry harmonization:Diverging EPA disposal rules and REACH restriction schedules force parallel product line maintenance.
- Certification reciprocity gaps:JIS specifications from Japan's METI lack mutual recognition with European OEM approval processes, duplicating testing burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Steering Fluids Market |
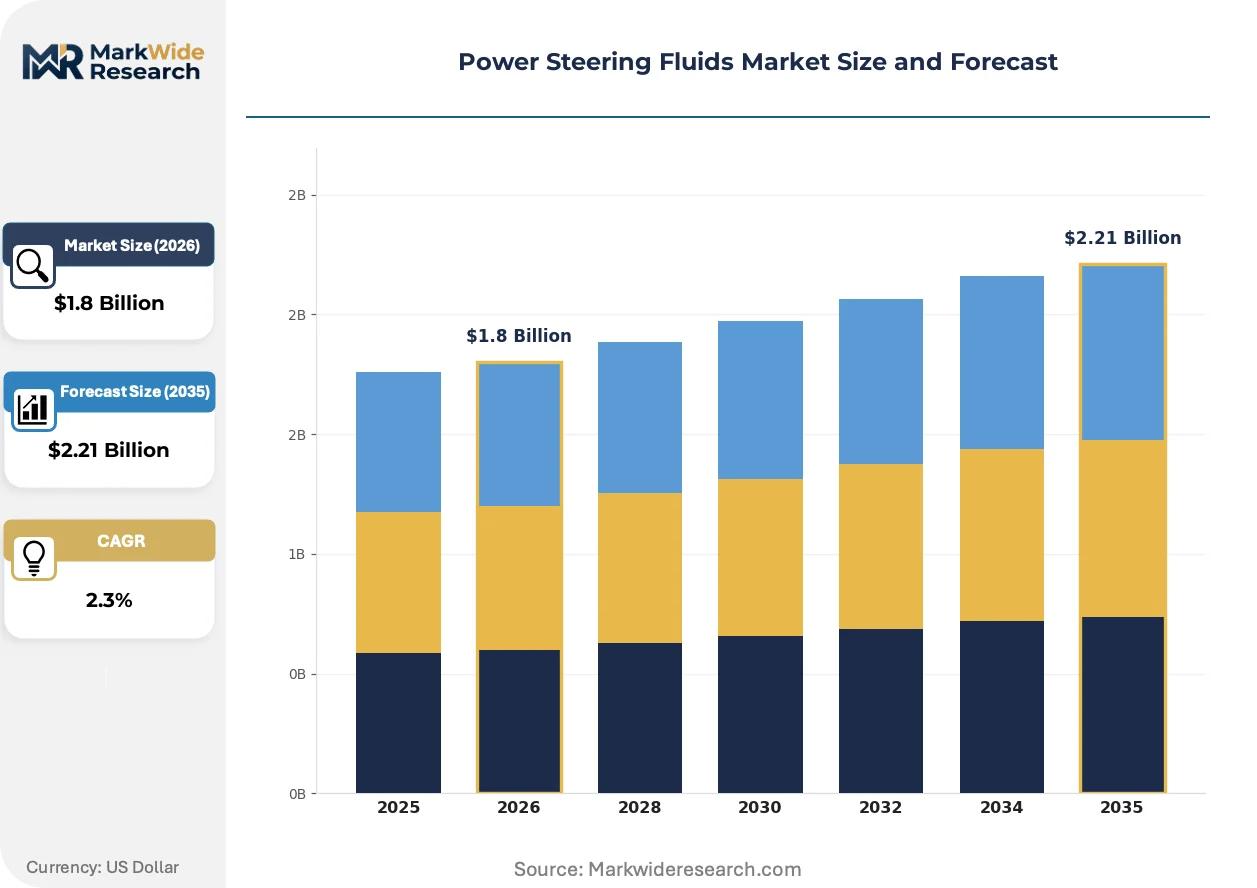
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Fluids, Biodegradable Fluids, ATF End User: OEMs, Aftermarket Providers, Service Centers, Fleet Operators Packaging Type: Bulk, Bottles, Cans, Drums Distribution Channel: Online Retail, Offline Stores, Distributors, Wholesalers |
| Companies Covered | Exxon Mobil Corporation, FUCHS, Lucas Oil Products Inc., AMSOIL Inc., Valvoline Inc., Bardahl Manufacturing Corp., Chevron Corp., Shell plc, Penrite Oil Co. Pty. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Steering Fluids Market Strategic Shifts
Formulation science and distribution architecture are evolving in parallel as suppliers navigate the transition from factory-fill dependency to aftermarket service economics. Three developments are restructuring competitive advantage.
Synthetic base stock technology is virtualizing the traditional mineral-synthetic product hierarchy. Thermal stability improvements enable single-fluid coverage across broader climate zones, reducing inventory complexity for distributors. Fleet procurement managers are consolidating SKUs around these extended-range formulations, compressing the viable product portfolio toward premium positioning.
REACH restrictions on specific corrosion inhibitor chemistries are forcing additive package redesigns across European supply chains. Blenders must substitute legacy components while maintaining elastomer compatibility with existing seal materials. German OEM specification holders are responding with phased approval timelines that synchronize reformulation investments across qualified supplier bases.
Service interval extension is altering channel economics for fluid replacement. Independent repair networks are bundling steering system inspection with brake and transmission services, unbundling the standalone power steering fluid transaction. This pattern concentrates in aging vehicle markets where multi-system maintenance contracts replace discrete fluid sales.
Power Steering Fluids Market Segmentation
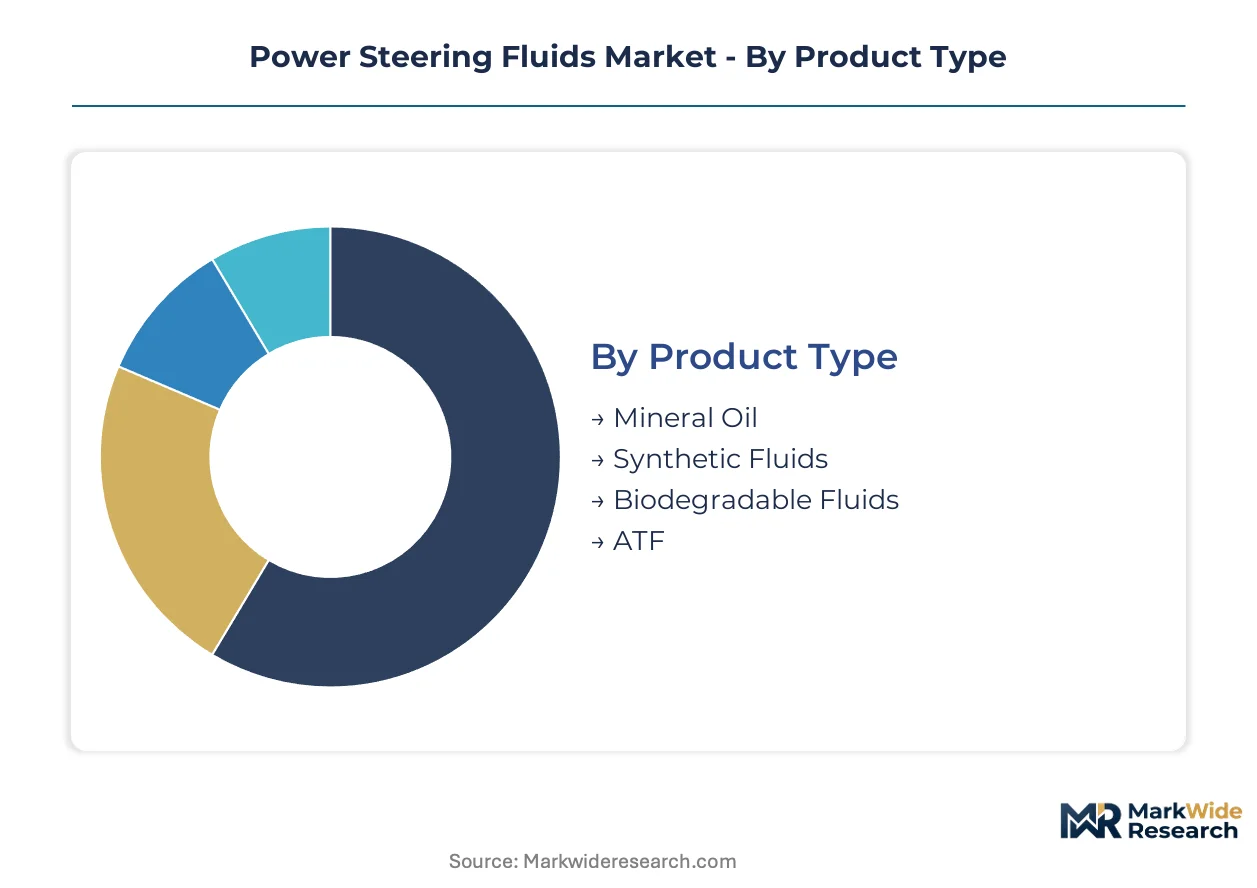
Power steering fluid procurement patterns diverge sharply between factory-fill specifications and aftermarket service economics. Segmentation reveals how formulation chemistry, packaging scale, and channel access determine competitive positioning across vehicle lifecycles.
Product Type:
Mature mineral formulations coexist with emerging synthetic and biodegradable alternatives as electrification pressures legacy hydraulic systems.
- Mineral Oil:Refined petroleum base stocks with additive packages for corrosion inhibition and foam suppression dominate legacy vehicle parc maintenance. Demand concentrates in independent service networks across Brazil and India where cost-sensitive fleet operators prioritize unit economics over drain interval extension.
- Synthetic Fluids:Polyalphaolefin and ester-based formulations deliver thermal stability across broader temperature windows, enabling extended service intervals. German OEM specification holders are consolidating procurement around these grades to satisfy REACH-mandated reformulation timelines while maintaining elastomer compatibility with existing seal materials.
- Biodegradable Fluids:Vegetable oil-derived bases with synthetic ester modifiers address petroleum disposal restrictions in sensitive watershed jurisdictions.
- ATF:Multi-purpose automatic transmission fluid formulations serve cross-application inventory reduction strategies in developing market service centers.
Mineral Oil retains volume leadership; Synthetic Fluids holds the steepest expansion curve.
End User:
Cost tier stratification separates centralized fleet procurement from fragmented retail transactions.
- OEMs:Factory-fill specifications demand certified fluid packages meeting JIS, GB, or German OEM approval protocols with full traceability documentation. Japanese and Chinese vehicle assemblers are narrowing qualified supplier bases as electrification reduces hydraulic steering fitment rates.
- Aftermarket Providers:Independent distributors and private-label blenders capture aging vehicle maintenance volume beyond warranty expiration. These channels dominate revenue concentration in Germany, China, and Brazil as vehicle parc aging accelerates fluid replacement cycles.
- Service Centers:Quick-lube and general repair facilities bundle steering system inspection with brake and transmission services, compressing standalone fluid transaction economics.
- Fleet Operators:Commercial vehicle and rental car operators centralize procurement through contracted maintenance programs to minimize downtime across aging hydraulic steering systems, climbing the fastest among end-user categories.
Aftermarket Providers command revenue concentration; Fleet Operators show the most rapid procurement centralization.
Packaging Type:
Volume scale determines packaging selection from single-serve retail to bulk fleet delivery systems.
- Bulk:Tanker and tote deliveries serve high-throughput fleet maintenance depots and assembly plant fill stations with minimal unit packaging overhead.
- Bottles:One-quart and one-liter polyethylene containers dominate North American retail auto parts channels for DIY enthusiast segments.
- Cans:Metal and composite cylinders serve professional service bay environments requiring controlled pour precision and contamination resistance.
- Drums:Fifty-five gallon steel containers anchor distributor inventory for high-volume independent repair networks.
Bulk and Drums anchor commercial procurement; Bottles sustain retail channel presence.
Distribution Channel:
Customer type alignment shapes channel selection between transactional immediacy and procurement efficiency.
- Online Retail:E-commerce platforms capture enthusiast and small fleet procurement with expanded SKU visibility and competitive pricing transparency.
- Offline Stores:Brick-and-mortar auto parts retailers maintain emergency availability for immediate failure response in consumer segments.
- Distributors:Regional fluid specialists provide technical support, inventory management, and credit terms to independent service centers.
- Wholesalers:Volume aggregators serve price-sensitive developing markets with minimal value-added services.
Distributors retain channel leadership in professional segments; Online Retail expands fastest in fragmented procurement environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining clusters in the United States, Germany, and China supply formulation feedstock to regional blending operations. Qualified supplier bases are narrowing as electrification reduces hydraulic steering fitment in new vehicle programs. Aftermarket service networks concentrate replacement fluid demand in aging vehicle markets.
United States
Independent repair channels and quick-lube networks drive aftermarket fluid replacement across an aging light-truck parc. EPA disposal regulations on petroleum-based lubricants compel reformulation investments among domestic blenders. Houston-Gulf Coast refining corridors supply Group II and III base stocks to regional formulators serving fleet maintenance depots.
Germany
German OEM specification holders consolidate procurement around synthetic grades to satisfy REACH-mandated additive redesigns. ECHA chemical restriction schedules force substitution of legacy corrosion inhibitors while maintaining elastomer compatibility. Stuttgart and Munich automotive clusters anchor qualified supplier programs with full traceability documentation requirements.
China
Domestic blenders scale capacity to serve Asia-Pacific vehicle assembly and capture aftermarket share from imported products. SAMR enforces GB standards for automotive lubricants that create compliance documentation barriers for foreign entrants. Yangtze River Delta chemical parks host integrated base oil and additive production serving regional formulation demand.
Brazil
Cost-sensitive fleet operators in independent service networks prioritize mineral oil formulations over synthetic alternatives. ANVISA maintains chemical registration requirements for lubricant additives that extend product approval timelines. São Paulo industrial corridors concentrate blending operations serving Mercosur distribution channels.
Japan
Vehicle assemblers narrow qualified supplier bases as electric power steering penetration reduces hydraulic fluid factory-fill volumes. METI maintains JIS specifications governing OEM approval processes for steering system fluids. Nagoya and Tokyo automotive clusters retain specification control over remaining hydraulic steering applications in commercial vehicle segments.
Power Steering Fluids Market Competitive Environment
Integrated petroleum majors and specialized lubricant formulators split the market between feedstock-integrated scale and specification-driven positioning. Supplier consolidation proceeds through qualified base narrowing at OEMs and SKU compression in aftermarket distribution. Three archetypes dominate: integrated refiners controlling base oil supply, specification holders anchoring OEM approval networks, and independent blenders capturing price-sensitive retail channels. Competitive moves center on backward integration into additive chemistry and geographic licensing of formulation intellectual property.
Within the integrated refiner tier, Exxon Mobil Corporation and Shell plc exemplify feedstock-integrated positioning through captive base oil refining. FUCHS occupies a position as a specification-focused European formulator anchored to German OEM approval networks. Lucas Oil Products Inc. represents the independent blender archetype targeting enthusiast and performance vehicle segments in North American retail channels.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| FUCHS |
| Lucas Oil Products Inc. |
| AMSOIL Inc. |
| Valvoline Inc. |
| Bardahl Manufacturing Corp. |
| Chevron Corp. |
| Shell plc |
| Penrite Oil Co. Pty. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Base oil feedstock volatility compresses blender margins and simultaneously widens pricing tier spreads between mineral and synthetic formulations while reshaping procurement patterns toward captive refining capacity.
Pricing Analysis
REACH chemical safety standards dictate the pricing tier structure across European supply chains, forcing additive package redesigns that stratify costs across premium-mid-economy levels. Certification grade and volume scale differentiate quotes, with fleet procurement managers extracting discounts against retail channel premiums. Cost compression in mineral formulations is intensifying because crude-linked feedstock swings erode blender margins. Independent service centers in Brazil and India exhibit highest price sensitivity, while German OEM specification holders accept premium positioning for elastomer compatibility assurance.
Supply Chain Analysis
Export-control restrictions on advanced synthetic base stock technology limit technology transfer from United States and German refiners to emerging market blenders. Supply concentrates in Houston-Gulf Coast corridors, Rotterdam refining clusters, and Yangtze River Delta chemical parks. Formulation draws from Group II and III base oils, polyalphaolefin stocks, and corrosion inhibitor additive packages. Single-source vulnerability runs through specialized seal conditioner chemistries facing REACH substitution timelines. Distribution runs through regional fluid specialists providing technical support and inventory management to independent service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment, where OEM approval protocols and certification reciprocity gaps create persistent switching costs for qualified suppliers.
For Market Incumbents: Insulate specification-holder status by deepening backward integration into additive chemistry production and securing phased REACH reformulation timelines with German OEMs. Electric power steering substitution threatens long-term factory-fill volumes, necessitating capture of aging aftermarket parc through distributor exclusivity arrangements in Brazil and China. For New Entrants and Emerging Players: Brazil's cost-sensitive independent service networks present underpenetration opportunities for mineral oil formulations with localized ANVISA compliance documentation. Target quick-lube bundling partnerships that unbundle standalone fluid transactions into multi-system maintenance contracts, leveraging price positioning against synthetic premiums. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specification-anchored formulators with captive base oil supply. Long-term viability hinges on aftermarket service network density rather than OEM fitment rates. Monitor electric power steering penetration in commercial vehicle segments as the inflection signal for hydraulic fluid demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captive supply of corrosion inhibitors secures margin control against REACH-mandated reformulation cycles. |
| Extended-Drain Synthetic Formulation Launch | Thermal stability claims differentiate fleet procurement bids from mineral alternatives in German commercial channels. |
| Geographic Licensing of Formulation IP | Technology transfer agreements bypass SAMR certification barriers for foreign blenders seeking China market access. |
| Multi-System Maintenance Bundling | Quick-lube partnerships compress transaction costs while capturing steering fluid volume within brake and transmission services. |
| Biodegradable Fluid Certification | Vegetable oil-derived bases address EPA disposal restrictions in watershed-sensitive United States jurisdictions. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with lubricant blenders, fleet procurement managers, aftermarket distributors, and OEM specification engineers; and secondary validation through customs trade records, SEC 10-K petroleum segment disclosures, ECHA chemical restriction schedules, and vehicle production databases. Bottom-up triangulation against top-down market sizing anchored volume estimates across formulation chemistry tiers.
Forecast inputs considered vehicle parc aging curves, electrification penetration rates in passenger and commercial segments, and regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include base oil chemistry tier, end-user procurement centralization, packaging scale, and regional production hub. CAGRs were derived from replacement cycle extension patterns and fleet operator consolidation trends.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated refiners or accelerated EPS substitution in heavy-duty trucks would shift outcomes. Material shifts in REACH chemical restriction schedules or SAMR certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Israel Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Qatar Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Turkey Marine Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
India Lubricants Market