
 Global Silica Gel Market | 2026-2036
Global Silica Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silica Gel Market Intelligence
The silica gel industry is consolidating around a sharp split between premium pharmaceutical-grade material and commodity desiccant supply. Cabot Corporation leverages its carbon-silica technology platform to sustain pricing power in high-purity segments. BASF anchors European supply through integrated petrochemical feedstock access. Evonik Industries differentiates via specialty silica R&D intensity, particularly in controlled-pore architectures for drug stabilization.
Silica gel is an amorphous form of silicon dioxide produced by acidifying sodium silicate solutions, yielding a rigid three-dimensional network with surface areas of 300–800 m²/g and pore diameters tunable from 2 to 20 nanometers. Its primary commercial purpose is adsorptive moisture control across packaging, electronics protection, and pharmaceutical stability applications. The granular product type dominates volume shipments for industrial drying, while beaded silica commands margin premiums in pharmaceutical and electronics applications where low dust generation matters. Powdered formulations serve cosmetics and specialty coatings, though this segment remains comparatively mature with slower growth trajectories.
REACH registration requirements in Europe, FDA 21 CFR compliance for pharmaceutical contact applications, and China's GB standards for food-grade desiccants collectively shape product specifications and market access barriers. The EPA oversees silica dust exposure limits in U.S. manufacturing facilities, influencing production equipment investments. Stakeholders must monitor evolving pharmaceutical serialization rules and dual carbon goals in China, as these will determine which product grades and packaging formats capture future margin pools.
Market Dynamics
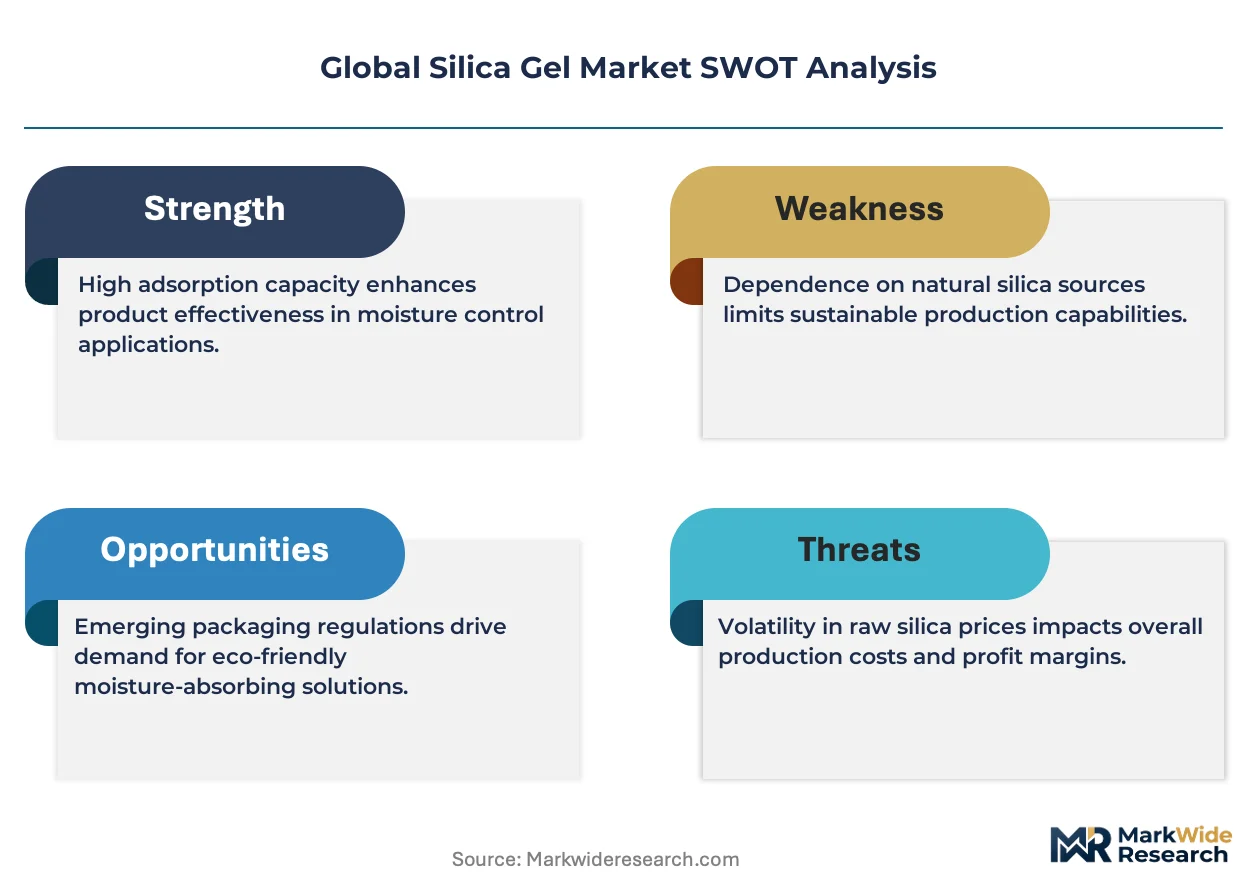
The silica gel market is bifurcating sharply between pharmaceutical-grade precision manufacturing and commodity desiccant production, with regulatory compliance costs now determining viable participation tiers rather than scale economies alone.
Growth Catalysts
- Biologics packaging surge:Moisture-sensitive monoclonal antibodies and cell therapies require ultra-low humidity control, expanding demand for beaded silica in vial and syringe packaging systems.
- EU Green Deal compliance:REACH registration mandates and dust emission thresholds are accelerating replacement of powdered silica with lower-dust beaded formulations across European pharmaceutical supply chains.
- Shenzhen-Dongguan electronics cluster:Semiconductor and consumer electronics manufacturing concentration in China's Pearl River Delta absorbs substantial desiccant volumes for component protection during assembly and shipping.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive production of sodium silicate from sand and soda ash exposes margins to natural gas price swings, particularly affecting European producers.
- Substitution by molecular sieves:Zeolite-based desiccants offer superior moisture capacity at low relative humidity, capturing share in electronics drying applications where space constraints dominate.
- Silica dust exposure limits:EPA workplace standards and OSHA enforcement in U.S. manufacturing facilities require capital-intensive filtration and containment systems, raising fixed costs for domestic producers.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization mandates and expanding domestic biologics manufacturing create demand for compliant desiccant systems in parenteral drug packaging.
- Controlled-release drug stabilization:Pore-engineered silica architectures enable moisture-activated drug release profiles, opening adjacent markets in oral solid dosage innovation.
- Reusable desiccant logistics:Industrial buyers in Germany and Japan are piloting returnable silica gel canister programs to meet CSRD circularity reporting requirements and reduce single-use packaging waste.
Industry Challenges
- Specialized process engineering talent:Sol-gel chemistry expertise and pore-size tuning capabilities remain concentrated among a limited pool of formulation scientists, constraining R&D velocity for mid-tier producers.
- FDA 21 CFR compliance timelines:Pharmaceutical-grade certification requires 18-24 month validation cycles for extractables and leachables testing, delaying market entry for new manufacturing facilities.
- Legacy equipment retrofit costs:Existing spray-drying and acidification lines require substantial modification to meet EU dust emission standards, forcing capital allocation decisions between upgrade and greenfield investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silica Gel Market |
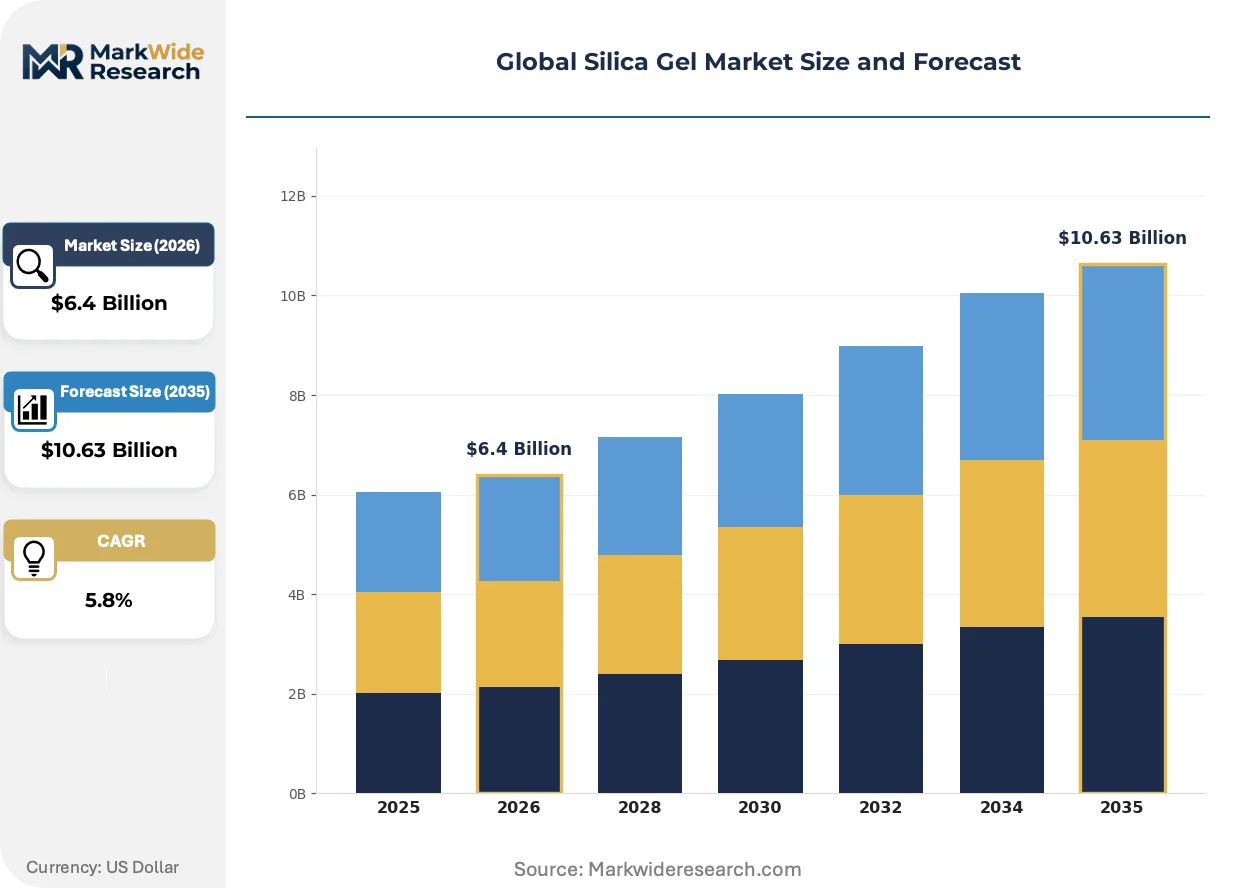
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Beaded, Powdered, Coated Application: Desiccants, Pharmaceuticals, Cosmetics, Electronics End User: Food Industry, Healthcare, Automotive, Chemical Manufacturing Packaging Type: Bulk Bags, Sachets, Bottles, Containers |
| Companies Covered | Cabot Corporation, BASF, Evonik Industries, U.S. Silica Holdings, Inc., Solvay, W.R. Grace & Co., Merck Group, 3M, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silica Gel Market Strategic Shifts & Innovations
Active materials engineering and regulatory precision are compressing product development cycles while opening differentiated applications beyond traditional moisture adsorption. Three developments are restructuring competitive positioning.
Smart silica formulations with humidity-indicating dyes are modularizing quality assurance workflows in pharmaceutical packaging. Drug manufacturers in Switzerland and Singapore are embedding color-shift silica directly into vial closures, eliminating separate humidity indicator cards and reducing packaging component counts. This convergence of desiccant and sensor functions is compressing supplier margins on standalone indicator products while capturing value in integrated delivery systems.
REACH authorization requirements for synthetic amorphous silica are tightening impurity thresholds for crystalline silica content. European chemical manufacturers are investing in acidification process controls and real-time particle monitoring to maintain registration status. Pharmaceutical-grade producers with existing analytical capabilities are extending compliance services to commodity suppliers, creating a two-tier market structure separated by regulatory infrastructure rather than base material quality.
Japanese electronics assemblers are consolidating desiccant procurement through designated logistics partners rather than direct supplier relationships. Trading houses in Tokyo and Osaka are aggregating volume across multiple OEMs to negotiate blanket pricing and manage inventory pooling. This channel restructuring is compressing direct manufacturer relationships and shifting margin capture toward distributors with bonded warehouse networks and just-in-time delivery capabilities.
Global Silica Gel Market Segmentation
Silica gel's functional versatility demands precise grade matching to application requirements. Product architecture, end-use specifications, and delivery formats each create distinct margin profiles and technical barriers.
Product Type:
Customization intensity varies sharply across this category, with pharmaceutical and electronics buyers demanding pore-engineered precision while industrial drying accepts commodity formulations.
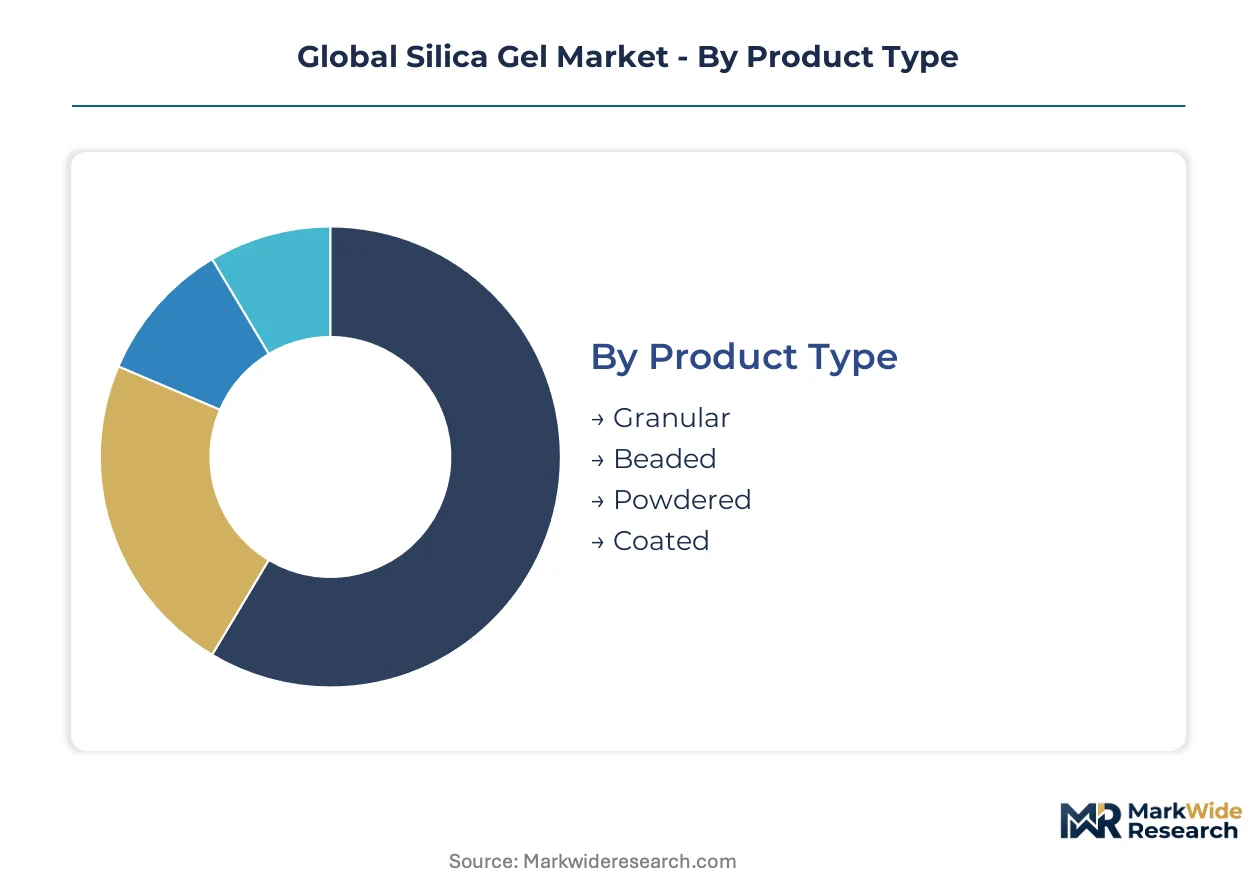
- Granular:Irregular particle morphology produced through acidification of sodium silicate solutions yields surface areas of 300-800 m²/g. Bulk industrial drying operations in China's electronics assembly corridors absorb substantial volumes for component protection during ocean freight.
- Beaded:Spherical particles manufactured via spray-drying offer controlled particle size distributions and minimal dust generation. Swiss and German pharmaceutical packagers specify beaded silica for parenteral drug stability under REACH dust emission thresholds.
- Powdered:Finely milled amorphous silica serves cosmetics formulations and specialty coatings with established specification standards.
- Coated:Surface-modified variants with humidity-indicating dyes or polymer encapsulation address integrated sensor applications.
Most installed capacity flows through Granular. Expansion is steepest in Beaded.
Application:
Regulatory stringency creates tiered entry barriers across application segments, with pharmaceutical contact applications demanding 18-24 month validation cycles.
- Desiccants:Moisture adsorption remains the foundational commercial purpose across packaging, electronics protection, and industrial drying. Shenzhen-Dongguan manufacturing clusters absorb substantial volumes for semiconductor component protection.
- Pharmaceuticals:FDA 21 CFR compliance and EMA stability requirements govern moisture control in biologics packaging. Monoclonal antibody and cell therapy expansion drives specification for ultra-low humidity beaded systems.
- Cosmetics:Powdered silica serves as rheology modifier and free-flow agent in color cosmetic formulations.
- Electronics:Precision moisture control protects integrated circuits and display assemblies during assembly and distribution.
Volume concentrates in Desiccants. Value capture is climbing fastest in Pharmaceuticals.
End User:
Customer procurement sophistication separates this category, with healthcare and automotive buyers demanding certificate-of-analysis documentation while food industry purchasing emphasizes unit economics.
- Food Industry:GB standards compliance and FDA food-contact approvals govern moisture control in packaged goods. Chinese domestic consumption growth absorbs substantial food-grade desiccant volumes.
- Healthcare:CDSCO serialization mandates in India and dual carbon goals in China shape pharmaceutical packaging specifications. Biologics manufacturing expansion drives demand for validated desiccant systems.
- Automotive:Electric vehicle battery pack assembly requires humidity control during cell manufacturing and module integration.
- Chemical Manufacturing:Process drying and catalyst support applications utilize commodity granular grades with established performance specifications.
Procurement volume centers on Food Industry. Technical specification intensity is expanding most quickly in Healthcare.
Packaging Type:
Supply chain configuration determines viable formats, with just-in-time electronics assembly favoring pre-portioned sachets while bulk chemical operations accept loose-fill delivery.
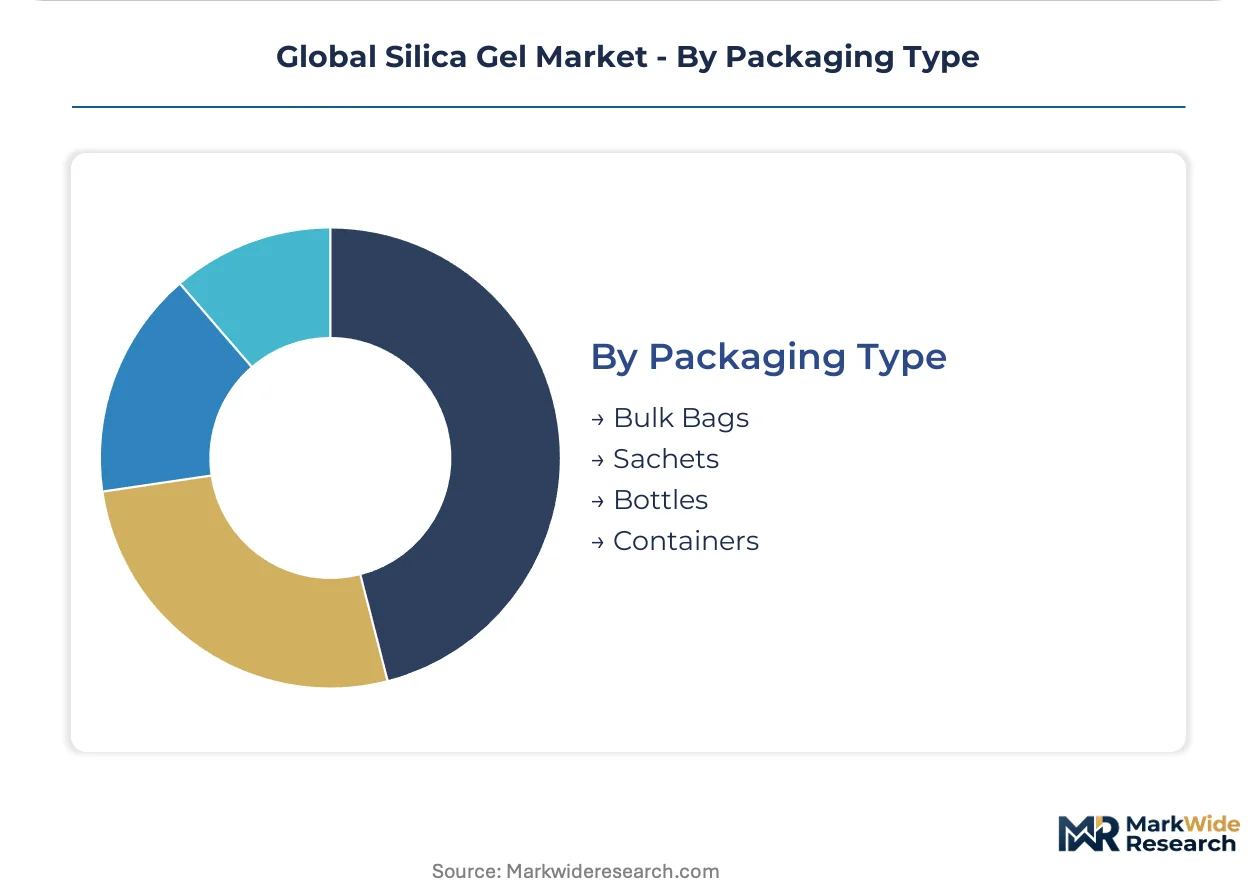
- Bulk Bags:Industrial-scale delivery to chemical manufacturing and large-scale drying operations minimizes per-unit packaging costs.
- Sachets:Pre-measured pouches with specified moisture capacity serve pharmaceutical vial packaging and consumer electronics boxes. Japanese trading houses aggregate OEM volumes for blanket pricing.
- Bottles:Reusable canister formats support German and Japanese pilot programs for returnable desiccant logistics under CSRD circularity reporting.
- Containers:Rigid packaging systems for high-value pharmaceutical applications with integrated humidity indicators.
Shipment volume flows predominantly through Bulk Bags. Format innovation is concentrating in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest absolute desiccant volumes, while Switzerland and Germany command the highest specification premiums for pharmaceutical-grade material. Regulatory divergence between REACH-strict Europe and FDA-governed North America creates parallel compliance ecosystems. Industrial clustering in specific cities concentrates both demand and supplier technical capabilities.
China
Shenzhen and Dongguan electronics corridors consume substantial beaded silica for semiconductor packaging and consumer electronics protection. GB standards for food-grade desiccants and dual carbon goals from MEE shape domestic manufacturing investments. The Pearl River Delta assembly clusters source locally to minimize logistics friction for just-in-time component protection.
Germany
Automotive battery manufacturing and pharmaceutical packaging drive specification for low-dust beaded formulations. REACH registration through ECHA and CSRD circularity reporting requirements accelerate returnable desiccant pilot programs. The Ruhr industrial basin and Bavarian chemical corridor host integrated silica production with petrochemical feedstock access.
United States
Biologics manufacturing expansion in Massachusetts and North Carolina sustains demand for FDA 21 CFR validated desiccant systems. EPA silica dust exposure limits and OSHA enforcement raise fixed costs for domestic production facilities. The Gulf Coast petrochemical corridor anchors sodium silicate feedstock supply for regional silica gel manufacturing.
India
Domestic pharmaceutical packaging growth and CDSCO serialization mandates create demand for compliant desiccant systems in parenteral drug applications. Maharashtra and Gujarat pharmaceutical clusters absorb increasing volumes of imported beaded silica for vial and syringe stability. The country's national pharmaceutical regulator tightens extractables testing requirements for primary packaging materials.
Japan
Electronics assemblers in Tokyo and Osaka consolidate procurement through designated logistics partners with bonded warehouse networks. METI industrial standards and JIS specifications govern moisture capacity ratings for precision component protection. Trading houses aggregate OEM volumes to negotiate blanket pricing and manage inventory pooling across multiple manufacturers.
Global Silica Gel Market Key Industry Players
Top-tier vendors anchor pharmaceutical-grade precision manufacturing, while mid-scale producers compete on commodity desiccant volumes and regional logistics reach. The market structure separates into three strategic archetypes: integrated petrochemical majors with captive feedstock, specialty silica R&D houses with pore-engineering capabilities, and regional fabricators serving packaging converters. M&A activity concentrates on acquiring sol-gel chemistry expertise, while capacity expansion targets pharmaceutical serialization demand in India and Southeast Asia.
Within the integrated petrochemical tier, BASF and Solvay occupy positions sustained by backward integration into sodium silicate feedstock. Evonik Industries exemplifies the R&D-intensive specialist archetype, with its controlled-pore architectures serving drug stabilization applications. Among North American players, Cabot Corporation anchors the carbon-silica technology platform segment. These three companies represent distinct competitive vectors: feedstock security, technical differentiation, and materials science convergence.
| Leading Market Players |
|---|
| Cabot Corporation |
| BASF |
| Evonik Industries |
| U.S. Silica Holdings, Inc. |
| Solvay |
| W.R. Grace & Co. |
| Merck Group |
| 3M |
| Clariant |
| Others |
Cost & Logistics Intelligence
Sodium silicate feedstock pricing, indexed to natural gas benchmarks in Northwest Europe, cascades through acidification and spray-drying stages into three distinct pricing tiers: pharmaceutical-grade beaded silica commands certification premiums under FDA 21 CFR and REACH registration, commodity granular grades compete on volume scale in Shenzhen-Dongguan electronics corridors, and specialty coated variants capture value-integrated sensor applications.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity granular grades while European REACH compliance costs sustain premiums for pharmaceutical beaded formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated extractables-tested material from industrial drying grades and food-contact compliant sachets. Cost compression in standard-tier granular silica intensifies because sodium silicate energy input costs fluctuate with regional natural gas pricing. Electronics OEMs in the Pearl River Delta exhibit highest price sensitivity, while Swiss and German pharmaceutical packagers prioritize batch certification documentation over unit economics.
Supply Chain Analysis
Returnable desiccant canister programs in Germany and Japan are introducing reverse-logistics flows that alter inventory pooling economics and distributor margin capture. Supply concentrates in China, Germany, and the United States, with the Pearl River Delta and Ruhr industrial basin anchoring regional production clusters. Manufacturing draws from sodium silicate feedstock, sulfuric acid reagents, and humidity-indicating dye inputs. Single-source vulnerability in pharmaceutical-grade sol-gel chemistry expertise constrains capacity expansion timelines. Distribution runs through Japanese trading houses with bonded warehouse networks and just-in-time delivery capabilities for electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silica gel market functions as a regulatory compounder where REACH authorization milestones and FDA 21 CFR validation cycles continuously reset entry barriers and sustain incumbent pricing power.
For Market Incumbents: Hedge against molecular sieve substitution in electronics drying by deepening controlled-pore R&D for biologics stabilization applications. Secure backward integration into sodium silicate feedstock or long-term offtake agreements with Gulf Coast petrochemical producers to defend margin position against natural gas price volatility. Prioritize certification infrastructure investments that extend REACH compliance services to commodity suppliers, creating regulatory capture mechanisms.
For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-grade beaded silica and economy granular desiccants creates white-space opportunity for mid-tier producers targeting Indian pharmaceutical packaging under CDSCO serialization mandates. Focus initial capacity on food-grade sachet formats for Chinese domestic consumption growth, leveraging GB standards compliance as a faster validation pathway than pharmaceutical certification. Pursue direct relationships with German automotive battery manufacturers seeking humidity control for electric vehicle assembly.
For Investors and Strategic Acquirers: Consolidation pressure builds where sol-gel chemistry expertise and pore-engineering capabilities remain concentrated among limited formulation scientist pools. Long-term viability favors specialty silica R&D houses with drug stabilization application pipelines over commodity desiccant fabricators exposed to sodium silicate feedstock volatility. Target acquisition archetypes include regional European producers with existing REACH registration infrastructure. Monitor FDA 21 CFR validation cycle durations as an inflection indicator for new manufacturing facility economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate Feedstock | Gulf Coast petrochemical corridor access insulates margin from natural gas price swings in European production. |
| REACH Registration Infrastructure Investment | ECHA compliance capabilities create two-tier market separation between registered and unregistered suppliers. |
| Controlled-Pore Architecture R&D Expansion | Pore-engineered silica for monoclonal antibody stabilization captures biologics packaging value pools. |
| Returnable Desiccant Logistics Pilot Programs | CSRD circularity reporting in Germany and Japan shifts procurement toward reusable canister formats. |
| CDSCO Serialization Compliance Capacity | Indian pharmaceutical packaging demand under domestic biologics manufacturing expansion creates import substitution opportunity. |
Research Approach
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, technical R&D directors, and distribution channel partners; secondary validation through customs/trade data, SEC 10-K filings, and Cefic industry reports; and bottom-up and top-down triangulation — were reconciled to construct market estimates. Field engagement with silica gel manufacturers, pharmaceutical packaging converters, and electronics assembly procurement teams informed capacity utilization and pricing dynamics. Secondary sources included REACH registration databases, FDA 21 CFR guidance documents, and GB standards compliance records.
Data-stream reconciliation across product type, application, end-use industry, and regional production hub segmentation dimensions generated volume and value outputs across the analysis window. CAGRs were derived from segment-level growth trajectory modeling informed by biologics manufacturing expansion rates, electronics assembly cluster output, and pharmaceutical serialization mandate implementation timelines. Forecast inputs incorporated sodium silicate feedstock cost structures, REACH authorization requirement evolution, and dual carbon goal compliance investments in China.
Caveats apply where sodium silicate energy input cost volatility, REACH crystalline silica impurity threshold tightening, or molecular sieve technology advancement could materially shift the outlook. Forecasts reflect assumptions regarding pharmaceutical-grade validation cycle durations and electronics manufacturing geographic concentration. Practitioners should monitor FDA 21 CFR extractables testing requirement changes and EU Green Deal dust emission standard evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Thermally Stable Antiscalant Market