
 Hydrogen Sulfide Scavengers Market | 2026-2036
Hydrogen Sulfide Scavengers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Sulfide Scavengers Market Intelligence
Midstream pipeline operators is collapsing as the fastest-expanding buyer archetype for hydrogen sulfide scavengers, overtaking traditional refinery procurement patterns. SLB dominates chemical injection systems through its integrated wellsite services platform. Baker Hughes Company anchors its position via specialized H2S management technologies for sour gas fields. Clariant differentiates through tailored scavenger formulations optimized for varying temperature and pressure regimes.
Hydrogen sulfide scavengers are reactive chemical formulations—typically amine-based, triazine-based, or metal oxide compounds—engineered to neutralize toxic H2S gas through irreversible chemical binding at concentrations ranging from trace levels to several thousand ppm. These agents protect pipeline metallurgy from sulfide stress cracking and ensure worker safety in hydrocarbon processing, wastewater treatment, and geothermal energy operations. Liquid formulations lead the product type landscape due to ease of continuous injection and metering precision, while solid scavengers represent the fastest-growing category for remote wellpad applications lacking liquid handling infrastructure. The oil and gas application segment commands the dominant margin pool, though water treatment is accelerating as municipal anaerobic digesters face tighter effluent standards.
The EPA enforces hydrogen sulfide exposure limits under OSHA PEL standards and Clean Air Act provisions, directly mandating scavenger deployment at processing facilities exceeding threshold emissions. State regulators in Texas and Louisiana supplement federal rules with site-specific air quality permits that prescribe H2S monitoring and mitigation protocols. The EU REACH framework and Classification, Labelling and Packaging Regulation govern scavenger chemical registration and hazard communication for European suppliers accessing the market. Stakeholders must monitor evolving state-level methane and H2S co-regulation packages, as these rules increasingly bundle scavenger performance requirements with broader emissions control mandates.
Market Dynamics
Upstream oil and gas operators are intensifying sour gas production across Texas and North Dakota shale basins, forcing midstream pipeline operators to expand scavenger procurement faster than traditional refinery buyers. The EPA's tightened Clean Air Act emissions standards are compelling facility upgrades that embed continuous H2S monitoring and mitigation systems.
Growth Catalysts
- Clean Air Act mandates:EPA enforcement of hydrogen sulfide exposure limits under OSHA PEL standards directly mandates scavenger deployment at processing facilities exceeding threshold emissions.
- Sour gas field expansion:High-sulfur crude and natural gas processing in Texas and North Dakota shale basins is accelerating procurement volumes from midstream operators.
- Triazine-based formulations:These reactive chemical compounds neutralize toxic H2S through irreversible binding, protecting pipeline metallurgy from sulfide stress cracking in high-pressure regimes.
Market Restraints
- Amine feedstock volatility:Price instability in ethylene oxide and ammonia derivatives compresses formulation margins for scavenger producers.
- Louisiana supply concentration:Gulf Coast chemical manufacturing clusters create geographic vulnerability to hurricane disruption and logistics bottlenecks.
- Metal oxide substitution:Iron sponge and zinc oxide media compete for low-flow, batch-treatment applications where liquid injection infrastructure is absent.
Strategic Opportunities
- Geothermal energy operations:H2S-rich brine processing in California and Nevada geothermal fields represents an underpenetrated application vertical with specialized temperature requirements.
- EU REACH compliance services:European chemical registration and hazard communication mandates create advisory revenue streams for suppliers navigating CLP regulation complexity.
- Solid scavenger remote deployment:Wellpad applications lacking liquid handling infrastructure favor solid formulations, opening channel innovation through packaged delivery systems.
Industry Challenges
- Process safety engineering talent:Scarce expertise in H2S handling protocol design limits facility upgrade execution speed for midstream operators.
- Legacy system integration:Retrofitting continuous injection systems into existing pipeline infrastructure demands customized engineering without disrupting hydrocarbon flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Sulfide Scavengers Market |
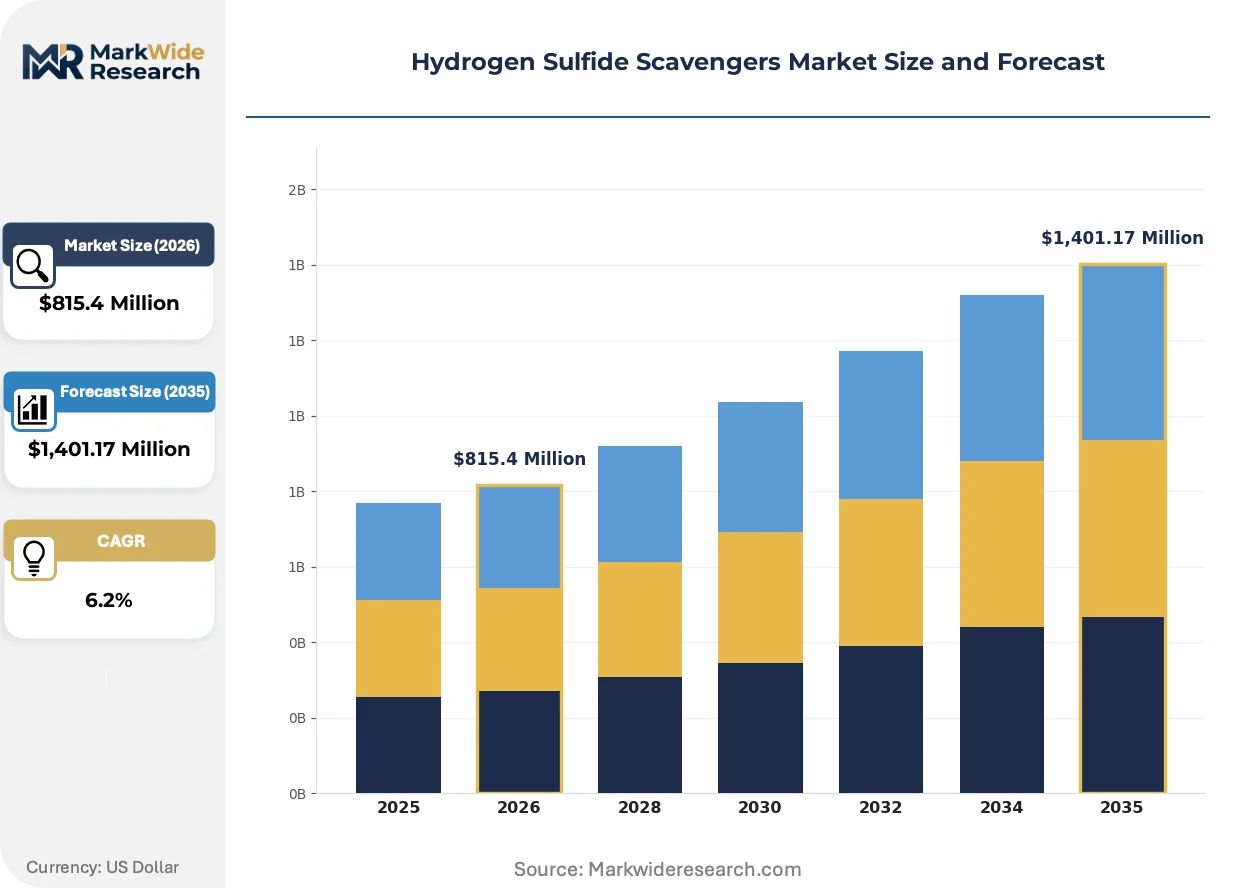
| Market Size in 2026 | $815.4 Million |
| Market Size in 2035 | $1,401.17 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Gas, Powder Application: Oil & Gas, Water Treatment, Chemical Manufacturing, Pulp & Paper Technology: Chemical, Biological, Thermal, Electrochemical End User: Refineries, Municipalities, Industries, Energy Sector |
| Companies Covered | SLB, Veolia, BASF SE, The Dow Chemical Company, Clariant, Baker Hughes Company, Umicore, The Lubrizol Corporation, Merichem Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Sulfide Scavengers Market Strategic Shifts & Innovations
Reactive scavenger chemistry is diversifying beyond conventional amine and triazine bases as operators demand formulations optimized for extreme pressure-temperature regimes. Solid-state delivery systems are gaining traction in remote extraction sites where liquid logistics prove uneconomical.
Non-regenerable scavenger technology is fragmenting the traditional service model. These single-use formulations eliminate regeneration infrastructure requirements. Midstream pipeline operators in the Permian Basin are adopting them for temporary flowback treatment. The technology is fragmenting procurement patterns away from long-term chemical service contracts toward commodity-style spot purchasing.
EPA enforcement of the Clean Air Act National Emission Standards for Hazardous Air Pollutants is tightening monitoring protocols. Facilities must now demonstrate continuous H2S capture efficiency rather than periodic compliance sampling. Texas Commission on Environmental Quality is responding with site-specific air quality permits that prescribe real-time emissions verification, forcing scavenger vendors to certify performance under actual operating conditions.
Buyer concentration among supermajor shale operators is compressing supplier negotiation leverage. These consolidated purchasers now demand performance-guaranteed contracts where scavenger costs tie directly to measured H2S removal rates. The shift is most visible in the Eagle Ford formation, where Devon Energy and EOG Resources have unbundled chemical procurement from integrated wellsite service packages.
Hydrogen Sulfide Scavengers Market Segmentation
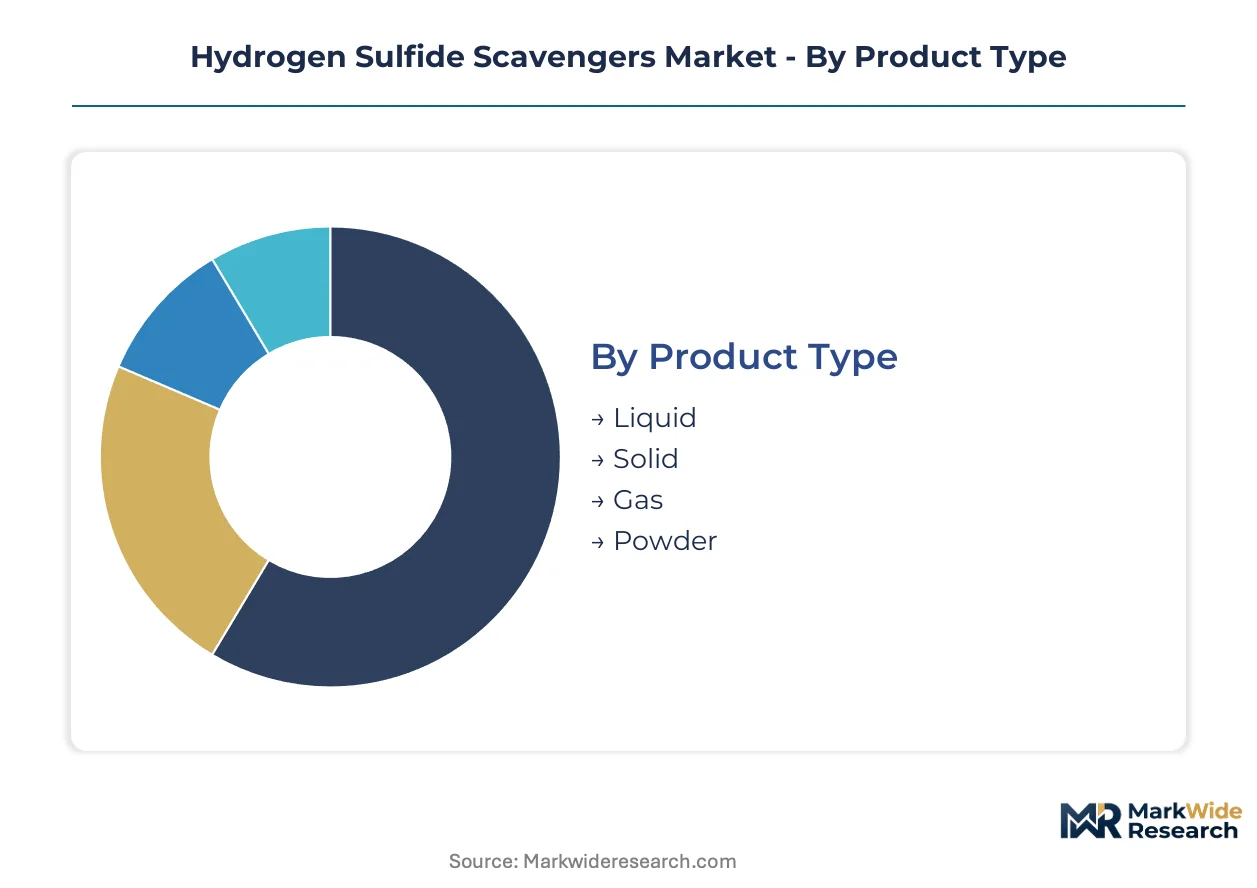
Segmentation reveals how scavenger procurement channels diverge by physical form, application severity, and facility infrastructure. Buyers route liquid formulations through integrated service contracts while solids and gases move through specialized distributors.
Product Type:
Liquid scavengers flow through wellsite service platforms and chemical injection system providers. Solid and gas alternatives channel through packaged goods distributors serving remote locations lacking liquid handling infrastructure.
- Liquid:Continuous injection systems meter amine-based and triazine-based formulations with precision. Demand concentrates in Texas and North Dakota shale basins where midstream pipeline operators require real-time H2S neutralization at high flow rates. The EPA's Clean Air Act enforcement mandates continuous treatment at processing thresholds.
- Solid:Metal oxide compounds and regenerable media deploy in batch-treatment configurations for remote wellpads. Procurement is accelerating in the Permian Basin where temporary flowback treatment and lacking liquid logistics favor packaged delivery systems.
- Gas:Vapor-phase scavengers target enclosed vessel headspace treatment in storage tanks and processing equipment. Municipal wastewater facilities in California use these for anaerobic digester off-gas control.
- Powder:Dry chemical formulations enable precise dosing in low-volume applications. Pulp and paper mills in the Pacific Northwest adopt these for black liquor recovery boiler protection.
Liquid formulations dominate installed base. Solid scavengers are where expansion concentrates.
Application:
Cost tier stratification separates mission-critical oil and gas applications from compliance-driven water treatment and manufacturing uses. Premium pricing attaches to sour gas field operations where failure risks pipeline integrity.
- Oil & Gas:Upstream production, midstream transportation, and downstream refining operations deploy scavengers at every stage. Sulfide stress cracking prevention drives specification in high-pressure Permian and Bakken formations where hydrogen sulfide concentrations reach several thousand ppm.
- Water Treatment:Municipal anaerobic digesters and industrial wastewater systems face tightening effluent standards. California and Nevada geothermal brine processing creates specialized demand for high-temperature formulations.
- Chemical Manufacturing:Process stream purification in sulfuric acid and carbon disulfide production requires trace-level H2S removal. Gulf Coast petrochemical clusters represent concentrated procurement.
- Pulp & Paper:Kraft process emissions control and recovery boiler protection drive specification. Pacific Northwest mills prioritize worker safety in enclosed pulping operations.
Oil and Gas commands the dominant margin pool. Water Treatment is climbing the fastest.
Technology:
Volume concentration favors chemical methods at scale while biological and thermal alternatives serve niche regulatory environments. Customer type determines technology selection—integrated operators prefer proven chemical systems while municipalities experiment with lower-carbon alternatives.
- Chemical:Reactive binding through amine, triazine, and metal oxide compounds remains the workhorse approach. Irreversible neutralization chemistry protects pipeline metallurgy across Texas and North Dakota shale operations.
- Biological:Microbial oxidation systems target low-concentration, continuous-flow applications. California municipal digesters pilot these for combined methane and H2S management under state climate mandates.
- Thermal:High-temperature destruction suits concentrated waste streams from chemical manufacturing. Gulf Coast refineries deploy these for Claus unit tail gas treatment.
- Electrochemical:Emerging direct oxidation methods eliminate chemical consumption. Nevada geothermal operators test these for H2S-rich brine processing where reagent logistics prove costly.
Chemical technology anchors current procurement. Electrochemical methods are gaining share fastest.
End User:
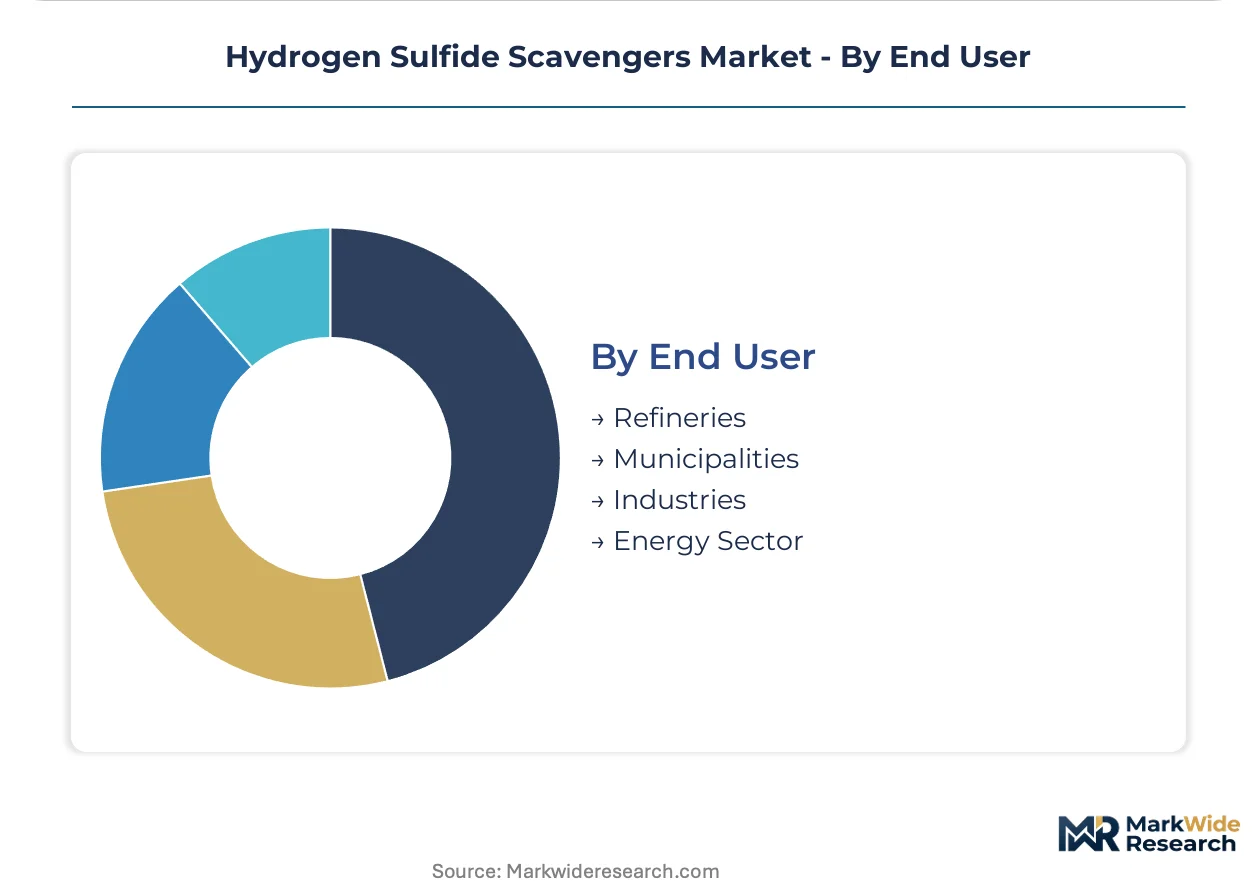
Supply concentration shapes channel strategy—refinery procurement consolidates through integrated service contracts while municipalities fragment across competitive bidding processes. Energy sector buyers unbundle chemical procurement from wellsite packages.
- Refineries:Complex sulfur recovery units and crude unit overhead systems demand continuous scavenger injection. Gulf Coast and Midwest facilities embed H2S management into process safety engineering protocols.
- Municipalities:Wastewater treatment plants and landfill gas operations face OSHA PEL compliance. Texas Commission on Environmental Quality site-specific permits prescribe real-time emissions verification.
- Industries:Pulp and paper, chemical manufacturing, and food processing facilities deploy scavengers for worker protection and product quality. Pacific Northwest paper mills specify powder formulations.
- Energy Sector:Upstream producers and midstream pipeline operators represent the steepest expansion trajectory. Devon Energy and EOG Resources in the Eagle Ford formation demand performance-guaranteed contracts tied to measured removal rates.
Refineries hold the largest installed base. Energy Sector is where procurement is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network anchors North American hydrogen sulfide scavenger procurement, moving high-sulfur crude from West Texas to Gulf Coast refineries. Midstream operators along this corridor deploy continuous injection systems to meet federal emissions thresholds. Expansion patterns track sour gas field development across four distinct national markets.
United States
The Eagle Ford formation in South Texas and the Bakken shale in North Dakota drive scavenger demand as Devon Energy and EOG Resources intensify sour gas extraction. The EPA enforces hydrogen sulfide exposure limits under OSHA PEL standards and Clean Air Act provisions, mandating deployment at processing facilities exceeding threshold emissions. Houston and Corpus Christi host concentrated chemical manufacturing clusters supplying triazine-based formulations to Permian Basin operators.
Canada
Alberta's oil sands operations and Saskatchewan heavy crude processing create specialized demand for high-temperature scavenger formulations. Health Canada and provincial regulators enforce workplace exposure limits that align with federal environmental protection statutes. Calgary anchors the procurement decision-making for Canadian energy majors operating across the Western Canadian Sedimentary Basin.
Germany
The EU REACH framework and Classification, Labelling and Packaging Regulation govern scavenger chemical registration for European suppliers accessing industrial markets. ECHA mandates comprehensive hazard communication protocols for amine-based and metal oxide compounds. The Rhine-Ruhr petrochemical cluster concentrates formulation manufacturing and distribution logistics for continental demand.
Saudi Arabia
High-sulfur crude processing at Jubail and Yanbu industrial complexes drives scavenger procurement for refinery sulfur recovery units and gas treatment facilities. The national oil company embeds H2S management into process safety engineering protocols across upstream and downstream operations. The Eastern Province hosts integrated chemical manufacturing sites supplying metal oxide scavengers to regional operators.
China
Sichuan Basin sour gas fields and Tarim Basin high-sulfur crude production accelerate scavenger deployment as national energy security priorities shift to domestic resource extraction. MEE standards for hazardous air pollutant control tighten monitoring requirements at processing facilities. The Yangtze River Delta chemical manufacturing corridor supplies formulated products to western production basins through established distribution networks.
Hydrogen Sulfide Scavengers Market Key Industry Players
Listed leaders compete with private specialists across technology licensing and service integration dimensions. The vendor base organizes around three tiers: integrated oilfield service platforms, specialized chemical formulators, and regional distribution specialists. Strategic archetypes include full-service wellsite operators, formulation-focused technology providers, and logistics-optimized regional suppliers. Competitive moves concentrate on portfolio diversification into solid-state delivery systems and geographic expansion through distributor partnerships.
Within the integrated service tier, SLB and Baker Hughes Company represent archetypes combining chemical injection systems with wellsite operations. Clariant exemplifies the formulation-specialist model through tailored scavenger chemistry. Veolia occupies a position bridging industrial water treatment and energy sector applications. These anchors demonstrate how competitive positioning fragments across service integration depth rather than consolidating around single-dominant players.
| Leading Market Players |
|---|
| SLB |
| Veolia |
| BASF SE |
| The Dow Chemical Company |
| Clariant |
| Baker Hughes Company |
| Umicore |
| The Lubrizol Corporation |
| Merichem Technologies |
| Others |
Cost & Logistics Intelligence
EPA Clean Air Act certification gates supplier qualification while simultaneously enabling price differentiation between compliant and non-compliant formulation tiers. Buyers in Texas and North Dakota shale basins face dual pressure: emissions thresholds mandate continuous scavenger deployment, yet procurement teams exploit volume concentration to compress contract rates.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with supermajor operators commanding 15-25% contract reductions against spot-market benchmarks. Three-tier pricing separates performance-guaranteed formulations from standard injection chemicals and economy-grade batch treatments. Cost compression in the economy tier is intensifying because metal oxide substitutes erode liquid scavenger margins for remote wellpad applications. Midstream pipeline operators exhibit highest price sensitivity due to unbundled chemical procurement from integrated service packages, while municipal wastewater facilities prioritize compliance certification over unit cost.
Supply Chain Analysis
Louisiana and Texas anchor North American scavenger formulation manufacturing, with Houston and Corpus Christi clusters supplying triazine-based and amine-based compounds to Permian Basin operators. Feedstock supply draws from Gulf Coast ethylene oxide and ammonia derivative production, with metal oxide precursors sourced from Appalachian zinc processing facilities. Single-source vulnerability concentrates in Louisiana chemical manufacturing corridors exposed to hurricane disruption and barge logistics bottlenecks. Distribution runs through integrated wellsite service platforms for liquid formulations, while solid scavengers channel through packaged goods distributors serving remote extraction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where performance-guaranteed chemical management contracts expand faster than commodity formulation sales. Recurring revenue layers from continuous injection system monitoring and real-time emissions verification now outpace hardware-only procurement growth.
For Market Incumbents: Consolidate formulation manufacturing capacity in Gulf Coast corridors to capture economies of scale against emerging metal oxide substitutes. Deepen backward integration into amine feedstock production to buffer margin compression from ethylene oxide price volatility. Channel control through exclusive wellsite service partnerships remains essential as Devon Energy and EOG Resources unbundle chemical procurement from integrated packages. For New Entrants and Emerging Players: EPA compliance fast-tracks for solid scavenger formulations open immediate market access without competing against entrenched liquid injection infrastructure. Geothermal energy operations in California and Nevada represent the most penetrable vertical, with specialized high-temperature chemistry requirements underserved by incumbent suppliers. A go-to-market angle through packaged delivery systems for remote Permian Basin wellpads bypasses capital-intensive liquid logistics networks. For Investors and Strategic Acquirers: EPA National Emission Standards for Hazardous Air Pollutants enforcement reshapes the acquisition landscape toward vendors with certified continuous monitoring capabilities. Long-term viability centers on suppliers integrating real-time emissions verification into service contracts rather than commodity chemical producers. The signal to watch is Texas Commission on Environmental Quality site-specific permit bundling of scavenger performance guarantees with broader air quality mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Feedstock | Captive ethylene oxide supply secures margin stability against Gulf Coast feedstock volatility. |
| Solid Scavenger Formulation Development | Remote wellpad applications in Permian Basin favor packaged delivery over liquid infrastructure. |
| Performance-Guaranteed Service Contracts | Eagle Ford operators now tie scavenger costs to measured H2S removal rates. |
| Geothermal Energy Vertical Expansion | California and Nevada H2S-rich brine processing demands specialized high-temperature chemistry. |
| EU REACH Compliance Advisory Services | European chemical registration mandates create recurring revenue streams for hazard communication expertise. |
Research Approach
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings for this hydrogen sulfide scavenger market assessment. Primary fieldwork encompassed discussions with midstream pipeline procurement directors, oilfield chemical plant managers, EPA compliance officers, wellsite service operations heads, and municipal wastewater treatment superintendents. Secondary sources integrated EPA enforcement databases, Texas Commission on Environmental Quality permit filings, customs trade records for amine and triazine imports, and SEC 10-K disclosures from integrated service providers. Bottom-up volume modeling triangulated against top-down value estimates derived from chemical injection system deployment rates.
Sensitivity analysis across feedstock price scenarios and regulatory enforcement intensity brackets tests forecast robustness throughout the projection horizon. Segmentation dimensions modeled include product form (liquid, solid, gas, powder), application severity (oil and gas, water treatment, chemical manufacturing, pulp and paper), technology type (chemical, biological, thermal, electrochemical), and end-user procurement structure (integrated service contract, spot commodity, performance-guaranteed agreement). CAGRs derive from regression analysis of historical scavenger procurement against sour gas production volumes and emissions standard tightening trajectories. Key inputs incorporate Permian Basin drilling activity indices and Clean Air Act enforcement budget allocations.
Underlying assumptions cover sustained sour gas field development in Texas and North Dakota, with deviation risk concentrated in amine feedstock supply disruptions and state-level methane-H2S co-regulation acceleration. Forecasts reflect documented conditions without guarantee of realization. Recalibration cycles align with material shifts in EPA enforcement priorities and supermajor operator procurement unbundling trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Powder Coating Guns Market