
 Hydrogen Silicone Fluid Market | 2026-2036
Hydrogen Silicone Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Silicone Fluid Market Insights
Petroleum-derived silicone fluids is shifting toward hydrogen-functional polysiloxanes in high-heat industrial applications where thermal stability commands premium positioning. Dow Corning Corporation leverages backward integration into silane precursors to secure feedstock continuity across North American operations. Wacker Chemie AG anchors its competitive stance through Bavarian manufacturing scale and proprietary hydrosilylation catalyst systems. Shin-Etsu Chemical Co., Ltd. dominates Asian supply corridors with captive methyl chloride and silicon metal assets.
Hydrogen silicone fluid denotes a polydimethylsiloxane backbone terminated or pendant-modified with Si-H bonds, typically exhibiting viscosities from 10 to 1,000 centistokes and hydride contents between 0.01 and 1.6 mol percent, serving primarily as crosslinking agents, reducing agents, and surfactant intermediates in silicone elastomer and resin synthesis. Fluid-grade products carry the deepest margin pools due to pharmaceutical and electronics-grade purification requirements, while emulsion formats are gaining fastest in water-based textile finishing as environmental compliance tightens. Resin applications remain structurally mature in electrical insulation, though gel segments are expanding in biomedical cushioning where biocompatibility certification creates pricing power.
EPA oversight of volatile methylsiloxanes in industrial emissions is elevating purity standards for US-sourced hydrogen silicone fluids, while REACH registration in Europe demands full toxicological dossiers for hydride-functional siloxanes above one-tonne thresholds. China's MEE is implementing stricter effluent limits on silicone monomer production that cascade into hydrogen fluid cost structures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capacity investments.
Market Dynamics
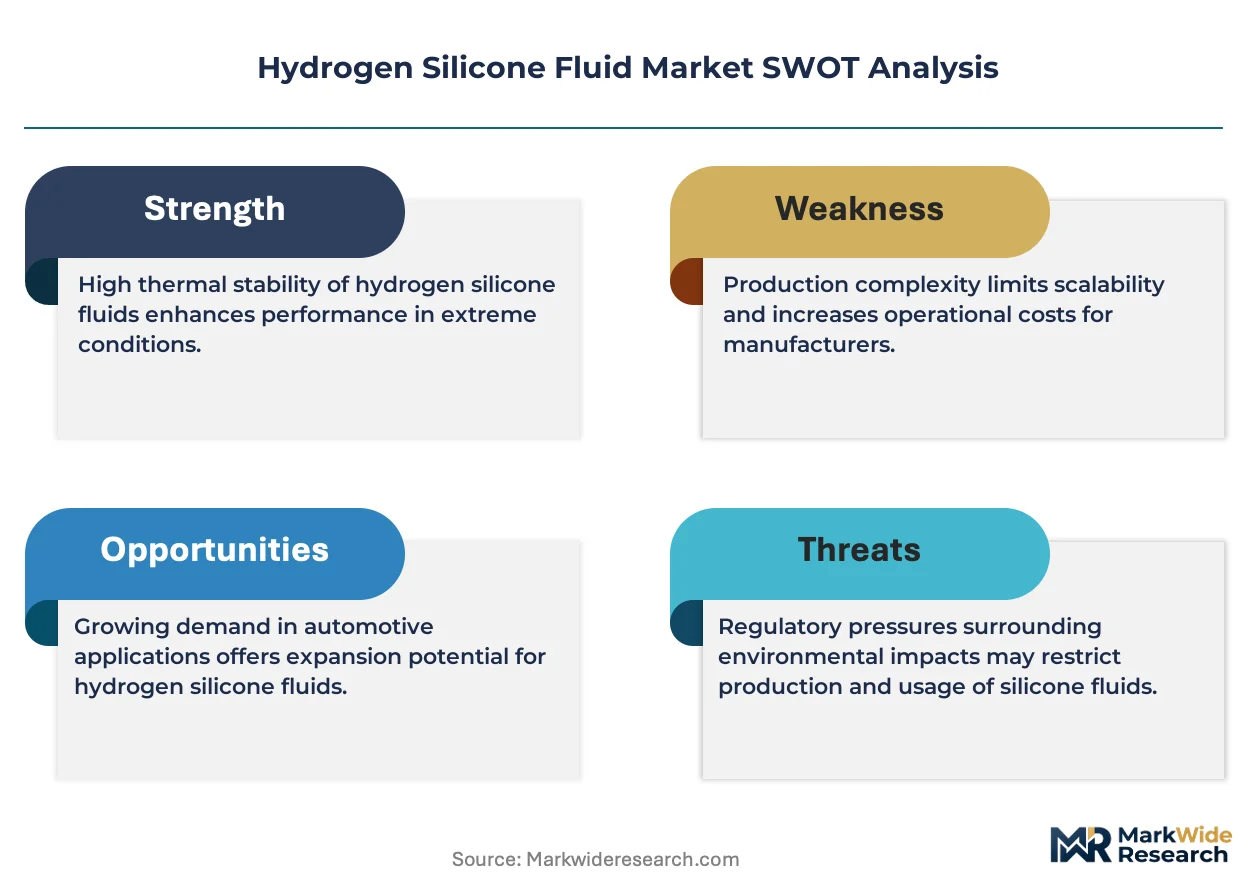
REACH compliance in Europe is tightening purity thresholds for silicone intermediates, forcing reformulation investments across the hydrogen silicone fluid supply base while simultaneously opening premium positioning for certified grades.
Growth Catalysts
- Electronics manufacturing clustering:China's Guangdong province concentrates demand from semiconductor packaging and thermal management applications, pulling high-purity fluid volumes through dedicated supply corridors.
- REACH registration thresholds:ECHA mandates for hydride-functional siloxanes above one-tonne volumes are consolidating qualified supplier pools, advantaging incumbent producers with established toxicological dossiers.
- Long-wear cosmetic formulations:South Korean cosmetics formulators are expanding procurement of hydrogen silicone fluids for skin formulations requiring extended stability under humid conditions.
Market Restraints
- Methyl chloride feedstock volatility:Captive silicon metal and methyl chloride assets concentrate upstream control with Asian integrated producers, exposing non-integrated converters to input cost swings.
- Siloxane emission scrutiny:EPA oversight of volatile methylsiloxanes in US industrial emissions is elevating purification capital requirements for domestic production assets.
- Water-based formulation substitution:Emulsion-format silicone alternatives are gaining traction in textile finishing as environmental compliance tightens, compressing neat fluid volumes in select applications.
Strategic Opportunities
- Biomedical gel certification:Biocompatibility certification for cushioning applications creates pricing power in gel segments where regulatory barriers limit supplier entry.
- MEE effluent compliance:China's Ministry of Ecology and Environment is implementing stricter effluent limits on silicone monomer production, creating first-mover advantage for producers with pre-compliant purification infrastructure.
- Water-based textile channels:Environmental compliance tightening is accelerating emulsion format adoption in textile finishing, opening formulation service revenue streams beyond commodity fluid sales.
Industry Challenges
- Hydrosilylation catalyst expertise:Proprietary catalyst systems for controlled Si-H functionalization require specialized organometallic chemistry capabilities that concentrate within Bavarian and Japanese technical centers.
- Pharmaceutical-grade certification timelines:FDA and EMA validation protocols for fluid-grade products extend commercialization cycles, tying up working capital during qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Silicone Fluid Market |
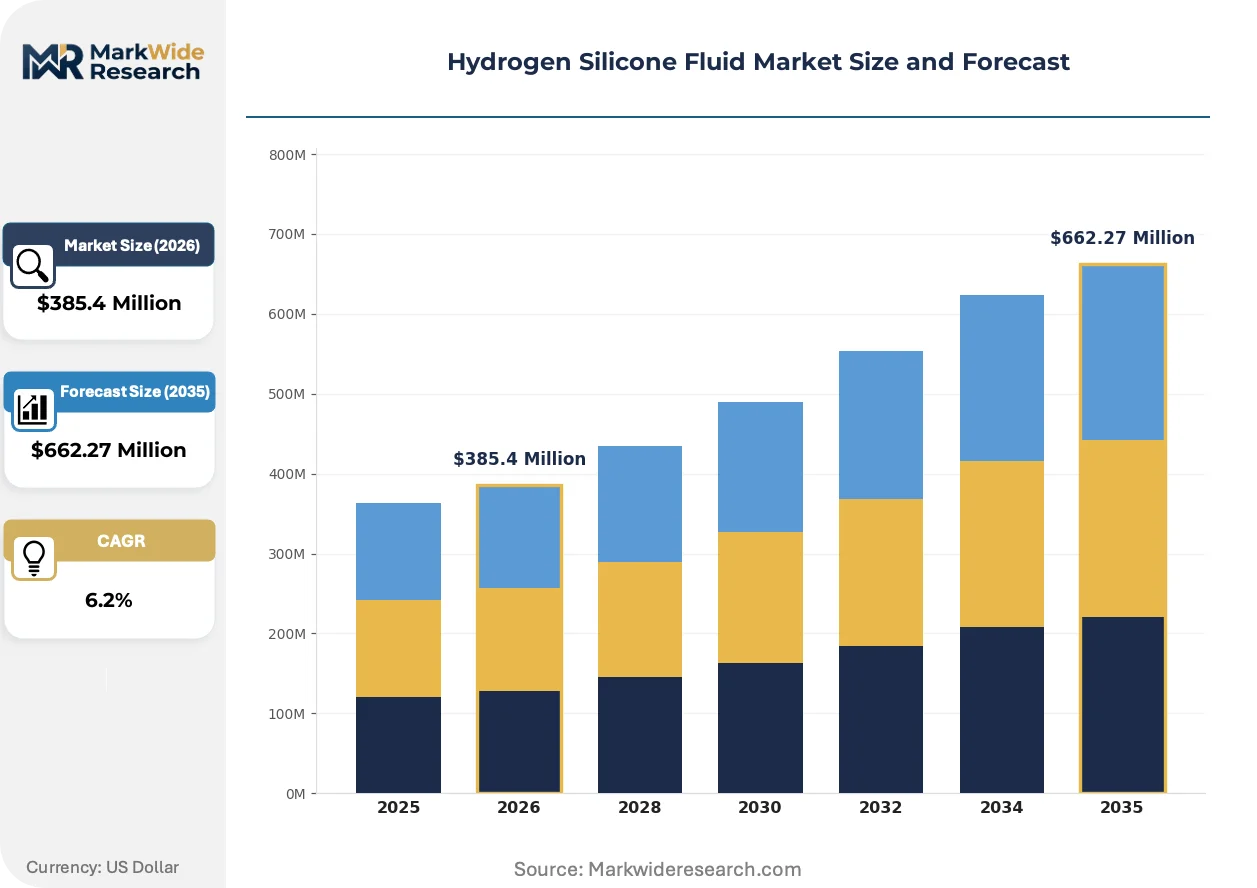
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Fluids, Resins, Gels Application: Cosmetics, Textile, Automotive, Industrial End User: Manufacturers, Laboratories, Retailers, Distributors Packaging Type: Bottles, Drums, Tanks, Pails |
| Companies Covered | Dow Corning Corporation, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Elkem ASA, Gelest Inc., KCC Corporation, Evonik Industries AG, Momentive Performance Materials Inc., Innospec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Silicone Fluid Market Trends and Innovations
Formulation chemistry is pivoting toward water-compatible delivery systems while thermal management demands pull higher-purity grades into semiconductor packaging. Electrification of transport and data infrastructure is reshaping performance specifications across end-use verticals.
Platinum-catalyzed hydrosilylation for precise Si-H bond placement is electrifying process control in elastomer crosslinking applications. Electronics manufacturers in South Korea and China are adopting these systems for thermal interface materials requiring exact cure profiles. The technology is compressing batch-to-batch variation penalties that previously eroded margin in high-specification segments.
REACH registration requirements for hydride-functional siloxanes are forcing toxicological investment decisions across European supply chains. Producers must commit to full dossier preparation or exit the market above one-tonne thresholds. Fluid-grade products face the steepest compliance burden due to pharmaceutical and electronics-grade purity requirements that intersect with registration obligations.
Buyer concentration in Guangdong electronics clusters is consolidating procurement leverage among a handful of large-scale formulators. Long-term supply agreements with embedded technical service components are displacing spot-market transactions for high-purity grades. This pattern is most visible in thermal management applications where qualification cycles lock in supplier relationships across multi-year horizons.
Hydrogen Silicone Fluid Market Segmentation
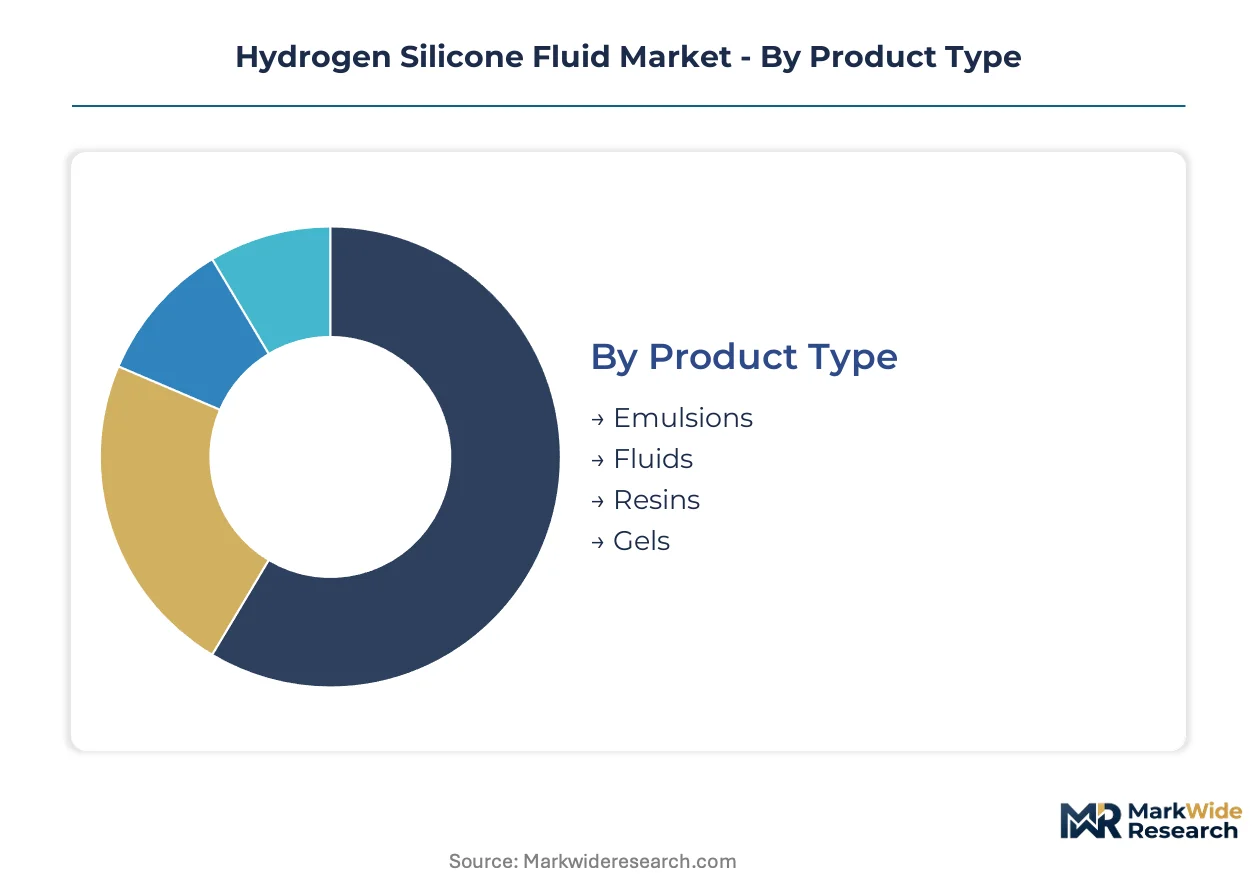
Hydrogen silicone fluid markets fragment across specification hierarchies that separate commodity crosslinkers from certified biomedical grades. Procurement patterns diverge sharply between bulk industrial buyers and formulation specialists requiring documented purity chains.
Product Type:
Specification thresholds separate pharmaceutical-grade fluids from industrial emulsions, with hydride content and viscosity bands determining end-use eligibility.
- Fluids:Polydimethylsiloxane backbones with terminal or pendant Si-H bonds, typically 10–1,000 centistokes viscosity, serve as crosslinking agents and reducing agents. Demand concentrates in Guangdong electronics clusters where semiconductor packaging requires thermal stability under high-heat conditions.
- Emulsions:Water-compatible delivery systems carry silicone actives in dispersed phase formats. South Korean textile finishers are accelerating procurement as MEE effluent limits tighten and water-based formulation mandates expand.
- Resins:Three-dimensional siloxane networks with hydride functionality provide electrical insulation in mature industrial applications.
- Gels:Soft, biocompatible cushioning materials require FDA and EMA validation protocols that extend commercialization timelines.
Fluids lead on scale; emulsions lead on momentum.
Application:
End-use performance requirements stratify procurement across humidity-stable cosmetics, thermal-management electronics, and durable industrial coatings.
- Cosmetics:Long-wear skin formulations in South Korea leverage hydrogen silicone fluids for extended stability under humid conditions. MFDS cosmetic safety assessments are tightening purity documentation requirements for imported silicone intermediates.
- Textile:Water-based finishing systems displace solvent carriers as environmental compliance tightens across Chinese and European dye houses.
- Automotive:Thermal interface materials in electric powertrains require precise cure profiles from platinum-catalyzed hydrosilylation systems.
- Industrial:High-heat elastomer crosslinking applications command premium positioning where thermal degradation resistance is non-negotiable.
Cosmetics commands margin premiums; textile shows steepest expansion trajectory.
End User:
Buyer scale and technical capability determine whether procurement flows through integrated manufacturers or specialized distribution channels.
- Manufacturers:Large-scale formulators in Guangdong electronics clusters consolidate procurement leverage through multi-year supply agreements with embedded technical service components.
- Laboratories:R&D facilities and quality control operations require small-batch, high-purity grades with full certification dossiers.
- Retailers:Specialty chemical distributors serve mid-tier formulators lacking direct supplier relationships.
- Distributors:Regional logistics networks bridge geographic gaps between Bavarian and Asian production centers and dispersed industrial consumers.
Manufacturers dominate volume capture; laboratories drive specification innovation.
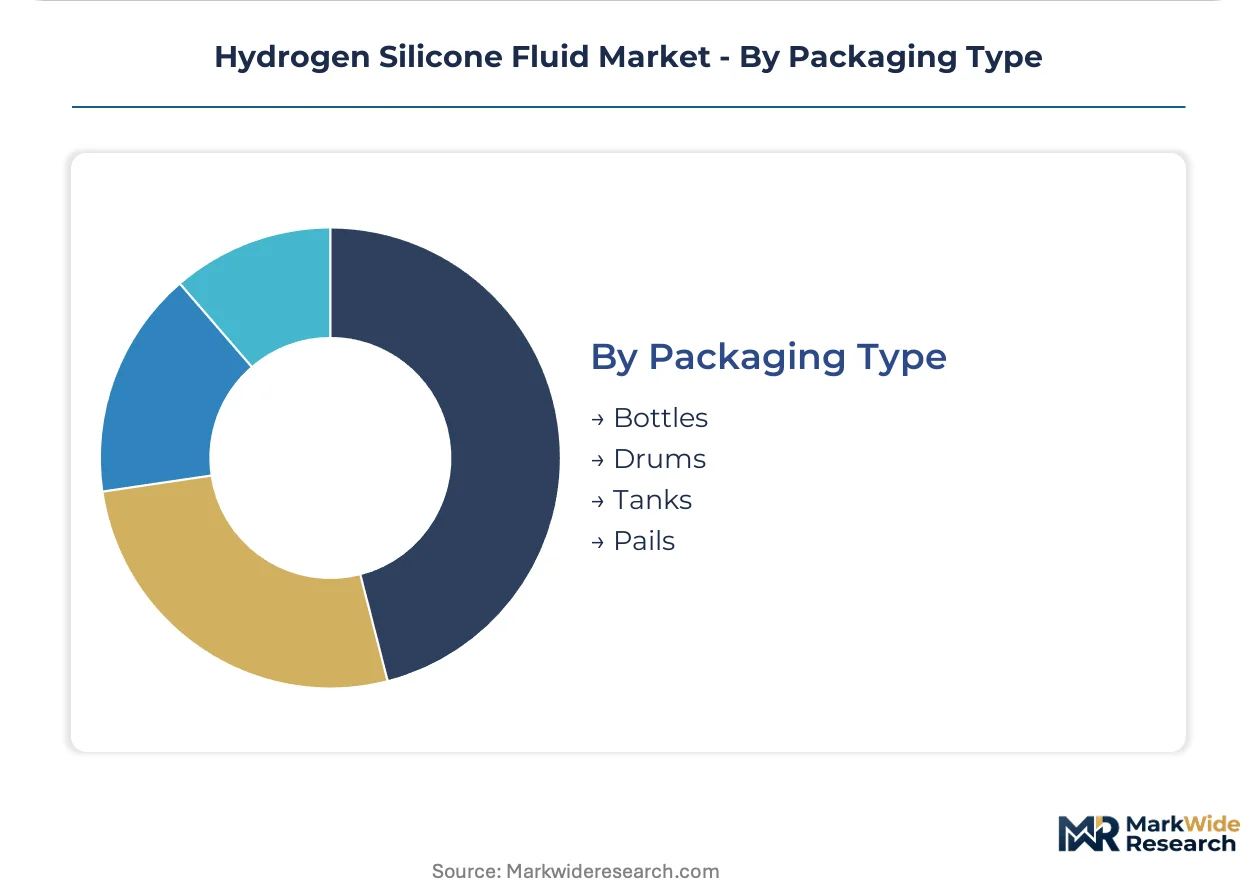
Packaging Type:
Container selection tracks volume scale, purity preservation requirements, and regulatory documentation needs across the value chain.
- Drums:Standard 200-liter steel containers serve mid-volume industrial buyers with established handling infrastructure and moderate purity requirements.
- Tanks:Bulk liquid transport systems support Guangdong electronics manufacturers with dedicated supply corridors and just-in-time delivery contracts.
- Bottles:Small-format packaging protects pharmaceutical-grade fluids from contamination during laboratory and pilot-scale use.
- Pails:Intermediate 20-liter containers balance portability with volume efficiency for specialty formulators and regional distributors.
Tanks dominate industrial throughput; bottles carry the highest per-liter value realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province concentrates electronics and personal care manufacturing clusters that dominate hydrogen silicone fluid offtake across the forecast window.
China
Guangdong electronics manufacturers pull high-purity fluid volumes for semiconductor packaging and thermal management applications. MEE effluent limits on silicone monomer production cascade into hydrogen fluid cost structures. Shenzhen and Dongguan clusters consolidate procurement leverage through dedicated supply corridors.
South Korea
Cosmetics formulators in Seoul Capital Area expand procurement for long-wear skin formulations requiring extended stability under humid conditions. MFDS cosmetic safety assessments tighten purity documentation requirements for imported silicone intermediates. Busan-Ulsan chemical complexes anchor domestic hydrosilylation capacity.
Germany
Bavarian manufacturing scale supports proprietary hydrosilylation catalyst systems for controlled Si-H functionalization. ECHA REACH mandates for hydride-functional siloxanes above one-tonne volumes consolidate qualified supplier pools. Wacker Chemie AG anchors competitive positioning through captive technical centers.
United States
EPA oversight of volatile methylsiloxanes in industrial emissions elevates purification capital requirements for domestic production assets. Dow Corning Corporation leverages backward integration into silane precursors to secure feedstock continuity across North American operations. Texas and Louisiana petrochemical corridors concentrate methyl chloride supply infrastructure.
Japan
Shin-Etsu Chemical Co., Ltd. dominates Asian supply corridors with captive methyl chloride and silicon metal assets. METI industrial standards shape performance specifications for electronics-grade hydrogen silicone fluids. Kanto and Kansai manufacturing belts concentrate precision chemical synthesis capabilities.
Hydrogen Silicone Fluid Market Competitive Landscape
Global majors compete with regional champions across catalyst technology and feedstock integration dimensions. The supplier base stratifies into integrated siloxane producers, specialty chemical converters, and formulation service providers. Three archetypes dominate: backward-integrated petrochemical conglomerates, organometallic chemistry specialists, and regional distribution platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers defend positioning in qualified supply pools.
Within the integrated producer tier, Dow Corning Corporation and Wacker Chemie AG exemplify archetypes anchored in captive precursor supply and proprietary process technology. Shin-Etsu Chemical Co., Ltd. occupies a position representing Asian manufacturing scale with metals-to-siloxanes integration. These three entities collectively illustrate how geographic clustering of feedstock assets and technical centers shapes competitive boundaries across the hydrogen silicone fluid value chain.
| Leading Market Players |
|---|
| Dow Corning Corporation |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Elkem ASA |
| Gelest Inc. |
| KCC Corporation |
| Evonik Industries AG |
| Momentive Performance Materials Inc. |
| Innospec Inc. |
| Others |
Pricing and Supply Chain Analysis
Methyl chloride spot indices in Asian petrochemical corridors cascade directly into hydrogen silicone fluid pricing tiers, compressing margins for non-integrated converters while amplifying capture rates for producers with captive silicon metal and methyl chloride assets in Guangdong and Kanto manufacturing belts.
Pricing Analysis
Input-cost pass-through from silicon metal and methyl chloride volatility stratifies pricing across three tiers: pharmaceutical-grade fluids command premium positioning due to FDA and EMA validation protocols, industrial emulsions compete on volume scale, and commodity crosslinkers face persistent cost compression. Price differentiation rests on certification grade and geographic delivery cost, with Guangdong electronics clusters leveraging multi-year offtake agreements to lock in supply security. Pricing pressure intensifies in standard-grade segments as water-based formulation alternatives displace neat fluid volumes in textile finishing applications. Laboratory buyers exhibit lowest price sensitivity due to small-batch certification requirements, while bulk industrial formulators negotiate aggressively on volume commitments.
Supply Chain Analysis
Single-source vulnerability sits with Asian integrated producers controlling captive methyl chloride and silicon metal supply, concentrating upstream leverage in Guangdong province, Kanto manufacturing belts, and Bavarian technical centers. The hydrogen silicone fluid supply chain draws from methyl chloride, silicon metal, and platinum-group catalyst inputs, with hydrosilylation chemistry capabilities clustering in German and Japanese organometallic specialist facilities. Tariff exposure on silane precursors and semiconductor-grade purification equipment presents structural risk for non-integrated converters dependent on cross-border equipment procurement. Distribution runs through dedicated supply corridors serving Guangdong electronics clusters, supplemented by regional distribution platforms bridging geographic gaps between production centers and dispersed industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hydrogen silicone fluids rests on pharmaceutical-grade certification premiums and MEE pre-compliant purification infrastructure that captures cost-down advantages as Chinese effluent limits tighten.
For Market Incumbents: Hedge methyl chloride feedstock exposure through backward integration into silane precursors or long-term supply agreements with Guangdong silicon metal producers. Lock in qualified supplier status under REACH registration thresholds by accelerating toxicological dossier completion for hydride-functional siloxanes above one-tonne volumes. Defend positioning against water-based formulation substitution by embedding technical service components in multi-year supply agreements with Guangdong electronics manufacturers. For New Entrants and Emerging Players: Platinum-catalyzed hydrosilylation process control systems offer a technology-first wedge into thermal interface material segments where batch-to-batch variation penalties erode incumbent margins. Target biomedical gel certification white space where FDA and EMA validation timelines create regulatory barriers limiting supplier entry. Pursue formulation service revenue models in South Korean textile finishing channels as MEE effluent limits accelerate emulsion-format adoption beyond commodity fluid sales. For Investors and Strategic Acquirers: Asymmetric upside sits with organometallic chemistry specialists possessing proprietary catalyst systems for controlled Si-H functionalization, given capability scarcity in Bavarian and Japanese technical centers. Five-to-ten year viability favors producers with pre-compliant purification infrastructure in China and established REACH dossiers in Europe. Watch for inflection signals in Guangdong procurement leverage concentration, where buyer consolidation among large-scale formulators may shift supplier pricing power dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Secures feedstock continuity against methyl chloride volatility in North American and Asian operations. |
| REACH Toxicological Dossier Investment | Consolidates qualified supplier pools above one-tonne thresholds under ECHA mandates. |
| Biomedical Gel Certification Pathway | Creates pricing power in cushioning applications where FDA validation limits competitor entry. |
| MEE Pre-Compliant Purification Infrastructure | Captures first-mover advantage as Chinese effluent limits cascade into hydrogen fluid cost structures. |
| Long-Term Supply Agreement with Technical Service | Locks in multi-year relationships with Guangdong electronics clusters undergoing procurement consolidation. |
Research Methodology
Coverage spans China, South Korea, Germany, United States, and Japan, with primary inputs from each market combining interviews with plant managers at integrated siloxane producers, procurement leads at Guangdong electronics manufacturers, distribution channel partners in specialty chemical logistics, and technical R&D directors in hydrosilylation catalyst development. Secondary validation draws from customs and trade data, ECHA REACH registration databases, SEC 10-K filings from petrochemical conglomerates, and MEE effluent compliance disclosures. Bottom-up segment modeling triangulates against top-down macroeconomic indicators to ensure consistency across regional production hub estimates.
Granularity-level framing applies specification-grade tiers, end-use industry verticals, packaging format categories, and regional production hub clusters across the modeling period. CAGRs derive from segmented volume-weighted averaging applied to each dimension, with cross-elasticity adjustments for substitution effects between emulsion and neat fluid formats. Industry-specific forecast inputs include semiconductor packaging demand trajectories in Guangdong, MFDS cosmetic safety assessment timelines in South Korea, and platinum-group metal price sensitivity in catalyst cost structures.
The model holds under stable regulatory enforcement trajectories for REACH and MEE compliance; deviation in tariff regimes on silane precursors or accelerated water-based formulation mandates would shift volume projections. Forecasts reflect documented assumptions regarding buyer concentration patterns and feedstock integration economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Trinitrotoluene (TNT) Market