
 Global Foundry Chemicals Market | 2026-2036
Global Foundry Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foundry Chemicals Market Foresight
Digital twin adoption in metal casting is fragmenting traditional process control architectures across foundry floors. ASK Chemicals GmbH leverages its binder portfolio to anchor European OEM supply chains for complex turbine castings. Vesuvius plc dominates refractory coatings for continuous steel casting, while Imerys S.A. specializes in mineral-based mold wash formulations for high-integrity aluminum components. Evonik Industries AG competes through silicon chemistry expertise in precision investment casting segments.
Foundry chemicals encompass consumable formulations that control mold integrity, metal fluidity, surface finish, and defect prevention during molten metal shaping. These materials typically operate at temperatures exceeding 1,500°C in ferrous applications and require controlled thermal decomposition profiles to prevent gas porosity in finished castings. Binder chemicals command the largest product type position due to their irreplaceable role in sand mold cohesion, though release agents represent the fastest-expanding category as die casting intensifies for electric vehicle powertrain housings. Investment casting sustains premium pricing power through aerospace-grade certification requirements, while sand casting occupies volume leadership across construction equipment and heavy machinery supply chains.
EPA emissions standards for metalcasting facilities in the United States mandate particulate and volatile organic compound controls that elevate demand for low-emission binder systems and water-based coatings. ECHA's REACH framework restricts specific aromatic compounds in European foundry resins, redirecting formulation R&D toward bio-based alternatives. China's MEE enforces dual carbon compliance thresholds that favor inorganic binder adoption over traditional furan systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
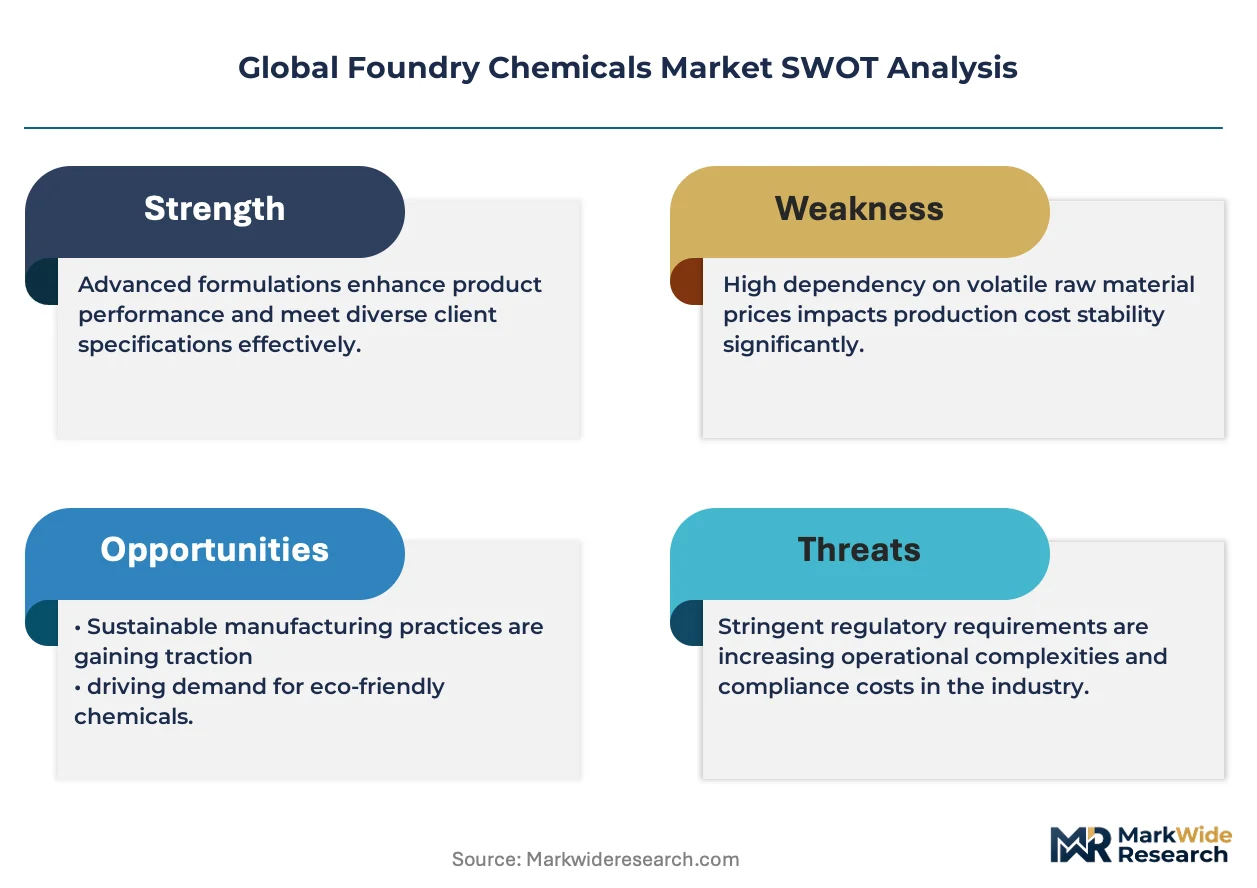
EPA emissions mandates and China's MEE dual carbon enforcement are compressing permissible chemistries for mold binders, forcing foundries toward water-based and inorganic formulations that alter traditional supplier economics.
Growth Catalysts
- Aerospace component certification:Turbine blade manufacturers demand aerospace-grade investment casting chemicals that meet FAA and EASA traceability standards, tightening supplier qualification windows.
- REACH aromatic restrictions:ECHA's framework on phenolic compounds redirects European formulation R&D toward bio-based resin alternatives, opening patent whitespace for compliant binder systems.
- India PLI capital goods expansion:Domestic casting capacity additions under the scheme accelerate consumption of high-performance mold coatings and core binders for construction equipment supply chains.
Market Restraints
- Furfuryl alcohol price volatility:Furan resin production costs swing with bioethanol feedstock markets, squeezing margin predictability for traditional no-bake binder suppliers.
- Refractory mineral concentration:High-purity zircon and chromite deposits cluster in South Africa and Kazakhstan, exposing coating formulators to geopolitical supply disruption.
- Inorganic binder performance gaps:Sodium silicate systems struggle with collapsibility in complex core geometries, limiting displacement of organic resins in precision applications.
Strategic Opportunities
- Vietnam foundry investment wave:Japanese and Korean OEMs relocate casting operations to northern industrial zones, creating greenfield demand for technical service partnerships.
- Digital twin integration:Convergence of thermal simulation software with real-time chemical dosing systems enables predictive mold quality management.
- EU Green Deal carbon border adjustments:CBAM implementation favors low-emission binder imports, rewarding early certification by non-European suppliers.
Industry Challenges
- Process metallurgist scarcity:Retirement waves deplete expertise in pyrolysis gas modeling for defect prevention, forcing reliance on external technical consultants.
- Multi-jurisdiction formulation registration:Divergent EPA, ECHA, and MEE substance inventories strand R&D investments when chemistries clear one market but fail another.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foundry Chemicals Market |
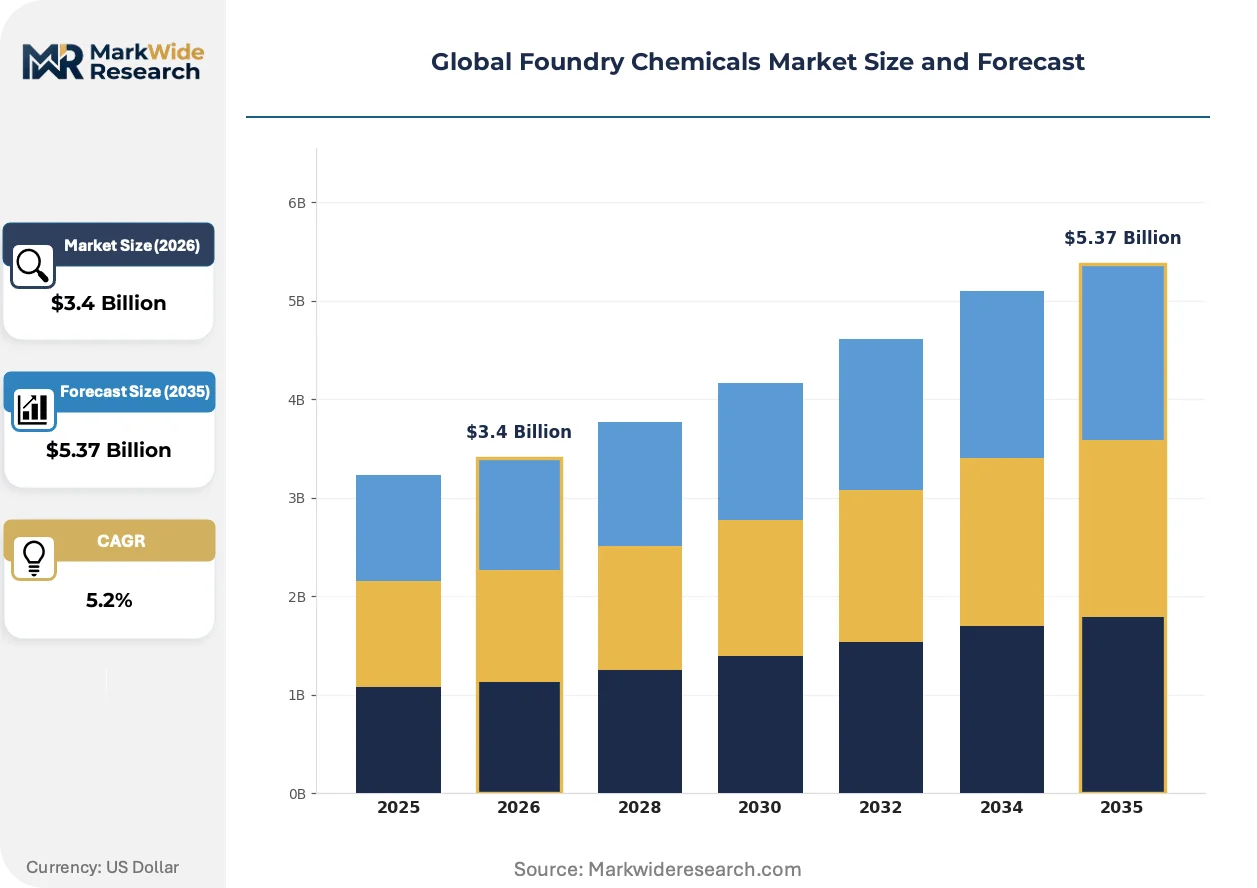
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binder Chemicals, Coatings, Degassing Agents, Mold Wash, Core Oil, Release Agents Process Type: Sand Casting, Die Casting, Investment Casting, Continuous Casting, Lost Foam Casting, Shell Molding End User Industry: Heavy Machinery, Construction Equipment, Electrical Components, Consumer Appliances, Defense Manufacturing, Aerospace Components Form: Liquid, Powder, Paste, Emulsion, Granular, Gel |
| Companies Covered | ASK Chemicals GmbH, HA International Ltd., Imerys S.A., Vesuvius plc, Hüttenes-Albertus Chemische Werke GmbH, BASF SE, Ashland Global Holdings Inc., Evonik Industries AG, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foundry Chemicals Market Shifts & Advancements
Formulation science and process digitization are converging to compress development cycles and enable mass customization of mold media properties for specific alloy systems.
Ceramic shell slurry technology is migrating from traditional colloidal silica binders toward advanced alumina-silicate sol-gel systems that withstand higher pouring temperatures. Aerospace investment casters in the United States and France adopt these materials for single-crystal turbine blade production. The shift is migrating from specialty aerospace applications toward broader acceptance in medical implant casting, compressing the premium pricing window for conventional silica-based suppliers.
REACH authorization requirements for chromium trioxide in refractory coatings force European foundries to reformulate mold wash systems or seek substitution through zircon-based alternatives. The industrial consequence extends beyond compliance costs to altered surface finish specifications for aluminum cylinder head castings. German automotive suppliers accelerate qualification of titanate-modified coatings to maintain die release performance without hexavalent chromium exposure liabilities.
Buyer concentration among tier-one automotive powertrain manufacturers drives specification unification across multiple foundry suppliers. Procurement teams at German and Japanese OEMs now mandate identical binder certifications from sand casting subcontractors across three continents. This consolidation is most visible in electric motor housing programs, where die casting release agent specifications flow directly from vehicle platform engineering centers to remote Mexican and Polish foundry operations.
Global Foundry Chemicals Market Segmentation
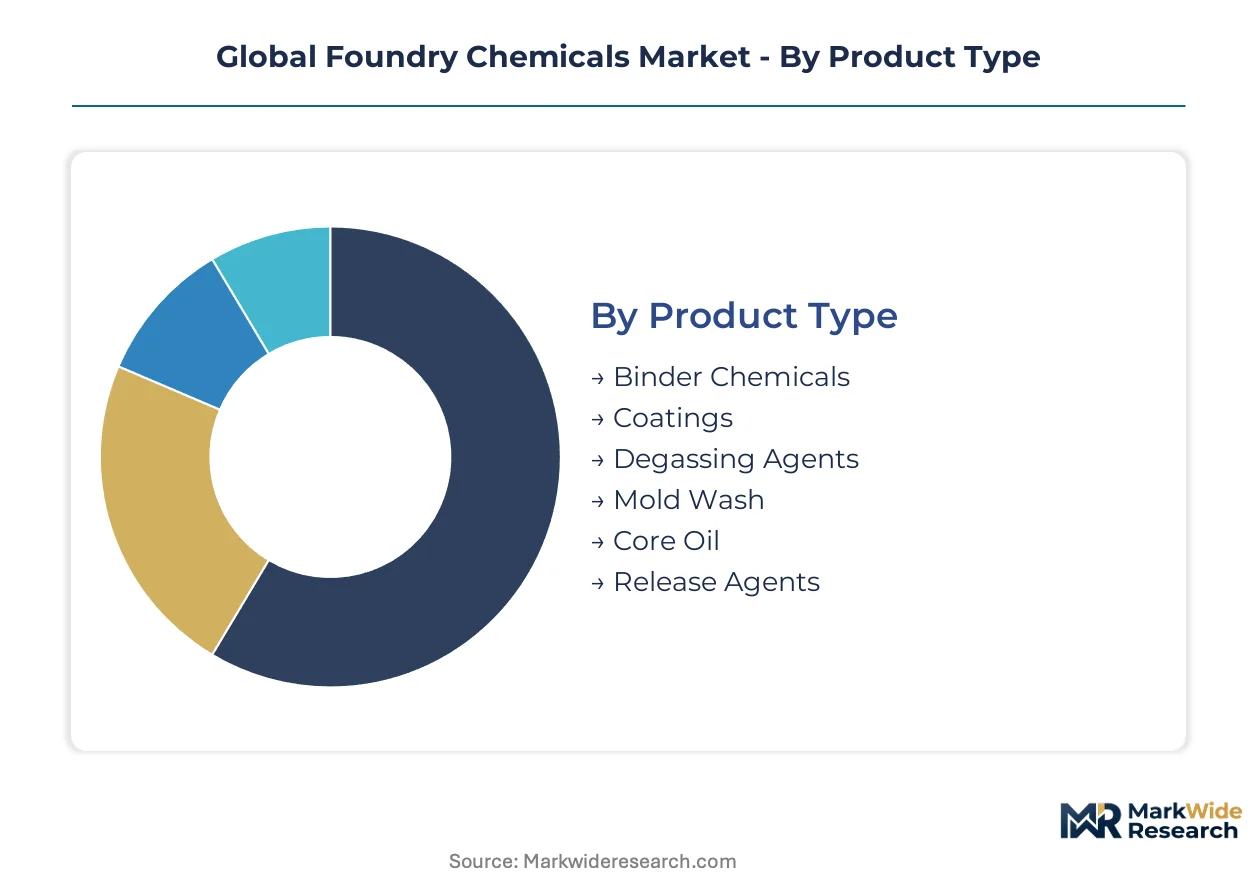
Foundry chemicals exhibit divergent consumption patterns across product categories, with some formulations turning over weekly in high-volume sand operations while others persist for months in precision investment casting cycles. Understanding these temporal dynamics alongside structural segmentation enables suppliers to align inventory positioning with actual foundry demand rhythms.
Product Type:
Binder chemicals cycle fastest in no-bake sand systems where daily core production consumes tonnage quantities, while release agents and mold washes turn over more slowly in die casting cells running continuous campaigns.
- Binder Chemicals:These resin and inorganic formulations provide structural integrity to sand molds and cores through controlled thermal decomposition. Demand concentrates in Indian construction equipment foundries expanding under PLI scheme incentives, where high core production volumes accelerate chemical turnover. Furan and phenolic systems dominate ferrous applications, though sodium silicate binders gain traction under China's MEE dual carbon enforcement.
- Release Agents:Die casting lubricants and protective coatings enable clean part ejection from permanent molds while extending tool life. Consumption is accelerating in Vietnamese industrial zones where Japanese and Korean OEMs relocate electric vehicle powertrain housing production, creating greenfield demand for water-based and graphite formulations.
- Coatings:Refractory barrier layers protect mold surfaces from molten metal erosion and control surface finish quality. Zircon-based systems substitute for chromium trioxide formulations under REACH authorization pressures in European automotive supply chains.
- Degassing Agents:Aluminum and magnesium foundries deploy these fluxes and inert gas precursors to eliminate hydrogen porosity in critical castings. Rotary impeller degassing units in US aerospace facilities drive consumption of hexachloroethane alternatives.
- Mold Wash:Mineral suspensions prevent metal penetration into sand molds and improve casting surface integrity. High-integrity aluminum cylinder head producers in Germany qualify titanate-modified systems to eliminate hexavalent chromium exposure.
- Core Oil:Traditional binder oils for oil sand core production persist in legacy foundry operations with limited environmental regulatory pressure. Declining share reflects displacement by synthetic resin systems in modern facilities.
Binder chemicals anchor the volume base while release agents gain share at the steepest rate.
Process Type:
Cost tier stratification separates high-investment precision processes from commodity volume methods, with capital intensity directly determining chemical specification stringency and supplier qualification requirements.
- Investment Casting:Ceramic shell slurry systems and colloidal silica binders enable near-net-shape production of complex geometries for aerospace and medical applications. Single-crystal turbine blade manufacturers in France and the United States drive adoption of advanced alumina-silicate sol-gel formulations that withstand superalloy pouring temperatures exceeding 1,600°C.
- Sand Casting:The dominant volume process employs chemically bonded sand molds for ferrous and non-ferrous components across construction equipment and heavy machinery supply chains. EPA emissions mandates for US metalcasting facilities elevate demand for low-VOC binder systems and water-based coatings in this segment.
- Die Casting:High-pressure aluminum and magnesium injection into permanent steel dies requires specialized lubricants, plunger tip dressings, and die release formulations. Automotive powertrain procurement teams at German and Japanese OEMs now mandate identical release agent certifications across Mexican and Polish subcontractor networks.
- Continuous Casting:Steel slab and billet production consumes refractory coatings and mold fluxes to control meniscus stability and surface quality. Vesuvius plc dominates this segment through technical service partnerships with integrated steel producers.
- Lost Foam Casting:Expandable polystyrene pattern vaporization during metal pouring requires specialized refractory coatings to prevent sand penetration and control gas evolution. Limited adoption outside automotive engine block applications constrains segment scale.
- Shell Molding:Phenolic resin-coated sand processes deliver exceptional surface finish for small-to-medium precision castings. Residual aromatic compound restrictions under ECHA REACH frameworks redirect formulation R&D toward bio-based resin alternatives.
Sand casting commands the broadest installed base while investment casting sustains the highest value per kilogram of chemical consumed.
End User Industry:
Customer concentration patterns vary sharply, with aerospace and defense procurement teams imposing multi-year qualification protocols while construction equipment buyers rotate suppliers based on spot pricing and logistics performance.
- Heavy Machinery:Mining equipment and agricultural machinery castings demand high-integrity ferrous components with controlled microstructures. Indian domestic capacity expansion under capital goods PLI schemes accelerates consumption of phenolic resin binders and zircon-based mold coatings.
- Aerospace Components:FAA and EASA traceability requirements for turbine blade investment casting impose stringent chemical certification and batch documentation standards. ASK Chemicals GmbH anchors European OEM supply chains through aerospace-grade binder portfolios.
- Construction Equipment:Excavator and loader manufacturers source large sand-cast structural components from distributed foundry networks. Procurement specifications emphasize cost efficiency over premium chemical performance in this segment.
- Electrical Components:Motor housings and transformer tank castings require pressure-tight aluminum and ductile iron grades. Die casting intensification for electric vehicle powertrain applications elevates release agent consumption.
- Defense Manufacturing:Armored vehicle and weapons system castings demand ballistic-grade steel and aluminum alloys with certified mechanical properties. Supply security considerations favor domestic chemical sourcing in US and European defense industrial bases.
- Consumer Appliances:Refrigeration compressor housings and washing machine components utilize die-cast aluminum and zinc alloys with cosmetic surface requirements. High-volume, low-margin production favors commodity chemical formulations.
Heavy machinery anchors procurement volume while aerospace components command the steepest specification premiums.
Form:
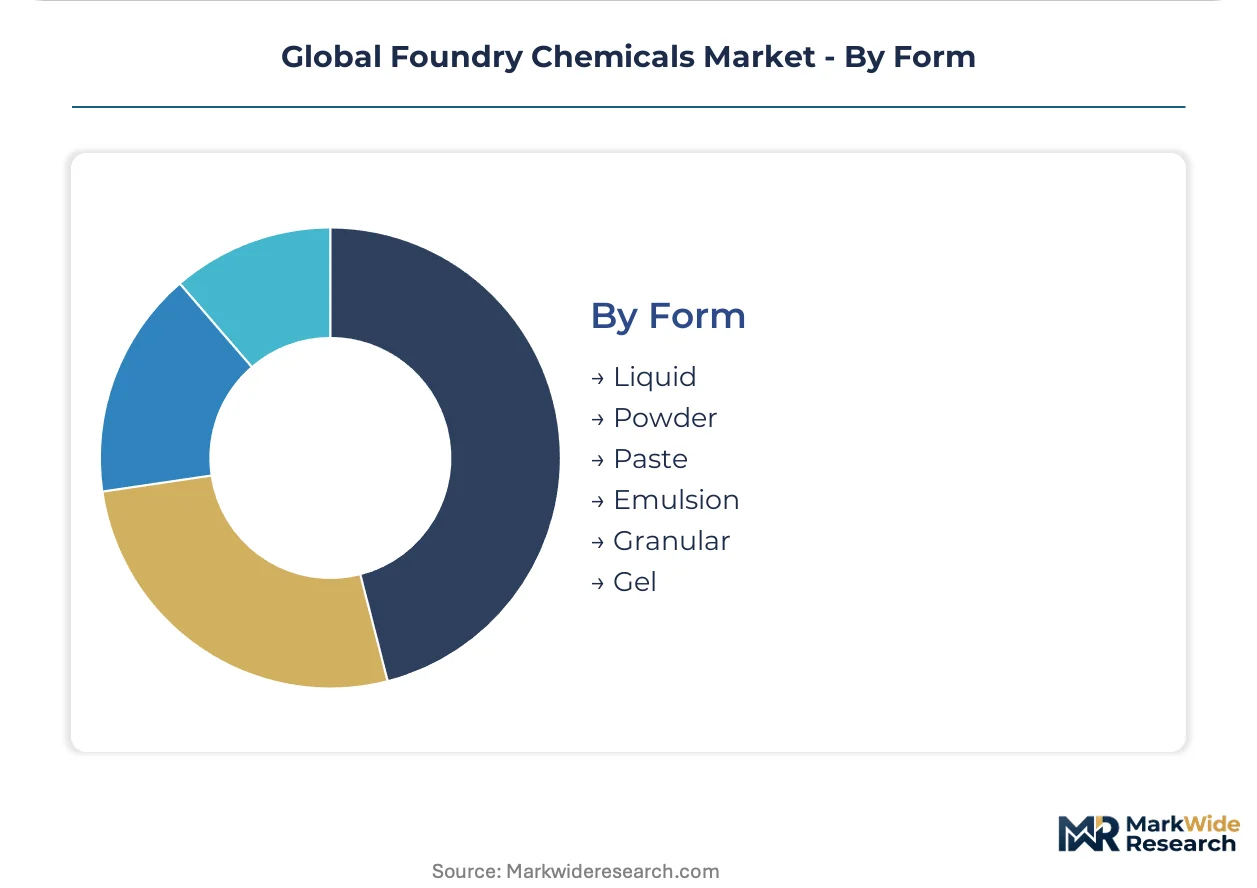
Supply logistics and dosing automation compatibility determine form selection, with liquid and powder dominating bulk consumption while specialized paste and gel formats serve precision application niches.
- Liquid:Pumpable resin binders, aqueous coatings, and solvent-based release agents enable continuous metering through automated dispensing systems. Standard format for high-volume sand and die casting operations.
- Powder:Refractory minerals, fluxes, and inorganic binders store stably and transport efficiently to remote foundry locations. Chromite and zircon concentrates from South African deposits supply coating formulators.
- Paste:High-viscosity mold dressings and plunger tip lubricants apply through manual or robotic swabbing in die casting cells. Thixotropic rheology prevents sag on vertical die surfaces.
- Emulsion:Water-based release agents and mold washes reduce VOC emissions while maintaining lubrication performance. EPA and MEE regulatory pressures accelerate displacement of solvent-based alternatives.
- Granular:Pre-coated shell molding sands and resin-coated proppant-style binders enable consistent refractory performance with simplified handling. Imerys S.A. specializes in mineral-based formulations for aluminum applications.
- Gel:Specialized ceramic shell slurries and thixotropic mold coatings provide controlled rheology for complex core geometries. Limited to investment casting and precision sand applications.
Liquid formulations dominate tonnage movement while emulsion formats climb fastest on environmental compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundry chemical exports supply precision casting operations across French aerospace clusters and Polish automotive subcontractor networks, creating a north-south corridor shaped by REACH compliance timelines and OEM certification requirements.
United States
EPA emissions mandates for metalcasting facilities compress permissible chemistries for mold binders, elevating demand for low-VOC phenolic systems and water-based coatings. FAA traceability requirements for turbine blade investment casting tighten supplier qualification windows for aerospace-grade formulations. Foundry chemical consumption concentrates in Ohio and Michigan automotive supply chains where die casting intensifies for electric vehicle powertrain housings.
Germany
ECHA REACH restrictions on aromatic compounds redirect formulation R&D toward bio-based resin alternatives, opening patent whitespace for compliant binder systems. German automotive suppliers accelerate qualification of titanate-modified mold wash coatings to eliminate hexavalent chromium exposure liabilities. Industrial chemical production clusters in North Rhine-Westphalia supply construction equipment foundries across the Ruhr industrial zone.
China
MEE dual carbon enforcement favors inorganic binder adoption over traditional furan systems in domestic sand casting operations. Sodium silicate binders gain traction as foundries reformulate to meet emissions thresholds. Casting capacity expansion in Jiangsu and Shandong provinces accelerates consumption of mold coatings for heavy machinery component production.
India
PLI scheme incentives for capital goods expand domestic casting capacity, accelerating consumption of high-performance core binders and zircon-based mold coatings. Phenolic resin systems dominate ferrous applications in construction equipment supply chains. Foundry chemical demand concentrates in Maharashtra and Gujarat industrial corridors where mining equipment manufacturers source large structural castings.
Vietnam
Japanese and Korean OEM relocation of casting operations to northern industrial zones creates greenfield demand for technical service partnerships in die casting release agents. Water-based and graphite formulations gain preference as environmental enforcement tightens. Haiphong and Bac Ninh provinces host expanding electric vehicle powertrain housing production facilities.
Global Foundry Chemicals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where binder chemistry expertise anchors premium positioning. The market exhibits moderate consolidation among European and Asian suppliers with established aerospace certification pathways, while regional formulators capture volume share in construction equipment segments. Strategic archetypes include integrated resin-chemistry conglomerates, mineral-specialist refractory houses, and precision-casting technology licensors. Dominant competitive moves center on portfolio diversification into bio-based formulations and geographic expansion through technical service partnerships in Southeast Asian industrial zones.
Within the European specialty chemical tier, ASK Chemicals GmbH and Hüttenes-Albertus Chemische Werke GmbH exemplify binder-chemistry depth, while Imerys S.A. occupies a position among mineral-based formulation specialists. Vesuvius plc represents the refractory-technology archetype with continuous casting service integration. These entities anchor competitive positioning through certification density rather than scale economics alone.
| Leading Market Players |
|---|
| ASK Chemicals GmbH |
| HA International Ltd. |
| Imerys S.A. |
| Vesuvius plc |
| Hüttenes-Albertus Chemische Werke GmbH |
| BASF SE |
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| Huntsman Corporation |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors shape cost dynamics for European binder chemical deliveries, concentrating supply power among North Rhine-Westphalia producers while forcing downstream price differentiation between REACH-compliant premium formulations and commodity furan systems.
Pricing Analysis
Next-generation alumina-silicate sol-gel binders command substantial premiums over legacy colloidal silica systems, while sodium silicate alternatives trade at economy positioning. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified ceramic shell slurries from automotive-grade mold washes and commodity construction equipment binders. Price differentiation hinges on EASA/FAA certification density and volume scale. Pricing pressure stems from furfuryl alcohol feedstock volatility squeezing traditional no-bake binder margins. Construction equipment buyers exhibit highest price sensitivity, while turbine blade manufacturers accept steep premiums for traceability documentation.
Supply Chain Analysis
Export controls on high-purity zircon and chromite concentrates from South Africa and Kazakhstan restrict refractory mineral flows to European coating formulators. Supply concentrates in Germany for precision binder chemistry, China for inorganic silicate systems, and India for phenolic resin expansion. Raw material dependencies include bioethanol for furan production, high-grade silica sand for mold media, and specialty aluminas for aerospace slurries. Single-source vulnerability in South African zircon deposits exposes coating manufacturers to geopolitical disruption. Distribution runs through technical service partnerships rather than commodity trading houses, with ASK Chemicals and Vesuvius maintaining direct foundry relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized pyrolysis gas modeling expertise is vanishing as veteran metallurgists retire, creating critical capability gaps that determine competitive survival across precision casting segments.
For Market Incumbents: Insulate aerospace certification portfolios through accelerated EASA/FAA qualification of bio-based resin alternatives before REACH aromatic restrictions tighten. Deepen captive supply of high-purity zircon through offtake agreements with South African miners to offset chromite substitution risks. Technical service density in Vietnamese industrial zones anchors Japanese OEM relationships against Korean competitor inroads. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese die casting release agents where Japanese and Korean OEM relocation creates greenfield technical service partnerships absent entrenched incumbents. Target water-based emulsion formulations for electric vehicle powertrain housing applications. Lead with environmental compliance credentials to bypass solvent-based incumbent relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with neglected foundry chemical divisions lacking aerospace certification pathways. Long-term viability favors mineral-specialist refractory houses with captive deposit access over pure-play resin formulators facing feedstock volatility. Watch sodium silicate binder performance improvements as the inflection signal for inorganic displacement of organic systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zircon Supply | Captive mineral access insulates Vesuvius and Imerys from South African export disruptions. |
| Bio-Based Resin R&D Partnerships | Collaboration with European biotech firms accelerates REACH-compliant phenolic alternatives for ASK Chemicals. |
| Vietnam Technical Service Expansion | Localized application engineering captures Japanese OEM die casting relocation in Haiphong industrial zones. |
| Digital Twin Platform Integration | Real-time chemical dosing convergence with thermal simulation software locks in predictive mold quality contracts. |
| EU Green Deal CBAM Pre-Certification | Early low-emission binder documentation rewards non-European suppliers with preferential import positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foundry plant managers, procurement leads at automotive OEMs, technical R&D directors at binder manufacturers, and distribution channel partners serving construction equipment networks. Secondary validation drew from customs and trade data, SEC filings of listed chemical conglomerates, and ECHA REACH substance inventory updates. Bottom-up volume modeling triangulated against top-down value estimates across product type, process technology, and end-use industry segments.
Calibration anchored historical consumption patterns to installed foundry capacity across the analysis window, with forward projections modeling segment-specific CAGRs derived from capacity expansion announcements and regulatory compliance timelines. Segmentation dimensions included binder chemistry family, casting process type, alloy system served, and regional production cluster. Forecast inputs incorporated EPA emissions mandate implementation schedules and PLI scheme disbursement trajectories for Indian capital goods.
Sensitivities concentrate around furfuryl alcohol price volatility, South African mineral export policy shifts, and sodium silicate performance breakthroughs in precision applications. Forecasts reflect documented assumptions on regulatory enforcement intensity and OEM qualification cycle durations. Material shifts in REACH authorization timelines or MEE dual carbon thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market