
 Shea Olein Market | 2026-2036
Shea Olein Market Size, Share, and Industry Trends Forecast 2026-2036
Shea Olein Market Outlook
Palm stearin is recalibrating competitive economics across the liquid shea fraction space as formulators weigh cost ratios against functional parity in emollient systems. BASF SE leverages its oleochemicals platform to secure multi-origin lipid streams for European cosmetic houses. The Savannah Fruits Company anchors its position through direct-sourced shea networks spanning northern Ghana and Burkina Faso. Sophim S.A differentiates via pharmaceutical-grade fractionation capabilities that serve dermo-cosmetic laboratories in France and Italy.
Shea olein is the liquid triglyceride fraction extracted from shea butter through controlled fractionation or solvent separation, typically yielding an oleic acid content of 55-70 percent with a melting point below 25 degrees Celsius, making it suitable for pumpable cosmetic bases and food-grade coating applications. Refined shea olein dominates volume flows into mass-market cosmetics where color stability and neutral odor are non-negotiable specifications, while organic shea olein commands premium positioning among certified clean beauty lines in France and Germany. Skin care products represent the fastest-growing application channel as indie brands and dermatological labels reformulate around plant-derived emollients with published comedogenic safety profiles.
REACH registration through ECHA governs chemical safety dossiers for shea olein imports into the European Union, while FDA oversight applies to cosmetic ingredient labeling and GRAS determinations for food-contact uses in the United States. BIS quality mandates in India and CDSCO pharmaceutical excipient standards create parallel compliance tracks for suppliers targeting multiple jurisdictions. Stakeholders must monitor how evolving EU Green Deal traceability requirements and emerging carbon border adjustments reshape origin documentation costs and cooperative certification premiums across West African supply corridors.
Market Dynamics
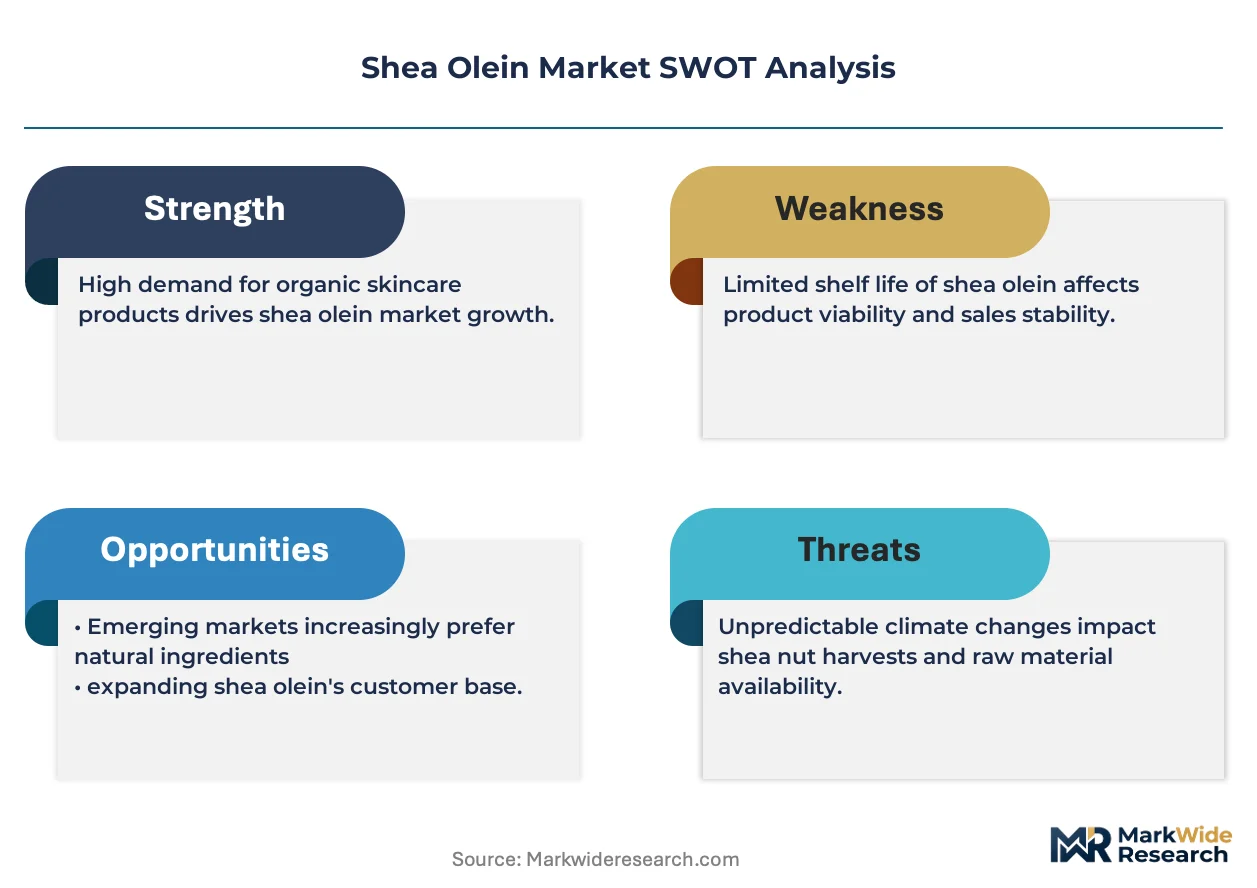
REACH compliance through ECHA is tightening purity thresholds for cosmetic-grade vegetable lipids, forcing formulators to requalify supply chains and cooperatives to invest in upgraded fractionation infrastructure across West African origin zones.
Growth Catalysts
- EU Green Deal traceability mandates:The EU Green Deal is accelerating demand for documented sustainable sourcing as European cosmetic houses require full origin disclosure for shea olein procurement from Ghana and Burkina Faso cooperatives.
- Clean beauty certification expansion:Indie skin care brands in France and Germany are reformulating around plant-derived emollients with published comedogenic safety profiles, pulling organic shea olein into premium positioning.
- Pumpable cosmetic base requirements:Low-melting-point lipid technology is enabling pumpable cosmetic formulations that substitute shea olein for less stable liquid fractions in mass-market personal care manufacturing.
Market Restraints
- Shea kernel supply concentration:Over seventy percent of raw shea nut processing concentrates in northern Ghana and Burkina Faso, exposing European formulators to climate-driven harvest volatility and cooperative capacity constraints.
- Palm stearin cost arbitrage:Fractionated palm oil derivatives from Southeast Asian refiners undercut shea olein on price in emollient applications where functional parity is acceptable to cost-optimized formulators.
- REACH registration burden:ECHA chemical safety dossier requirements impose fixed compliance costs that disproportionately burden small-scale West African exporters lacking dedicated regulatory affairs capacity.
Strategic Opportunities
- Pharmaceutical excipient expansion:CDSCO standards in India and emerging pharmaceutical-grade specifications in Italy are opening dermo-cosmetic laboratory channels for GMP-certified shea olein fractionation.
- Carbon border adjustment positioning:The EU's emerging carbon border mechanism creates first-mover advantage for cooperatives that pre-certify supply chain emissions documentation ahead of 2026 implementation timelines.
- Direct-to-brand cooperative platforms:Digital traceability infrastructure is enabling Ghanaian and Burkinabe cooperatives to bypass traditional commodity traders and contract directly with certified clean beauty houses in France and Germany.
Industry Challenges
- Fractionation technician scarcity:Advanced lipid separation expertise remains concentrated in European oleochemical facilities, constraining West African cooperatives from upgrading to pharmaceutical-grade production capabilities.
- Multi-jurisdiction certification sequencing:Suppliers targeting simultaneous REACH, FDA GRAS, and BIS compliance face non-harmonized testing protocols that extend product qualification timelines by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shea Olein Market |
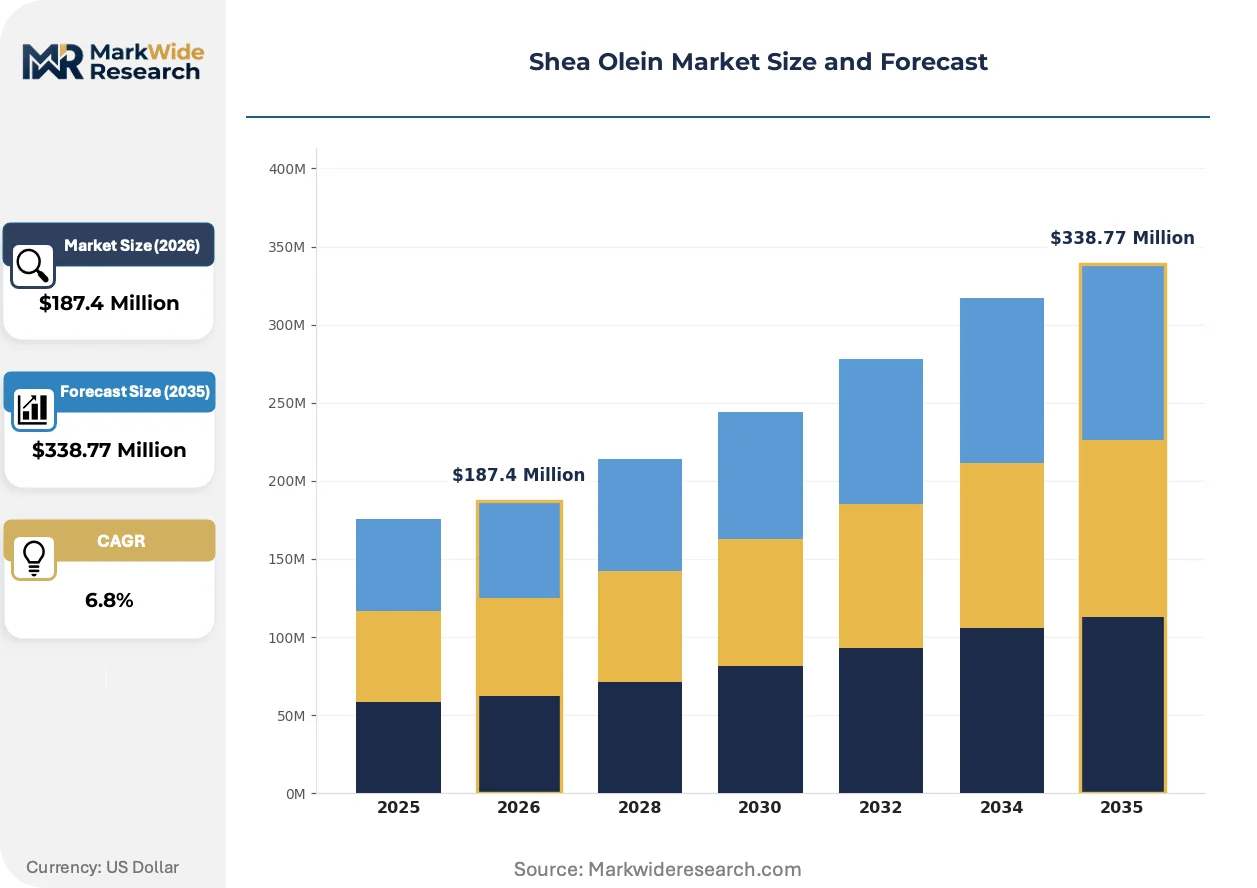
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Shea Olein, Unrefined Shea Olein, Organic Shea Olein, Conventional Shea Olein Application: Cosmetics, Food Industry, Pharmaceuticals, Skin Care Products End User: Manufacturers, Wholesale Distributors, Retailers, Consumers Packaging Type: Bottles, Tubs, Pouches, Bulk Containers |
| Companies Covered | Bunge Ltd, Vink Chemicals GmbH & Co. KG, BASF SE, The Savannah Fruits Company, Ghana Nuts Company Limited, Cargill Incorporated, Sophim S.A, The Organic Shea Butter Company, AAK AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shea Olein Market Strategic Shifts
Shea olein supply chains are digitizing traceability infrastructure while fractionation technology advances enable tighter specification control for pharmaceutical and dermo-cosmetic applications.
Supercritical CO2 fractionation is unifying extraction and refining into continuous processing that preserves heat-sensitive triglyceride profiles. French dermo-cosmetic laboratories are adopting this technology at pilot scale for pharmaceutical-grade shea olein production. The process is unifying quality assurance and origin verification into single-pass documentation that satisfies both REACH and emerging carbon border requirements.
REACH Annex XVII updates are expanding restricted substance lists for cosmetic-grade vegetable lipids imported into the European Union. This regulatory tightening is disqualifying traditional solvent-extracted shea olein batches that exceed residual solvent thresholds. German and French formulators are responding by mandating supercritical or mechanical fractionation methods in supplier qualification protocols.
Beauty houses are consolidating supplier relationships around cooperatives with pre-certified organic and fair-trade credentials. Direct contracting is replacing spot-market purchasing for mass-market skin care lines in France and Germany. This consolidation is most visible among indie brands seeking published supply chain transparency for marketing differentiation against conventional emollient alternatives.
Shea Olein Market Segmentation
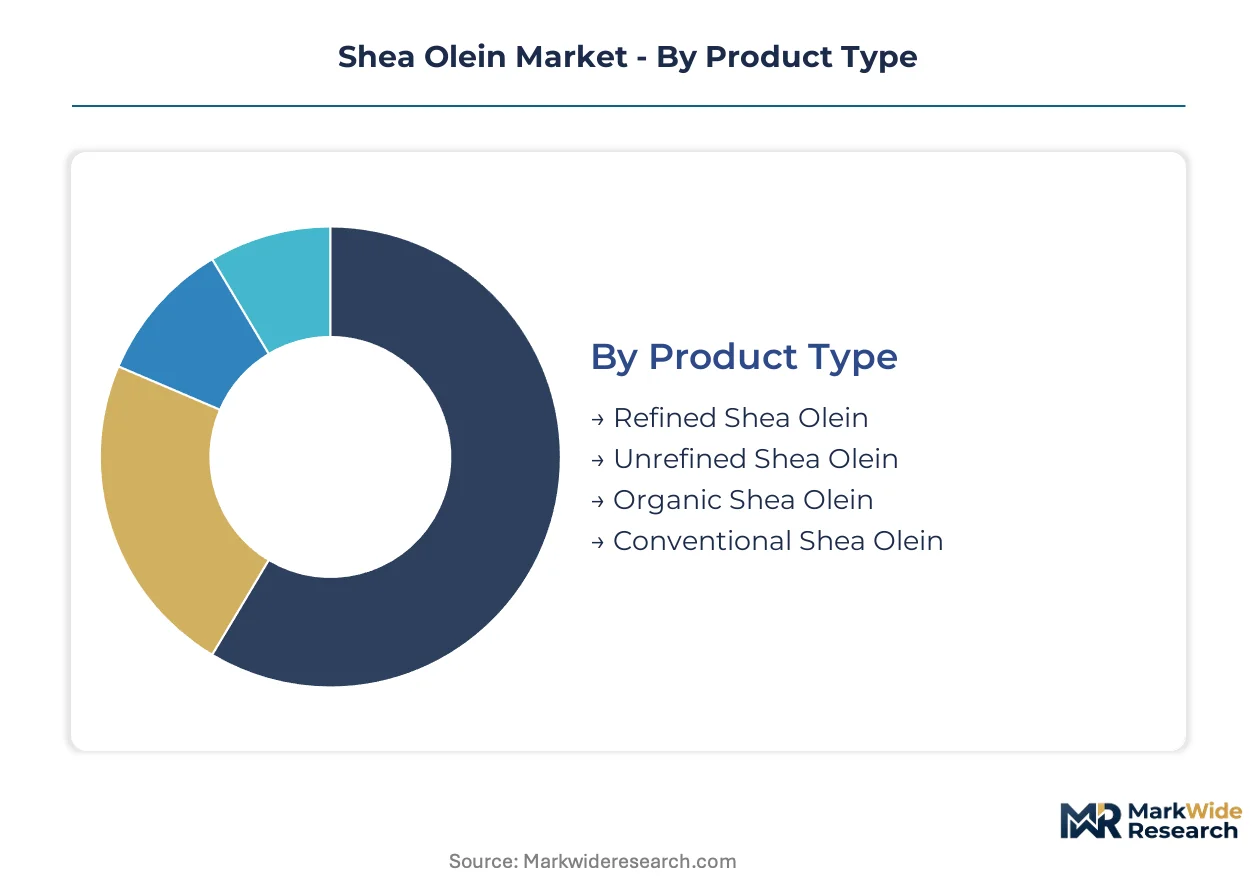
Shea olein procurement patterns diverge sharply across product grades, end-use specifications, and channel economics. Formulators in France and Germany segment purchases by functional performance, certification tier, and supply chain documentation depth.
Product Type:
Buyers in this category differentiate by odor stability, color specification, and organic certification premium rather than base functionality.
- Refined Shea Olein:Bleached and deodorized to neutral odor with iodine values below 75, meeting mass-market cosmetic color stability requirements. French formulators for pumpable body lotions specify refined grades where batch-to-batch consistency outweighs traceability premiums.
- Organic Shea Olein:Certified to EC 834/2007 standards with full cooperative origin documentation from Ghana or Burkina Faso. German clean beauty houses absorb 15-30% procurement premiums for published supply chain transparency that supports marketing claims.
- Unrefined Shea Olein:Retains characteristic nutty aroma and golden color for artisanal cosmetic positioning.
- Conventional Shea Olein:Non-certified standard grade serving cost-optimized emollient applications where REACH compliance alone satisfies requirements.
Volume sits with refined grades; growth tilts toward organic certification tiers.
Application:
Technical specifications and regulatory burden separate buyers, with pharmaceutical channels demanding GMP documentation that cosmetic formulators rarely require.
- Cosmetics:Pumpable emollient bases for mass-market personal care manufacturing. French and German houses specify low-melting-point fractions for dispensable formulations that substitute for less stable liquid lipids.
- Skin Care Products:Indie brands and dermatological labels in Italy prioritize published comedogenic safety profiles. These buyers mandate supercritical CO2 fractionation methods that preserve heat-sensitive triglyceride structures for sensitive-skin positioning.
- Food Industry:GRAS-status coatings and confectionery applications with FDA oversight for food-contact uses.
- Pharmaceuticals:CDSCO excipient standards in India and emerging dermo-cosmetic laboratory specifications in France drive pharmaceutical-grade demand.
Cosmetics commands current volume; skin care products are expanding most quickly.
End User:
Scale economics and documentation capabilities determine access to certified supply streams from West African cooperatives.
- Manufacturers:Large-scale cosmetic and personal care producers with dedicated regulatory affairs capacity. These buyers manage REACH dossier requirements and multi-jurisdiction certification sequencing for mass-market product lines.
- Wholesale Distributors:Intermediate aggregators serving smaller formulators lacking direct cooperative relationships.
- Retailers:Clean beauty specialty channels with private-label skin care programs requiring origin-verified supply.
- Consumers:Direct artisanal purchases through cooperative digital platforms, still marginal but climbing fastest.
Manufacturers retain volume dominance; cooperative-to-consumer platforms show steepest expansion trajectory.
Packaging Type:
Handling infrastructure and shelf-life requirements separate industrial buyers from specialty channel needs.
- Bulk Containers:ISO tank and drum shipments for European oleochemical refiners and large cosmetic houses. These buyers optimize logistics costs through consolidated procurement from Ghanaian and Burkinabe cooperatives.
- Bottles:Retail-ready packaging for indie brand direct distribution and dermo-cosmetic laboratory sampling programs.
- Tubs:Food-service and artisanal cosmetic positioning where scoopable consistency matters.
- Pouches:Emerging flexible format for sample programs and travel-size skin care lines.
Bulk containers carry volume concentration; bottles gain share fastest among certified clean beauty channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European formulators in France and Germany absorb the majority of premium-grade shea olein flows, while West African origin zones in Ghana and Burkina Faso anchor upstream supply concentration. Regulatory tightening through ECHA REACH compliance is reshaping procurement documentation requirements across all major demand markets.
Germany
Clean beauty houses in Hamburg and Berlin drive organic-certified shea olein procurement for pumpable emollient formulations. ECHA REACH registration mandates force requalification of supplier dossiers for residual solvent thresholds. The North Rhine-Westphalia chemical cluster hosts oleochemical refiners that fractionate multi-origin lipid streams for mass-market cosmetic manufacturing.
France
Dermo-cosmetic laboratories in Provence and the Paris Basin prioritize supercritical CO2 fractionation methods for heat-sensitive triglyceride preservation. ANSM pharmaceutical standards align with emerging CDSCO excipient requirements for cross-border supply. Sophim S.A anchors pharmaceutical-grade production capabilities serving sensitive-skin positioning channels.
Ghana
Cooperatives in the Northern Region scale traceable supply networks for direct-to-brand contracting with European personal care manufacturers. The country's national standards authority enforces export quality mandates for cosmetic-grade vegetable lipids. Tamale processing clusters invest in upgraded fractionation infrastructure to meet REACH Annex XVII purity thresholds.
Burkina Faso
Women-led cooperatives around Bobo-Dioulasso and Ouagadougou concentrate shea kernel collection for organic certification premiums. Climate-driven harvest volatility exposes supply chains to capacity constraints during low-yield seasons. Sahel-region processing facilities digitize origin documentation to satisfy EU Green Deal traceability mandates ahead of carbon border implementation.
United States
FDA GRAS determinations govern food-contact shea olein applications in confectionery and coating sectors. Indie skin care brands in California and New York reformulate around plant-derived emollients with published comedogenic safety profiles. East Coast distributors manage multi-jurisdiction certification sequencing for suppliers targeting simultaneous REACH and BIS compliance.
Shea Olein Market Competitive Environment
Capacity expansion dominates the current landscape as fractionation facilities scale to meet pharmaceutical-grade specification demand. The vendor base clusters around three archetypes: integrated oleochemical majors with multi-origin lipid platforms, West African cooperative networks with direct-sourced traceability, and pharmaceutical-grade specialists with GMP-certified fractionation capabilities. Strategic partnerships between European formulators and origin-zone cooperatives are displacing traditional commodity trader intermediation. Technology licensing for supercritical CO2 extraction is emerging as a secondary competitive vector.
Among integrated oleochemical majors, BASF SE and Bunge Ltd occupy positions exemplifying multi-jurisdiction compliance management and global supply chain orchestration. The Savannah Fruits Company anchors the cooperative-network archetype through direct-sourced shea networks spanning northern Ghana and Burkina Faso. Sophim S.A sits within the pharmaceutical-grade specialist tier, representing dermo-cosmetic laboratory channels in France and Italy.
| Leading Market Players |
|---|
| Bunge Ltd |
| Vink Chemicals GmbH & Co. KG |
| BASF SE |
| The Savannah Fruits Company |
| Ghana Nuts Company Limited |
| Cargill Incorporated |
| Sophim S.A |
| The Organic Shea Butter Company |
| AAK AB |
| Others |
Value Chain & Pricing Dynamics
Organic-to-conventional certification divergence splits the shea olein market into parallel pricing architectures that reshape how Ghanaian and Burkinabe cooperatives configure their upstream operations and how European formulators manage procurement exposure. REACH Annex XVII compliance costs embed directly into organic premiums, while palm stearin arbitrage compresses conventional grade realizations and forces origin-zone processors to absorb margin erosion or risk volume displacement.
Pricing Analysis
Volume-mass-market refined grades trade on thin margins against palm stearin substitution, while organic-certified fractions capture 15-30% procurement premiums from French and German clean beauty houses. Price differentiation rests on supercritical CO2 fractionation certification and cooperative origin documentation depth. Pricing pressure intensifies in conventional tiers as Southeast Asian palm derivatives undercut West African supply on unit cost. Mass-market formulators exhibit highest price sensitivity; dermo-cosmetic laboratories absorb premiums for pharmaceutical-grade heat-sensitive triglyceride preservation.
Supply Chain Analysis
REACH and EU Green Deal traceability mandates gate market access, forcing cooperatives to digitize origin documentation before carbon border implementation. Supply concentrates in Ghana and Burkina Faso, with over seventy percent of raw shea kernel processing anchored in northern Ghanaian clusters and Bobo-Dioulasso cooperatives. Raw material flows draw from Sahel-region harvests, mechanical pressing infrastructure, and solvent extraction capacity. Single-source vulnerability runs through climate-driven harvest volatility in West African origin zones. Distribution runs through direct-to-brand cooperative platforms displacing traditional commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration burdens and fractionation infrastructure requirements are consolidating competitive position around scale players with dedicated regulatory affairs capacity, forcing smaller West African exporters toward cooperative aggregation or exit.
For Market Incumbents: Anchor market position through backward integration into supercritical CO2 fractionation capacity in France or pharmaceutical-grade certification investments in Italian dermo-cosmetic channels. Secure long-term offtake agreements with Ghanaian and Burkinabe cooperatives before carbon border documentation requirements harden. Palm stearin substitution threat demands cost parity defense through scale economies in refined grade production. For New Entrants and Emerging Players: EU Green Deal traceability mandates in France and Germany open a window for cooperatives with pre-certified organic credentials to bypass trader intermediation and contract directly with indie skin care brands. Target pharmaceutical excipient channels in India under CDSCO standards where GMP-certified supply remains underdeveloped. Lead with digital traceability infrastructure as go-to-market differentiator against incumbent commodity flows. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade fractionation specialists given ANSM and emerging CDSCO excipient standard convergence. Long-term viability favors assets with captive cooperative relationships in Ghana and Burkina Faso and supercritical processing technology. Watch for EU carbon border adjustment implementation as inflection signal for origin-documentation-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Networks | Direct sourcing from Ghanaian and Burkinabe women's cooperatives secures traceable supply ahead of EU Green Deal mandates. |
| Supercritical CO2 Fractionation Scale-Up | Heat-sensitive triglyceride preservation meets Sophim S.A pharmaceutical-grade specifications for dermo-cosmetic laboratories. |
| REACH Annex XVII Pre-Certification | Residual solvent threshold compliance qualifies supply for ECHA-registered cosmetic formulators in Germany. |
| Direct-to-Brand Digital Platform Launch | Bypassing commodity traders captures margin premiums from French and German clean beauty houses. |
| Pharmaceutical Excipient GMP Certification | CDSCO standards alignment opens dermo-cosmetic laboratory channels in Italy and emerging Indian pharmaceutical markets. |
Study Parameters
Trade databases, ECHA registration filings, and customs export records formed the secondary backbone, cross-referenced against primary interviews with cooperative processing managers in Ghana and Burkina Faso, cosmetic formulators in France and Germany, and pharmaceutical excipient procurement leads in Italy. Bottom-up volume modeling triangulated against top-down value estimates derived from oleochemical platform disclosures and clean beauty brand supply chain transparency reports.
Bottom-up modeling built from shea kernel harvest estimates through fractionation yield assumptions to end-use consumption by grade tier, application channel, and certification level across the projection horizon. Segmentation dimensions spanned refined-organic-unrefined-conventional product grades, cosmetics-skin care-food-pharmaceutical applications, and manufacturer-distributor-retailer-consumer end users. CAGRs derived from regression against historical lipid price elasticities and substitution dynamics with palm stearin.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 fractionation scale-up in West African origin zones would alter the outlook. Forecasts reflect assumptions around REACH enforcement intensity and EU carbon border adjustment implementation scope. A model refresh is warranted upon material change in ECHA purity threshold updates or palm oil derivative pricing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Hydrogen Sulphide Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Hydrogen Silicone Fluid Market