
 Pentane Plus Market | 2026-2036
Pentane Plus Market Size, Share, and Industry Trends Forecast 2026-2036
Pentane Plus Market Outlook
South Korea's petrochemical expansion near Ulsan is reshaping regional supply dynamics for light hydrocarbon derivatives. ExxonMobil Corporation leverages integrated refinery-chemical complexes to sustain cost-advantaged pentane plus output. Shell plc anchors its position through deep feedstock flexibility across European and Asian cracking facilities. INEOS Group Holdings S.A. competes on specialty blend formulations tailored to polymerization-grade specifications.
Pentane Plus denotes a hydrocarbon fraction containing C5 alkanes—primarily n-pentane, isopentane, and cyclopentane—typically boiling between 35°C and 80°C, recovered from natural gas liquids or refinery streams and employed as solvents, blowing agents, and extraction media. Chemical Manufacturing end use dominates volume absorption due to reliance on pentane plus as polymerization diluents and reaction solvents. The Refrigeration segment registers the fastest structural expansion as hydrocarbon refrigerant formulations displace fluorinated gases under environmental protocols. Solvent applications retain mature margin pools despite slower volume growth relative to extraction agent deployment in oilfield chemistry.
EPA regulations on volatile organic compound emissions constrain product formulations in North American markets, while REACH registration requirements govern substance authorization across European chemical supply chains. China's MEE enforces national standards for air pollutants that directly limit pentane plus volatility profiles in industrial applications. South Korea's MFDS and KOSHA frameworks impose parallel workplace exposure controls that filter market access for non-compliant suppliers. Stakeholders must monitor evolving refrigerant phase-down schedules and regional carbon intensity benchmarks to align capacity investments with compliant demand corridors.
Market Dynamics
The phase-down of fluorinated refrigerants under environmental protocols is redirecting formulation chemistry toward hydrocarbon alternatives, compressing substitution timelines for pentane plus across HVAC and appliance manufacturing.
Growth Catalysts
- F-Gas Regulation phase-down schedules:The European Union's refrigerant transition mandates accelerate hydrocarbon adoption in commercial cooling systems. Appliance OEMs reformulate insulation foams to capture compliance credits.
- Polyurethane foam blowing agents:Construction and appliance sectors absorb rising pentane plus volumes as cyclopentane blends displace legacy HFC systems. East Asian foam manufacturers anchor this demand corridor.
- Shale-derived NGL abundance:North American feedstock expansion lowers raw material costs for C5 fractionation. Petrochemical operators near the US Gulf Coast expand light hydrocarbon recovery capacity.
Market Restraints
- Crude oil price volatility:Naphtha and natural gas liquids pricing directly compress margin structures for pentane plus producers. Feedstock cost pass-through lags create quarterly earnings instability.
- Flammability classification barriers:NFPA and ATEX codes restrict pentane plus handling infrastructure in populated industrial zones. Secondary containment and electrical classification requirements inflate capital deployment costs.
- Carbon dioxide substitute penetration:Supercritical CO2 extraction systems displace hydrocarbon solvents in select pharmaceutical and botanical applications. Equipment amortization cycles slow hydrocarbon reclamation.
Strategic Opportunities
- India's cold chain infrastructure buildout:The country's PLI scheme for refrigeration equipment creates virgin demand for hydrocarbon refrigerant formulations. Domestic appliance assembly lacks qualified pentane plus suppliers.
- Geothermal binary cycle plants:Isopentane working fluid demand rises as organic Rankine cycle installations expand. Iceland and Kenya project pipelines specify polymerization-grade purity specifications.
- China's dual carbon goals:Provincial emissions trading schemes reward manufacturers switching to low-GWP blowing agents. Shandong and Jiangsu foam clusters face compliance deadlines that favor local pentane plus sourcing.
Industry Challenges
- Specialized fractionation engineering:C5 isomer separation requires precision distillation expertise scarce outside established petrochemical corridors. New market entrants struggle to secure licensed process technology.
- REACH authorization timelines:European chemical registration dossiers demand multi-year toxicological studies. Smaller blenders lack resources to maintain substance portfolios under evolving data requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pentane Plus Market |
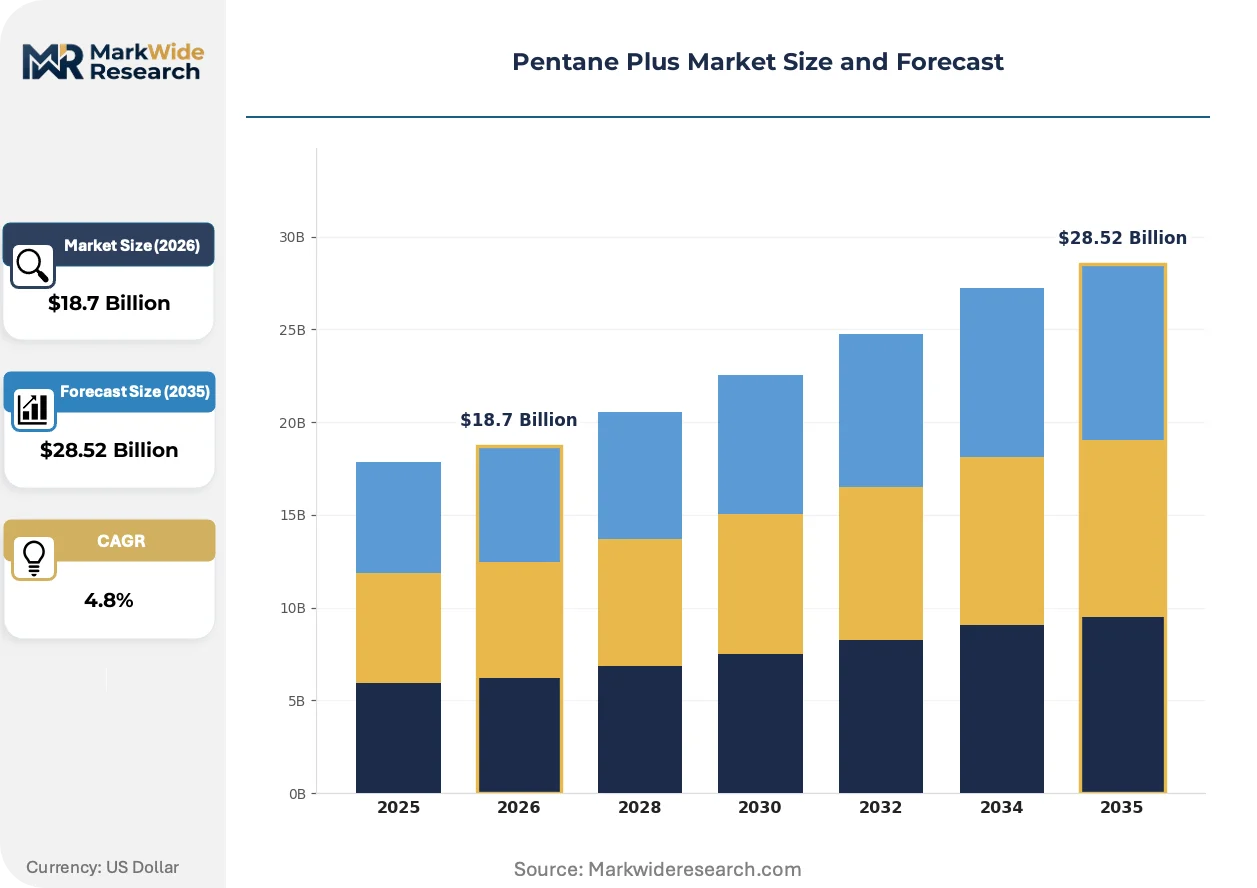
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pentane, Iso-pentane, n-pentane, Pentane Blends End Use Industry: Chemical Manufacturing, Oil & Gas, Refrigeration, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale Application: Solvent, Fuel Additive, Extraction Agent, Chemical Intermediate |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, Phillips 66 Company, TotalEnergies SE, INEOS Group Holdings S.A., SABIC, HCS Group, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pentane Plus Market Strategic Shifts
Formulation science is converging with emissions accounting, forcing product developers to optimize for carbon intensity metrics alongside traditional performance benchmarks. This recalibration permeates blowing agent selection, solvent recovery design, and refrigerant lifecycle analysis.
Advanced blend engineering is hybridizing isopentane and cyclopentane ratios to balance vapor pressure and thermal conductivity in appliance insulation. Refrigerator manufacturers in South Korea and Germany deploy these optimized formulations to meet tightening energy efficiency standards. The technology is hybridizing equipment design requirements across compressor, foam, and cabinet engineering disciplines.
EPA SNAP program amendments restrict high-GWP alternatives in commercial refrigeration, accelerating hydrocarbon transition timelines. Equipment retrofit protocols and technician certification requirements reshape service sector economics. North American supermarket chains now specify pentane-compatible systems in new construction RFPs to preempt regulatory exposure.
Buyer consolidation among appliance OEMs compresses supplier qualification cycles and unbundles technical service from material supply contracts. Procurement teams now mandate lifecycle carbon disclosures alongside unit pricing. This behavioral shift concentrates contract awards among blenders with verified Scope 3 data and regional logistics infrastructure.
Pentane Plus Market Segmentation
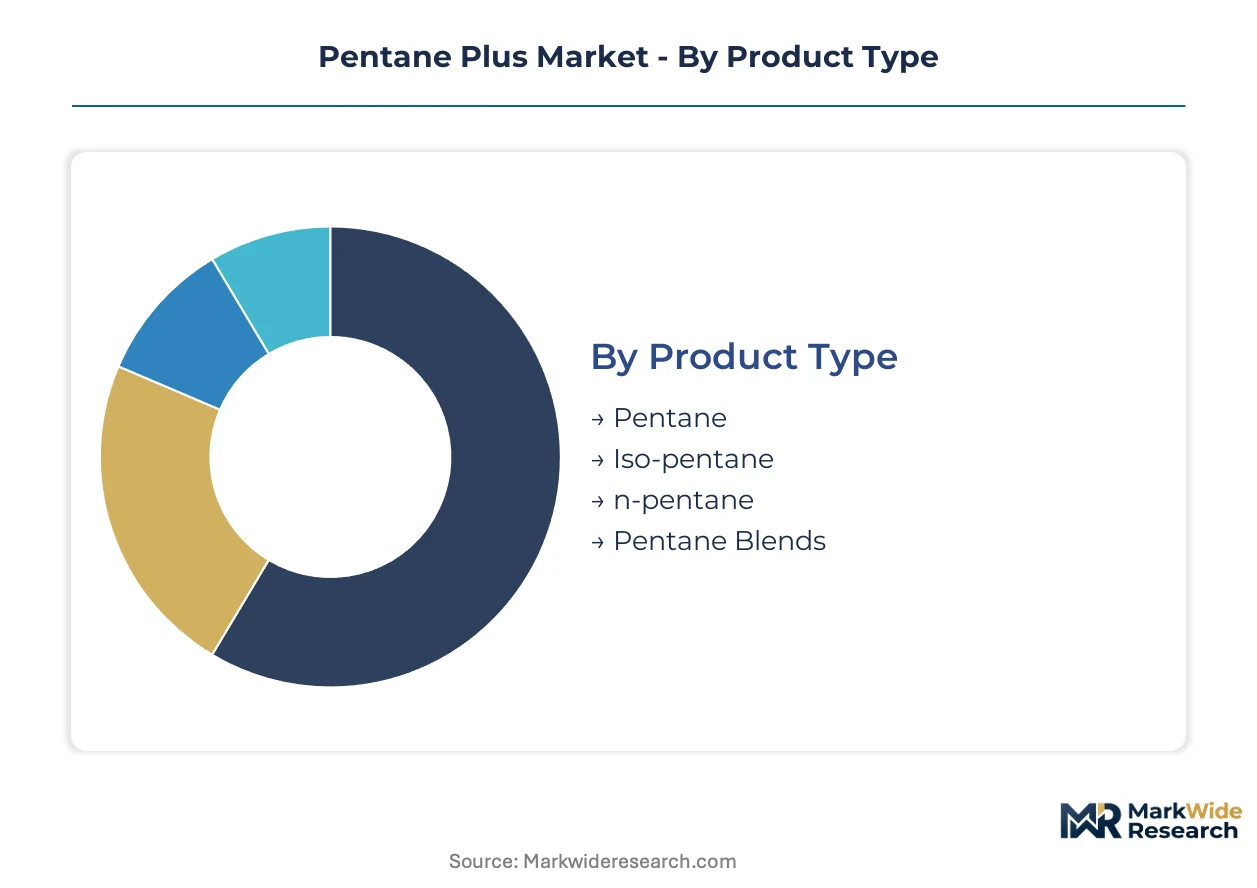
Segmentation in the Pentane Plus Market reveals how feedstock chemistry, regulatory pressure, and end-use specifications fragment demand into distinct commercial corridors. Each dimension carries unique margin structures and qualification barriers that reshape supplier positioning.
Product Type:
Product chemistry determines vapor pressure profiles and flammability classifications that gate market access across regulated jurisdictions.
- Pentane:A straight-chain C5 alkane with 36°C boiling point, prized for consistent evaporation rates in laboratory and industrial solvent applications. Polyurethane foam manufacturers in South Korea specify this grade for controlled cell structure formation in appliance insulation.
- Iso-pentane:Branched C5 isomer delivering lower boiling point and higher vapor pressure than n-pentane. Refrigeration equipment OEMs in Germany favor this profile for hydrocarbon refrigerant blends that optimize thermodynamic efficiency under EU F-Gas Regulation phase-down mandates.
- n-pentane:Linear structure provides predictable solubility parameters for polymerization diluents. Chemical manufacturers near the US Gulf Coast consume volumes for polyethylene catalyst carrier applications.
- Pentane Blends:Custom isomer ratios engineered to balance cost and performance in extraction processes. Oilfield chemistry suppliers deploy these formulations for crude oil demulsification.
Pentane commands the established base. The steepest expansion runs through Iso-pentane.
End Use Industry:
End-use concentration tracks regional industrial specialization and regulatory enforcement intensity across major economies.
- Chemical Manufacturing:Polymerization-grade pentane plus serves as reaction diluent and catalyst carrier in polyethylene and polypropylene production. ExxonMobil's integrated complexes supply this corridor with captive C5 recovery.
- Oil & Gas:Extraction agents demulsify crude and recover heavy hydrocarbons from oil sands. Canadian operators specify low-aromatic blends to meet PMRA environmental release standards.
- Refrigeration:Hydrocarbon refrigerant formulations displace R-134a and R-404A under environmental protocols. Appliance manufacturers in South Korea anchor demand for cyclopentane-isopentane blends that balance energy efficiency with flammability compliance under KOSHA workplace codes.
- Pharmaceuticals:High-purity grades function as crystallization solvents and extraction media for active pharmaceutical ingredients. FDA oversight of residual solvent limits restricts supplier qualification to GMP-certified blenders.
Chemical Manufacturing absorbs the dominant volume share. Refrigeration is expanding most quickly as regulatory deadlines compress substitution timelines.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and geographic proximity to fractionation assets.
- Direct Sales:Large-volume contracts with integrated petrochemical operators and multinational appliance OEMs. Shell plc leverages direct relationships to secure multi-year supply agreements with polyurethane foam manufacturers.
- Distributors:Regional stockists with blending and repackaging capabilities serve mid-tier chemical processors. INEOS Group Holdings S.A. maintains distributor networks across European industrial corridors.
- Online Retail:E-commerce platforms facilitate small-laboratory and research-grade purchases. Specialized chemical marketplaces handle hazardous material documentation for academic and R&D buyers.
- Wholesale:Bulk terminal operators aggregate volumes for redistribution to smaller industrial consumers. US Gulf Coast terminals channel shale-derived NGL fractions to downstream blenders.
Direct Sales captures the premium contract base. Distributors are gaining share fastest as mid-market buyers seek technical support bundled with supply security.
Application:
Application segmentation maps functional chemistry to performance specifications and substitution economics.
- Solvent:Dissolution and cleaning applications in coatings, adhesives, and electronics manufacturing. China's GB standards for volatile organic compound emissions constrain product formulations in industrial zones.
- Fuel Additive:Octane enhancement and volatility adjustment in gasoline blending. Refinery operators near Ulsan integrate pentane plus into finished fuel specifications.
- Extraction Agent:Botanical and pharmaceutical processing where supercritical CO2 systems prove capital-intensive. Equipment amortization cycles slow hydrocarbon displacement in specialty chemical production.
- Chemical Intermediate:Feedstock for isoprene, synthetic rubber, and specialty chemical synthesis. Polymerization-grade specifications demand tight impurity controls that filter supplier participation.
Solvent applications retain the mature revenue base. Extraction Agent deployment is climbing the fastest as pharmaceutical and botanical processors seek alternatives to fluorinated solvents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE enforces national standards for air pollutants that directly limit pentane plus volatility profiles across industrial zones. Regional pentane plus demand clusters around three distinct regulatory environments and feedstock corridors.
China
Shandong and Jiangsu foam clusters face compliance deadlines that favor local pentane plus sourcing. China's dual carbon goals reward manufacturers switching to low-GWP blowing agents through provincial emissions trading schemes. The Yangtze River Delta hosts polyurethane foam manufacturers absorbing rising volumes as cyclopentane blends displace legacy HFC systems.
South Korea
Appliance OEMs in the Seoul Capital Area anchor demand for cyclopentane-isopentane blends that balance energy efficiency with flammability compliance. KOSHA workplace codes filter market access for non-compliant suppliers. The Busan-Ulsan petrochemical corridor near Ulsan concentrates production gravity for light hydrocarbon derivatives.
United States
Petrochemical operators near the US Gulf Coast expand light hydrocarbon recovery capacity from shale-derived NGL abundance. EPA SNAP program amendments restrict high-GWP alternatives in commercial refrigeration, accelerating hydrocarbon transition timelines. North American supermarket chains now specify pentane-compatible systems in new construction RFPs.
Germany
Refrigeration equipment OEMs favor isopentane profiles for hydrocarbon refrigerant blends that optimize thermodynamic efficiency. The EU F-Gas Regulation phase-down mandates accelerate hydrocarbon adoption in commercial cooling systems. Industrial corridors in North Rhine-Westphalia host appliance manufacturers deploying optimized formulations to meet tightening energy efficiency standards.
India
The country's PLI scheme for refrigeration equipment creates virgin demand for hydrocarbon refrigerant formulations. Domestic appliance assembly lacks qualified pentane plus suppliers. Maharashtra and Gujarat industrial zones present entry points for distributors with blending and repackaging capabilities.
Pentane Plus Market Competitive Environment
Integrated energy majors and specialty chemical groups split the market between feedstock-advantaged volume players and formulation-focused blenders. The vendor base concentrates around refinery-chemical complexes with captive C5 recovery capabilities. Three archetypes dominate: integrated oil companies with backward control over NGL supply, European petrochemical specialists with deep feedstock flexibility, and Asian chemical conglomerates serving regional foam clusters. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants secure multi-year supply agreements with appliance OEMs.
Among integrated oil companies, ExxonMobil Corporation and Shell plc exemplify the feedstock-anchored archetype with positions across North American and European cracking facilities. INEOS Group Holdings S.A. occupies a position within the specialty formulation tier, serving mid-tier chemical processors through distributor networks across European industrial corridors. These three companies represent distinct strategic postures: scale-driven upstream integration, geographic diversification across cracking assets, and technical service bundling for qualified blend specifications.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| Phillips 66 Company |
| TotalEnergies SE |
| INEOS Group Holdings S.A. |
| SABIC |
| HCS Group |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Feedstock cost volatility in North American shale corridors and Middle Eastern NGL exports determines both the spread between polymerization-grade and solvent-grade pricing tiers and the geographic shape of pentane plus supply networks. Buyers in East Asian foam clusters face wider price bands when US Gulf Coast fractionation capacity tightens, forcing procurement teams to balance long-term offtake contracts against spot market exposure.
Pricing Analysis
Price spreads between the US Gulf Coast and South Korea's Ulsan corridor widen during peak construction seasons when polyurethane foam manufacturers accelerate inventory builds. Three-tier pricing structure across polymerization-grade, technical-grade, and solvent-grade levels reflects purity specifications and vapor pressure tolerances. Cost compression in technical-grade blends is intensifying because Chinese domestic fractionators are expanding C5 recovery capacity. Appliance OEMs with multi-year supply agreements show the least price sensitivity, while spot buyers in Indian solvent applications absorb the highest volatility.
Supply Chain Analysis
Contract fractionation at ExxonMobil's Baytown complex, Shell's Moerdijk facility, and SABIC's Jubail operations holds the majority of merchant pentane plus capacity. Supply concentrates in the United States, Saudi Arabia, and South Korea, with secondary blending nodes in Germany and Singapore. Feedstock draws from shale-derived natural gas liquids, refinery catalytic reformer streams, and gas plant condensate recovery. Single-source vulnerability runs through the Strait of Hormuz for Middle Eastern naphtha-derived C5 feeds. Distribution runs through direct pipeline connections to integrated chemical complexes, supplemented by refrigerated barge and ISO tank movements for spot volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phase-down and parallel EPA SNAP restrictions on high-GWP refrigerants are compressing substitution timelines, positioning hydrocarbon blowing agents as a high-growth disruption vector with structural tailwinds across appliance manufacturing and commercial cooling infrastructure.
For Market Incumbents: Harden feedstock security through backward integration into NGL gathering systems or long-term supply agreements with shale basin operators. Expand fractionation capacity in the US Gulf Coast to capture cost advantages as export demand from East Asian foam clusters climbs. Defend against specialty blenders by embedding technical service teams within appliance OEM engineering departments. For New Entrants and Emerging Players: Build out blending and repackaging capabilities in Maharashtra and Gujarat industrial zones to serve India's PLI-driven refrigeration equipment buildout. Target virgin demand corridors where domestic appliance assembly lacks qualified pentane plus suppliers. Lead with KOSHA-compliant formulation expertise and localized logistics infrastructure rather than competing on feedstock scale. For Investors and Strategic Acquirers: Regional blenders with verified Scope 3 carbon disclosures and established distributor relationships in European industrial corridors represent the most defensible acquisition archetype. Long-term viability hinges on positioning for refrigerant transition economics and low-GWP blowing agent compliance deadlines. Watch for inflection signals in provincial emissions trading scheme participation rates across Shandong and Jiangsu foam clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | US Gulf Coast fractionators capture shale NGL abundance to serve East Asian foam demand. |
| Backward Integration | Upstream control over NGL gathering systems locks in feedstock cost advantages for integrated operators. |
| Long-term Supply Agreement | Multi-year contracts with South Korean appliance OEMs secure volume commitments through refrigerant transition. |
| Green Manufacturing Transition | Low-GWP blowing agent certification opens procurement channels under EU F-Gas Regulation compliance. |
| Joint Venture | Partnerships with Indian distributors address PLI scheme refrigeration demand in Maharashtra industrial zones. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at fractionation facilities, procurement leads at polyurethane foam manufacturers, distribution channel partners in European industrial corridors, and technical R&D directors at specialty blenders, and refined through secondary validation against customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K disclosures from integrated energy majors, and EPA SNAP program regulatory filings. Bottom-up volume estimates by end-use application were triangulated against top-down feedstock availability models.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product grade tier, end-use industry concentration, regional production hub proximity, and refrigerant regulatory compliance cluster. CAGRs were derived from slope analysis of normalized adoption curves within each segment, calibrated against historical substitution patterns in blowing agent transitions and hydrocarbon refrigerant deployment rates in commercial cooling systems.
Stress conditions across crude oil price volatility bands, EU F-Gas Regulation enforcement intensity, and Chinese dual carbon goal implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding refrigerant phase-down schedules and regional carbon intensity benchmark evolution. Quarterly review of provincial emissions trading scheme participation rates, appliance OEM hydrocarbon system specification rates, and US Gulf Coast NGL fractionation utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Ethyl Acrylate Market