
 Global Itaconic Acid Market | 2026-2036
Global Itaconic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Itaconic Acid Market Foresight
Chinese fermentation capacity is shifting toward dedicated itaconic acid streams as domestic producers scale biosynthetic output. Zhejiang Guoguang Biochemistry leverages integrated glucose-to-itaconate fermentation infrastructure across eastern China. Qingdao Kehai Biochemistry anchors coastal supply chains through specialized biochemical export terminals. Iwata Chemical dominates high-purity refining protocols for Asian pharmaceutical and polymer customers.
Itaconic acid is an unsaturated dicarboxylic acid produced primarily via submerged fermentation of Aspergillus terreus on carbohydrate substrates, yielding a white crystalline solid with melting point near 165°C that serves as a platform chemical for unsaturated polyester resins, superabsorbent polymers, and bio-based acrylic acid substitutes. Polymer grade material commands the deepest margin pools due to stringent purity thresholds in unsaturated polyester manufacturing, while bioplastic grade volumes are accelerating fastest as brand owners reformulate packaging around certified compostable feedstocks. Synthetic resins and coatings applications occupy mature demand positions with stable offtake from construction and automotive OEMs.
REACH registration requirements in Europe, FDA food contact substance notifications in the United States, and China's GB standards for industrial biochemical purity collectively elevate compliance costs for cross-border suppliers while filtering sub-scale producers from premium segments. ECHA's evolving classification of bio-based platform chemicals under CLP regulation is tightening hazard communication protocols for downstream formulators. Stakeholders must monitor fermentation yield breakthroughs and regulatory reciprocity agreements between major import jurisdictions to secure long-term supply positions.
Market Dynamics
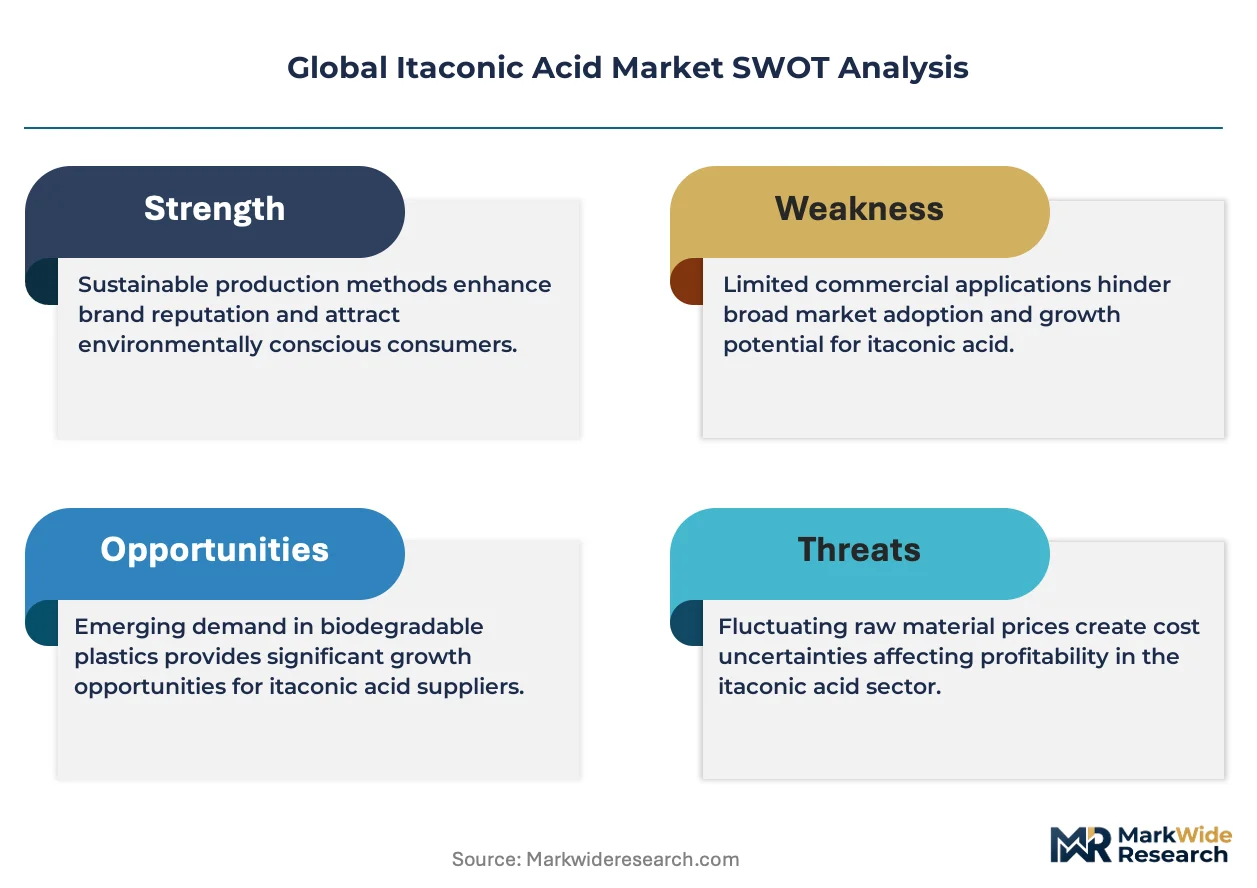
Fermentation yield breakthroughs are compressing unit economics while EU Green Deal bio-based material mandates redirect polymer-grade offtake toward certified compostable supply chains. This dual pressure is restructuring competitive positioning between established Asian producers and emerging European biorefinery operators.
Growth Catalysts
- EU Green Deal bio-based mandates:Packaging brand owners across Germany, France, and the Netherlands face binding recycled and renewable content thresholds that accelerate polymer-grade itaconate absorption into unsaturated polyester formulations.
- Cellulosic feedstock diversification:Second-generation fermentation substrates from agricultural residues are reducing glucose dependency and expanding viable production geographies beyond traditional corn belt concentrations.
- Shandong-Zhejiang capacity clustering:Chinese producers concentrate capital deployment in coastal provinces with integrated glucose supply, specialized export terminals, and established biochemical logistics infrastructure.
Market Restraints
- Glucose price volatility:Fermentation economics remain tethered to corn and wheat starch markets, with input cost swings compressing margin visibility for non-integrated operators.
- REACH registration burden:ECHA compliance costs for bio-based platform chemicals under CLP regulation filter sub-scale European entrants from premium polymer and pharmaceutical segments.
- Petrochemical acrylic acid substitution:Fossil-derived acrylic acid retains cost advantages in coating and adhesive applications where bio-based certification carries no price premium.
Strategic Opportunities
- India PLI scheme for bioplastics:Production-linked incentives for bio-based material manufacturing create first-mover advantages for fermentation capacity establishing before domestic supply matures.
- Superabsorbent polymer grade expansion:Personal care and hygiene manufacturers seek non-petroleum diaper and sanitary product inputs, opening volume absorption at purity thresholds below pharmaceutical specifications.
- CRSD supply chain disclosure requirements:EU corporate sustainability reporting mandates force brand owners to document bio-based feedstock provenance, rewarding transparent fermentation operators with preferred supplier status.
Industry Challenges
- Fermentation strain optimization expertise:Aspergillus terreus yield engineering requires specialized microbial physiology talent scarce outside established Chinese and Japanese research clusters.
- Multi-jurisdiction certification timelines:Simultaneous FDA food contact substance notifications, REACH dossier preparation, and GB standard compliance extend product launch cycles by 18-24 months.
- Legacy petrochemical customer integration:Unsaturated polyester resin formulators maintain entrenched acrylic acid supply contracts and require extensive reformulation validation before accepting itaconate substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Itaconic Acid Market |
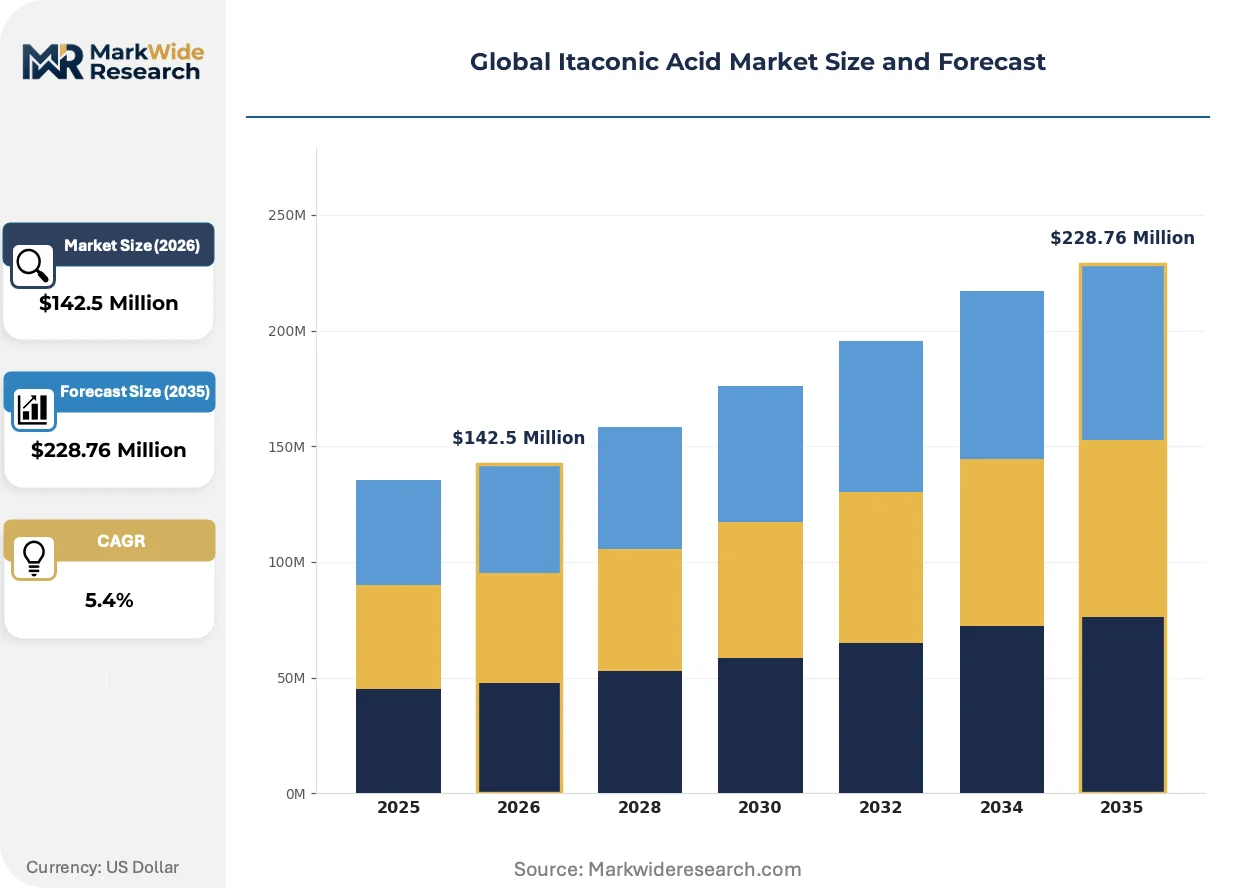
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Grade, Pharmaceutical Grade, Food Grade, Industrial Grade, Bioplastic Grade Application: Adhesives, Coatings, Plasticizers, Synthetic Resins, Surfactants, Detergents End User Industry: Textile Manufacturing, Paint & Coating Producers, Biotech Firms, Construction Material Suppliers, Cosmetic Manufacturers Form: Powder, Granular, Liquid Concentrate, Solution, Crystalline |
| Companies Covered | Itaconix Corporation, Zhejiang Guoguang Biochemistry Co., Ltd., Qingdao Kehai Biochemistry Co., Ltd., Alpha Chemika, Jinan Huaming Biochemistry Co., Ltd., Shandong Kaison Biochemical Co., Ltd., Qingdao Langyatai Group Co., Ltd., Iwata Chemical Co., Ltd., Aekyung Petrochemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Itaconic Acid Market Shifts & Advancements
Continuous fermentation systems and metabolic engineering advances are collapsing the cost gap between bio-based and petrochemical platform chemicals. These developments are redirecting capital toward integrated biorefinery configurations that capture value across multiple product streams.
CRISPR-edited Aspergillus terreus strains with enhanced itaconate export pumps are rewriting yield benchmarks for submerged fermentation processes. Specialty polymer manufacturers in Japan and Germany are adopting these biocatalysts at pilot scale. The technology is compressing the capital intensity required to achieve pharmaceutical-grade purity thresholds.
REACH registration requirements for bio-based platform chemicals under evolving CLP classification protocols are tightening hazard communication obligations for downstream formulators. ECHA's expanding dossier demands elevate compliance costs disproportionately for small-volume importers. Polymer-grade suppliers with established European legal entities are capturing share from cross-border traders lacking in-house regulatory affairs capacity.
Brand-owner procurement teams are unbundling long-term offtake agreements into shorter certification-linked contracts that tie pricing to verified bio-based content percentages. Personal care and packaging verticals in France and the Netherlands lead this transition. The shift rewards fermentation operators with blockchain-traceable supply chains and third-party sustainability certifications.
Global Itaconic Acid Market Segmentation
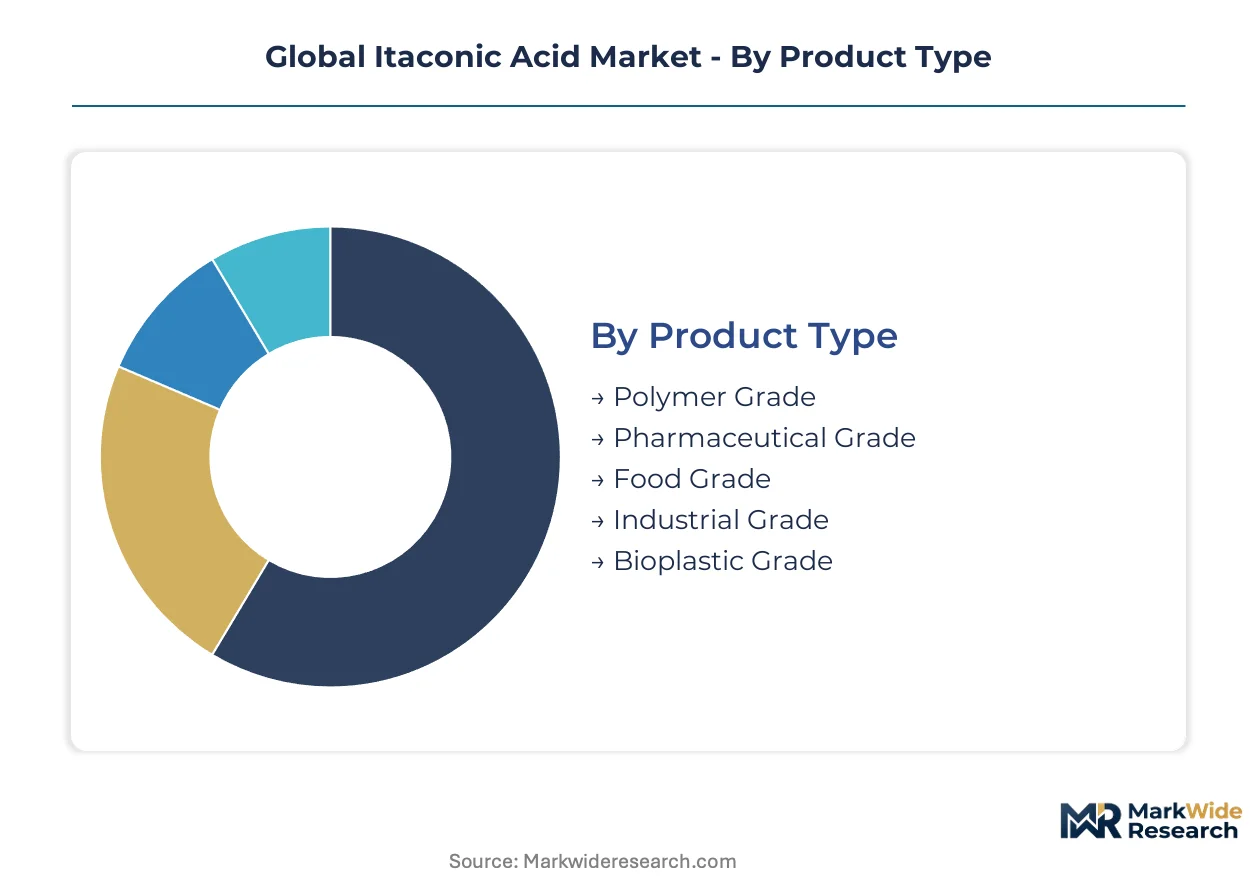
Itaconic acid segmentation reflects divergent purity thresholds and certification requirements across downstream value chains. Grade differentiation determines pricing bandwidths and regulatory compliance burdens for fermentation operators.
Product Type:
Upgrade cycles in unsaturated polyester manufacturing are driving specification tightening across polymer-grade supply tiers.
- Polymer Grade:Stringent purity protocols above 99.5% enable substitution for petrochemical acrylic acid in unsaturated polyester resin formulations. German automotive OEMs and Dutch packaging converters absorb the deepest volume pools under EU Green Deal bio-based mandates.
- Bioplastic Grade:Certified compostable feedstock specifications serve brand-owner reformulation targets for single-use packaging. French and Dutch procurement teams tie contract pricing to verified bio-based content percentages through blockchain-traceable supply chains.
- Pharmaceutical Grade:Meets USP and EP monograph standards for excipient applications.
- Food Grade:Complies with FDA food contact substance notifications and EFSA purity requirements.
- Industrial Grade:Standard technical specifications for non-critical chemical synthesis applications.
Volume placements concentrate in Polymer Grade; the faster expansion belongs to Bioplastic Grade.
Application:
Cost tier differentiation separates commodity coating additives from specialty surfactant formulations requiring extended regulatory dossiers.
- Synthetic Resins:Unsaturated polyester manufacturers in Japan and Germany leverage itaconate crosslinking density for marine and automotive composite applications. Legacy petrochemical supply contracts slow reformulation validation cycles.
- Coatings:Waterborne acrylic systems incorporate itaconic acid for adhesion promotion and corrosion resistance. Construction sector demand from German and Chinese infrastructure projects maintains stable offtake.
- Adhesives:Pressure-sensitive and structural bonding applications.
- Plasticizers:Bio-based alternatives to phthalate esters in flexible PVC.
- Surfactants:Anionic and non-ionic formulations for industrial cleaning.
- Detergents:Chelating and dispersant functions in household products.
Application volumes cluster in Synthetic Resins; Coatings are climbing the fastest on construction sector absorption.
End User Industry:
Customer type fragmentation spans mature industrial sectors and emerging biotech applications with divergent procurement sophistication.
- Paint & Coating Producers:Formulation houses in Germany and Japan integrate polymer-grade itaconate for high-performance automotive and marine finishes. REACH registration reciprocity with Asian suppliers compresses qualification timelines.
- Biotech Firms:Fermentation-derived platform chemical offtake supports pharmaceutical intermediate and biocatalytic process development. Japanese and German research clusters absorb pilot-scale volumes.
- Textile Manufacturing:Fiber treatment and dye fixation applications.
- Construction Material Suppliers:Concrete admixtures and waterproofing compounds.
- Cosmetic Manufacturers:pH adjustment and chelation in personal care formulations.
Industry placements concentrate in Paint & Coating Producers; Biotech Firms show the steepest expansion trajectory.
Form:
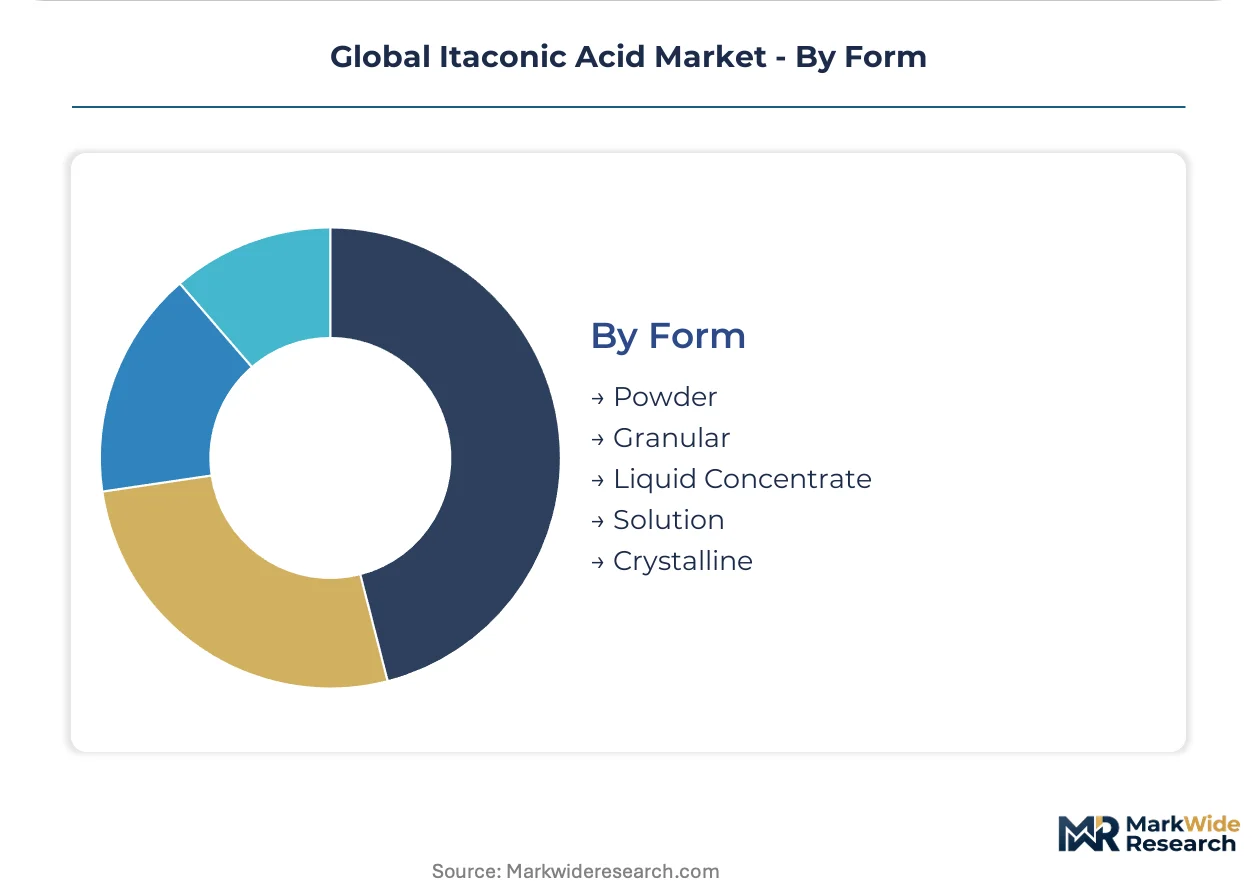
Supply chain configuration favors dry forms for long-haul logistics and liquid concentrates for integrated coastal biorefineries.
- Crystalline:High-purity solid form with defined melting point near 165°C serves pharmaceutical and polymer customers requiring precise dosing control. Japanese refiners dominate purification protocols.
- Powder:Milled crystalline material for rapid dissolution in aqueous systems.
- Granular:Free-flowing particles for bulk handling in resin manufacturing.
- Liquid Concentrate:Fermentation broth refinement reduces downstream processing energy.
- Solution:Pre-dissolved aqueous formulations for immediate process integration.
Form volumes concentrate in Crystalline; Liquid Concentrate is gaining share fastest at coastal fermentation clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn belt glucose supplies anchor fermentation economics across multiple continents. Coastal biochemical clusters in China and Europe concentrate downstream refining capacity. Regulatory divergence between ECHA, FDA, and China's GB standards fragments compliance pathways.
China
Shandong and Zhejiang provinces absorb the deepest capacity investments as domestic producers scale dedicated itaconate fermentation streams. MIIT's dual carbon goals accelerate biosynthetic platform chemical subsidies while tightening industrial emissions standards. Qingdao's specialized biochemical export terminals anchor coastal supply chains serving polymer customers in Japan and Germany.
Germany
Automotive OEMs and packaging converters in Bavaria and North Rhine-Westphalia drive polymer-grade absorption under binding EU Green Deal bio-based content mandates. ECHA's evolving CLP classification protocols tighten hazard communication obligations for downstream formulators. Frankfurt-Rhine-Main logistics corridors integrate fermentation-derived feedstocks into unsaturated polyester manufacturing.
United States
Construction sector demand from Texas and California infrastructure projects stabilizes coatings-grade offtake. FDA food contact substance notification requirements extend product launch cycles for imported fermentation material. Gulf Coast petrochemical corridors resist itaconate substitution where fossil-derived acrylic acid retains cost advantages.
Japan
Pharmaceutical-grade refining protocols concentrate around METI-supported research clusters in Kanto and Kansai regions. PMDA monograph alignment with USP and EP standards enables cross-border excipient supply. Iwata Chemical anchors high-purity output for Asian polymer and pharmaceutical customers.
India
Maharashtra and Gujarat fermentation operators exploit PLI scheme incentives for bioplastics manufacturing before domestic supply matures. BIS industrial biochemical purity standards elevate compliance costs for cross-border traders. Mumbai-Pune industrial corridors attract pilot-scale capacity targeting personal care and hygiene superabsorbent polymer applications.
Global Itaconic Acid Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and integrated biorefinery configurations. The market structures around three maturity tiers: coastal Chinese fermentation specialists with captive glucose supply, Japanese refiners dominating high-purity protocols, and European operators leveraging regulatory proximity to ECHA. Strategic archetypes include yield-engineering biocatalyst developers, blockchain-traceable supply chain operators, and backward-integrated glucose-to-itaconate platforms. Competitive moves concentrate on metabolic engineering licensing partnerships and shorter certification-linked offtake contracts.
Within the coastal Chinese tier, Zhejiang Guoguang Biochemistry Co., Ltd. and Qingdao Kehai Biochemistry Co., Ltd. exemplify integrated fermentation infrastructure with specialized export terminal access. Iwata Chemical Co., Ltd. occupies a position representing high-purity refining expertise for pharmaceutical and polymer segments. These three anchors illustrate the geographic and technical stratification shaping procurement decisions: Chinese operators capture volume through scale, while Japanese specialists command premium positioning through purity protocols.
| Leading Market Players |
|---|
| Itaconix Corporation |
| Zhejiang Guoguang Biochemistry Co., Ltd. |
| Qingdao Kehai Biochemistry Co., Ltd. |
| Alpha Chemika |
| Jinan Huaming Biochemistry Co., Ltd. |
| Shandong Kaison Biochemical Co., Ltd. |
| Qingdao Langyatai Group Co., Ltd. |
| Iwata Chemical Co., Ltd. |
| Aekyung Petrochemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Glucose feedstock costs cascade through fermentation economics into three distinct pricing tiers for polymer-grade, bioplastic-grade, and pharmaceutical-grade itaconic acid. Zhejiang and Shandong producers leverage captive corn starch supply to compress standard-tier quotations, while Japanese refiners command premium positioning through USP-certified purification protocols. ECHA registration reciprocity with Asian suppliers compresses European qualification timelines, altering price sensitivity across buyer archetypes.
Pricing Analysis
Warranty and certification bundling separate contract structures in this market, with polymer-grade supply typically including REACH dossier support while pharmaceutical-grade transactions unbundle regulatory filing costs. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds and certification depth, with German automotive OEMs least sensitive and Asian trading houses most price-responsive. Cost compression in standard-tier material is intensifying because Shandong capacity additions outpace specialty-grade fermentation yield improvements. Margins are tightening due to glucose price volatility tethered to corn futures.
Supply Chain Analysis
Dual-sourcing mandates from German and Dutch packaging converters require qualification of at least one Asian and one European fermentation operator, fragmenting procurement concentration. Supply concentrates in China, Japan, and Germany, with coastal Chinese clusters feeding glucose-to-itaconate platforms and Japanese refiners anchoring high-purity output. Corn starch and wheat glucose feed fermentation reactors, while specialized biochemical export terminals and refrigerated container fleets complete downstream logistics. Single-source vulnerability persists in pharmaceutical-grade refining expertise concentrated around Iwata Chemical and select Japanese research clusters. Distribution runs through integrated coastal biorefineries with captive export infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation strain optimization expertise functions as the binding capacity constraint, propping polymer-grade pricing as EU Green Deal mandates accelerate offtake ahead of yield-engineering talent availability.
For Market Incumbents: Extend metabolic engineering licensing partnerships to secure CRISPR-edited Aspergillus terreus strain access before academic spin-outs commercialize competing biocatalysts. Deepen backward integration into cellulosic feedstock preprocessing to dilute glucose cost exposure. Anchor capacity expansion in Zhejiang corridor terminals with established biochemical logistics infrastructure. For New Entrants and Emerging Players: Personal care superabsorbent polymer manufacturers represent an underserved buyer archetype seeking non-petroleum inputs at purity thresholds below pharmaceutical specifications. Indian PLI scheme incentives for bioplastics manufacturing create first-mover positioning ahead of domestic supply maturation. Pursue blockchain-traceable supply chain certification to capture French and Dutch procurement teams tying contract pricing to verified bio-based content percentages. For Investors and Strategic Acquirers: CRISPR-edited strain pilot-scale adoption by Japanese and German specialty polymer manufacturers is the leading indicator that yield-engineering biocatalyst developers will command acquisition premiums. Five-to-ten year viability hinges on regulatory reciprocity agreements between ECHA, FDA, and China's GB standards reducing multi-jurisdiction certification timelines. Target fermentation operators with integrated glucose supply and established European legal entities. Watch for REACH registration reciprocity announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulosic Feedstock | Reduces glucose dependency and expands viable production geographies beyond traditional corn belt concentrations. |
| CRISPR Strain Licensing Partnership | Compresses capital intensity required to achieve pharmaceutical-grade purity thresholds for Japanese refiners. |
| Blockchain-Traceable Supply Chain Certification | Captures preferred supplier status under EU CSRD supply chain disclosure requirements for Dutch converters. |
| European Legal Entity Establishment | Enables direct REACH registration and captures share from cross-border traders lacking regulatory affairs capacity. |
| Coastal Biorefinery Terminal Investment | Integrates fermentation output with specialized biochemical export infrastructure at Qingdao and Zhejiang clusters. |
Research Methodology
Multi-period observation of fermentation capacity additions, glucose price volatility, and EU Green Deal mandate implementation timelines anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Zhejiang fermentation facilities, procurement leads at German automotive OEMs, distribution channel partners in biochemical logistics, and technical R&D directors specializing in Aspergillus terreus strain engineering. Secondary validation drew from customs and trade data, MIIT biosynthetic platform chemical subsidy disclosures, ECHA registration databases, and SEC filings of publicly traded bioplastics manufacturers. Bottom-up fermentation capacity modeling and top-down polymer-grade demand projection triangulated volume estimates.
Input-output matrices mapped glucose feedstock availability through fermentation yield assumptions to grade-specific output volumes across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, regional production hub clustering, and certification depth. CAGRs derived from weighted average of historical capacity deployment rates and mandate-driven demand elasticity coefficients. Industry-specific forecast inputs incorporated MIIT dual carbon goal implementation pace and ECHA CLP classification protocol evolution.
Revisions become necessary when glucose price volatility exceeds historical bands, fermentation yield breakthroughs collapse unit economics faster than modeled, or regulatory reciprocity agreements between major import jurisdictions fail to materialize. Deviation in EU Green Deal bio-based content mandate enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Global Activated Carbon Canisters Market