
 Paraffin Inhibitors Market | 2026-2036
Paraffin Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Paraffin Inhibitors Market Intelligence
Performance-based chemical management contracts is expanding as the dominant service layer in paraffin control, shifting risk from operators to suppliers. ChampionX leverages its integrated production chemistry platform to anchor long-term offshore contracts. SLB sustains technology leadership through real-time wax deposition monitoring systems. BASF SE competes on polymer backbone innovation for cold-flow improvement in high-wax crudes.
Paraffin inhibitors are specialty chemicals designed to disrupt wax crystal nucleation and growth in hydrocarbon streams, typically comprising polymeric dispersants or surfactant blends that modify crystal morphology to maintain fluidity at reduced temperatures. Their primary commercial purpose centers on preventing pipeline blockages and production losses in crude oil extraction and transport systems. Crystal inhibitors occupy the largest margin pool due to formulation complexity and patent-protected polymer architectures, while multi-functional inhibitors represent the fastest-growing category as operators seek to consolidate chemical injection programs. Onshore applications remain the mature volume base, though offshore applications command premium pricing driven by logistics constraints and subsea delivery requirements.
The EPA regulates paraffin inhibitor discharge under offshore NPDES permits, while the EU ECHA enforces REACH registration for polymer components with marine toxicity profiles, collectively elevating biodegradable formulation requirements. OSHA process safety standards govern onshore chemical handling and storage infrastructure. Stakeholders must monitor evolving subsea chemical discharge thresholds and assess backward integration into bio-based polymer feedstocks to preempt regulatory displacement of conventional chemistries.
Market Dynamics
Deepwater pre-salt production economics are compressing chemical injection budgets while demanding higher-performance wax control, forcing formulation suppliers to absorb technical risk through performance-based contracting structures.
Growth Catalysts
- Pre-salt crude expansion:Brazilian deepwater fields exhibit wax content exceeding conventional grades, necessitating continuous inhibitor injection at subsea wellheads. Petrobras-led development in the Santos Basin anchors volume demand for crystal inhibitor chemistries.
- REACH marine toxicity standards:The EU ECHA framework on polymer biodegradability is accelerating reformulation investments toward bio-based dispersant backbones. Suppliers registering compliant architectures gain preferential positioning in North Sea offshore tenders.
- Real-time monitoring integration:Downhole wax deposition sensors are enabling predictive chemical dosing, reducing over-injection waste. Gulf of Mexico operators are deploying these systems on high-pressure high-temperature completions.
Market Restraints
- Ethylene feedstock volatility:Polymer backbone production depends on ethylene oxide and alpha-olefin availability, with pricing tied to naphtha cracking economics. Margin compression during feedstock spikes limits R&D reinvestment capacity.
- Specialty chemical supply concentration:Three merchant suppliers control the majority of high-molecular-weight polymeric dispersant manufacturing. Geographic concentration in the US Gulf Coast exposes buyers to hurricane-related supply interruptions.
- Subsea delivery logistics:Offshore inhibitor deployment requires dedicated umbilical infrastructure and subsea storage units. Capital intensity of subsea chemical systems restricts adoption to megaproject developments.
Strategic Opportunities
- West African deepwater basins:Pre-salt analogs offshore Angola and Nigeria remain underpenetrated for advanced paraffin control. Local content requirements favor joint-venture structures with established international suppliers.
- Multi-functional inhibitor consolidation:Operators are seeking single-chemical solutions combining wax control with corrosion inhibition and hydrate suppression. Formulation platforms integrating three or more functions command premium positioning.
- EPA biodegradable discharge pathways:The agency's evolving subsea chemical guidelines create first-mover advantage for suppliers with validated biodegradation data. Early registrants secure long-term platform offtake agreements.
Industry Challenges
- Subsea chemist skill scarcity:Formulation optimization for high-pressure high-temperature conditions requires specialized expertise in polymer-solvent compatibility. Major operators are competing for limited talent pools in Aberdeen and Houston.
- REACH registration timeline compression:Polymer component dossiers for marine toxicity assessment require 18-24 month preparation cycles. Accelerated regulatory deadlines risk supply discontinuities for non-compliant chemistries.
- Legacy infrastructure incompatibility:Existing onshore tankage and injection skids often lack temperature control for next-generation low-pour-point formulations. Retrofit costs burden adoption of advanced crystal modifier systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraffin Inhibitors Market |
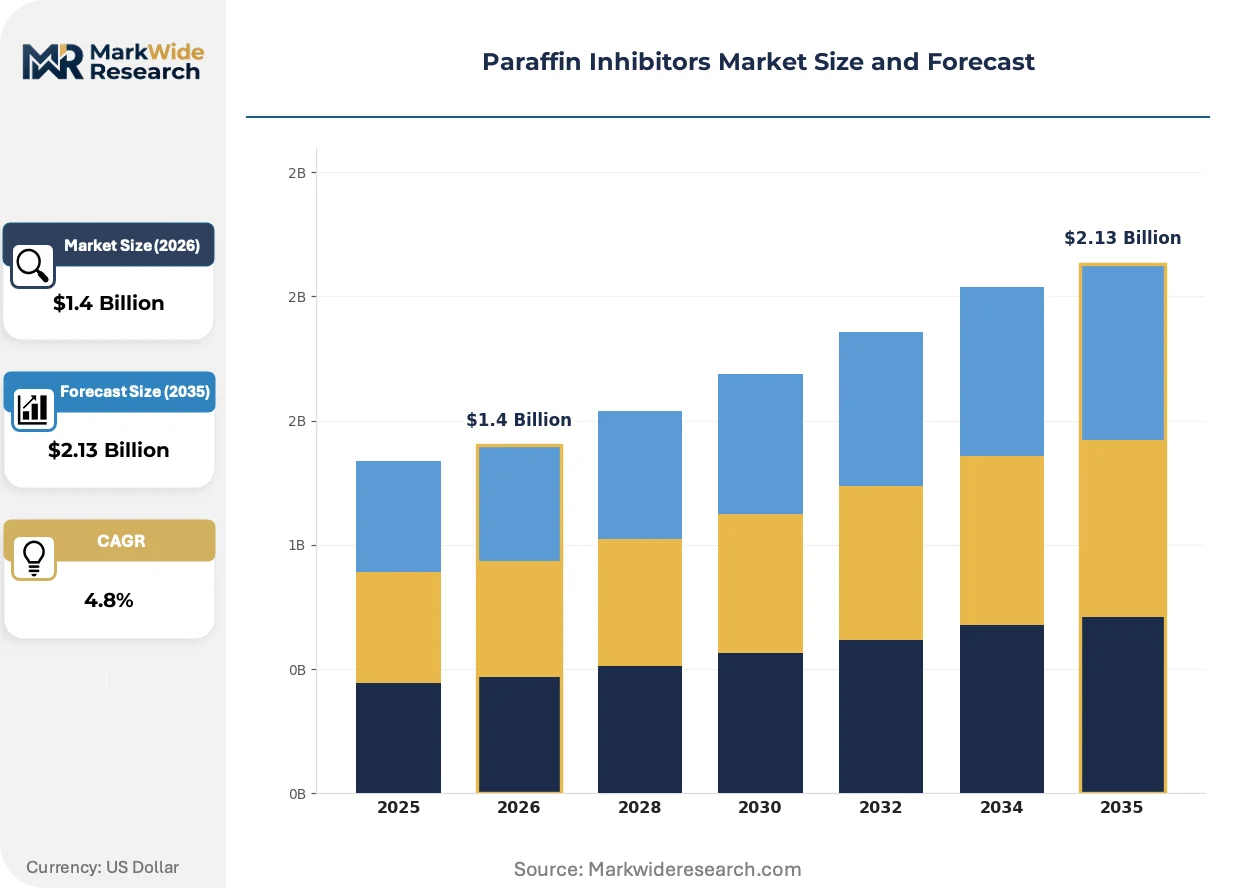
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystal Inhibitors, Emulsion Inhibitors, PVD Inhibitors, Multi-Functional Inhibitors Application: Onshore Applications, Offshore Applications, Oil Production, Pipeline Transport End User: Oil & Gas Industry, Chemical Processing, Refining, Marine Form: Liquid, Powder, Gel, Emulsion |
| Companies Covered | ChampionX, SLB, BASF SE, Halliburton, Dow Inc., Baker Hughes, Evonik Industries, Ecolab Inc., Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraffin Inhibitors Market Strategic Shifts & Innovations
Digital integration of chemical delivery with production optimization systems is compressing the traditional separation between chemical suppliers and operator engineering teams.
Polymer-surfactant hybrid architectures are overtaking conventional single-mechanism inhibitors in deepwater applications. These dual-function chemistries simultaneously disrupt wax nucleation and modify crystal growth kinetics. Brazilian pre-salt operators are specifying hybrid formulations in 80% of new subsea chemical injection contracts. The technology is overtaking legacy polymeric dispersants in margin contribution due to patent-protected molecular designs and reduced dosage requirements.
EPA's offshore NPDES permit revisions are tightening chronic toxicity thresholds for discharged production chemicals. The regulatory pressure is forcing reformulation of incumbent surfactant packages toward bio-derived alternatives. Gulf of Mexico deepwater facilities face the most immediate compliance deadlines, with operators pre-qualifying suppliers based on validated biodegradation test data.
Integrated chemical management contracts are displacing traditional volume-based purchasing across major offshore developments. Operators transfer dosage optimization risk to suppliers in exchange for guaranteed production uptime metrics. This procurement evolution is most advanced in the North Sea, where Equinor and Shell have adopted full-service chemical stewardship models on multiple producing assets.
Paraffin Inhibitors Market Segmentation
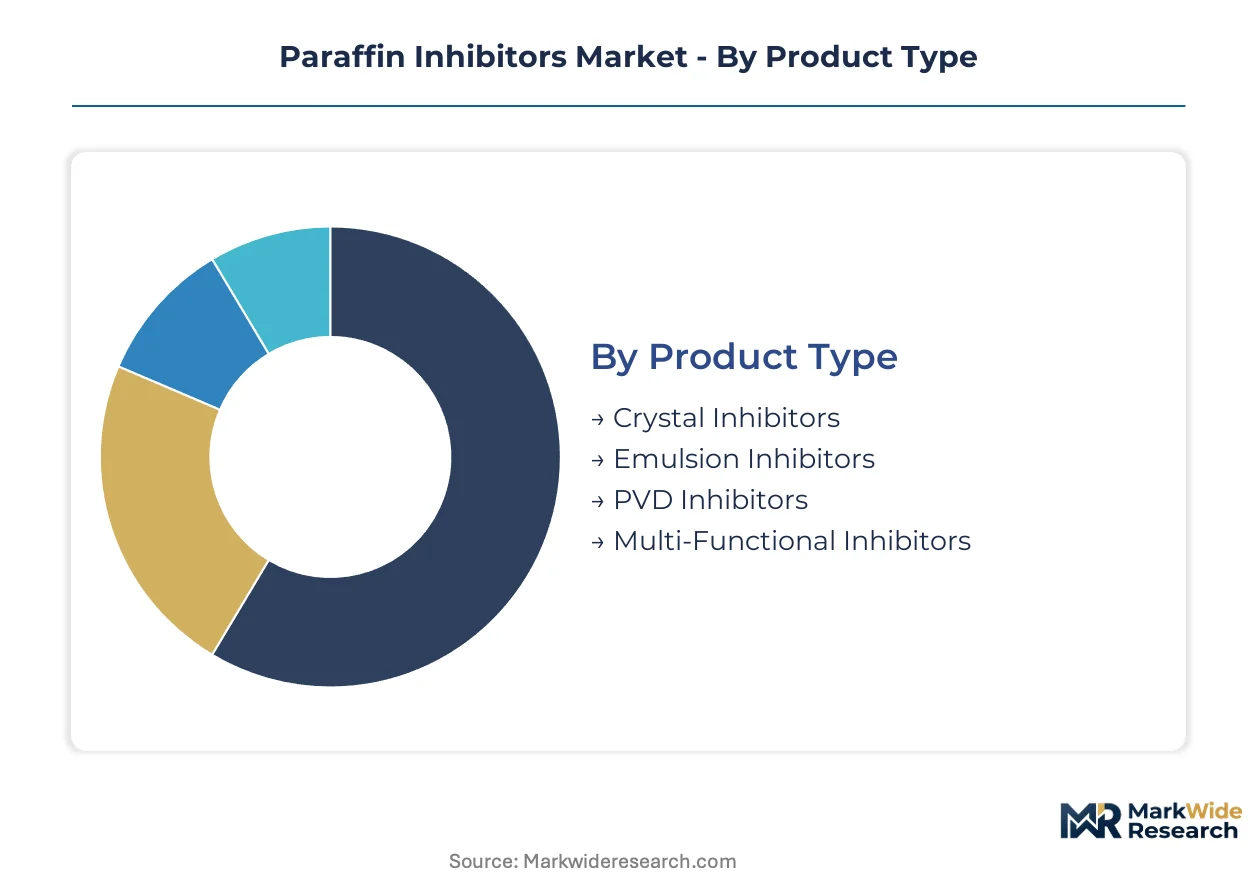
Paraffin inhibitor suppliers configure product portfolios across four distinct segmentation axes. Each dimension carries different margin profiles, regulatory exposure, and technical barriers to entry that determine competitive positioning.
Product Type:
Crystal inhibitors dominate volume shipments while multi-functional formulations capture expanding premium pricing.
- Crystal Inhibitors:Polymeric dispersants and surfactant blends that modify wax crystal morphology to prevent nucleation and growth. Demand concentrates in Brazilian pre-salt fields where wax content exceeds conventional crudes, driven by Petrobras subsea injection specifications.
- Multi-Functional Inhibitors:Integrated chemistries combining wax control with corrosion inhibition and hydrate suppression functions. Gulf of Mexico operators are consolidating chemical injection programs to reduce umbilical complexity on deepwater platforms.
- Emulsion Inhibitors:Surfactant packages designed to break water-in-oil emulsions while controlling paraffin deposition.
- PVD Inhibitors:Pressure-volume-temperature optimized formulations for high-pressure high-temperature well conditions.
Today's leader: Crystal Inhibitors. Tomorrow's challenger: Multi-Functional Inhibitors.
Application:
Offshore deployments command premium economics despite smaller volumes, reflecting subsea logistics constraints and performance guarantees.
- Offshore Applications:Subsea wellhead injection and platform-based chemical delivery systems. North Sea operators under EU REACH marine toxicity mandates are pre-qualifying suppliers with validated biodegradation data.
- Onshore Applications:Pipeline transport and tankage injection for conventional production. Mature volume base with price-sensitive procurement through volume-based contracts.
- Oil Production:Downhole and gathering system applications focused on maintaining well productivity.
- Pipeline Transport:Long-distance crude movement requiring cold-flow maintenance across temperature differentials.
Offshore Applications anchor supplier margins. Onshore Applications defend volume scale.
End User:
Oil and gas operators drive formulation specifications while chemical processors represent a fragmented secondary channel.
- Oil & Gas Industry:Integrated supermajors and national oil companies specifying performance-based chemical management contracts. Brazilian deepwater development anchors demand concentration for advanced crystal modifier systems.
- Refining:Downstream processing units managing wax deposition in crude distillation and vacuum units.
- Chemical Processing:Petrochemical facilities handling waxy feedstocks with specialized additive requirements.
- Marine:Bunker fuel treatment and cargo heating applications for vessel operators.
Oil & Gas Industry sets technical standards. Refining offers margin expansion through specification upgrading.
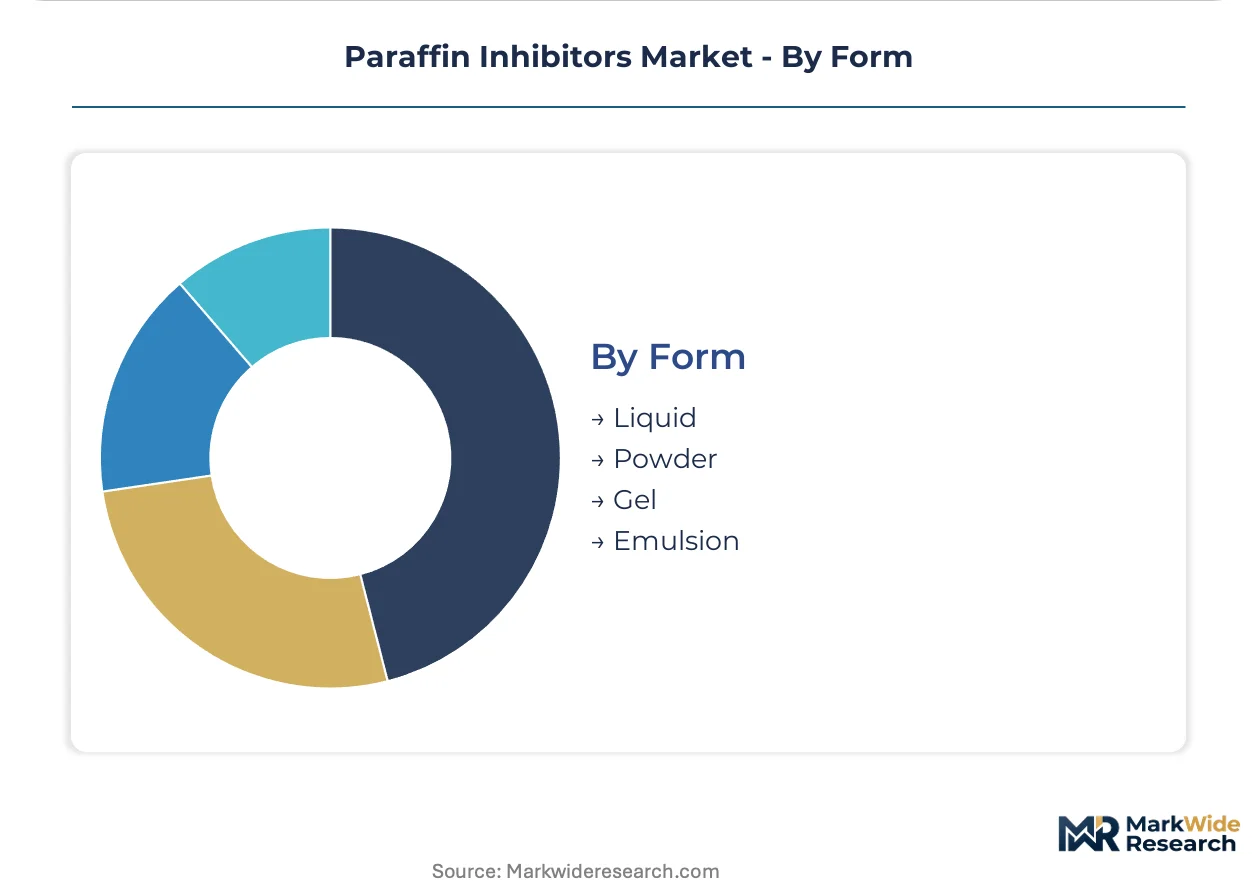
Form:
Liquid formulations dominate subsea delivery while powder and gel alternatives address specific handling constraints.
- Liquid:Pump-ready solutions for continuous injection via umbilical infrastructure. Gulf of Mexico facilities specify liquid formulations for compatibility with existing subsea storage and distribution systems.
- Gel:High-viscosity carriers for extended-release applications in remote wellbores.
- Powder:Concentrated solid additives for on-site dilution and batch treatment programs.
- Emulsion:Water-based dispersions reducing solvent content for environmental compliance.
Liquid formulations maintain delivery dominance. Gel formats are gaining traction in extended-reach drilling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basins generate heavier inhibitor demand per barrel than US Gulf fields, while Norway's North Sea operators face stricter marine toxicity deadlines than their North American counterparts.
United States
Deepwater platforms in the Gulf of Mexico deploy real-time wax deposition sensors on high-pressure high-temperature completions. EPA offshore NPDES permit revisions tighten chronic toxicity thresholds for discharged production chemicals. Houston anchors the largest concentration of formulation laboratories serving subsea chemical injection programs.
Brazil
Petrobras-led development in the Santos Basin drives continuous inhibitor injection at subsea wellheads where pre-salt crude wax content exceeds conventional grades. ANVISA registration requirements for imported chemical additives create compliance barriers for non-local suppliers. Rio de Janeiro hosts the primary technical centers coordinating crystal inhibitor specifications for deepwater developments.
Norway
Equinor and Shell have adopted full-service chemical stewardship models across multiple producing assets in the North Sea. EU ECHA REACH framework on polymer biodegradability accelerates reformulation investments toward bio-based dispersant backbones. Aberdeen competes with Houston for limited talent pools in subsea chemist expertise.
United Kingdom
North Sea operators under EU marine toxicity mandates pre-qualify suppliers with validated biodegradation data for platform-based chemical delivery systems. HSE offshore safety regulations govern chemical handling and storage infrastructure on aging production facilities. Scotland's Aberdeen cluster maintains specialized polymer-solvent compatibility research capabilities.
China
National oil companies expand chemical injection programs in offshore Bohai Bay fields with wax deposition challenges. MEE environmental standards on marine discharge from offshore platforms elevate biodegradable formulation requirements. Tianjin and Qingdao house the primary manufacturing bases for polymeric dispersant production serving domestic deepwater developments.
Paraffin Inhibitors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service providers commanding offshore platform contracts while independent chemical houses defend onshore volume accounts. The vendor base concentrates around three merchant suppliers controlling high-molecular-weight polymeric dispersant manufacturing. Strategic archetypes include integrated production chemistry platforms, polymer backbone innovators, and real-time monitoring system integrators. Competitive moves center on performance-based contracting structures and backward integration into bio-based polymer feedstocks.
Among US-based integrated service providers, ChampionX and Halliburton occupy positions anchoring long-term offshore chemical management contracts through risk-transfer arrangements. SLB exemplifies the technology leadership archetype through its focus on predictive dosing systems. BASF SE, as a European chemical conglomerate, represents the polymer innovation tier competing on molecular architecture differentiation for cold-flow improvement applications.
| Leading Market Players |
|---|
| ChampionX |
| SLB |
| BASF SE |
| Halliburton |
| Dow Inc. |
| Baker Hughes |
| Evonik Industries |
| Ecolab Inc. |
| Clariant |
| Others |
Cost & Logistics Intelligence
Polymer-surfactant hybrid architectures are compressing cost economics while concentrating supply among patent-holding formulators, as Brazilian pre-salt operators specify advanced crystal modifiers that legacy dispersant manufacturers cannot produce without licensing or R&D reinvestment.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard polymeric dispersants, though premium hybrid formulations retain pricing power through performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates subsea-certified hybrids from onshore commodity dispersants and unbranded regional alternatives. Pricing pressure stems from ethylene oxide feedstock volatility tied to naphtha cracking economics. National oil companies in Brazil exhibit lowest price sensitivity due to production uptime penalties, while independent onshore operators in mature US basins drive hardest volume negotiations.
Supply Chain Analysis
Dual-sourcing mandates from Equinor and Shell require North Sea operators to qualify at least two suppliers for critical subsea chemistries, fragmenting procurement across ChampionX, SLB, and BASF SE. Manufacturing concentrates in the US Gulf Coast, Germany, and China, with polymer backbone production drawing from alpha-olefin feedstocks sourced from Saudi Arabia and South Korea. Single-source vulnerability persists for high-molecular-weight dispersant manufacturing after hurricane-related interruptions. Distribution runs through integrated service providers anchoring long-term offshore contracts rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Brazil's premium-tolerant pre-salt demand and China's cost-optimized manufacturing base, with the spread widened by ANVISA registration barriers that protect incumbent margins.
For Market Incumbents: Anticipate REACH registration timeline compression by accelerating polymer dossier preparation for marine toxicity assessment. Prioritize backward integration into bio-based ethylene feedstocks to preempt EPA biodegradable discharge pathway requirements. Defend platform offtake agreements through integrated chemical management contracts that transfer dosage optimization risk. For New Entrants and Emerging Players: Regional distributors in West Africa represent the most penetrable channel partner type for breaking into underdeveloped pre-salt analogs offshore Angola and Nigeria. Target joint-venture structures with local content requirements rather than direct operator sales. Emphasize multi-functional inhibitor platforms that consolidate umbilical complexity for deepwater developments lacking infrastructure for multiple chemical injection streams. For Investors and Strategic Acquirers: Valuations sit cheapest among independent chemical houses with polymer backbone innovation capabilities but lacking integrated service infrastructure. Five-to-ten-year viability hinges on bio-based formulation transitions outpacing regulatory displacement of conventional chemistries. Monitor EPA subsea chemical guideline revisions as the primary inflection signal for first-mover advantage in biodegradable discharge pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Expansion | ChampionX and SLB anchor long-term offshore agreements transferring technical risk from Petrobras to suppliers. |
| Bio-Based Polymer Feedstock Integration | BASF SE competes on molecular architecture differentiation as ECHA REACH mandates accelerate reformulation investments. |
| Real-Time Monitoring System Deployment | Downhole wax deposition sensors enable predictive dosing across Gulf of Mexico high-pressure high-temperature completions. |
| Multi-Functional Inhibitor Development | Gulf of Mexico operators consolidate chemical injection programs to reduce umbilical complexity on deepwater platforms. |
| West African Joint Venture Formation | Local content requirements in Angola and Nigeria favor partnership structures with established international suppliers. |
Research Approach
Coverage spans Brazil, the United States, Norway, the United Kingdom, and China, with primary inputs from each market gathered through structured interviews with subsea chemists, offshore platform operations managers, chemical procurement leads at national oil companies, and polymer R&D directors. Secondary validation draws from EPA NPDES permit filings, ECHA REACH registration databases, ANVISA chemical additive records, SEC 10-K disclosures from integrated service providers, and customs trade data on alpha-olefin imports. Bottom-up volume estimates triangulate with top-down market sizing across product type, application, and regional dimensions.
Granularity-level modeling extends to crystal inhibitor versus multi-functional inhibitor chemistry types, offshore versus onshore deployment contexts, and subsea wellhead versus platform-based delivery systems. CAGRs derive from segment-level growth rate reconciliation against macro oil production forecasts and deepwater development capex trajectories. Industry-specific inputs include Petrobras subsea injection specifications, Equinor chemical stewardship contract structures, and EPA chronic toxicity threshold evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene feedstock price volatility and REACH registration timeline enforcement. Deviation in Brazilian pre-salt production economics or EPA biodegradable discharge pathway finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Proline Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Thermic Fluids Market