
 Chemical Process Mixers Market | 2026-2036
Chemical Process Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Process Mixers Market Analytics
Germany is reconfiguring its position as a high-specification manufacturing hub for chemical process mixers serving European specialty chemical demand. SPX FLOW leverages its vertical integration into precision casting and drive assembly to sustain delivery reliability for large-capacity units. Sulzer anchors its competitive stance through deep specialization in multistage mixing systems for polymerization processes. Alfa Laval competes on heat-integrated mixer designs that occupy premium positions in pharmaceutical sterile processing.
Chemical process mixers are industrial machines designed to achieve homogeneous blending of liquid, solid, or multiphase materials through controlled mechanical, pneumatic, or ultrasonic energy input, typically operating at pressures from atmospheric to 150 bar and temperatures spanning cryogenic to 500°C depending on alloy selection. Their primary purpose centers on ensuring reaction uniformity, thermal transfer efficiency, and product consistency across continuous or batch production cycles. Batch mixers retain dominant share in pharmaceutical and fine chemical applications where recipe integrity and cleaning validation govern equipment selection, while continuous mixers are gaining structural ground in bulk chemical and food processing lines seeking throughput optimization and reduced holdup volume. Mechanical agitation technology leads installed base owing to proven scale-up methodology and broad fluid compatibility, though magnetic agitation carves out defensible margin pools in aseptic and high-purity segments where seal integrity eliminates contamination pathways.
The EPA enforces emissions and material containment standards that shape mixer sealing technology and vapor recovery system design in US chemical manufacturing facilities. EMA and REACH jointly determine surface finish specifications, extractable testing protocols, and substance restriction lists that govern mixer construction for European pharmaceutical and cosmetic applications. OSHA mechanical safety directives and ATEX explosion protection frameworks further constrain equipment configuration for flammable solvent processing. Stakeholders must weigh regulatory trajectory against capital cycle timing when committing to platform architectures that must serve multiple jurisdictions through 2035 and beyond.
Market Dynamics
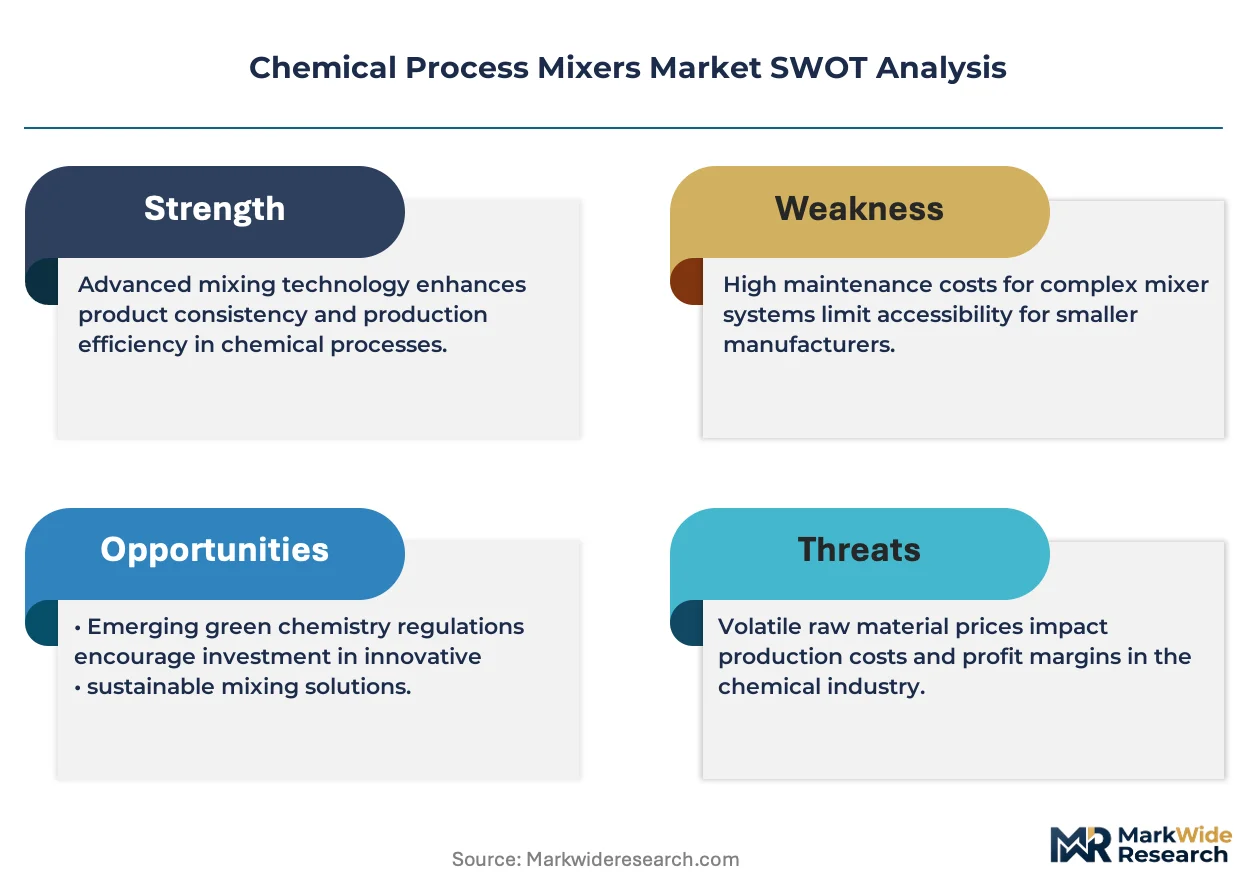
REACH compliance and the EU Green Deal are compressing material selection windows for wetted components, forcing manufacturers to validate new alloys against corrosion resistance and extractable limits simultaneously. This regulatory compression is redrawing competitive boundaries between established European suppliers and emerging Asian fabricators.
Growth Catalysts
- Hyderabad-Ahmedabad pharmaceutical corridor expansion:Indian CDMOs are commissioning stainless steel batch units for active pharmaceutical ingredient synthesis, creating concentrated equipment demand.
- EMA surface finish specifications:Sterile processing requirements for pharmaceutical mixers are tightening Ra values and mandating electropolishing documentation, elevating specification premiums.
- Magnetic agitation technology:Seal-free designs are penetrating aseptic biologics manufacturing where contamination pathways must be eliminated entirely.
Market Restraints
- Nickel alloy price volatility:Hastelloy and Inconel input costs swing with mining output from Indonesian and Philippine laterite deposits, compressing margin predictability for corrosion-resistant unit producers.
- German precision casting concentration:Critical impeller and shaft manufacturing clusters around Baden-Württemberg foundries, creating single-source vulnerability for large-capacity mixer drivetrains.
- Continuous mixer scale-up limitations:Residence time distribution control becomes probabilistic above 50 cubic meters, constraining adoption in bulk chemical applications requiring absolute batch traceability.
Strategic Opportunities
- Brazilian specialty chemical localization:ANVISA is tightening import documentation for pharmaceutical manufacturing equipment, creating captive demand for domestically assembled units with local validation support.
- Heat-integrated mixer designs:Convergence of mechanical agitation with plate heat exchanger geometries enables combined reaction-crystallization duty in polymerization processes.
- EU Green Deal material substitution mandates:Incentives for fluoropolymer-free seal designs are accelerating development of advanced ceramic bearing systems for high-purity applications.
Industry Challenges
- ASME U-stamp certification timelines:Pressure vessel qualification for North American projects extends delivery schedules by 14-20 weeks, constraining project execution velocity.
- Computational fluid dynamics modeling talent:Mixer design houses face acute shortages of engineers capable of validating multiphase turbulence models against physical test data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Process Mixers Market |
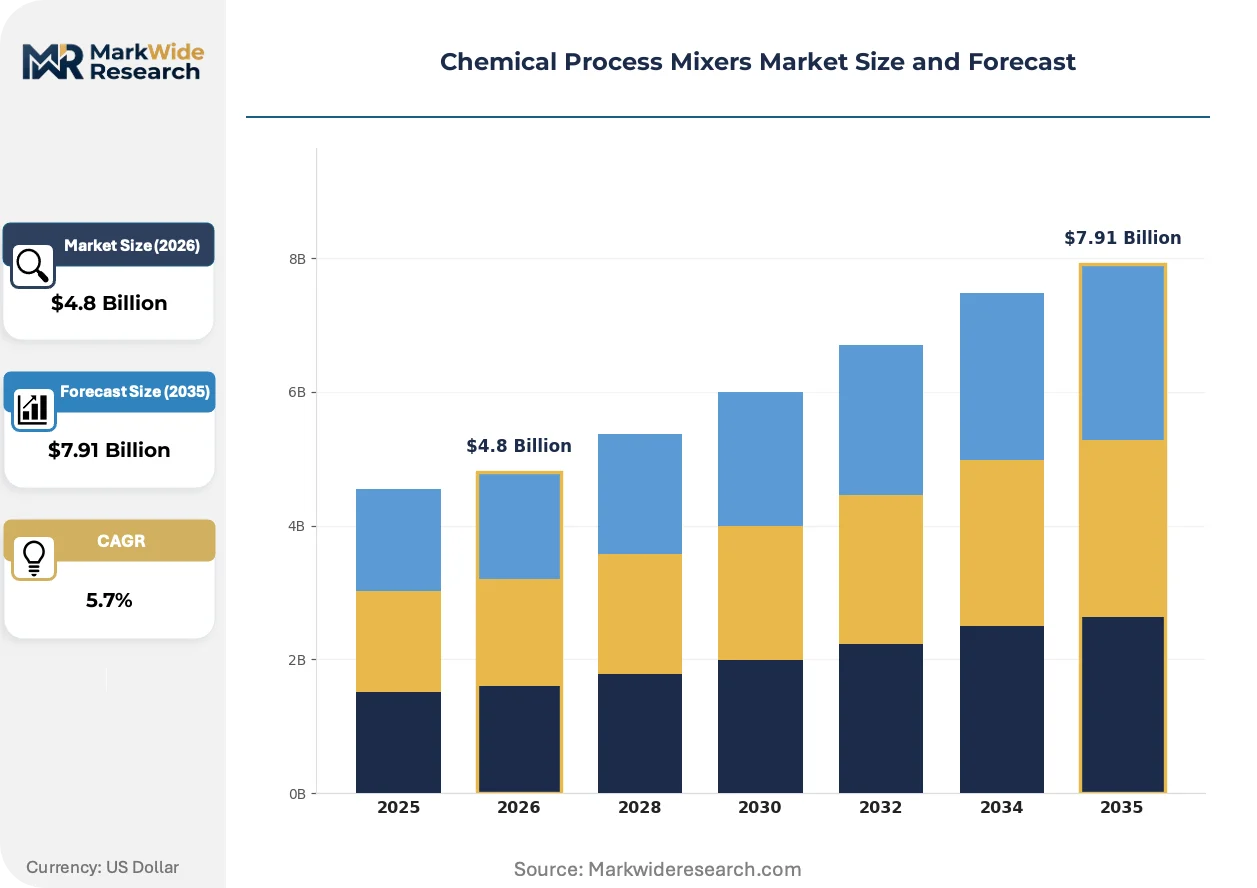
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mixers, Continuous Mixers, Multistage Mixers, Portable Mixers Technology: Mechanical Agitation, Air Agitation, Magnetic Agitation, Ultrasonic Mixing End Use Industry: Chemicals, Pharmaceuticals, Food & Beverage, Cosmetics Capacity: Small Scale, Medium Scale, Large Scale, Custom Capacity |
| Companies Covered | SPX FLOW, Sulzer, Alfa Laval, Xylem, GEA Group, EKATO Holding, Philadelphia Mixing Solutions, Charles Ross & Son Company, Silverson Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Process Mixers Market Evolving Landscape
Digital twin deployment and additive manufacturing are converging to compress prototype-to-production cycles for complex impeller geometries. Equipment suppliers are repositioning around predictive maintenance capabilities and modular platform architectures.
Computational fluid dynamics is migrating from post-design validation to real-time optimization. Pharmaceutical manufacturers in Switzerland and Germany are embedding CFD-driven speed controls that adjust agitation profiles based on in-line viscosity sensors. This shift is collapsing the traditional separation between equipment procurement and process development functions, forcing mixer vendors to employ PhD-level chemical engineers in sales engineering roles.
EPA emissions enforcement under the Clean Air Act is tightening vapor recovery requirements for volatile solvent processing. Mixer sealing technology must now demonstrate 99.5% containment efficiency for benzene and toluene service. Fine chemical producers in Texas and Louisiana are retrofitting magnetic drive systems and closed-loop nitrogen purging to avoid Title V permit modifications.
After-sales service unbundling is fragmenting traditional OEM revenue streams. Indian pharmaceutical clusters now procure spare impellers and mechanical seals through independent distributors rather than original equipment channels. This disintermediation is most pronounced in Ahmedabad, where local fabrication shops reverse-engineer wear parts for European-designed units at 40-60% cost differentials.
Chemical Process Mixers Market Segmentation
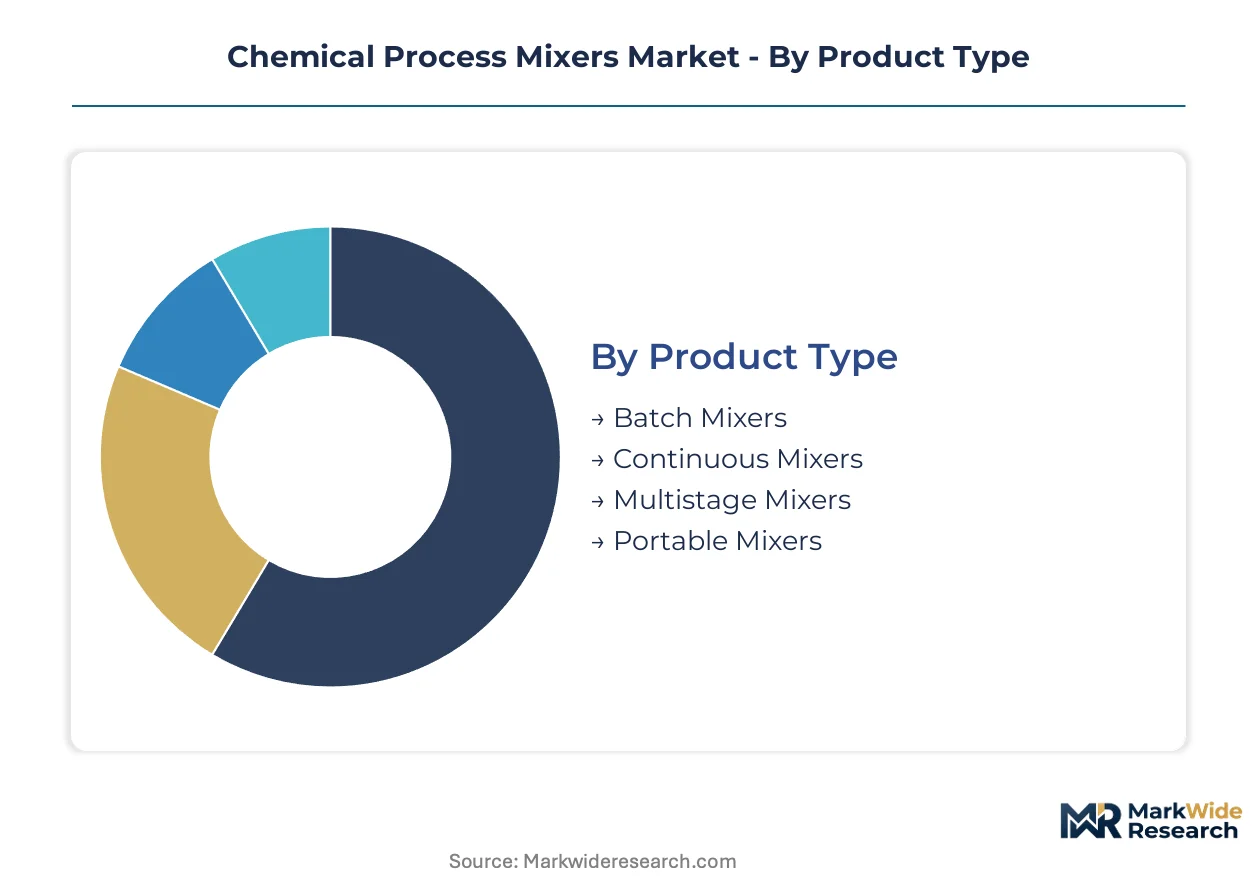
Mixer specification varies dramatically across production cycles. Batch units in pharmaceutical suites require 12-18 month qualification timelines, while continuous food processing lines turn over in 24-36 months. Understanding segment velocity protects capital deployment timing.
Product Type:
Cycle times stretch from rapid-turn portable rentals to decade-long continuous line investments.
- Batch Mixers:Vessel-based systems with discrete loading, mixing, and discharge sequences dominate pharmaceutical and fine chemical manufacturing. Demand concentrates in Hyderabad and Ahmedabad where Indian CDMOs commission stainless steel units for active pharmaceutical ingredient synthesis under CDSCO oversight. EMA surface finish specifications tighten Ra values and mandate electropolishing documentation, elevating specification premiums.
- Continuous Mixers:Steady-state flow systems achieve throughput optimization in bulk chemical and food processing applications. Residence time distribution control becomes probabilistic above 50 cubic meters, constraining adoption where absolute batch traceability governs regulatory compliance. German specialty chemical manufacturers favor these for polymerization sequences.
- Multistage Mixers:Cascaded chamber designs enable sequential reaction steps without intermediate transfer.
- Portable Mixers:Mobile drum and tote agitation equipment serves contract manufacturing and seasonal production demands.
Batch Mixers dominates installed base. Continuous Mixers is where expansion concentrates.
Technology:
Cost tiers separate commodity mechanical drives from precision magnetic systems commanding 3-4x price multiples.
- Mechanical Agitation:Shaft-sealed impeller systems using gearboxes and electric motors retain the broadest installed base. Proven scale-up methodology and broad fluid compatibility sustain demand across chemical and food applications. EPA emissions enforcement under the Clean Air Act tightens vapor recovery requirements, driving retrofit demand for improved sealing.
- Magnetic Agitation:Seal-free designs using rare-earth couplings eliminate contamination pathways in aseptic biologics manufacturing. Swiss and German pharmaceutical manufacturers embed CFD-driven speed controls adjusting agitation profiles based on in-line viscosity sensors. This technology carves defensible margin pools where seal integrity is non-negotiable.
- Air Agitation:Pneumatic bubble-driven mixing serves explosion-risk environments and simple blending duties.
- Ultrasonic Mixing:High-frequency cavitation systems achieve emulsification without mechanical shear.
Mechanical Agitation anchors volume leadership. Magnetic Agitation is climbing the fastest on specification premiums.
End Use Industry:
Application severity determines alloy selection and documentation burden.
- Chemicals:Corrosion-resistant units handle acids, bases, and solvents across commodity and specialty production. REACH compliance and the EU Green Deal compress material selection windows, forcing simultaneous validation of new alloys against corrosion resistance and extractable limits. Nickel alloy price volatility swings with Indonesian and Philippine laterite mining output.
- Pharmaceuticals:Sterile processing equipment serves active ingredient synthesis and formulation. FDA and EMA jointly determine surface finish specifications, extractable testing protocols, and substance restriction lists. Hyderabad-Ahmedabad corridor expansion creates concentrated equipment demand from Indian CDMOs.
- Food & Beverage:Sanitary designs meet USDA and FSSAI hygiene mandates for edible product contact.
- Cosmetics:Precision emulsification systems support cream, lotion, and pigment dispersion applications.
Chemicals commands the largest equipment population. Pharmaceuticals is gaining share fastest on regulatory specification premiums.
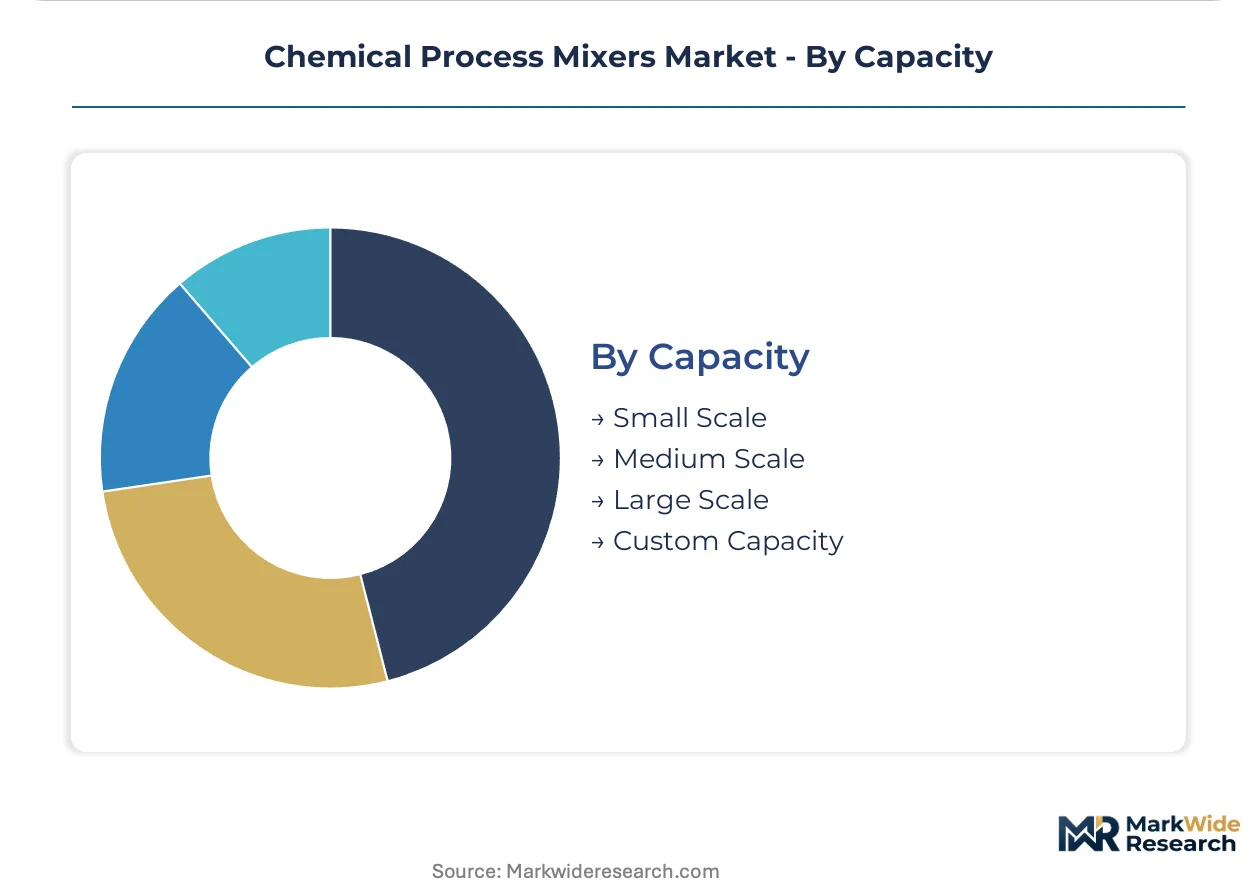
Capacity:
Customer type stratification separates pilot-scale R&D purchases from integrated production line commitments.
- Small Scale:Laboratory and pilot-scale units below 100 liters serve process development and clinical batch production. Pharmaceutical manufacturers in Switzerland deploy these for formulation screening before technology transfer to commercial suites.
- Medium Scale:Production units between 100 and 10,000 liters bridge pilot validation and commercial manufacturing. Brazilian specialty chemical localization under ANVISA import documentation tightening favors domestically assembled medium-scale units with local validation support.
- Large Scale:Industrial vessels exceeding 10,000 liters dominate bulk chemical and food processing. German precision casting concentration around Baden-Württemberg foundries creates single-source vulnerability for impeller and shaft manufacturing.
- Custom Capacity:Engineered-to-order systems address non-standard geometries and extreme pressure-temperature ratings.
Medium Scale captures the broadest customer base. Custom Capacity is expanding most quickly on specialty chemical diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision casting clusters around Baden-Württemberg foundries supply critical impeller and shaft components for large-capacity units worldwide. This supply concentration creates single-source vulnerability while shaping regional competitive positioning across three continents.
United States
EPA emissions enforcement under the Clean Air Act drives retrofit demand for magnetic drive systems and closed-loop nitrogen purging in Texas and Louisiana fine chemical corridors. OSHA mechanical safety directives and ATEX frameworks constrain equipment configuration for flammable solvent processing. Houston-Gulf Coast petrochemical clusters commission corrosion-resistant batch units for specialty chemical manufacturing.
Germany
REACH compliance and the EU Green Deal compress material selection windows for wetted components in specialty chemical manufacturing. EMA surface finish specifications tighten Ra values and mandate electropolishing documentation for pharmaceutical sterile processing. Baden-Württemberg foundries concentrate precision casting for impeller and shaft manufacturing serving European demand.
India
CDSCO oversight governs active pharmaceutical ingredient synthesis equipment in expanding contract manufacturing operations. The Hyderabad-Ahmedabad pharmaceutical corridor commissions stainless steel batch units from domestic and European suppliers. Local fabrication shops in Ahmedabad reverse-engineer wear parts for European-designed units at significant cost differentials.
Switzerland
Swissmedic regulates sterile processing equipment for biologics manufacturing where contamination pathways must be eliminated. Pharmaceutical manufacturers embed CFD-driven speed controls adjusting agitation profiles based on in-line viscosity sensors. Basel-Zurich pharmaceutical clusters demand magnetic agitation systems for aseptic production environments.
Brazil
ANVISA import documentation tightening creates captive demand for domestically assembled pharmaceutical manufacturing equipment. Specialty chemical localization incentives favor medium-scale units with local validation support over imported alternatives. São Paulo state industrial corridors attract assembly operations serving Latin American contract manufacturing demand.
Chemical Process Mixers Market Competitive Landscape
Vertically integrated multinationals and specialized engineering houses split the market into distinct capability tiers. Consolidation pressure concentrates around precision casting and drive assembly competencies where scale advantages compound. Equipment suppliers compete through predictive maintenance platforms, modular architectures, and CFD-integrated design services. M&A activity targets magnetic agitation specialists and regional validation service providers.
Among European-based engineering groups, SPX FLOW, Sulzer, and Alfa Laval exemplify divergent competitive positioning. SPX FLOW represents backward integration into precision casting and drive assembly for delivery reliability. Sulzer occupies a position in multistage mixing system specialization for polymerization processes. Alfa Laval anchors heat-integrated mixer design capabilities serving pharmaceutical sterile processing segments.
| Leading Market Players |
|---|
| SPX FLOW |
| Sulzer |
| Alfa Laval |
| Xylem |
| GEA Group |
| EKATO Holding |
| Philadelphia Mixing Solutions |
| Charles Ross & Son Company |
| Silverson Machines |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors transmit nickel alloy cost volatility from Indonesian laterite mining zones directly into European mixer pricing, amplifying margin compression for corrosion-resistant batch units while forcing specification premiums to stratify across certification tiers.
Pricing Analysis
REACH dictates the pricing tier structure across the European installed base, separating EMA-validated sterile processing units from standard chemical-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors on surface finish documentation burden and electropolishing certification depth. Cost compression in economy-tier mechanical agitation systems is intensifying because Indian CDMOs now procure reverse-engineered wear parts at substantial discounts. Pharmaceutical sterile processing buyers exhibit least price sensitivity due to validation timeline risks, while commodity chemical operators maximize supplier switching.
Supply Chain Analysis
Baden-Württemberg foundries and Swiss precision machining clusters hold captive capacity for large-scale impeller and shaft manufacturing serving global demand. Component sourcing draws from Indonesian nickel laterite deposits, German precision casting networks, and Indian stainless steel fabrication corridors. Single-source vulnerability concentrates in drivetrain manufacturing where Baden-Württemberg capacity lacks geographic redundancy. Distribution runs through OEM direct channels for validated pharmaceutical units and independent aftermarket distributors for standard chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Indian pharmaceutical CDMOs as their procurement scale concentrates across the Hyderabad-Ahmedabad corridor, fragmenting traditional OEM aftermarket revenue streams through localized fabrication alternatives.
For Market Incumbents: Insulate margin pools in magnetic agitation technology by deepening captive supply of rare-earth coupling assemblies and accelerating CFD-integrated design service capabilities. Seal-free biologics manufacturing demand is displacing mechanical agitation in Swiss and German sterile processing clusters, threatening volume leadership in premium tiers. Backward integration into precision casting capacity in Baden-Württemberg represents the critical defensive lever against single-source supply disruption. For New Entrants and Emerging Players: Build out regional validation service capabilities in Brazil under ANVISA documentation tightening, targeting medium-scale pharmaceutical assembly with domestic compliance support. Brazilian specialty chemical localization offers the most penetrable white-space given import barrier escalation and absence of established local OEM presence. Partner with São Paulo state industrial corridor operators for assembly footprint access rather than greenfield manufacturing investment. For Investors and Strategic Acquirers: Magnetic agitation specialists with embedded CFD modeling competencies present acquisition targets with defensible technology moats in aseptic biologics segments. Long-term viability across the analysis window hinges on regulatory specification depth rather than commodity volume scale. Watch EMA surface finish specification trajectory as the inflection signal for premium-tier margin expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive supply of Baden-Württemberg impeller capacity eliminates single-source vulnerability for large-unit drivetrains. |
| CFD-Integrated Design Service Launch | Swiss and German pharmaceutical manufacturers now embed real-time agitation optimization into sterile processing workflows. |
| Brazilian Assembly Localization | ANVISA documentation tightening creates captive demand for domestically validated medium-scale pharmaceutical units. |
| Magnetic Agitation Technology Acquisition | Seal-free designs command specification premiums in aseptic biologics where contamination elimination is non-negotiable. |
| Aftermarket Channel Restructuring | Indian pharmaceutical clusters now source wear parts through independent distributors rather than OEM channels. |
Research Methodology
The analysis maps batch mixer, continuous mixer, and magnetic agitation technology sub-sectors, each validated through procurement directors at Indian CDMOs, plant engineers at German specialty chemical manufacturers, and aftermarket service heads at European OEMs. Primary interview intelligence triangulates against customs trade data for nickel alloy imports, EMA surface finish guidance documents, and SEC filings from listed equipment suppliers. Bottom-up unit demand estimation and top-down industry revenue reconciliation anchor quantitative outputs.
Fixed assumptions across the projection horizon include sustained REACH compliance stringency, continued nickel price volatility from Indonesian mining output, and stable EMA surface finish specifications for sterile processing. Segmentation modeling spans product type, technology category, end-use industry vertical, and capacity tier. CAGRs derive from installed base turnover rates, replacement cycle analysis, and greenfield project pipeline tracking across pharmaceutical and specialty chemical corridors.
Stress conditions across nickel alloy price bands, EMA specification tightening velocity, and Indian localization policy intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against CDSCO equipment registration databases and ANVISA import documentation trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Lime Manufacturing Market