
 Global Sponge Applicator Market | 2026-2036
Global Sponge Applicator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sponge Applicator Market Outlook
Polyurethane foam is consolidating its position as the dominant substrate across premium and mass-market sponge applicator lines, displacing natural latex in applications where allergen sensitivity creates liability exposure. Glocos International leverages captive foam production to control input costs across its applicator portfolio. Taiki Group anchors its competitive stance through Japanese precision-molding expertise in cosmetic-grade sponge geometries. Beautyblender differentiates via proprietary edgeless designs that command premium positioning in professional makeup channels.
A sponge applicator is a porous, compressible tool engineered from open-cell foam, microfiber composites, or synthetic elastomers with controlled pore density ranging from 50 to 200 pores per inch, designed to pick up, transfer, and blend liquid or cream formulations across surfaces. Foam variants dominate volume shipments due to their cost-efficiency in disposable cosmetic and household cleaning applications, while microfiber segments capture disproportionate margin pools where reusability and streak-free performance justify higher unit prices. Synthetic materials represent the fastest-growing composition category as manufacturers reformulate away from natural latex to meet dermatological safety protocols and extend shelf stability.
REACH restrictions on isocyanate-based precursors and the EU's broader chemical hazard classifications are forcing reformulation investments across European supply chains, while the FDA's color additive and cosmetic safety regulations shape product-market access in the United States. China's SAMR enforces GB standards for cosmetic tool materials that increasingly align with international norms, reducing friction for export-oriented manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment supply chains and inflate certification burdens for multi-region operators.
Market Dynamics
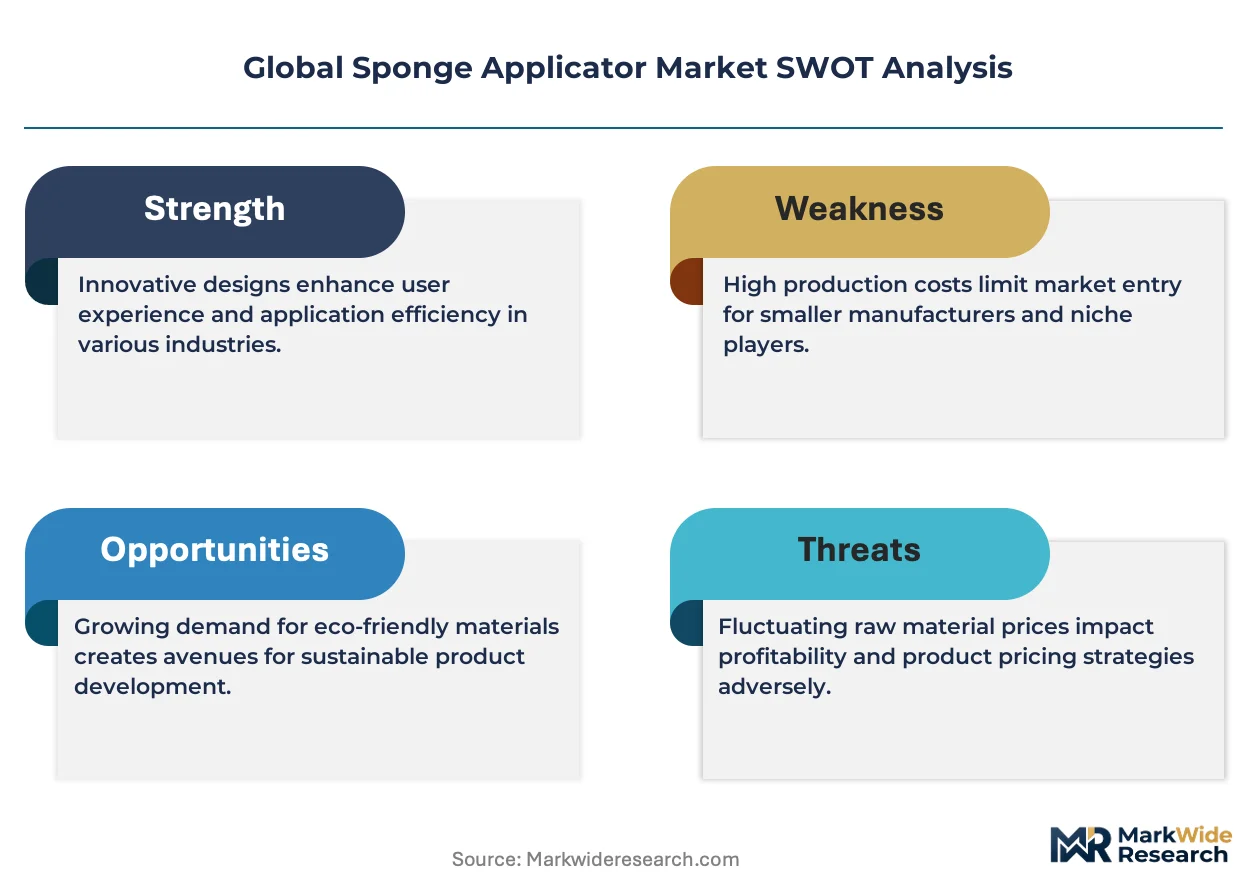
Polyurethane foam consolidation and REACH-driven material reformulation are compressing supplier margins while concentrating production among foam-captive manufacturers who can absorb compliance costs internally.
Growth Catalysts
- Cosmetic-grade polyurethane foam:Open-cell foam with 80-120 pores per inch delivers superior foundation blending performance, displacing natural latex in professional makeup artist kits across North America and Western Europe.
- China's SAMR alignment with GB standards:Harmonized cosmetic tool material regulations reduce export certification friction for domestic manufacturers supplying Korean and Japanese beauty brands.
- Microfiber composite layering:Dual-density construction combining absorbent cores with streak-resistant surfaces commands premium positioning in reusable applicator segments.
Market Restraints
- Isocyanate precursor cost volatility:TDI and MDI feedstock prices fluctuate with crude oil indices, squeezing foam converter margins when contract pricing lags spot markets by 90-120 days.
- Single-region foam concentration:Zhejiang and Guangdong provinces host over 60 percent of global cosmetic-grade foam extrusion capacity, creating geographic risk exposure for non-captive applicator brands.
- Latex allergen liability:Dermatological adverse event reporting requirements under FDA cosmetic safety guidance force reformulation investments for legacy natural rubber product lines.
Strategic Opportunities
- India's underpenetrated professional makeup channel:Bollywood production growth and bridal service expansion create first-mover advantage for edgeless sponge geometries priced below import parity.
- Solvent-free adhesive bonding:UV-cured lamination eliminates VOC emissions during microfiber-foam composite assembly, qualifying products for EU Green Deal procurement preferences.
- Direct-to-artist subscription models:Monthly replenishment services bypass traditional beauty retailer slotting fees while capturing professional makeup artist lifetime value.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning foam rheology and skin compatibility testing concentrates among legacy Japanese and German suppliers, limiting new entrant product development velocity.
- Multi-jurisdiction certification timelines:Sequential FDA color additive petitions and REACH SVHC dossier preparation extend product launch cycles by 14-18 months for reformulated synthetic foam lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sponge Applicator Market |
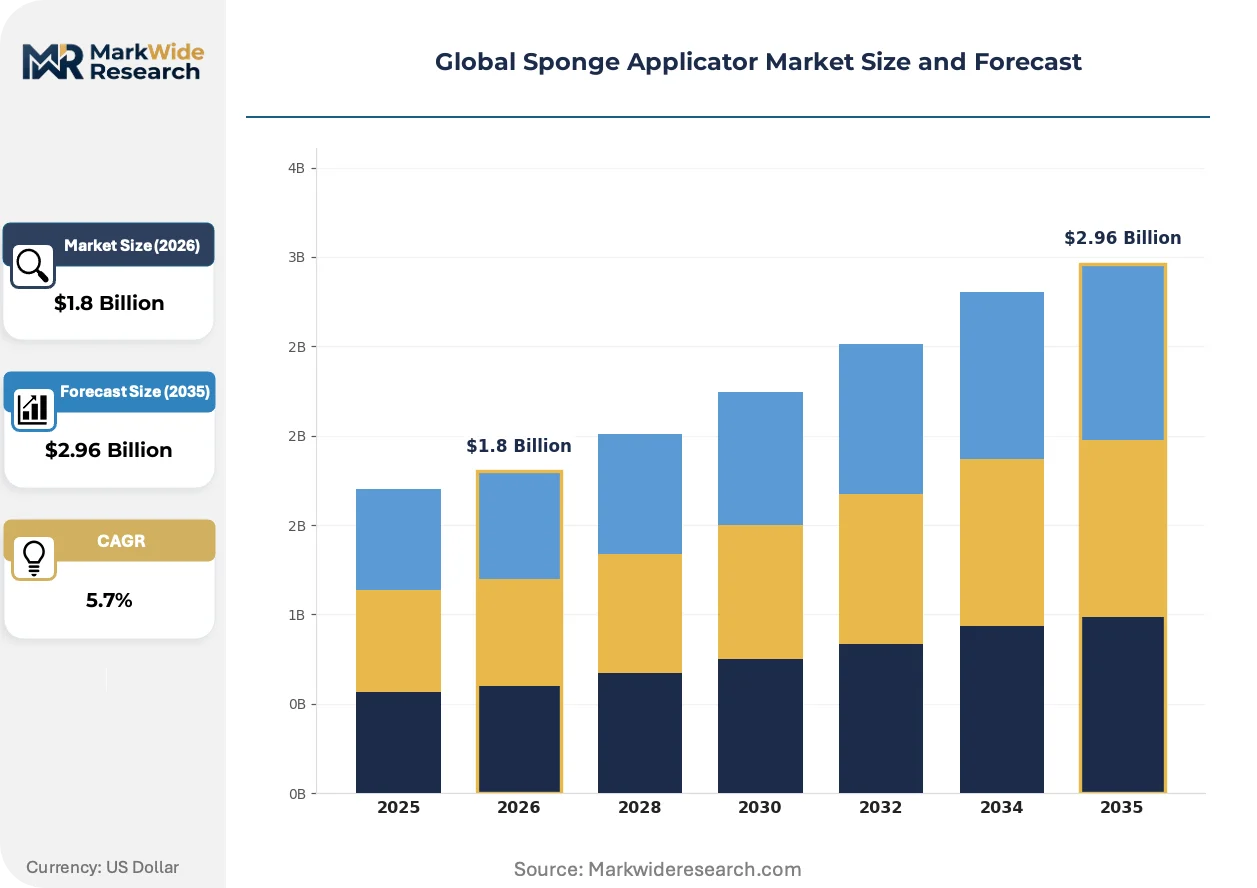
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Latex, Microfiber, Synthetic End User: Cosmetics, Household, Automotive, Industrial Application: Makeup, Cleaning, Painting, Personal Care Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Gilca, Glocos International, Taiki Group, Menshen, Brooklyn Products International, Real Techniques, Beautyblender, ECOTOOLS, Spectrum Laboratory Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sponge Applicator Market Strategic Shifts
Material science convergence with dermatological safety protocols is compressing product development cycles while fragmenting competitive advantage between foam chemistry specialists and precision-molding equipment manufacturers.
Silicone-infused hybrid foams are overtaking conventional polyurethane in premium concealer applicators, combining the compressibility of open-cell structures with non-porous surface hygiene that professional makeup artists demand for client sanitation protocols. Department store beauty halls and specialized e-commerce platforms are accelerating adoption curves by 40 percent versus mass-market drugstore channels. This substrate shift is overtaking legacy latex and basic polyurethane positioning in the $15-plus unit price tier, compressing margin pools for non-differentiated foam converters.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent residues in foam production are forcing European manufacturers to migrate toward supercritical CO2 foaming processes by 2027. Industrial consequence includes 25-30 percent capital expenditure increases for extrusion line retrofits and third-party process validation requirements. German and French cosmetic applicator specialists are most affected, responding through consortia arrangements to share toxicological testing burdens and accelerate alternative chemistry dossier preparation.
Professional makeup artists are consolidating purchase authority through centralized procurement cooperatives that negotiate annual volume contracts directly with foam converters, bypassing traditional beauty distributor markups. This channel disintermediation concentrates buying power among 200-300 artist collectives across Los Angeles, London, and Seoul, replacing fragmented individual purchasing. The cooperative model is most visible in South Korea's K-beauty training academy networks, where graduating artists enter pre-negotiated supply agreements that lock in applicator sourcing for 24-month certification cycles.
Global Sponge Applicator Market Segmentation
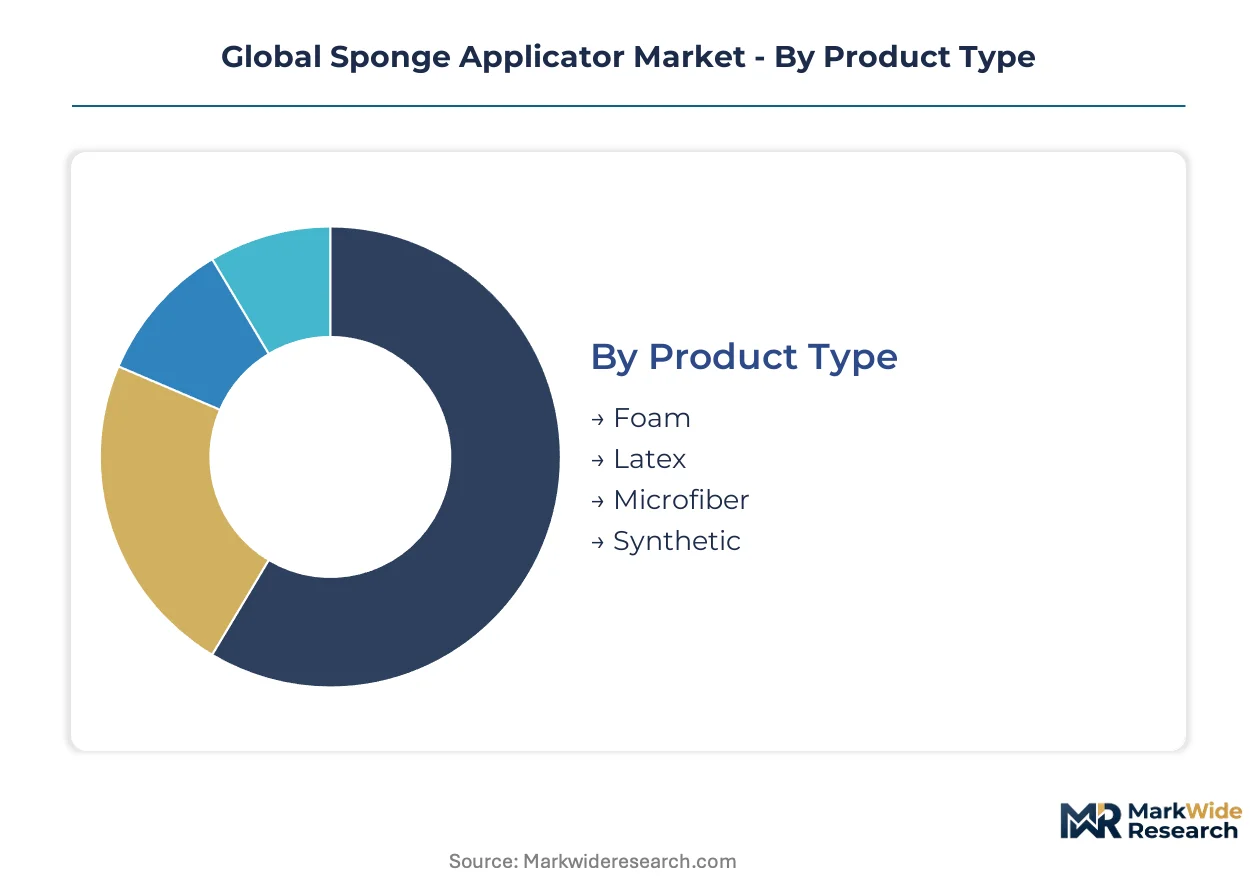
Segmentation in the sponge applicator market exposes divergent compliance burdens and margin profiles. Material composition determines REACH and FDA certification pathways, while end-use application shapes volume concentration and pricing power across channels.
Product Type:
REACH restrictions on isocyanate-based precursors and FDA color additive petitions create tiered certification loads across material categories. European manufacturers face SVHC dossier requirements for polyurethane foam lines, while natural latex triggers dermatological safety protocols in US professional channels.
- Foam:Open-cell polyurethane with 80-120 pores per inch dominates foundation blending applications. Demand concentrates in professional makeup artist kits across North America and Western Europe, where allergen sensitivity has displaced natural latex in premium positioning. REACH Annex XVII compliance costs squeeze converter margins.
- Synthetic:Silicone-infused hybrid structures combine compressibility with non-porous surface hygiene for client sanitation protocols. Korean beauty training academies and Los Angeles production studios drive adoption in the $15-plus unit tier. SAMR GB standard alignment accelerates Chinese domestic manufacturing scale.
- Microfiber:Dual-density construction with absorbent cores and streak-resistant surfaces.
- Latex:Legacy natural rubber formulations facing reformulation investments under FDA cosmetic safety guidance.
Foam sits at the top of the volume ranking, with synthetic climbing the fastest.
End User:
Cost tier stratification separates disposable mass-market consumption from reusable professional-grade procurement. Cosmetics channels absorb premium unit economics, while industrial applications prioritize volume contract pricing and standardized specifications.
- Cosmetics:Professional makeup artists and bridal services demand edgeless geometries and precision-molded densities. India's Bollywood production growth and South Korean K-beauty academies concentrate demand expansion. Direct-to-artist subscription models bypass traditional retailer slotting fees.
- Household:Cleaning applications favor cost-efficient disposable foam with lower pore density specifications. Zhejiang and Guangdong manufacturing clusters supply mass-market retail channels. Price sensitivity limits margin capture versus professional segments.
- Automotive:Controlled porosity for coating and finishing applications.
- Industrial:Standardized specifications for painting and surface treatment processes.
Cosmetics commands the steepest expansion trajectory, with household maintaining volume dominance.
Application:
Customer type fragmentation separates individual consumers from institutional procurement cooperatives. Professional makeup artists consolidate purchase authority through centralized negotiation, while retail channels serve fragmented individual demand.
- Makeup:Foundation and concealer application drives precision-molding requirements and proprietary edgeless designs. Department store beauty halls accelerate adoption curves versus mass-market drugstore channels. UV-cured lamination qualifies products for EU Green Deal procurement preferences.
- Cleaning:Household and industrial surface treatment applications prioritize absorbency and durability. Reusable microfiber composites capture margin pools where streak-free performance justifies higher unit prices. Solvent-free adhesive bonding eliminates VOC emissions.
- Painting:Automotive and industrial coating finish requirements.
- Personal Care:Skincare and hygiene applications with dermatological safety protocols.
Makeup leads volume concentration, with cleaning gaining share fastest in reusable segments.
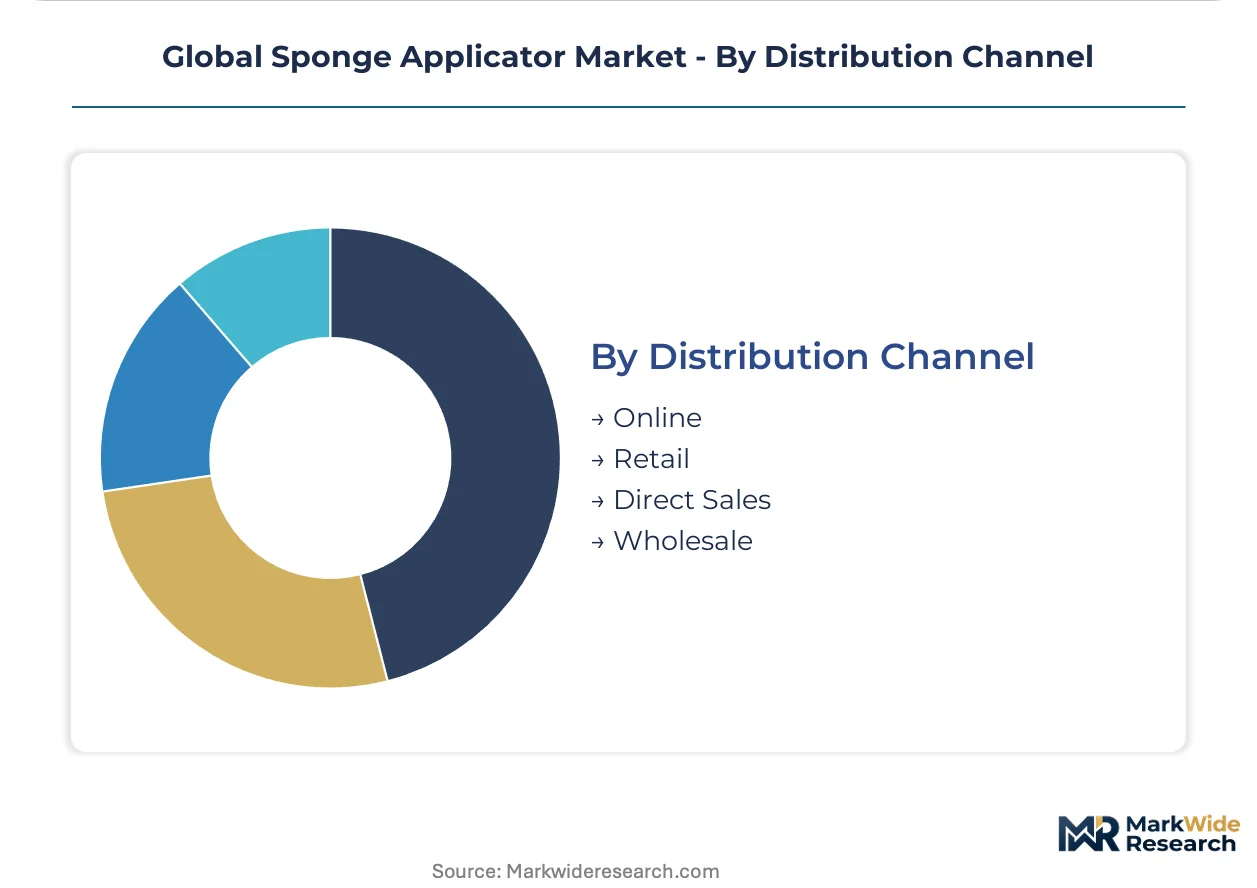
Distribution Channel:
Supply concentration in Chinese extrusion capacity shapes channel economics and geographic risk exposure. Captive foam production advantages concentrate among manufacturers with backward integration into raw material supply.
- Online:Specialized e-commerce platforms and direct-to-consumer models capture professional artist lifetime value. Monthly replenishment services lock in 24-month certification cycles for graduating Korean academy artists. Digital channels bypass fragmented individual purchasing patterns.
- Retail:Department store beauty halls and drugstore mass-market tiers stratify by price positioning. Slotting fees compress margins for non-differentiated foam converters. Three-tier pricing separates premium edgeless designs from standard geometries.
- Direct Sales:Annual volume contracts negotiated by artist cooperatives in London and Seoul.
- Wholesale:Industrial and automotive volume procurement through distributor networks.
Retail maintains volume leadership, with online expanding most quickly in professional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Guangdong provinces concentrate over sixty percent of global cosmetic-grade foam extrusion capacity, creating geographic risk exposure for brands without captive supply chains. Demand fragmentation across professional makeup, household cleaning, and industrial coating applications produces divergent regulatory compliance burdens by jurisdiction.
United States
Professional makeup artists in Los Angeles and New York drive premium edgeless sponge adoption for film production and bridal services. FDA cosmetic safety guidance tightens dermatological testing protocols for latex-containing formulations, forcing reformulation investments. Beautyblender anchors proprietary design positioning through direct-to-artist channels that bypass traditional retailer markups.
China
Domestic beauty consumption scales rapidly in Shanghai and Beijing, while manufacturing clusters in Zhejiang and Guangdong supply Korean and Japanese brand OEM contracts. SAMR alignment of GB standards with international cosmetic tool material norms reduces export certification friction for domestic foam converters. Local capacity expansion absorbs regional demand that previously relied on Japanese imports.
Germany
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent residues force supercritical CO2 foaming process adoption by 2027. Industrial applicator specialists in North Rhine-Westphalia and Bavaria respond through consortia arrangements to share toxicological testing burdens. Capital expenditure increases of twenty-five to thirty percent for extrusion line retrofits compress margins for non-captive manufacturers.
South Korea
K-beauty training academy networks in Seoul and Busan consolidate graduating artist procurement through pre-negotiated twenty-four-month supply agreements. MFDS cosmetic safety standards align with SAMR GB norms, enabling seamless cross-border sourcing from Chinese foam converters. Precision-molding expertise concentrates among legacy suppliers serving the professional channel.
India
Bollywood production growth in Mumbai and bridal service expansion in Delhi-NCR create first-mover advantage for edgeless sponge geometries priced below import parity. BIS cosmetic tool material standards remain under development, creating temporary regulatory ambiguity for foreign entrants. Domestic manufacturing capacity lags demand, preserving import dependence for premium professional-grade applicators.
Global Sponge Applicator Market Competitive Environment
Backward integration into captive foam production dominates the current landscape as manufacturers absorb REACH compliance costs internally. The vendor base stratifies between foam-captive specialists with in-house polyurethane extrusion and non-integrated brands dependent on third-party converters. Three archetypes define competitive positioning: chemistry-integrated manufacturers controlling raw material supply, precision-molding specialists leveraging Japanese or German equipment expertise, and design-centric brands commanding premium through proprietary geometries. Consolidation pressure concentrates among European foam converters facing capital-intensive solvent-free process transitions, while Asian manufacturers expand capacity to capture displaced volume.
Within the chemistry-integrated tier, Glocos International exemplifies captive foam production advantages that insulate margin structures from TDI and MDI feedstock volatility. Taiki Group anchors Japanese precision-molding expertise in cosmetic-grade sponge geometries, occupying a position where equipment specialization creates defensible product differentiation. Beautyblender sits within the design-centric archetype, representing proprietary edgeless positioning that commands professional channel premium pricing. These three companies illustrate how competitive advantage fragments between upstream material control, manufacturing precision, and brand-driven geometry innovation.
| Leading Market Players |
|---|
| Gilca |
| Glocos International |
| Taiki Group |
| Menshen |
| Brooklyn Products International |
| Real Techniques |
| Beautyblender |
| ECOTOOLS |
| Spectrum Laboratory Products |
| Others |
Value Chain & Pricing Dynamics
TDI and MDI feedstock volatility cascades through three pricing tiers as foam converters pass through crude oil-indexed cost swings to professional makeup artists, mass-market retailers, and industrial procurement officers with 90-120 day contract lags.
Pricing Analysis
Input-cost pass-through from isocyanate precursors compresses margins at foam converter tiers while premium edgeless designs absorb volatility through brand premium. Price differentiation rests on certification grade and volume scale, with REACH-compliant synthetic foam commanding premium positioning over legacy latex. Pricing pressure stems from Zhejiang and Guangdong manufacturing cluster competition in mass-market household segments. Professional makeup artist cooperatives exhibit lowest price sensitivity, while drugstore mass-market channels face acute cost compression.
Supply Chain Analysis
Dual-sourcing requirements from Korean and Japanese beauty brands mandate multi-supplier qualification across Zhejiang, Guangdong, and emerging Indian foam extrusion capacity. Raw material dependencies center on toluene diisocyanate, methylene diphenyl diisocyanate, and silicone elastomer feedstocks. Single-region concentration risk concentrates in China's eastern seaboard provinces, exposing non-captive brands to geographic disruption. Distribution runs through direct-to-artist subscription platforms, department store beauty halls, and industrial wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by professional makeup artist demand-shift toward silicone-infused hybrid foams with dermatological safety certification.
For Market Incumbents: Deploy captive foam production to insulate margin structures from TDI and MDI feedstock volatility threatening non-integrated competitors. Accelerate REACH Annex XVII compliance investments ahead of 2027 supercritical CO2 foaming mandates in Germany and France. Secure artist cooperative procurement contracts in Seoul and Los Angeles before channel disintermediation consolidates buying power.
For New Entrants and Emerging Players: Capture India's underpenetrated professional makeup channel where Bollywood production growth and bridal service expansion outpace domestic manufacturing capacity. Target solvent-free adhesive bonding capabilities for EU Green Deal procurement qualification. Pursue direct-to-artist subscription models that bypass retailer slotting fees and lock in 24-month certification cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where European foam converters face capital-intensive solvent-free process transitions without captive chemistry integration. Long-term viability favors backward-integrated manufacturers controlling polyurethane extrusion and precision-molding equipment specialization. Monitor REACH SVHC dossier preparation timelines as inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Extrusion | Captive TDI and MDI supply insulates Glocos International from feedstock volatility squeezing third-party converters. |
| Supercritical CO2 Foaming Transition | Eliminates N-methyl-2-pyrrolidone residues qualifying German manufacturers for REACH Annex XVII compliance. |
| Direct-to-Artist Subscription Launch | Beautyblender bypasses retailer markups while capturing professional makeup artist lifetime value in Los Angeles. |
| Solvent-Free Adhesive Bonding | UV-cured lamination eliminates VOC emissions qualifying microfiber composites for EU Green Deal procurement. |
| Precision-Molding Equipment Specialization | Taiki Group leverages Japanese equipment expertise to defend cosmetic-grade sponge geometry differentiation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foam converter plant managers, cosmetic brand procurement leads, professional makeup artist cooperative representatives, and REACH compliance officers with secondary validation through customs trade data, ECHA SVHC dossier filings, SAMR GB standard publications, and FDA cosmetic safety guidance documents. Bottom-up segment enumeration and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting across material composition, end-use application, and distribution channel dimensions drove analytical framework construction across the projection horizon. CAGRs derived from elasticity-adjusted demand modeling incorporating professional makeup artist kit replenishment cycles, K-beauty academy graduation rates, and industrial coating application growth. Forecast inputs included isocyanate precursor price indices and regulatory compliance timeline assumptions.
Underlying measurement precision varies by segment; synthetic foam and professional cosmetics channels carry tighter precision than household cleaning and industrial applications given data availability. Forecasts reflect assumptions regarding SAMR-REACH regulatory harmonization and solvent-free process adoption curves. Deviation in isocyanate feedstock price volatility or REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Metal Removal Fluids Market