
 Global Odor Control Systems Market | 2026-2036
Global Odor Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Odor Control Systems Market Intelligence
The US Environmental Protection Agency's National Emission Standards for Hazardous Air Pollutants (NESHAP) is realigning the cost-of-entry calculus for industrial operators. This forces investment in advanced systems beyond basic compliance. Evoqua Water Technologies LLC leverages its extensive portfolio in water and wastewater treatment applications. Meanwhile, CECO Environmental Corp. specializes in air quality and fluid handling solutions for diverse industrial clients.
Odor control systems are engineered solutions designed to capture, contain, and neutralize malodorous compounds from industrial and municipal air streams. These systems often utilize media like activated carbon with specific pore structures to adsorb volatile organic compounds (VOCs). While sewage treatment remains the dominant application sector, demand from the pulp & paper industry is accelerating. Within system types, biofiltration represents the fastest-growing segment due to its lower operating costs and sustainability profile compared to thermal oxidation.
Regulatory frameworks from bodies like the European Chemicals Agency (ECHA) and China's Ministry of Ecology and Environment (MEE) set stringent limits on industrial emissions. These rules directly influence technology selection and investment cycles for end users. Consequently, system manufacturers must navigate a complex patchwork of regional standards to ensure market access. The critical decision for buyers now revolves around balancing initial capital expenditure against long-term operational efficiency and regulatory compliance risk.
Market Dynamics
Stricter air quality regulations, like the EU's Industrial Emissions Directive, are the central force compelling operators to upgrade from basic odor masking to advanced neutralization technologies, altering investment priorities across industrial and municipal sectors.
Growth Catalysts
- Regulatory Mandates:The EU's Industrial Emissions Directive compels upgrades at industrial facilities, stimulating system retrofits to meet stricter air quality standards.
- Industrialization in China:Public health priorities drive municipal investment in wastewater and solid waste odor control infrastructure across China's industrializing regions.
- Pulp & Paper Sector Needs:The pulp and paper industry requires specialized systems to control sulfur compounds, creating specific demand for targeted chemical scrubbers.
Market Restraints
- High Capital Costs:The significant initial investment for systems like thermal oxidizers deters adoption, particularly among smaller industrial operators.
- Media Replacement Costs:Consumable media such as activated carbon requires frequent, costly replacement, impacting long-term operational expenditures for end-users.
- Regulatory Fragmentation:A complex patchwork of regional standards from bodies like the EPA and ECHA increases design complexity and compliance costs for manufacturers.
Strategic Opportunities
- Agricultural Applications:Underpenetrated agricultural sectors, specifically large-scale livestock and poultry operations, present a significant opportunity for odor abatement solutions.
- Smart System Integration:Integrating IoT sensors and analytics for predictive maintenance and real-time performance monitoring offers a new value proposition for system providers.
- Emerging Economies:Industrializing nations in Southeast Asia and Latin America represent new growth frontiers as environmental regulations begin to tighten.
Industry Challenges
- System Integration Complexity:Retrofitting modern odor control systems into older, existing industrial plants presents significant engineering and operational hurdles for facility managers.
- Specialized Skill Gaps:A scarcity of trained technicians and chemical engineers is a challenge for operating and maintaining complex biological or catalytic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Odor Control Systems Market |
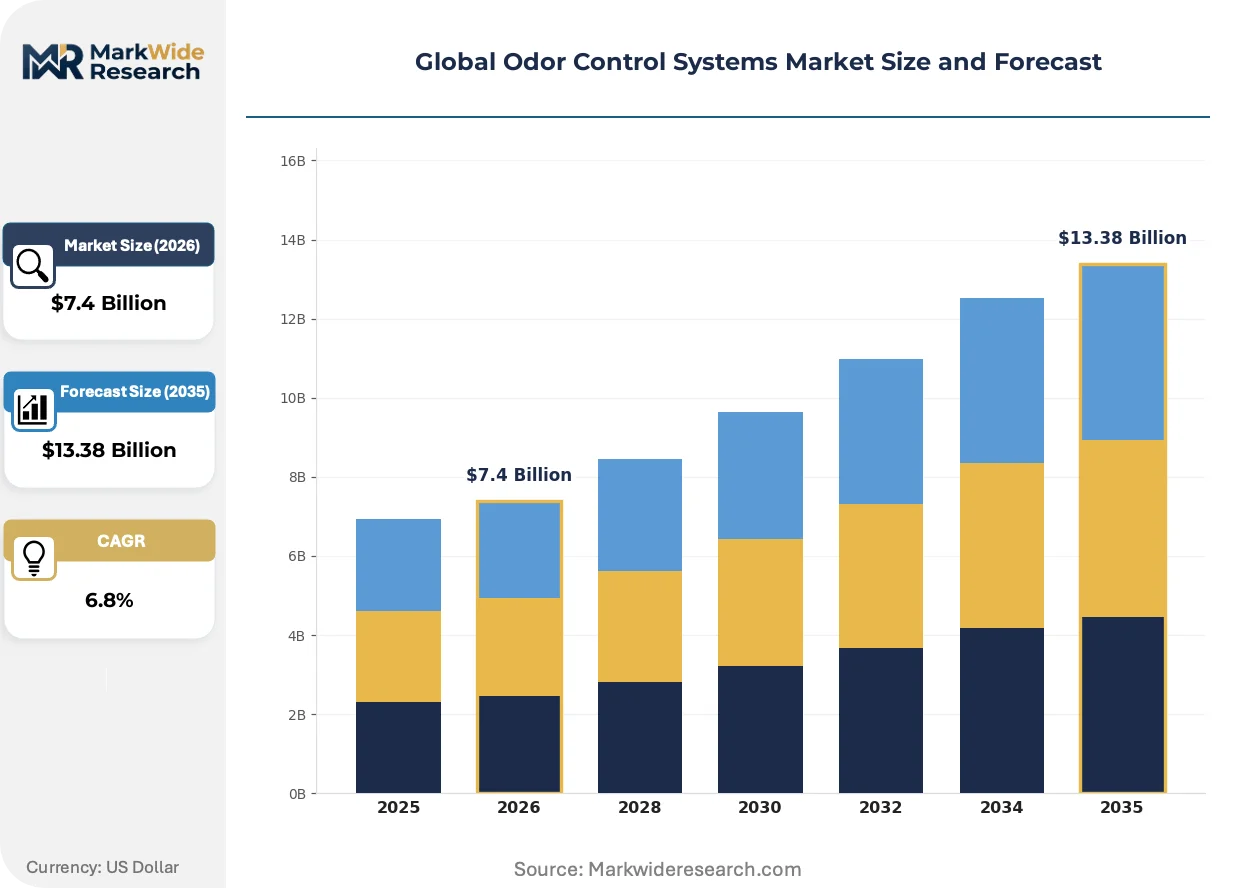
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Biofiltration, Chemical Scrubbing, Adsorption, Thermal Oxidation, Ozonation Technology: Activated Carbon, Wet Scrubber, UV Oxidation, Electrostatic Precipitator, Photocatalytic Oxidation Application Sector: Sewage Treatment, Pulp & Paper, Food Processing, Waste Management, Chemical Manufacturing End User: Municipal Facilities, Industrial Plants, Waste Disposal Units, Commercial Establishments, Agricultural Sites |
| Companies Covered | Evoqua Water Technologies LLC, MANN+HUMMEL, Veolia Environnement S.A., Anguil Environmental Systems, Inc., CECO Environmental Corp., Ecolab Inc., Durr Group, BioAir Solutions, LLC, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Odor Control Systems Market Strategic Shifts & Innovations
Market evolution is defined by a move toward proactive, intelligent systems. This transition prioritizes sustainable performance and real-time data over passive, compliance-only odor management strategies, reflecting a deeper operational integration.
Advanced electrochemical oxidation systems utilize electricity to generate reactive oxygen species directly in the air stream, neutralizing odor compounds without chemical additives. Food processing facilities and microelectronics fabrication plants are adopting these systems for their precision and residue-free operation. This technology is electrifying the field of air treatment, shifting focus from consumable media to durable, electrically-driven abatement solutions.
The US Environmental Protection Agency's National Emission Standards for Hazardous Air Pollutants (NESHAP) imposes stringent limits on specific volatile organic compounds. This regulation compels industrial sites to move beyond general odor masking and implement technologies that can verifiably destroy targeted chemical compounds. Refineries and chemical manufacturing operations are most affected, often upgrading from carbon adsorbers to more effective thermal oxidation systems to ensure compliance.
End-users are increasingly seeking service-based contracts that bundle equipment, media replacement, maintenance, and performance guarantees into a single operational fee. This model challenges the traditional capital equipment sales cycle, forcing manufacturers to develop robust after-sales service divisions. This shift is most prominent within the municipal wastewater sector, where public utilities favor predictable operational expenditures over large, intermittent capital outlays.
Global Odor Control Systems Market Segmentation
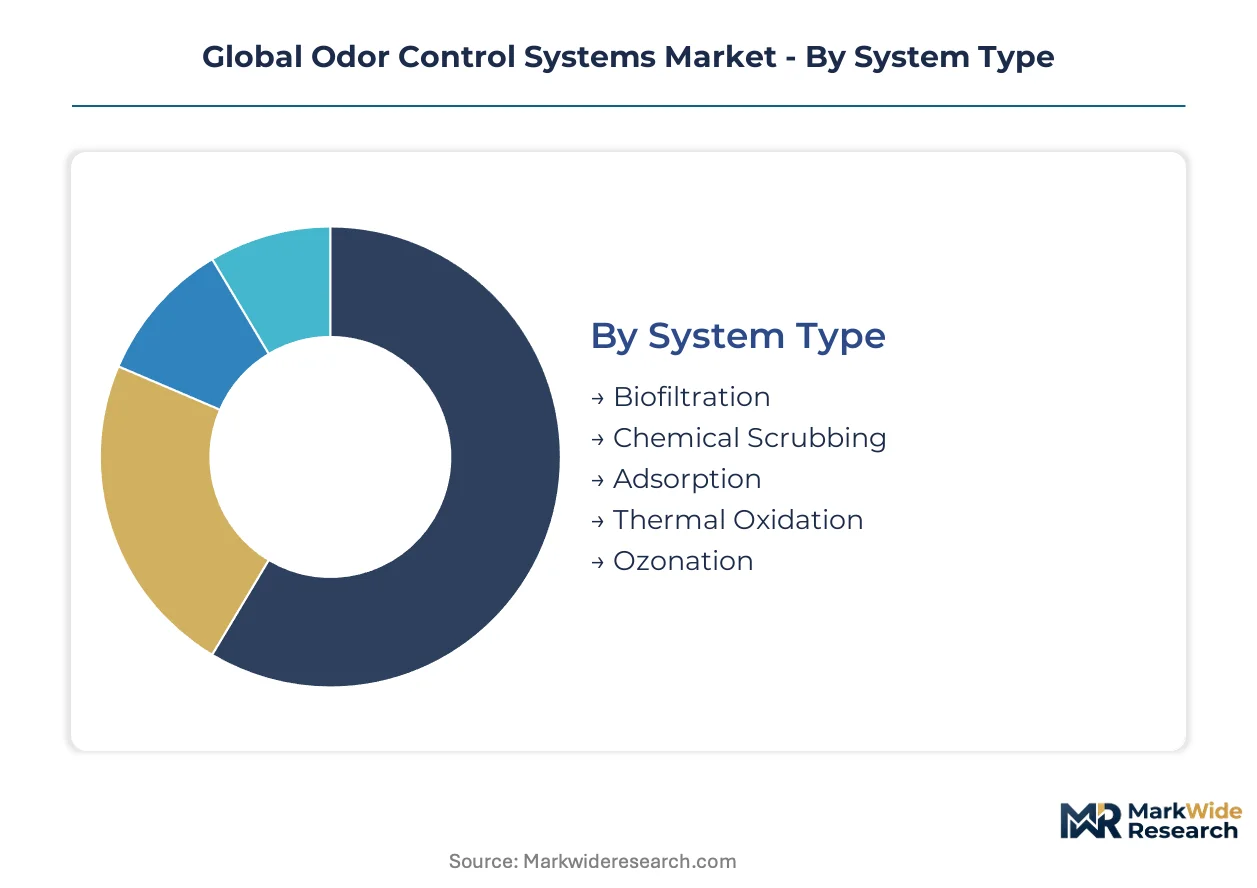
The Global Odor Control Systems Market exhibits varied demand patterns influenced by operational requirements and regulatory pressures. Understanding these distinct segments allows manufacturers to tailor solutions and identify specific growth pockets. This detailed segmentation illuminates the diverse landscape of odor abatement.
System Type:
Industrial and municipal buyers prioritize specific odor control system types based on emission characteristics and regulatory compliance mandates.
- Biofiltration:These systems utilize microorganisms immobilized on a filter bed to biologically degrade volatile organic compounds (VOCs) and malodorous gases. Demand concentrates in municipal wastewater treatment facilities due to their lower operating costs and sustainable profile.
- Thermal Oxidation:Thermal oxidizers destroy odor-causing compounds by heating air streams to high temperatures, converting pollutants into less harmful substances. Refineries and chemical manufacturing operations adopt these systems for stringent compliance with US NESHAP regulations.
- Chemical Scrubbing:Chemical scrubbers remove pollutants from air streams through absorption into a liquid, often used for specific sulfur compounds in the pulp and paper industry.
- Adsorption:Adsorption systems, typically using activated carbon, capture odor molecules on the surface of a porous solid, finding application in diverse industrial settings.
- Ozonation:Ozonation employs ozone as a powerful oxidant to neutralize odor compounds, particularly effective in rendering plants and food processing.
Volume sits with Adsorption; growth tilts toward Biofiltration.
Technology:
The choice of odor control technology directly correlates with the specific chemical nature of pollutants and the required removal efficiency for a given application.
- Activated Carbon:Activated carbon filters utilize highly porous carbon media to adsorb a broad spectrum of volatile organic compounds and other odorants from air streams. Industrial plants and waste management facilities drive demand, valuing its versatility for various pollutant types.
- Wet Scrubber:Wet scrubbers remove particulate matter and gaseous pollutants by contacting the contaminated air stream with a scrubbing liquid, often used in chemical manufacturing and pulp & paper for acid gas removal. Demand in chemical manufacturing facilities is significant due to their ability to handle corrosive gases.
- UV Oxidation:UV oxidation systems use ultraviolet light to break down odor-causing molecules, finding niche applications in smaller-scale air purification.
- Electrostatic Precipitator:Electrostatic precipitators remove fine particulate matter from air streams using electrostatic force, primarily in industrial exhaust systems.
- Photocatalytic Oxidation:Photocatalytic oxidation employs UV light and a catalyst to oxidize organic pollutants, gaining traction in indoor air quality applications.
Activated Carbon technology sees widespread market adoption, while Photocatalytic Oxidation is climbing the fastest.
Application Sector:
Different application sectors face unique odor challenges and regulatory pressures, influencing their investment in specialized abatement solutions.
- Sewage Treatment:Sewage treatment plants generate significant malodors from hydrogen sulfide and other compounds, necessitating robust odor control systems for public health and environmental compliance. Municipal facilities in rapidly urbanizing regions like China are a primary demand source due to increasing wastewater volumes.
- Waste Management:Waste management facilities, including landfills and composting sites, produce diverse odor emissions from decomposing organic matter, driving demand for advanced biofiltration and chemical scrubbing. Stricter air quality mandates from bodies like the US EPA compel these facilities to upgrade their existing infrastructure.
- Pulp & Paper:The pulp and paper industry requires specialized systems to control sulfur compounds and other process-related odors.
- Food Processing:Food processing facilities implement odor control to manage emissions from cooking, fermentation, and waste, ensuring local air quality.
- Chemical Manufacturing:Chemical manufacturing operations deploy advanced odor control to mitigate emissions of volatile organic compounds and hazardous air pollutants.
Sewage Treatment commands the largest share of investment, with Waste Management showing a steep expansion trajectory.
End User:
End-user segments vary significantly in their operational scale and complexity of odor management needs, dictating system capacity and technology choices.
- Industrial Plants:Industrial plants, encompassing chemical manufacturing, refineries, and food processing, require tailored odor control solutions to meet specific process emission profiles and strict environmental permits. Regulatory frameworks from the European Chemicals Agency (ECHA) directly influence technology selection for these operators.
- Municipal Facilities:Municipal facilities, primarily wastewater treatment plants and public waste collection sites, represent a large-scale end-user segment driven by public health concerns and local air quality regulations. Investment in China's industrializing regions is particularly pronounced as municipal odor control becomes a public health priority.
- Waste Disposal Units:Waste disposal units, such as landfills and transfer stations, implement odor control to manage emissions from decomposing waste.
- Commercial Establishments:Commercial establishments, including restaurants and hotels, use smaller-scale odor control systems for indoor air quality and localized exhaust.
- Agricultural Sites:Agricultural sites, especially large-scale livestock operations, are an underpenetrated sector presenting significant opportunity for odor abatement solutions.
Industrial Plants represent a significant market segment, while Agricultural Sites are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapidly industrializing regions, particularly those designated for economic development, drive significant demand for odor control systems. Public health priorities in these zones compel substantial municipal investment in wastewater and solid waste infrastructure. This focus on environmental compliance reshapes regional market dynamics.
China
Demand drivers: Rapid urbanization and industrial expansion necessitate extensive odor control in municipal and industrial settings. China's Ministry of Ecology and Environment (MEE) sets stringent emission standards for various industries. In the Yangtze River Delta, cities like Shanghai are investing heavily in advanced wastewater treatment facilities to mitigate urban air pollution.
United States
The United States sees demand from stricter air quality mandates for waste management facilities and compliance with specific industrial emission regulations. The US Environmental Protection Agency's (EPA) NESHAP compels industrial sites to upgrade to advanced abatement technologies. Refineries along the Gulf Coast, particularly in Texas, are adopting thermal oxidation systems to meet stringent VOC destruction requirements.
Germany
Industrial facilities in Germany require system upgrades to comply with rigorous European Union environmental directives. The EU's Industrial Emissions Directive mandates advanced pollution control technologies across diverse industrial sectors. Chemical manufacturing hubs in North Rhine-Westphalia are investing in biofiltration and chemical scrubbing to manage complex process emissions.
India
Expanding industrial bases and growing urban populations necessitate improved odor management in municipal and industrial waste streams. India's Central Pollution Control Board (CPCB) introduces stricter guidelines for industrial and municipal effluent treatment. In the Delhi-NCR region, new waste-to-energy plants are integrating advanced odor control solutions to address public health concerns.
France
Public utilities in France prioritize sustainable odor control solutions for wastewater treatment plants and composting facilities. National environmental codes, influenced by the European Chemicals Agency (ECHA), govern industrial emissions and waste management practices. Metropolitan areas like Paris are implementing smart odor monitoring systems in their sewage networks to optimize abatement strategies.
Global Odor Control Systems Market Key Industry Players
United States producers anchor one tier of the odor control systems market; European specialists hold significant positions in advanced environmental technologies. The market exhibits a tiered structure, with large diversified environmental solutions providers coexisting with specialized air quality firms. Strategic archetypes include integrated water and wastewater treatment companies, dedicated air pollution control manufacturers, and niche technology innovators. Many companies engage in portfolio diversification and strategic partnerships to expand their global reach.
Within the diversified environmental solutions tier, Evoqua Water Technologies LLC, a US-based entity, represents a major player with extensive water and wastewater treatment applications. Veolia Environnement S.A., a French public limited company, exemplifies broad environmental services, including odor control. CECO Environmental Corp., another US-based corporation, anchors the specialized air quality and fluid handling segment, serving diverse industrial clients. These entities leverage their established portfolios and global presence to address complex odor abatement challenges across multiple sectors.
| Leading Market Players |
|---|
| Evoqua Water Technologies LLC |
| MANN+HUMMEL |
| Veolia Environnement S.A. |
| Anguil Environmental Systems, Inc. |
| CECO Environmental Corp. |
| Ecolab Inc. |
| Durr Group |
| BioAir Solutions, LLC |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
Activated carbon spot prices, influenced by global commodity markets for raw materials like coconut shells and coal, cascade through the odor control system supply chain into tiered product and service offerings for end-users.
Pricing Analysis
Premium pricing for short lead times drives immediate procurement decisions for critical system components. Project-based contracts dominate, with pricing heavily influenced by the customization level required for industrial applications. Price differentiation emerges from performance guarantees and the extent of after-sales service bundling. Pricing pressure stems from the high initial capital investment for advanced systems, particularly impacting smaller industrial operators. The municipal sector often exhibits lower price sensitivity for upfront capital, favoring predictable operational expenditures over the long term.
Supply Chain Analysis
Domestic content mandates in regions like the European Union are reshaping the sourcing of key components and media. Supply concentration for activated carbon filters primarily resides with manufacturers in China and specialized producers in Europe. The market relies on a steady supply of specialized chemical reagents for scrubbers and biofiltration media. Single-source vulnerability for advanced sensor components presents a structural risk. Distribution runs through direct sales channels to large industrial and municipal clients, supplemented by specialized distributors serving smaller commercial establishments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race, with players pursuing control over both specialized media production and comprehensive service delivery.
For Market Incumbents:Deploy bundled service contracts to secure recurring revenue streams and deepen client relationships within the municipal wastewater sector. Invest in R&D for advanced biofiltration media and electrochemical oxidation systems to counter emerging technology threats. Expand global service divisions, particularly in industrializing regions, to meet the growing demand for complex system maintenance. Leverage existing client bases to cross-sell upgrades to meet evolving regulatory standards.
For New Entrants and Emerging Players:Begin with niche technology solutions, such as photocatalytic oxidation, targeting underpenetrated sectors like large-scale agricultural operations. Focus on specific regional markets in Southeast Asia where environmental regulations are tightening but competition remains less entrenched. Offer modular, easily scalable systems that reduce initial capital outlay for small and medium-sized industrial clients. Develop strong sustainability profiles to appeal to environmentally conscious buyers.
For Investors and Strategic Acquirers:Distressed-cycle entries favor acquirers with strong balance sheets in the European and North American markets. Long-term viability is robust, driven by persistent regulatory enforcement and public health imperatives over the projection horizon. Target specialized technology firms in biofiltration or smart system integration to gain intellectual property and market share. The signal to watch is a consolidation trend among regional service providers, indicating readiness for larger-scale integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increased production of biofiltration media supports sustainable technology adoption in municipal facilities. |
| Long-term Supply Agreement | Securing activated carbon supply mitigates commodity price volatility for adsorption system manufacturers. |
| Joint Venture | Partnering for smart system integration enhances predictive maintenance capabilities for industrial end-users. |
| Acquisition of Specialist Firm | Gaining electrochemical oxidation technology expands offerings for precision air treatment applications. |
| Service Division Expansion | Strengthening after-sales support builds customer loyalty and ensures system uptime for public utilities. |
Research Approach
European Union Industrial Emissions Directive documents, US EPA NESHAP guidelines, and China MEE reports formed the secondary backbone, supplemented by trade publications and corporate filings. Primary research involved interviews with wastewater treatment plant managers, industrial environmental compliance officers, chemical engineers, and odor control system manufacturers. This comprehensive approach ensured a robust understanding of market dynamics through bottom-up and top-down triangulation.
Historical trendline analysis established foundational growth patterns across the analysis window. The analytical framework modeled market evolution across system type (biofiltration, thermal oxidation), technology (activated carbon, wet scrubber), application sector (sewage treatment, waste management), end-user (industrial plants, municipal facilities), and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived by extrapolating historical trends and integrating anticipated regulatory changes and industrial expansion rates in China.
Underlying measurement precision varies by segment; sewage treatment and waste management carry tighter precision than others due to more standardized reporting. Forecasts reflect assumptions regarding future regulatory enforcement levels and technological advancements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market