
 Heat Shrink Tubes Market | 2026-2036
Heat Shrink Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Tubes Market Foresight
Modular kit configurations for wire harness protection is pivoting procurement patterns toward bundled tubing assortments with color-coded sizing. TE Connectivity leverages its cross-continental manufacturing footprint to supply standardized kits to tier-one automotive harness suppliers. Sumitomo Electric Industries anchors its position through captive resin compounding operations in Japan and Thailand. HellermannTyton differentiates by dominating the channel for distributor-packaged assortments targeting MRO and contractor segments.
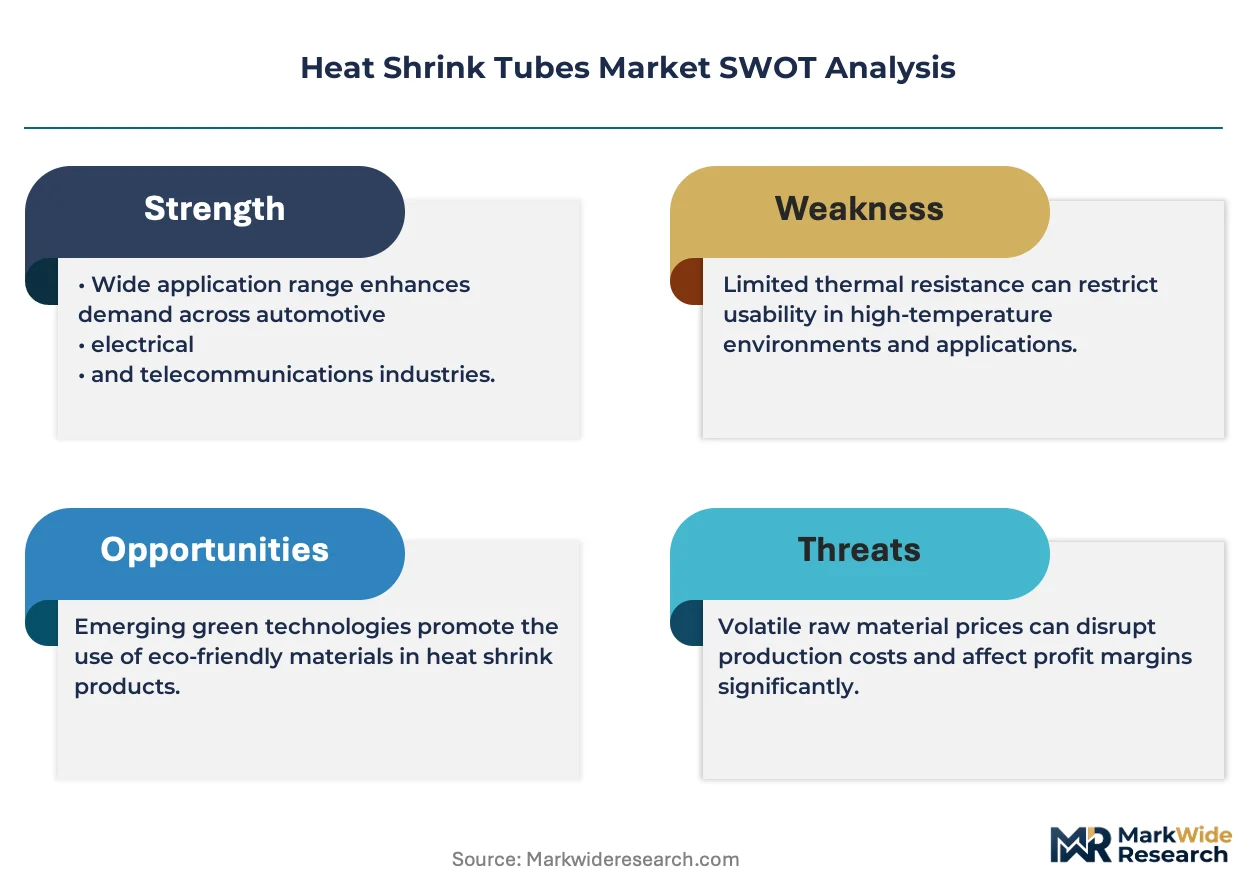
Heat shrink tubes are cross-linked polymeric sleeves, typically manufactured from irradiated polyolefin or fluoropolymer substrates, that contract radially when exposed to heat above their crystalline melting point to form tight environmental seals around substrates. Their primary purpose is to provide electrical insulation, strain relief, and mechanical protection for conductors, terminals, and splices in harsh operating environments. Polyolefin formulations lead volume shipments due to cost-performance balance across general-purpose electrical applications, while fluoropolymer grades command premium positioning in aerospace and chemical-processing end uses where temperature extremes and solvent resistance justify higher unit economics. The automotive end-user segment is expanding fastest as high-voltage EV platforms multiply connection points requiring insulation rated above 600 volts.
UL 224 standards in the United States, the EU's RoHS directive restricting hazardous substances in electrical equipment, and China's GB/T 2408 flammability ratings collectively shape material selection, testing protocols, and market access conditions for tubing suppliers. REACH registration requirements in Europe further constrain additive packages used in halogen-free flame-retardant formulations, elevating compliance costs for non-European exporters. Stakeholders must monitor evolving battery safety regulations in major automotive production jurisdictions to anticipate specification shifts for high-voltage insulation materials.
Market Dynamics
Automotive electrification is compressing specification cycles for high-voltage insulation materials, forcing tubing suppliers to synchronize R&D calendars with EV platform launches rather than traditional aftermarket replacement schedules.
Growth Catalysts
- GB/T 2408 flame-retardant mandates:China's upgraded flammability ratings for electrical components are accelerating halogen-free formulation investments across Asian resin compounders.
- EV battery pack architectures:High-voltage platforms above 600 volts multiply connection points requiring dual-wall tubing with enhanced dielectric strength.
- Germany's automotive cable assembly corridor:OEM specification power concentrates procurement authority with certified suppliers serving Wolfsburg, Stuttgart, and Munich production clusters.
Market Restraints
- Polyolefin resin price volatility:Feedstock ethylene and propylene fluctuations compress margin predictability for irradiation processors.
- REACH additive restrictions:ECHA constraints on phosphorus-based flame retardants limit formulation flexibility for European exporters.
- Silicone cold-shrink alternatives:Tool-free installation advantages threaten medium-volume electrical contracting applications.
Strategic Opportunities
- India's transmission infrastructure buildout:Grid modernization under CEA directives creates specification openings for medium-wall utility-grade tubing.
- RoHS compliance as competitive filter:Halogen-free certification requirements in EU markets disadvantage non-compliant Asian exporters.
- Smart factory integration:IoT-enabled heat guns with temperature feedback loops enable precision installation in aerospace wire harness shops.
Industry Challenges
- Irradiation technician scarcity:Electron beam operation expertise concentrates at aging facilities in Japan and the United States.
- UL 224 certification timelines:Extended third-party testing cycles delay product launches for automotive harness suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Tubes Market |
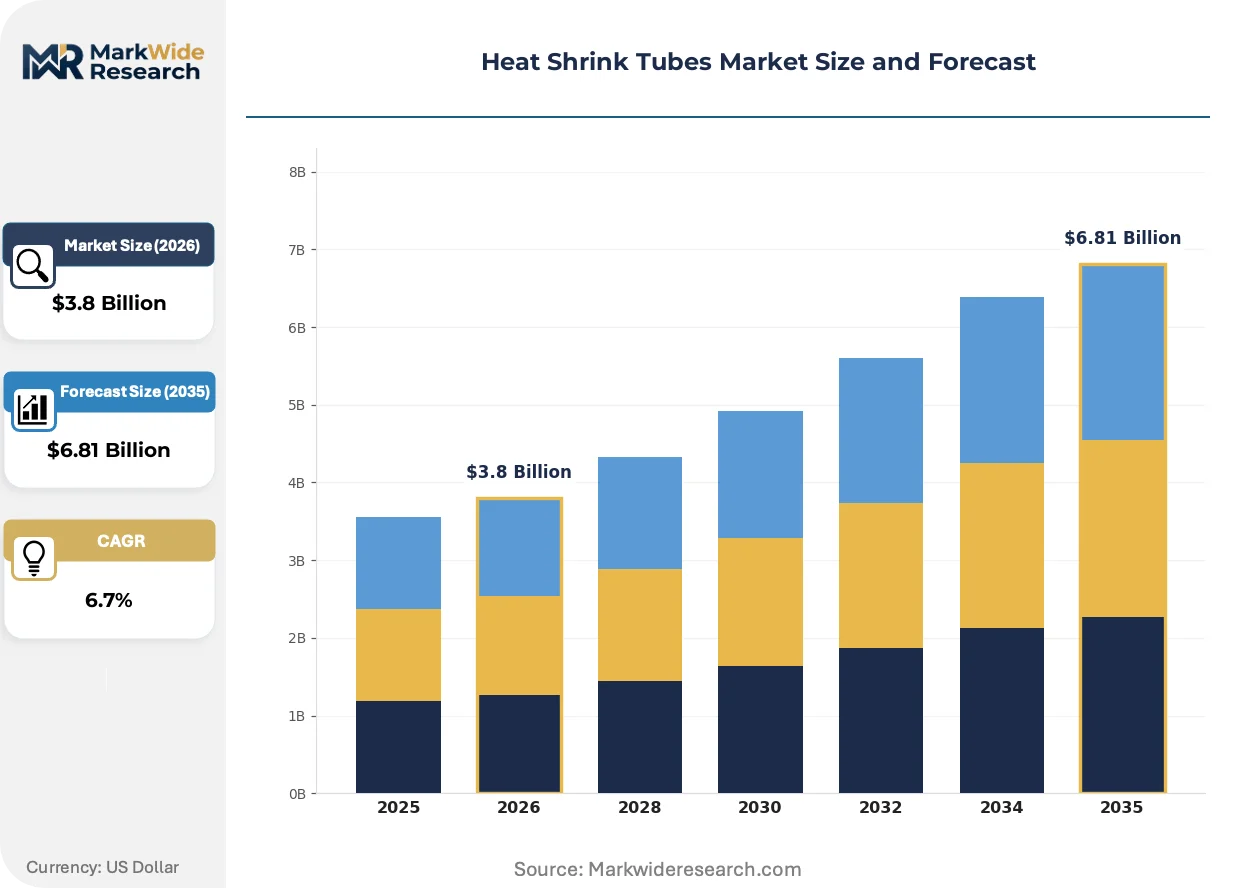
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, Fluoropolymer, Elastomer Application: Electrical Insulation, Mechanical Protection, Bundling, Marking End User: Telecommunications, Automotive, Consumer Electronics, Aerospace Size: Small, Medium, Large, Custom |
| Companies Covered | 3M, TE Connectivity, Sumitomo Electric Industries, ABB, HellermannTyton, Alpha Wire, Panduit, Qualtek Electronics, Zeus Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Tubes Market Shifts & Advancements
Material science advances and installation automation are compressing the gap between commodity polyolefin tubing and performance-grade fluoropolymer solutions across multiple end-use verticals.
Dual-wall adhesive-lined constructions are unifying environmental sealing and mechanical strain relief into single-installation components. Automotive tier-one suppliers specify these for under-hood harness protection in hybrid platforms. The technology is unifying previously separate procurement categories of tubing and potting compounds into consolidated bills of material.
REACH registration requirements for novel flame-retardant additives are elevating compliance documentation burdens for non-European compounders. Suppliers must reformulate halogen-free packages without restricted phosphorus esters to maintain market access. Asian exporters to Germany's automotive sector face the steepest adaptation costs.
Kit-based procurement models are displacing single-SKU purchasing for MRO and contractor segments. Distributor-packaged assortments with color-coded diameter ranges reduce field selection errors and inventory carrying costs. This pattern concentrates most visibly in North American electrical wholesale channels serving commercial construction.
Heat Shrink Tubes Market Segmentation
Heat shrink tube procurement diverges sharply between specification-driven automotive harness contracts and price-sensitive MRO distributor channels. Understanding where customization premiums apply versus where commodity grades dominate purchasing decisions separates margin capture from volume erosion.
Product Type:
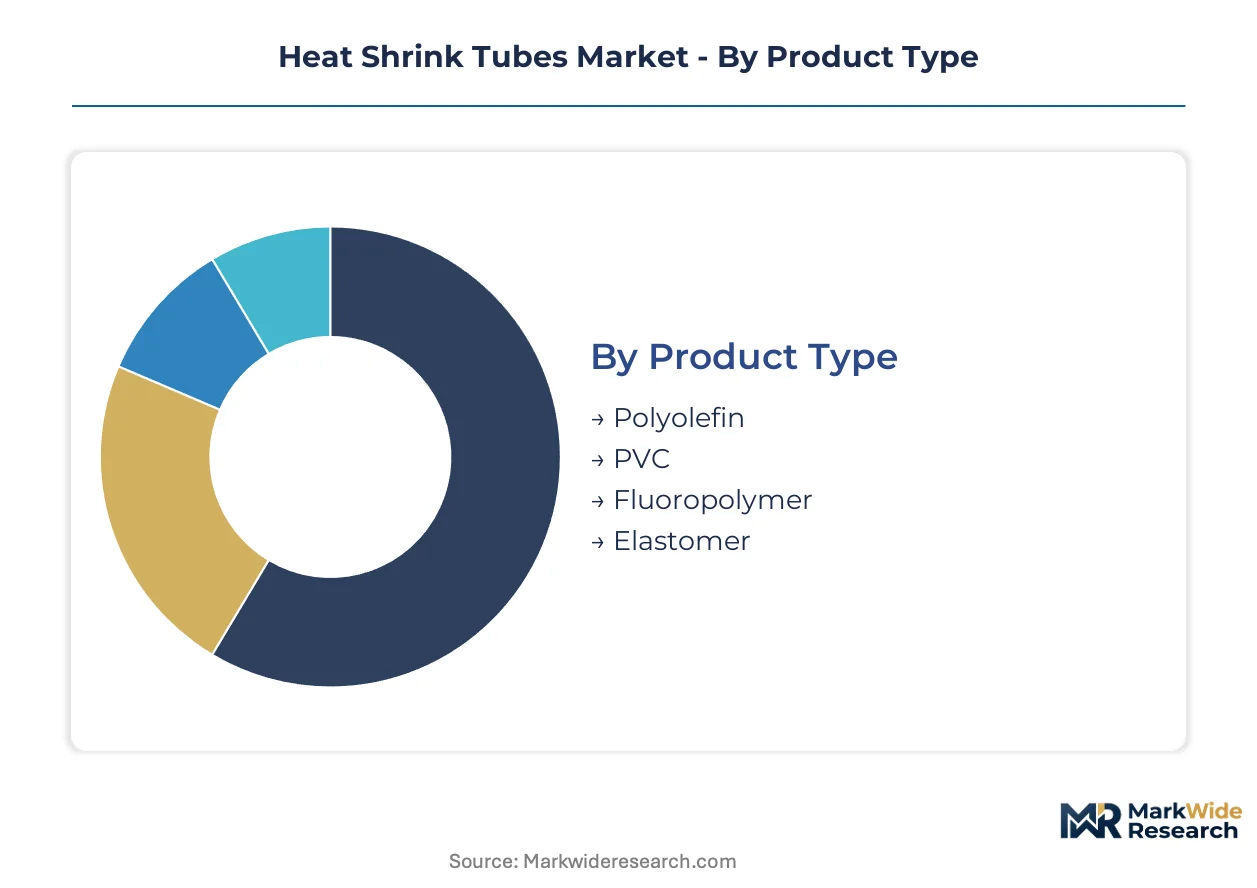
Customization depth spans from off-the-shelf irradiated polyolefin to fluoropolymer grades engineered for specific chemical resistance profiles.
- Polyolefin:Irradiated cross-linked formulations deliver the cost-performance balance that dominates general-purpose electrical applications. Automotive wire harness manufacturers in Germany's Stuttgart corridor specify medium-wall grades for EV battery pack protection under GB/T 2408 flame-retardant protocols.
- Fluoropolymer:PTFE and FEP substrates withstand temperature extremes from minus 200 to plus 260 degrees Celsius alongside aggressive solvent exposure. Aerospace wire harness shops in Toulouse and Seattle pay formulation premiums for FAR 25.853 compliant grades that polyolefin cannot match.
- PVC:Plasticized formulations serve low-temperature flexibility requirements in consumer electronics cable management where cost minimization overrides longevity.
- Elastomer:Silicone-modified constructions accommodate extreme flex cycling in robotics and industrial automation umbilicals.
Most installed capacity flows through Polyolefin. Expansion is steepest in Fluoropolymer.
Application:
Functional requirements determine whether single-wall commodity tubing suffices or dual-wall adhesive-lined constructions command specification.
- Electrical Insulation:Dielectric strength ratings above 600 volts separate EV-qualified grades from standard industrial inventory. High-voltage platform architectures multiply connection points requiring certified insulation across automotive production clusters.
- Mechanical Protection:Abrasion-resistant outer layers and environmental sealing against moisture ingress protect under-hood harnesses in hybrid powertrains. Dual-wall constructions unify previously separate tubing and potting compound procurement categories.
- Bundling:Color-coded diameter assortments reduce field selection errors in commercial construction electrical contracting.
- Marking:Pre-printed identification sleeves streamline harness assembly traceability in aerospace and defense applications.
Electrical Insulation commands the specification premium. Mechanical Protection is gaining share fastest as adhesive-lined technology displaces multi-component sealing approaches.
End User:
Customer concentration varies from fragmented MRO distributor networks to consolidated tier-one automotive harness procurement.
- Automotive:OEM specification power concentrates authority with certified suppliers serving Wolfsburg, Stuttgart, and Munich production corridors. High-voltage EV platforms above 600 volts are compressing specification cycles and forcing R&D calendar synchronization.
- Aerospace:AS23053 qualified grades and FAR 25.853 flammability compliance create qualification barriers that insulate incumbent suppliers. Boeing and Airbus harness shops demand lot traceability and material certification documentation.
- Telecommunications:Fiber optic cable protection and copper network infrastructure maintenance drive volume through distributor-packaged assortments.
- Consumer Electronics:Price-sensitive cable management applications prioritize PVC formulations with minimal wall thickness.
Automotive absorbs the most specification engineering resources. Aerospace maintains the steepest margin premiums.
Size:
Dimensional standardization enables kit-based procurement models while custom extrusions serve specialized industrial applications.
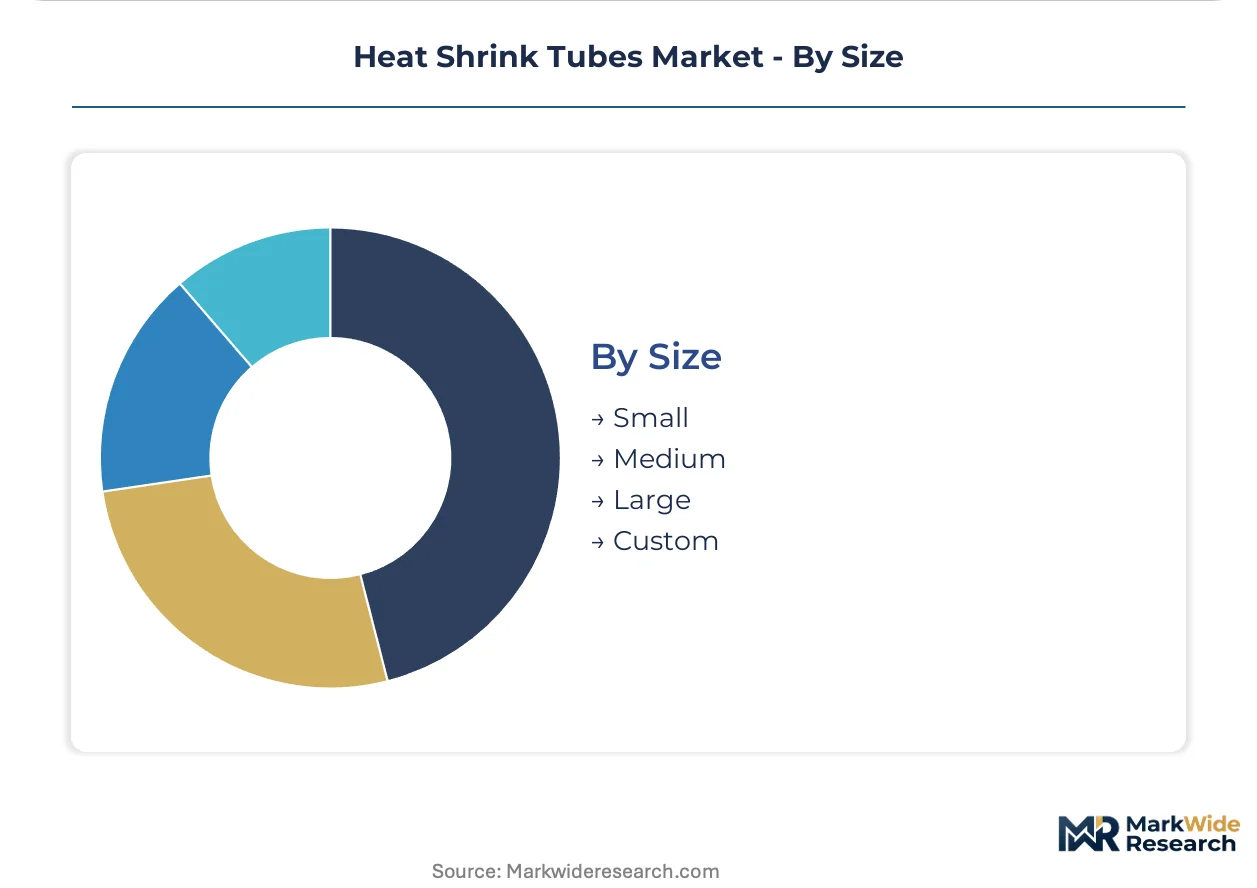
- Medium:Diameter ranges from 6mm to 25mm dominate automotive wire harness protection and electrical panel builds. TE Connectivity and Sumitomo Electric Industries anchor procurement volumes through standardized kit configurations.
- Small:Sub-6mm diameters serve micro-electronics, sensor wiring, and medical device applications where precision shrinking matters.
- Large:Above-25mm constructions protect heavy-cable industrial power distribution and marine umbilical systems.
- Custom:Non-standard diameters and dual-wall thickness profiles accommodate specialized chemical processing and oilfield equipment.
Medium sizes carry the highest shipment volumes. Custom specifications extract the widest margin spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat shrink tube manufacturing first scaled in post-war Japan and the United States through electron beam irradiation facilities serving military and aerospace wire harness demands. Production lineage now traces through three continents where automotive electrification and infrastructure buildouts concentrate procurement authority.
United States
Defense aerospace programs and data center power distribution sustain demand for high-performance fluoropolymer grades. FAA certification requirements for commercial aircraft wiring create qualification barriers that insulate incumbent suppliers serving Boeing's Seattle-area harness shops. UL 224 testing protocols administered by third-party laboratories in the Midwest extend product launch timelines for automotive tier-one suppliers.
Germany
Volkswagen's Wolfsburg complex and BMW's Munich production corridors specify certified tubing for 800-volt EV architectures. REACH restrictions on phosphorus-based flame retardants administered by ECHA force reformulation investments among Asian exporters seeking automotive qualification. Stuttgart's tier-one harness suppliers synchronize R&D calendars with platform launch cycles rather than aftermarket replacement schedules.
China
State Grid transmission infrastructure buildouts and domestic EV battery pack production multiply procurement volumes for medium-wall polyolefin constructions. GB/T 2408 flammability ratings upgraded by SAMR redirect formulation strategies toward halogen-free compounds across resin compounders in the Yangtze River Delta. BYD and CATL production facilities in Shenzhen and Ningbo specify certified insulation for high-voltage connection points.
Japan
Captive resin compounding operations anchor supply security for automotive harness manufacturers serving Toyota and Nissan platforms. METI industrial standards and JIS certification protocols maintain quality benchmarks that constrain price-based competition. Electron beam irradiation expertise concentrates in aging facilities around Nagoya and Osaka, creating technician scarcity risks for capacity expansion.
India
Central Electricity Authority directives on grid modernization create specification openings for utility-grade tubing in transmission infrastructure. Domestic automotive cable assembly plants serving Maruti Suzuki and Tata Motors import certified grades while local compounders invest in halogen-free formulation capability. Maharashtra and Gujarat industrial corridors concentrate demand from electrical panel builders and renewable energy project developers.
Heat Shrink Tubes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and captive resin supply. The vendor base organizes into three tiers: multinational electrical component conglomerates with cross-continental manufacturing footprints; mid-scale specialists with backward integration into compounding operations; and distributor-packaged assortment providers serving fragmented MRO channels. Consolidation pressure operates through automotive qualification requirements that favor incumbent suppliers with existing platform approvals. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves as suppliers position for EV platform procurement cycles.
Within the multinational tier, 3M and TE Connectivity occupy positions defined by standardized kit configurations and cross-regional supply security. Sumitomo Electric Industries exemplifies the captive-compounding archetype through in-house resin operations in Japan and Thailand. Among channel-focused specialists, HellermannTyton sits within the distributor-packaged assortment segment targeting contractor and maintenance-repair-overhaul procurement patterns.
| Leading Market Players |
|---|
| 3M |
| TE Connectivity |
| Sumitomo Electric Industries |
| ABB |
| HellermannTyton |
| Alpha Wire |
| Panduit |
| Qualtek Electronics |
| Zeus Industrial Products |
| Others |
Supply & Pricing Matrix
Ethylene and propylene feedstock volatility propagates from Asian petrochemical complexes through irradiation processors to tier-one automotive harness suppliers, compressing margin predictability at each pricing tier downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer aerospace grades from polyolefin automotive certifications and PVC consumer electronics inventory. Price differentiation centers on UL 224 certification depth and captive resin compounding capability. Cost compression in commodity polyolefin grades is intensifying because of spot resin volatility and silicone cold-shrink substitution threats. MRO distributor channels exhibit the steepest price sensitivity; aerospace wire harness shops absorb the widest formulation premiums.
Supply Chain Analysis
Container freight rates from Yangtze River Delta ports to Hamburg and Long Beach directly impact landed costs for Asian compounders serving European and North American automotive corridors. Manufacturing gravity concentrates in China, Japan, and Germany, with captive electron beam irradiation facilities anchoring supply security for tier-one harness suppliers. Raw material sourcing draws from Saudi and US Gulf Coast ethylene crackers, Japanese fluoropolymer resin production, and German additive compounding. Single-source vulnerability concentrates in aging Nagoya and Osaka irradiation facilities where technician scarcity constrains capacity expansion. Distribution runs through distributor-packaged assortments for MRO channels and direct mill contracts for automotive qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive electrification and EV battery safety mandates concentrate procurement authority with certified suppliers commanding formulation premiums.
For Market Incumbents: Deploy captive resin compounding investments to defend margin position against REACH-driven additive reformulation costs and silicone cold-shrink substitution threats. Deepen automotive platform approval moats by synchronizing R&D calendars with 800-volt EV architecture launches at Wolfsburg, Stuttgart, and Munich production clusters. Channel control through standardized kit configurations insulates against distributor consolidation. For New Entrants and Emerging Players: Distributor networks serving India's transmission infrastructure buildout under CEA directives represent the most penetrable white-space target for utility-grade medium-wall tubing. Halogen-free formulation capability gaps among non-compliant Asian exporters create specification openings for REACH-ready compounders. Pursue joint development agreements with Maharashtra and Gujarat electrical panel builders to establish local qualification credentials. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive qualification barriers and electron beam irradiation technician scarcity intersect to strand sub-scale compounders without platform approvals. Long-term viability favors suppliers with backward integration into resin production and existing OEM certification relationships. Watch for inflection signals in battery safety regulation harmonization across China's SAMR, EU's ECHA, and US NHTSA jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of halogen-free formulations insulates margins from REACH additive restrictions. |
| Automotive Platform Qualification Investment | UL 224 and GB/T 2408 certifications unlock procurement at Wolfsburg and Stuttgart EV production clusters. |
| Distributor-Packaged Assortment Expansion | Color-coded kit configurations reduce field selection errors in North American electrical wholesale channels. |
| Smart Factory Integration Partnership | IoT-enabled heat gun installations with temperature feedback loops penetrate aerospace wire harness shops. |
| India Manufacturing Footprint Establishment | CEA grid modernization directives create specification openings for utility-grade tubing in Maharashtra corridors. |
Research Methodology
Direct dialogue with automotive tier-one procurement officers, electron beam irradiation facility managers, resin compounding technical directors, and electrical wholesale distribution buyers grounded qualitative findings in operational reality. Secondary validation drew from UL certification databases, REACH registration filings, SAMR GB standard updates, customs trade flows, and SEC disclosures from listed electrical component suppliers. Bottom-up shipment tallies by product grade and end-use segment triangulated against top-down market sizing from petrochemical feedstock demand models.
Segment-level value and volume estimates across the projection horizon reflect econometric modeling of irradiation capacity utilization, resin price pass-through coefficients, and automotive production cluster demand elasticities. The analytical framework disaggregated polyolefin, fluoropolymer, PVC, and elastomer grades by wall thickness configuration, adhesive lining presence, and certification tier. CAGRs were derived from regression-weighted scenario outputs incorporating EV platform penetration curves and infrastructure investment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery safety regulation divergence and polyolefin resin price volatility. Forecasts reflect documented assumptions about irradiation capacity expansion timelines and automotive platform qualification success rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Quicklime Market