
 Republic of Ireland Renewable Energy Market | 2026-2036
Republic of Ireland Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Republic of Ireland Renewable Energy Market Analytics
A capital-intensity divergence between offshore wind developers and distributed solar installers is unwinding competitive dynamics across the Republic of Ireland. ESB Generation & Trading leverages its legacy grid infrastructure to dominate onshore interconnectivity. Statkraft Ireland Ltd anchors its position through deep specialization in hydropower and emerging offshore pipelines. Greencoat Renewables plc sustains yield-focused investment models that attract pension capital into operational wind assets.
The Republic of Ireland Renewable Energy sector encompasses electricity generation from wind, solar, biomass, and hydropower resources, with offshore wind turbines now reaching 15 MW unit capacity and floating foundation pilots advancing in Atlantic waters. The primary purpose is decarbonizing a power system still partially dependent on natural gas peaking plants while meeting corporate renewable procurement obligations. Onshore wind retains mature scale advantages across the Irish midlands, yet offshore installations command premium development margins due to higher capacity factors and seabed lease scarcity. Distributed solar is gaining structural traction among commercial end users seeking behind-the-meter savings, while centralized biomass faces feedstock logistics constraints that limit geographic expansion.
The Commission for Regulation of Utilities shapes market access through auction design and grid connection policy, while the EPA enforces emissions ceilings that indirectly accelerate coal and peat displacement. EirGrid's Shaping Our Electricity Future framework mandates system-level flexibility procurement that favors hybrid wind-storage configurations. Stakeholders must monitor auction clearing prices against rising capital costs and decide whether to front-load offshore development or sequence onshore repowering investments.
Market Dynamics
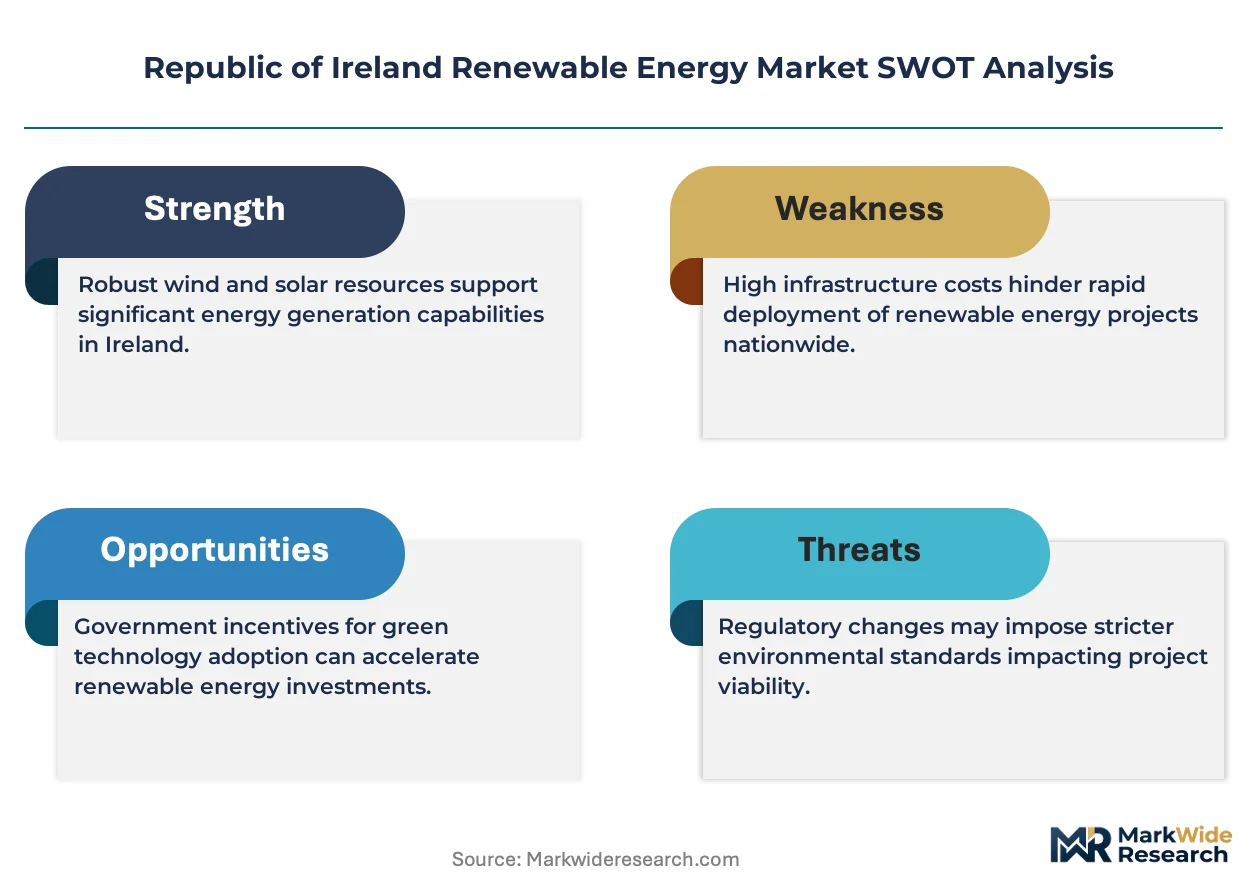
Offshore wind lease scarcity in Irish Atlantic waters is compressing development timelines and forcing capital allocation trade-offs between floating foundation pilots and established fixed-bottom arrays.
Growth Catalysts
- EirGrid's Shaping Our Electricity Future:This framework mandates system-level flexibility procurement that favors hybrid wind-storage configurations across the Munster and Leinster regions.
- Corporate power purchase agreements:Data center operators in Dublin and Cork are scaling long-term contracts with wind developers, creating bankable revenue streams for new capacity.
- Climate Action Plan offshore targets:Binding mandates for seabed lease allocation are accelerating project pipelines beyond historical onshore development rates.
Market Restraints
- Grid reinforcement bottlenecks:EirGrid connection queues in the west and northwest extend project commissioning timelines by 18-36 months.
- Specialized vessel scarcity:Heavy-lift installation ships for 15 MW turbine components concentrate in North Sea ports, inflating mobilization costs.
- Seabed lease competition:Limited Maritime Area Consent allocations create winner-take-all dynamics that exclude mid-scale developers.
Strategic Opportunities
- Atlantic floating wind pilots:Demonstration projects off the west coast offer first-mover advantages in deep-water technology commercialization.
- Behind-the-meter solar:Commercial and industrial rooftops in Cork and Limerick remain underpenetrated relative to grid-scale alternatives.
- Green hydrogen offtake:The EU Hydrogen Strategy and REPowerEU create demand corridors for electrolyzer-fed renewable integration.
Industry Challenges
- Marine consenting expertise:Qualified environmental impact assessors and marine ecologists are concentrated in Dublin, creating regional talent asymmetries.
- Interconnection synchronization:Celtic Sea and Irish Sea cable projects require coordinated timing with UK and French grid operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Republic of Ireland Renewable Energy Market |
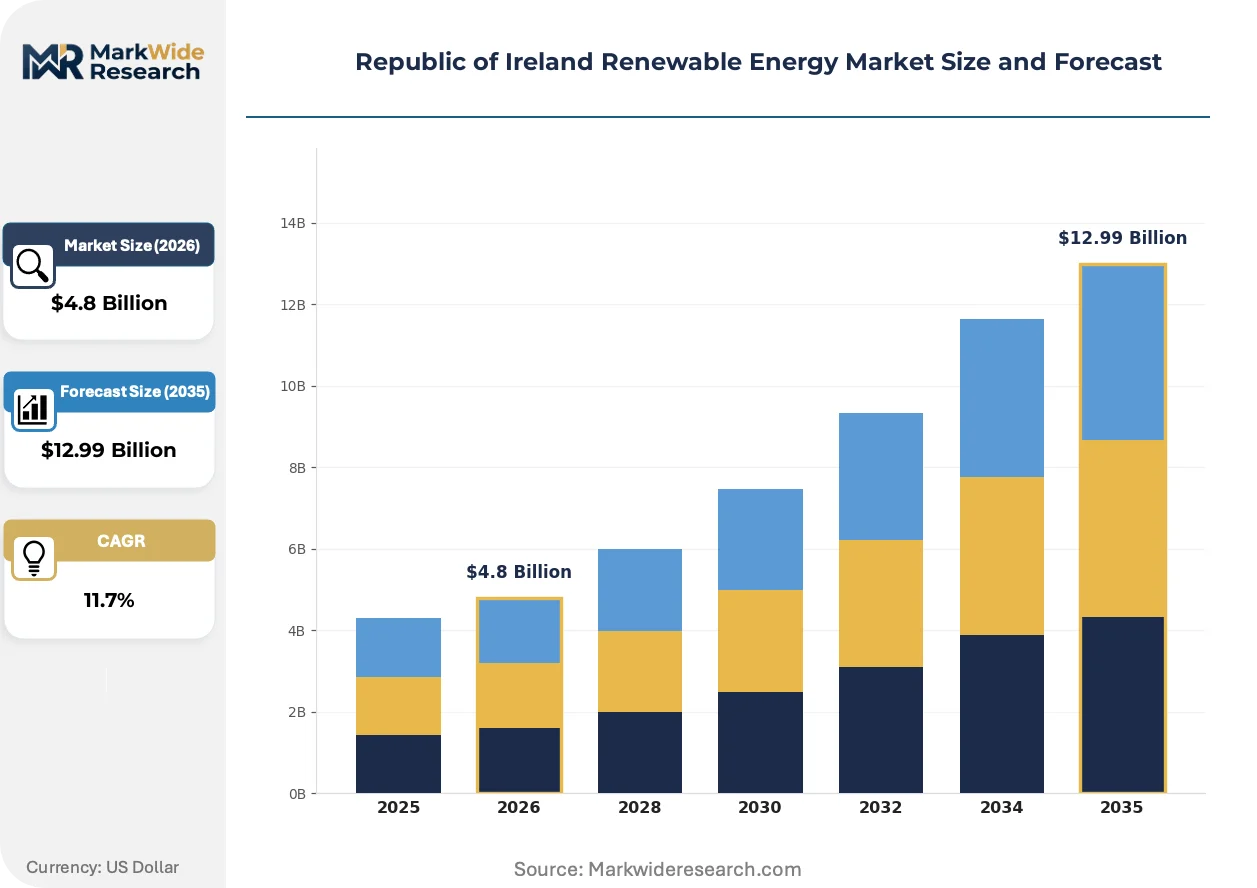
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Wind, Solar, Biomass, Hydropower Installation Type: Onshore, Offshore, Distributed, Centralized End User: Residential, Commercial, Industrial, Government Technology: Photovoltaic, Wind Turbine, Bioenergy, Small Hydro |
| Companies Covered | ESB Generation & Trading, SSE Renewables, Statkraft Ireland Ltd, Energia Group, Greencoat Renewables plc, Ørsted A/S, EDF Renewables, RES Group UK & Ireland Ltd, Mainstream Renewable Power Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Republic of Ireland Renewable Energy Market Evolving Landscape
Technology convergence between offshore wind and grid-scale storage is redefining asset configuration standards across the Republic of Ireland, with floating foundation pilots and modular battery integration commanding disproportionate engineering attention.
Turbine nacelle design is miniaturizing auxiliary systems while expanding rotor swept area, enabling 15 MW unit capacity within standardized installation vessel envelopes. Developers along the Wicklow and Wexford coasts are specifying these configurations for projects targeting 2028-2030 commissioning. The technology is miniaturizing balance-of-plant footprints, reducing seabed preparation costs and permitting timelines for sensitive marine habitats.
The Commission for Regulation of Utilities is reformulating auction design to incorporate non-price criteria including community benefit funds and supply-chain local content. This shift rewards developers with established Irish fabrication partnerships and penalizes pure merchant traders. Projects in the Irish Sea zone are restructuring consortium compositions to maximize scoring under the revised framework.
Corporate buyers are consolidating procurement through multi-site aggregated power purchase agreements rather than single-asset contracts. Data center clusters in Dublin and pharmaceutical manufacturers in Cork are negotiating portfolio-level arrangements that span onshore and offshore resources. This pattern is most pronounced among entities with Science Based Targets initiative commitments and Scope 2 emissions disclosure obligations.
Republic of Ireland Renewable Energy Market Segmentation
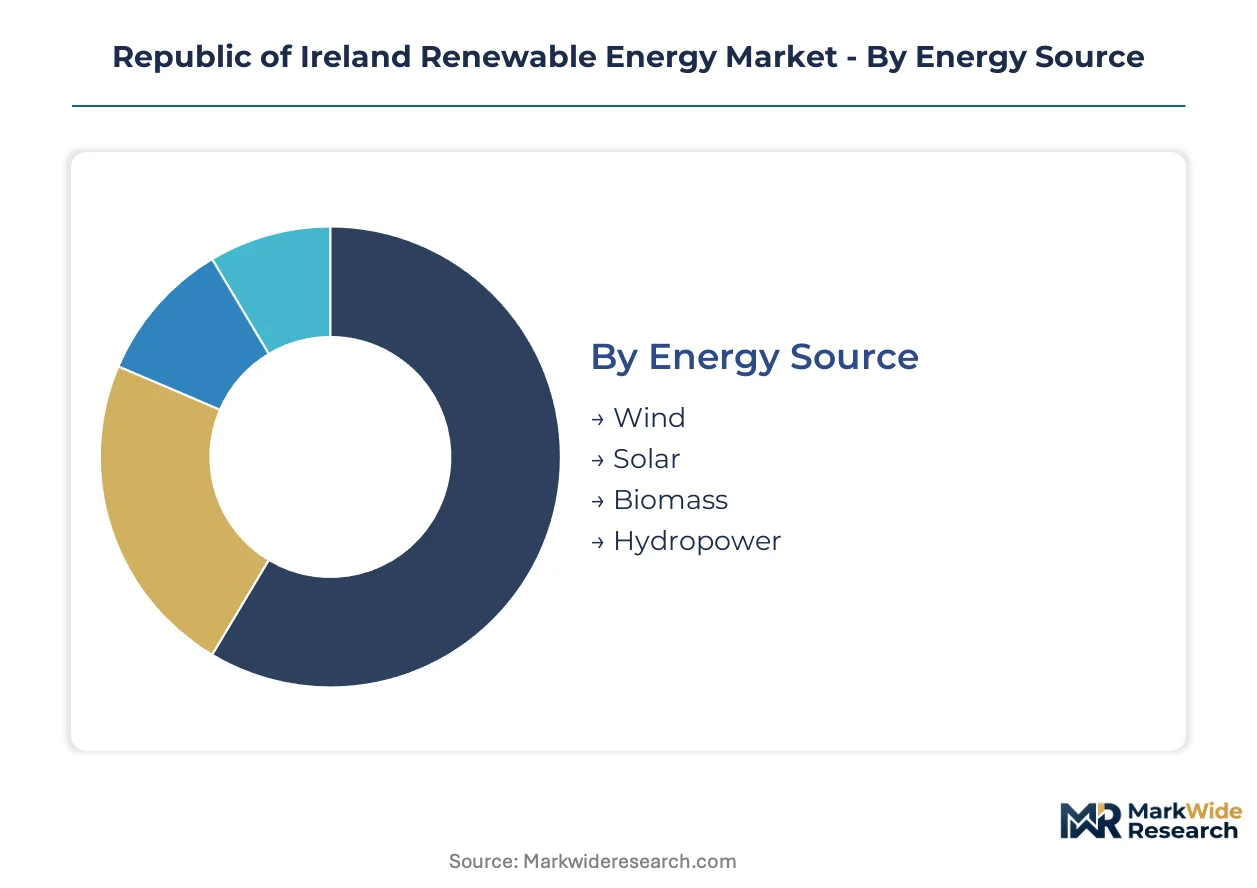
Segmentation in the Republic of Ireland renewable energy market reveals how capital flows differentially across technology maturity curves and regulatory incentive structures. Channel dynamics vary sharply between utility-scale auctions and behind-the-meter commercial procurement.
Energy Source:
Wind capacity channels through EirGrid's centralized auction mechanisms while solar and biomass serve more fragmented commercial offtake arrangements.
- Wind:Onshore turbines dominate the Irish midlands with established grid infrastructure, while offshore arrays command premium development margins in Atlantic waters due to higher capacity factors and Maritime Area Consent scarcity. Data center operators in Dublin and Cork are scaling power purchase agreements with wind developers, creating bankable revenue streams that accelerate project financing timelines.
- Solar:Photovoltaic installations concentrate in distributed commercial rooftops across Cork and Limerick, with behind-the-meter configurations avoiding grid connection queues that plague utility-scale alternatives. The technology is gaining structural traction among pharmaceutical manufacturers seeking Scope 2 emissions reductions without exposure to wholesale price volatility.
- Biomass:Bioenergy faces feedstock logistics constraints that limit geographic expansion beyond established agricultural supply sheds in the southeast.
- Hydropower:Small-scale run-of-river facilities anchor Statkraft Ireland's portfolio, leveraging legacy civil infrastructure with minimal environmental permitting friction.
Wind dominates installed base. Solar is where expansion concentrates.
Installation Type:
Capital intensity and consenting complexity create distinct margin structures across deployment configurations.
- Onshore:Fixed-bottom wind turbines across the midlands benefit from mature supply chains and standardized grid connection protocols, delivering baseline capacity additions with predictable commissioning schedules.
- Offshore:Arrays in the Irish Sea and Atlantic waters require specialized heavy-lift vessels concentrated in North Sea ports, inflating mobilization costs and compressing development timelines against binding Climate Action Plan targets.
- Distributed:Commercial and industrial rooftop solar in Munster remains underpenetrated relative to grid-scale alternatives, offering faster permitting pathways through local authority frameworks.
- Centralized:Utility-scale configurations face EirGrid connection queues extending 18-36 months in western regions, favoring developers with balance-sheet capacity to carry pre-revenue project phases.
Onshore installations anchor current capacity. Offshore pipelines are climbing the fastest.
End User:
Procurement scale and contract duration vary systematically across customer categories, with corporate buyers driving technology mix decisions.
- Residential:Small-scale rooftop solar and micro-generation schemes serve households through SEAI grant programs, with limited grid export capacity constraining system sizing.
- Commercial:Pharmaceutical manufacturers and data center clusters negotiate aggregated power purchase agreements spanning multiple sites and generation technologies, consolidating procurement leverage.
- Industrial:Energy-intensive facilities in Cork and Limerick prioritize behind-the-meter solar with battery storage to manage peak demand charges and grid reliability risks.
- Government:Public sector procurement through the Office of Government Procurement favors established onshore wind with proven performance records and community benefit fund compliance.
Commercial offtake dominates contracted capacity. Industrial behind-the-meter deployment is gaining share fastest.
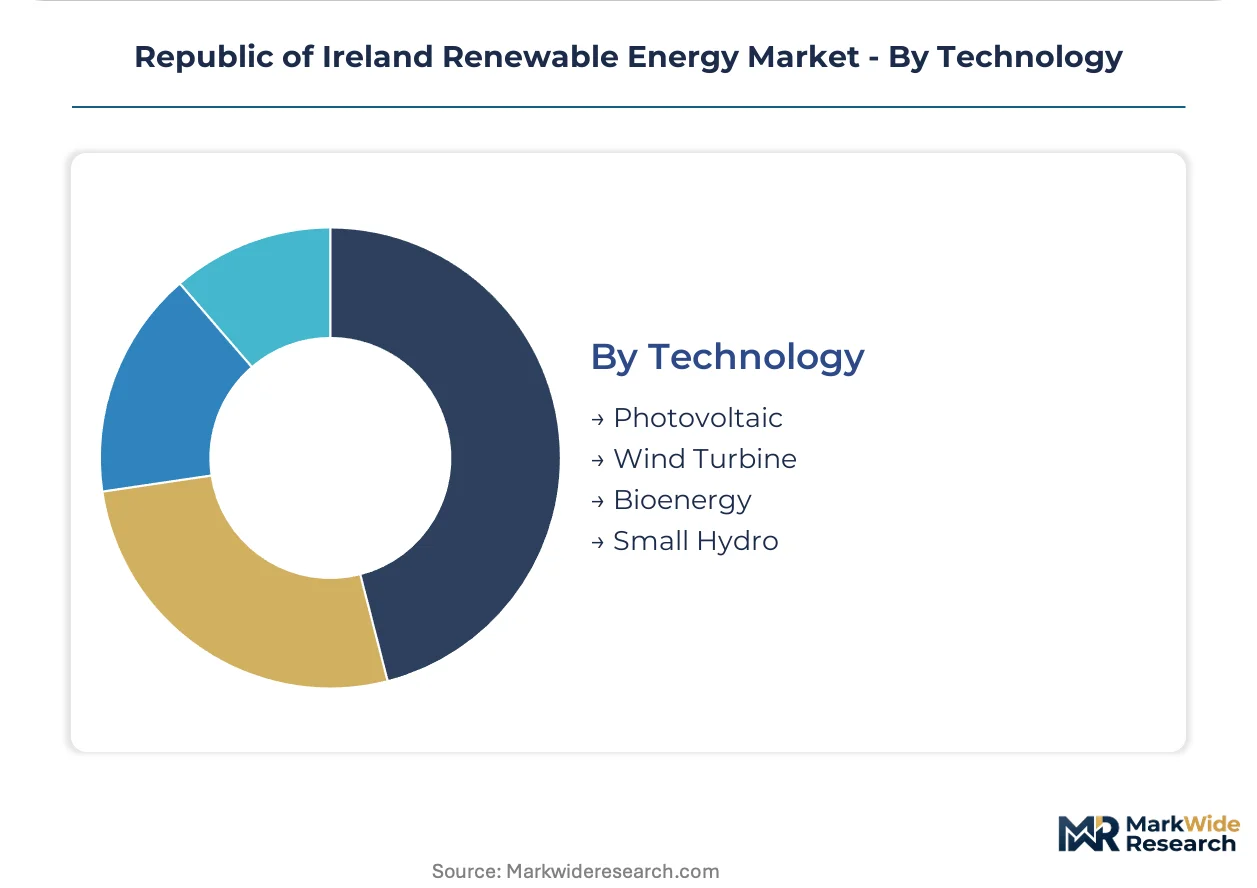
Technology:
Equipment specification standards diverge between auction-compliant utility-scale configurations and flexible commercial installations.
- Photovoltaic:Module efficiency ratings and inverter compatibility determine grid connection eligibility under EirGrid's Distribution Code, with commercial rooftops specifying higher degradation warranties than utility-scale ground-mount alternatives.
- Wind Turbine:15 MW unit capacity now standard for offshore projects targeting 2028-2030 commissioning, with nacelle designs miniaturizing auxiliary systems while expanding rotor swept area within standardized vessel envelopes.
- Bioenergy:Anaerobic digestion and combustion systems face emissions ceiling constraints enforced by the EPA, limiting deployment to agricultural regions with secured feedstock supply agreements.
- Small Hydro:Run-of-river configurations leverage existing civil infrastructure with minimal environmental impact assessment requirements, sustaining yield-focused investment models for pension capital deployment.
Wind turbine technology dominates capital deployment. Photovoltaic systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power concentrates in Dublin and Cork where data center load growth outpaces grid reinforcement, while western counties face connection queue penalties that compress development margins by 18-36 months.
Dublin and the Greater Dublin Area
Data center clusters in Dublin 15 and Tallaght drive contracted capacity demand through aggregated power purchase agreements. The Commission for Regulation of Utilities shapes access through auction design favoring hybrid wind-storage configurations. EirGrid's Shaping Our Electricity Future framework mandates flexibility procurement that channels investment toward battery co-location projects.
Cork and Munster Region
Pharmaceutical manufacturers and industrial facilities prioritize behind-the-meter solar with storage to manage peak demand charges. The Climate Action Plan mandates binding offshore wind targets that accelerate Maritime Area Consent allocations in Celtic Sea waters. Grid reinforcement projects in Cork Harbour and Ringaskiddy are accelerating to match corporate procurement timelines.
Galway and the Western Region
Atlantic floating wind pilots off the west coast offer first-mover advantages in deep-water technology commercialization. EirGrid connection queues extend commissioning timelines, favoring developers with balance-sheet capacity for pre-revenue phases. Marine consenting expertise concentrates in Dublin, creating regional talent asymmetries for environmental impact assessment.
Limerick and the Mid-West
Commercial and industrial rooftop solar remains underpenetrated relative to grid-scale alternatives, offering faster permitting through local authority frameworks. The EPA enforces emissions ceilings that indirectly accelerate peat displacement in the region. Shannon Foynes Port is positioning for offshore wind staging and heavy-lift vessel mobilization.
Wexford and the South-East
Fixed-bottom offshore arrays in the Irish Sea command premium development margins due to higher capacity factors and seabed lease scarcity. The Commission for Regulation of Utilities is reformulating auction design to incorporate community benefit funds and supply-chain local content. Projects targeting 2028-2030 commissioning are specifying 15 MW turbine configurations with miniaturized balance-of-plant footprints.
Republic of Ireland Renewable Energy Market Competitive Landscape
Concentration sits with vertically integrated utilities leveraging legacy grid infrastructure and yield-focused investment vehicles deploying pension capital into operational assets. ESB Generation & Trading anchors onshore interconnectivity through established distribution networks. Three archetypes dominate: state-linked incumbents with grid control, Nordic specialists in hydropower and offshore pipelines, and listed yieldcos acquiring operational wind portfolios. Competitive moves center on auction positioning through local content partnerships and sequencing between offshore development and onshore repowering investments.
Among Ireland-based operators, ESB Generation & Trading and Energia Group exemplify the integrated utility archetype with grid infrastructure leverage. SSE Renewables and Ørsted A/S represent the offshore-focused developer tier targeting Maritime Area Consent allocations. Statkraft Ireland Ltd and Greencoat Renewables plc occupy distinct positions—one anchoring hydropower specialization with minimal permitting friction, the other sustaining yield-focused models that attract institutional capital into contracted cash flows.
| Leading Market Players |
|---|
| ESB Generation & Trading |
| SSE Renewables |
| Statkraft Ireland Ltd |
| Energia Group |
| Greencoat Renewables plc |
| Ørsted A/S |
| EDF Renewables |
| RES Group UK & Ireland Ltd |
| Mainstream Renewable Power Ltd |
| Others |
Value Network & Pricing Analysis
Heavy-lift vessel utilization rates above 85 percent in North Sea ports concentrate installation capacity among a handful of specialized operators, compressing margins for Irish offshore developers while elevating price floors for fixed-bottom arrays. This scale asymmetry between turbine OEMs and marine contractors reshapes procurement leverage across the Republic of Ireland project pipeline.
Pricing Analysis
Configured-to-order pricing for 15 MW offshore turbine packages commands a 15-25 percent premium over standardized onshore configurations due to marine-grade nacelle specifications and floating foundation adaptation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and supply-chain local content scoring under the Commission for Regulation of Utilities auction reforms. Cost compression in standardized onshore equipment is intensifying because Chinese module manufacturers are penetrating European distribution channels. Data center operators in Dublin demonstrate lowest price sensitivity due to long-term corporate procurement mandates, while agricultural biomass developers face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Inventory cycles for 15 MW turbine components stretch 14-18 months from order to Atlantic waters installation, tethering project timelines to OEM production slots in Denmark and Germany. Heavy-lift vessel fleets concentrate in Rotterdam, Esbjerg, and Bremerhaven, while power electronics and transformer manufacturing draws from China and South Korea. Single-source vulnerability sits with specialized jack-up vessels capable of operating in Irish Sea wave conditions. Distribution runs through EPC contractor consortiums that bundle turbine supply, marine logistics, and grid connection under turnkey arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Republic of Ireland renewable energy market functions as a defensive-moat sector where Maritime Area Consent scarcity creates regulatory entrenchment that protects first-mover offshore developers from replication.
For Market Incumbents: Secure long-term vessel charter agreements before 2026 delivery windows lock, insulating project timelines against North Sea port congestion. Deepen backward integration into grid-scale battery storage manufacturing to capture EirGrid flexibility procurement premiums. The emerging threat of floating foundation technology disruption from Scottish and Norwegian developers demands rapid pilot investment to maintain seabed lease positioning. For New Entrants and Emerging Players: Behind-the-meter solar servicing for Cork pharmaceutical manufacturers offers underexploited white-space where incumbent utilities lack commercial sales infrastructure. Target Munster region industrial facilities with leased rooftop arrangements and performance-guaranteed savings contracts. A direct-to-facility energy-as-a-service model bypasses EirGrid connection queues that cripple utility-scale competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operational onshore wind yieldcos with indexed power purchase agreements and inflation-linked offtake structures. Long-term viability across the analysis window favors developers with secured Maritime Area Consent allocations over merchant-exposed early-stage pipelines. The acquisition target archetype comprises repowering-ready midlands wind portfolios with grid connection priority rights. Monitor Celtic Sea interconnector synchronization announcements as the critical inflection signal for offshore valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Maritime Area Consent Acquisition | Seabed lease scarcity under the Climate Action Plan creates winner-take-all allocation dynamics for Celtic Sea zones. |
| Hybrid Wind-Storage Configuration | EirGrid's Shaping Our Electricity Future framework mandates system flexibility procurement favoring battery co-location. |
| Corporate PPA Aggregation | Data center clusters in Dublin and Cork consolidate procurement leverage across multi-site renewable portfolios. |
| Floating Foundation Pilot Investment | Deep-water technology commercialization off Galway offers first-mover advantages in Atlantic wind zones. |
| Local Content Partnership Structuring | Commission for Regulation of Utilities auction reforms reward established Irish fabrication and community benefit compliance. |
Research Methodology
A standing panel of EPC contractors, utility planning officers, IPP project developers, and marine logistics specialists provided ongoing calibration across the primary research phase. Input combined structured interviews with grid operators and renewable asset owners against secondary validation through EirGrid connection queue databases, EPA emissions filings, and Maritime Area Consent allocation records. Bottom-up project pipeline aggregation triangulated against top-down capacity installation forecasts from IEA and national energy agency publications.
Consistency checks against external benchmarks validated capacity deployment trajectories and auction clearing price assumptions across the projection horizon. The analytical framework modeled segmentation dimensions spanning energy source, installation type, end-user category, and technology specification, with regional grid reinforcement timelines as an Ireland-specific overlay. CAGRs were derived from installed base growth rates, capacity factor improvements, and corporate procurement obligation enforcement patterns.
Forecasts assume regulatory continuity in Irish Climate Action Plan mandates and EU REPowerEU hydrogen corridor funding; material policy shifts would require re-modeling seabed lease allocation timelines and green hydrogen offtake assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market