
 Europe Renewable Energy Market | 2026-2036
Europe Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Renewable Energy Market Analysis
Corporate offtakers from data centers and electro-intensive manufacturing is collapsing the historical dominance of utility-scale procurement in Europe. Ørsted leverages its offshore wind pipeline across the North Sea to anchor long-term contracts with industrial buyers. Vestas competes on turbine platform specialization for low-wind sites, while RWE AG extends its brownfield-to-greenfield repositioning across lignite transition zones in Germany and Poland.
Europe renewable energy encompasses electricity and heat generation from naturally replenishing sources including solar irradiance, wind kinetic energy, hydrological flow, and organic biomass conversion, typically harnessed through photovoltaic semiconductor arrays, horizontal-axis wind turbines, Francis or Pelton hydropower runners, and anaerobic digestion or combustion thermal cycles. The primary commercial purpose is to displace fossil-fuel baseload and intermediate generation while providing dispatchable or variable zero-carbon electrons to industrial, commercial, and residential end users. Solar photovoltaic installations occupy the largest share of annual capacity additions, though offshore wind commands premium margin pools due to higher capital intensity and specialized vessel requirements. Residential and commercial end-user segments are expanding fastest behind net-metering reforms and rooftop mandate policies, while utility-scale installations remain the volume anchor across Southern and Eastern Europe.
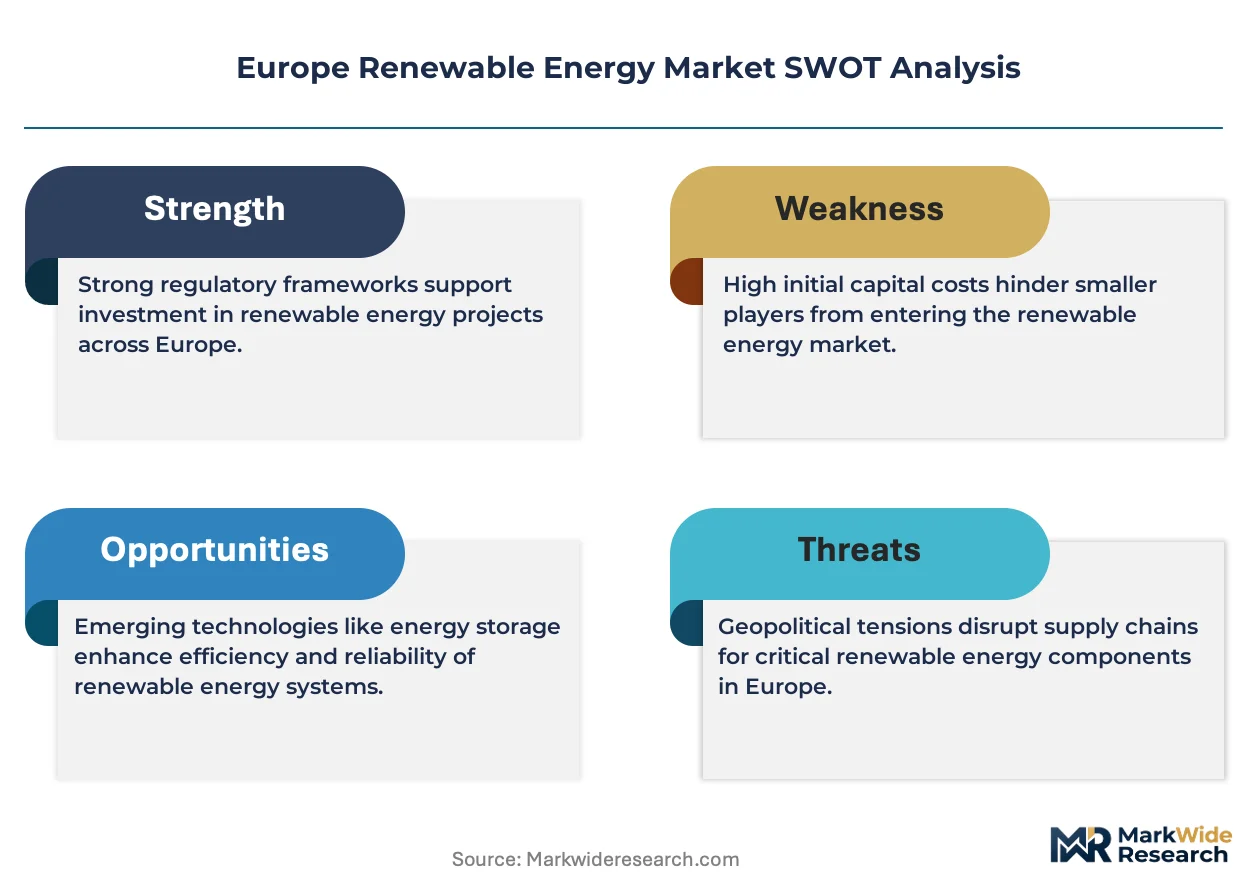
The EU Green Deal, REPowerEU, and the F-Gas Regulation collectively reshape project economics through carbon border adjustments, renewable hydrogen production targets, and phasedown of fluorinated greenhouse gases in heat pump and grid infrastructure. EMA coordination on sustainability reporting under CSRD and national regulators in Germany and Spain enforce disclosure standards that determine capital access for developers. Stakeholders must monitor grid congestion allocation mechanisms and cross-border capacity auction designs as the decisive variables for project returns.
Market Dynamics
Corporate power purchase agreements from hyperscale data center operators and electro-intensive manufacturing are collapsing the historical dominance of utility-scale procurement across Europe, forcing developers to restructure offtake strategies around direct bilateral contracts rather than merchant exposure or feed-in tariffs.
Growth Catalysts
- REPowerEU acceleration:The framework's streamlined permitting timelines and grid interconnection standards compress project development cycles from authorization to commercial operation.
- Data center load growth:Hyperscale cloud operators in Ireland, the Netherlands, and Germany anchor long-term renewable offtake to meet carbon-neutral commitments and secure stranded power.
- Offshore wind vessel specialization:Purpose-built installation and maintenance fleets unlock deeper North Sea sites with higher capacity factors and premium margin pools.
Market Restraints
- Grid congestion allocation:Bottlenecks in Germany's north-south transmission corridors and Spain's renewable-rich regions force curtailment and re-dispatch costs onto project economics.
- Critical mineral concentration:Rare earth processing and permanent magnet supply chains concentrate in single-source jurisdictions, exposing turbine and inverter manufacturers to input volatility.
- F-Gas phasedown timeline:The regulation's staged reduction of fluorinated greenhouse gases in heat pump and switchgear infrastructure compresses equipment replacement windows without fully scaled alternatives.
Strategic Opportunities
- Eastern European brownfield conversion:Lignite transition zones in Poland and Romania offer grid-connected sites with existing transmission access and local workforce availability.
- Renewable hydrogen production mandates:The EU's production targets under REPowerEU create dedicated offtake for electrolyzer-integrated wind and solar in Iberia and the North Sea.
- Agrivoltaic dual-use deployment:Mounting structures that preserve agricultural activity unlock permitting pathways in France and Italy where land-use conflicts stall conventional utility-scale projects.
Industry Challenges
- Specialized vessel crew scarcity:Offshore wind installation and maintenance operations face acute shortages of jack-up vessel operators and high-voltage cable technicians.
- CSRD disclosure preparation:The European Sustainability Reporting Standards require granular emissions and biodiversity data that most developers lack systems to capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Renewable Energy Market |
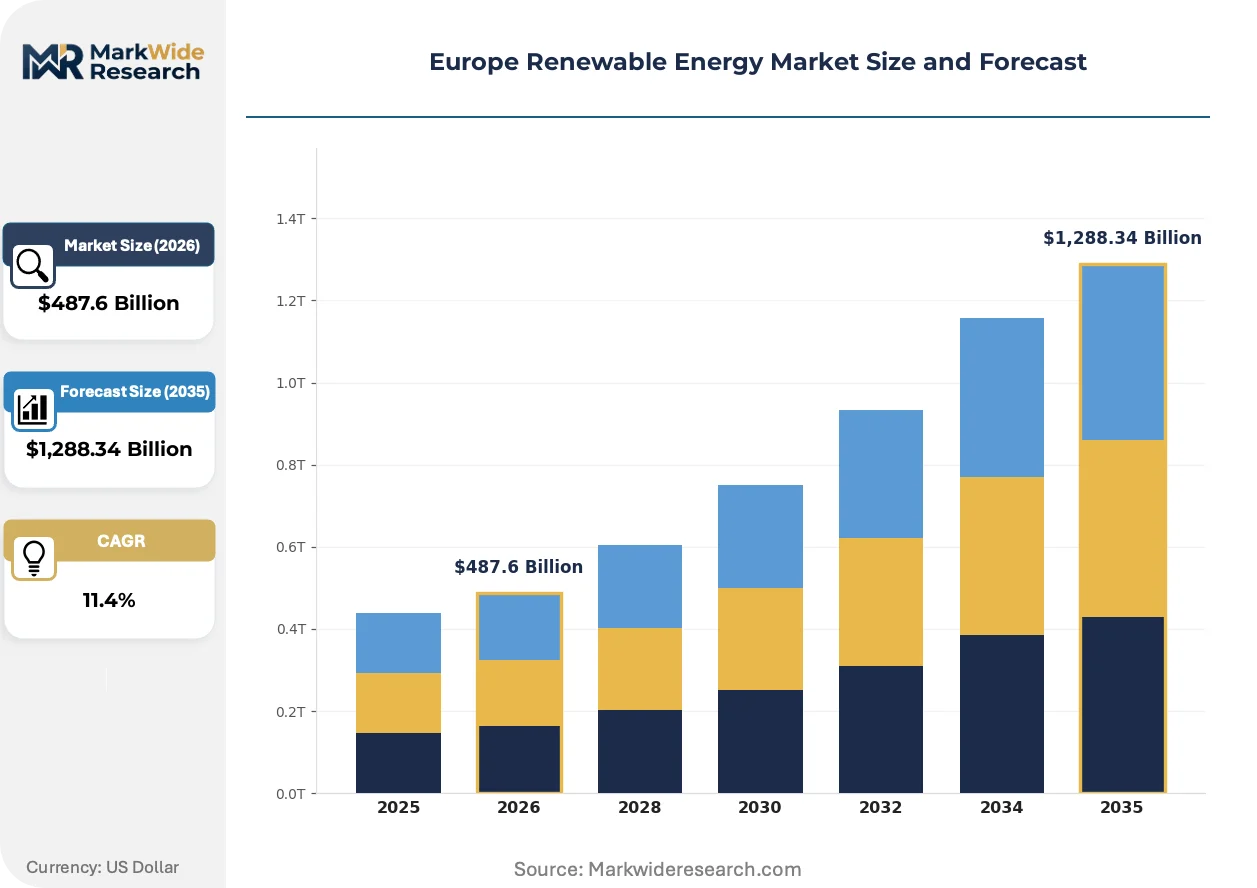
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,288.34 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydro, Biomass Technology Type: Photovoltaic, Offshore Wind, Geothermal, Small Hydropower End User: Residential, Commercial, Industrial, Utilities Installation Type: On-grid, Off-grid, Hybrid, Centralized |
| Companies Covered | Enel, Ørsted, Iberdrola, Equinor, SSE Renewables, Vestas, RWE AG, OX2 Group AB, Siemens, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Renewable Energy Market Emerging Trajectories
Technology convergence between power electronics and digital control systems is compressing balance-of-plant footprints while policy instruments accelerate the phaseout of carbon-intensive baseload across member states.
Modular power conversion hardware for distributed solar and storage applications is miniaturizing. Commercial and industrial installers across Germany and the Netherlands adopt containerized skid solutions that reduce on-site commissioning from weeks to days. This compression enables rapid deployment behind meter constraints and accelerates payback periods for mid-market offtakers.
The EU Green Deal's carbon border adjustment mechanism reshapes import competitiveness for electro-intensive manufacturing. Steel, aluminum, and chemical producers in Poland and Germany now face embedded emissions tariffs that redirect procurement toward verified renewable supply. This pressure cascades through supply chains, forcing tier-two suppliers to document scope two emissions or lose contract eligibility.
Direct bilateral contracting between developers and large energy consumers is displacing traditional utility intermediation. Data center operators in Ireland and hyperscale manufacturers in Bavaria negotiate sleeved power agreements that guarantee physical delivery rather than renewable energy certificate arbitrage. This shift concentrates credit risk assessment capabilities among a narrow tier of bankable offtakers.
Europe Renewable Energy Market Segmentation
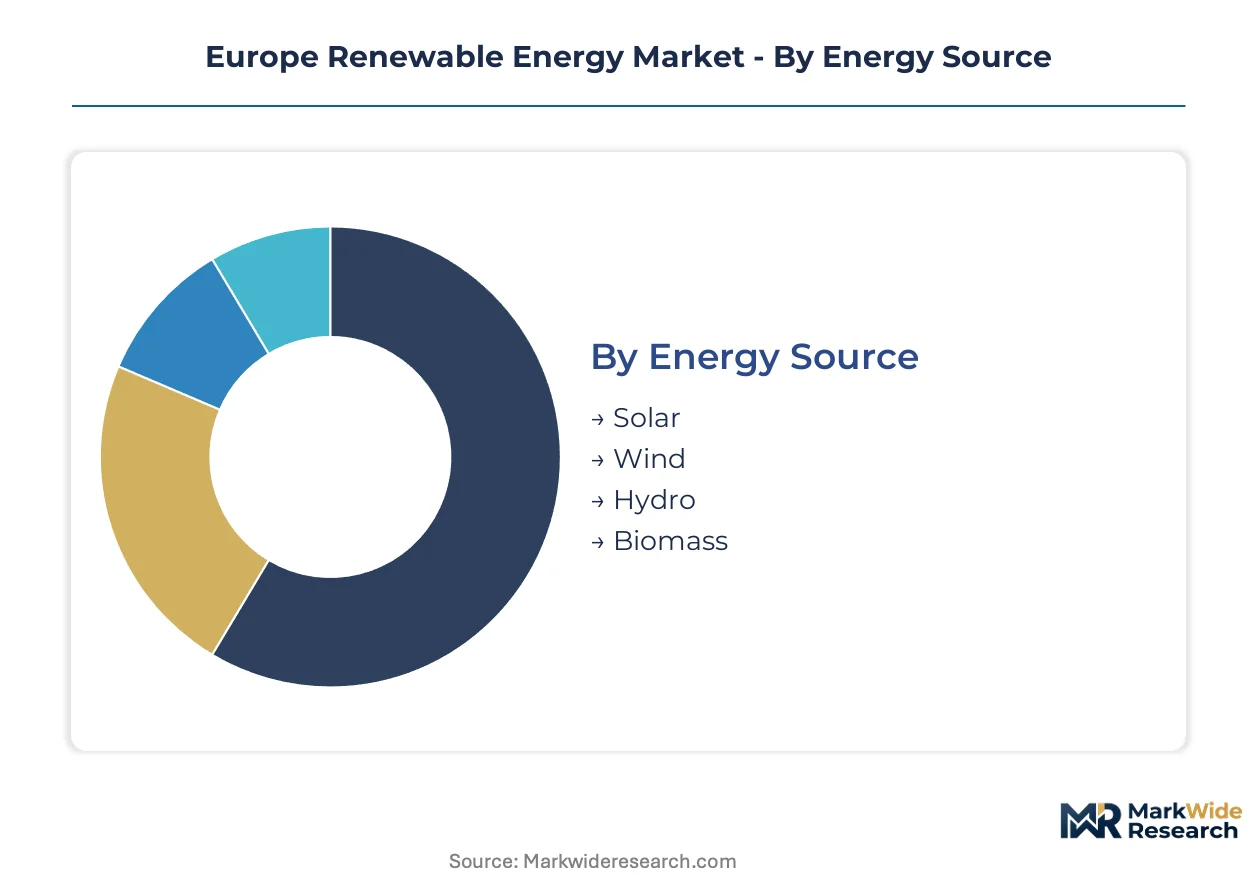
Segmentation in Europe's renewable energy market reveals how capital flows through distinct procurement channels, from bilateral corporate contracts to regulated utility auctions. Understanding these pathways exposes where margin pools concentrate and which technology configurations align with specific offtaker risk profiles.
Energy Source:
Channel mix varies sharply across primary energy sources, with utility-scale auctions dominating hydro and biomass while corporate PPAs capture premium wind and solar volumes.
- Solar:Photovoltaic semiconductor arrays convert direct and diffuse irradiance into DC electricity through silicon wafer or thin-film architectures. German and Spanish commercial installers drive capacity additions through rooftop mandates and net-metering reforms that collapse payback periods below six years.
- Wind:Horizontal-axis turbines extract kinetic energy through aerodynamic blade profiles and drivetrain generators. Denmark and Germany anchor offshore demand through North Sea lease rounds, while onshore repowering in Spain and France extends asset life without greenfield permitting delays.
- Hydro:Run-of-river and pumped-storage configurations harness gravitational water flow through Francis or Pelton turbine runners. Alpine regions in Austria and Switzerland maintain installed base dominance through century-old infrastructure with minimal marginal cost.
- Biomass:Anaerobic digestion and combustion thermal cycles convert organic feedstock into dispatchable power and district heat. Agricultural residues in Poland and forestry waste in Sweden supply combined heat and power plants with baseload reliability.
Hydro dominates installed base across Scandinavia and the Alps. Solar is where expansion concentrates, with annual capacity additions outpacing all other sources combined.
Technology Type:
Cost tier stratification separates mature mass-market technologies from capital-intensive specialized systems requiring dedicated installation fleets.
- Photovoltaic:Silicon-based semiconductor junctions generate electron-hole pairs under photon absorption, with module efficiencies ranging from 20-23% for monocrystalline architectures. Distributed commercial arrays in the Netherlands and Germany deploy containerized skid solutions that compress commissioning from weeks to days.
- Offshore Wind:Jacket and monopile foundations anchor turbines in water depths exceeding 50 meters, with capacity factors 15-20 points above onshore equivalents. Purpose-built jack-up vessels from specialized shipyards in Denmark and the Netherlands unlock deeper North Sea sites with premium margin structures.
- Geothermal:Binary cycle and flash steam plants extract subsurface thermal energy through drilled production wells. Iceland and Italy host the continent's only commercially scaled operations, constrained by geological rarity elsewhere.
- Small Hydropower:Run-of-river installations below 10 MW capacity avoid reservoir construction through diversion weirs and penstock channels. Romania and Slovenia retain development pipelines where environmental permitting exempts sub-threshold projects.
Photovoltaic commands volume leadership across Southern and Eastern Europe. Offshore wind is climbing the fastest, with auction prices collapsing 70% over the past decade to challenge wholesale parity.
End User:
Customer type determines contract structure, with industrial offtakers negotiating sleeved physical delivery while residential segments rely on standardized feed-in tariffs.
- Residential:Rooftop arrays and heat pump integration serve single-family and multi-unit dwellings through net-metering or self-consumption optimization. Italian and German households lead penetration rates behind subsidy schemes that offset upfront capital burdens.
- Commercial:Mid-market enterprises deploy behind-meter solar and storage to manage peak demand charges and carbon disclosure obligations. Logistics warehouses in Belgium and retail chains in France anchor this segment through portfolio-scale procurement.
- Industrial:Electro-intensive manufacturers negotiate direct bilateral contracts for physical renewable delivery rather than certificate arbitrage. Steel and chemical producers in Poland and Bavaria face EU carbon border adjustment pressure that redirects procurement toward verified zero-carbon supply.
- Utilities:Traditional generators and retail suppliers procure through regulated auctions and green certificate schemes to meet renewable portfolio obligations. Spanish and Portuguese utilities dominate auction participation, though corporate PPA displacement erodes their historical procurement monopoly.
Utilities retain installed base dominance from legacy feed-in tariff regimes. Industrial offtakers represent the steepest expansion trajectory, with data center operators and electro-intensive manufacturers collapsing traditional intermediation.
Installation Type:
Grid integration architecture determines revenue stability, with on-grid configurations accessing wholesale markets and off-grid systems capturing stranded load premiums.
- On-grid:Synchronous connection to transmission or distribution networks enables energy export and frequency regulation services. German and Spanish utility-scale solar and wind dominate this category through auction-based allocation of grid capacity rights.
- Off-grid:Islanded systems serve remote industrial sites or rural communities without network extension economics. Mining operations in Scandinavia and agricultural processing in Greece deploy diesel-hybrid replacements with battery storage integration.
- Hybrid:Co-located generation and storage assets optimize self-consumption and provide grid services through synthetic inertia and ramp rate control. Irish and British projects pair offshore wind with battery arrays to manage interconnection constraint periods.
- Centralized:Large-scale single-point generation feeds high-voltage transmission through dedicated substations. North Sea offshore clusters and Iberian solar parks concentrate capacity in gigawatt-scale nodes that minimize balance-of-system costs per megawatt.
On-grid configurations dominate cumulative capacity. Hybrid architectures are gaining share fastest, as storage cost declines enable new revenue stacking from ancillary services and energy arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind installation fleets and specialized cable manufacturing cluster around North Sea port infrastructure. Denmark, Germany, and the Netherlands host the dominant share of vessel operators and high-voltage interconnection suppliers.
Germany
Industrial hydrogen demand from steel producers in the Ruhr and chemical clusters in Ludwigshafen anchors electrolyzer-integrated renewable procurement. The Federal Network Agency (Bundesnetzagentur) auctions grid connection rights under the EnWG framework. North Sea offshore zones near Heligoland concentrate turbine installation activity through 2030.
Spain
Solar irradiance in Extremadura and Aragón supports gigawatt-scale photovoltaic parks serving electro-intensive manufacturing. The National Integrated Energy and Climate Plan mandates streamlined environmental impact assessments for renewable projects. The Zaragoza-Teruel corridor hosts agrivoltaic pilots that preserve agricultural output beneath panel arrays.
Denmark
Offshore wind capacity factors exceeding 50 percent attract vessel operators and foundation fabricators to Esbjerg and the Port of Copenhagen. The Danish Energy Agency coordinates lease rounds under the Energy Islands program. Bornholm Energy Island anchors hybrid wind-solar-storage configurations for Baltic Sea interconnection.
Poland
Lignite transition zones in Bełchatów and Turów offer grid-connected brownfield sites with existing transmission infrastructure. The National Energy and Climate Plan channels EU Just Transition Mechanism funds toward renewable repowering. Lower Silesian industrial clusters negotiate direct bilateral contracts with onshore wind developers.
United Kingdom
Round 4 and Round 5 offshore wind allocations in the Celtic Sea and Dogger Bank require specialized jack-up vessels from Aberdeen and Hull supply bases. The Contracts for Difference scheme guarantees strike prices that de-risk capital deployment. Scottish floating wind demonstrations in the Kincardine array test mooring systems for deeper water sites.
Europe Renewable Energy Market Vendor Landscape
Concentration sits with integrated utilities that combine development, generation, and offtake contracting under single corporate structures. The competitive map reveals a bifurcated structure: state-affiliated European majors control offshore wind pipelines through sovereign lease access, while independent power producers capture distributed solar and onshore wind through faster permitting cycles. Two archetypes dominate: vertically integrated energy majors with balance-sheet capacity for multi-gigawatt projects; and specialized developers that monetize early-stage origination through construction-ready asset sales. Competitive intensity manifests in M&A activity targeting pipeline depth and strategic partnerships securing vessel slots for offshore installation windows.
Among the integrated utility tier, Enel and Iberdrola exemplify the capital-deployment archetype that spans development, construction, and long-term asset ownership. Ørsted anchors the pure-play offshore wind specialist position, having originated from oil and gas transition. Vestas occupies the manufacturing-equipment layer, supplying turbine platforms across onshore and offshore configurations.
| Leading Market Players |
|---|
| Enel |
| Ørsted |
| Iberdrola |
| Equinor |
| SSE Renewables |
| Vestas |
| RWE AG |
| OX2 Group AB |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Gigawatt-scale procurement volumes from hyperscale data centers and electro-intensive manufacturers concentrate buying power among a narrow tier of bankable offtakers, compressing price floors for renewable developers while simultaneously rewarding suppliers with demonstrated installation track records and balance-sheet capacity. This scale dynamic stratifies the European market into distinct pricing tiers that reflect not merely technology costs but supply chain reliability premiums and offtaker creditworthiness.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs European renewable procurement, with premium tiers capturing offshore wind and electrolyzer-integrated projects backed by investment-grade offtakers, standard tiers absorbing utility-scale solar and onshore wind through auction mechanisms, and economy tiers serving distributed commercial and residential segments behind net-metering regimes. Price differentiation hinges on certification grade under EU Green Deal taxonomy alignment and after-sales service bundling including long-term asset management and performance guarantees. Cost compression in the standard tier is intensifying because auction price caps and merchant exposure limits erode developer margins, while premium-tier pricing holds firmer due to vessel slot scarcity and specialized foundation fabrication bottlenecks. Industrial offtakers exhibit lowest price sensitivity given carbon border adjustment exposure, whereas residential segments remain most responsive to upfront capital subsidies and payback period thresholds.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port complexes fluctuate with container availability and North Sea vessel positioning, compressing commissioning windows for time-sensitive installation campaigns. Permanent magnet supply chains concentrate in China and rare earth processing in Vietnam, while turbine nacelle assembly clusters in Denmark and blade manufacturing in Spain. Raw material dependencies span neodymium-iron-boron magnets, high-grade silicon steel laminations, and specialized epoxy resin systems for blade composites. Single-source vulnerability in jack-up vessel fleets exposes North Sea offshore schedules to weather window constraints and crew certification backlogs. Distribution runs through EPC contractors with established grid interconnection relationships and direct bilateral developer-offtaker contracting that bypasses traditional utility intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's renewable energy market represents a high-growth disruption anchored by REPowerEU's regulatory inflection, which collapses permitting timelines and redirects capital flows toward electrolyzer-integrated generation and corporate-backed offtake structures.
For Market Incumbents: Fortify project pipeline depth through brownfield site acquisition in Polish lignite transition zones and German coal phase-out regions, securing grid connection rights ahead of auction rounds. Vertical integration into specialized offshore vessel operations and high-voltage cable manufacturing mitigates jack-up slot scarcity and installation window risks. Prioritize CSRD disclosure infrastructure investment to maintain capital access under tightening European Sustainability Reporting Standards enforcement. For New Entrants and Emerging Players: Differentiate on agrivoltaic dual-use deployment expertise in French and Italian markets where land-use conflicts stall conventional utility-scale permitting. Target Eastern European distributed commercial solar segments with containerized skid solutions that compress commissioning timelines for mid-market logistics and retail offtakers. Pursue direct bilateral contracting with electro-intensive manufacturers facing EU carbon border adjustment pressure as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with construction-ready offshore wind assets in Danish and German lease zones, where auction price floors have stabilized and vessel slot access constitutes competitive moat. Long-term viability over the projection horizon rests on electrolyzer integration capabilities and renewable hydrogen offtake contract origination. Monitor F-Gas Regulation phasedown timelines as the decisive signal for heat pump and switchgear equipment replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | North Sea lease access under Danish Energy Islands program anchors long-term revenue visibility. |
| Corporate Power Purchase Agreement | Direct bilateral contracts with Bavarian chemical producers displace utility intermediation. |
| Electrolyzer Technology Licensing | REPowerEU hydrogen mandates create dedicated offtake for Iberian and North Sea wind. |
| Backward Integration into Vessel Operations | Jack-up fleet scarcity under German BSH permitting timelines rewards captive installation capacity. |
| Green Certification Program | EU taxonomy alignment under CSRD disclosure standards determines institutional capital access. |
Methodological Framework
Desk research of IEA renewable deployment databases, EMA regulatory filings, and national energy agency auction records preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Germany, Spain, and Denmark. Primary fieldwork with offshore wind vessel operators and electrolyzer engineering firms validated capacity expansion timelines and supply chain bottleneck assessments. Secondary triangulation incorporated FERC interconnection queue data, REPowerEU implementation progress reports, and corporate PPA disclosure filings. Bottom-up project-level aggregation and top-down national target reconciliation anchored market sizing across the analysis window.
Variance decomposition across energy source, technology type, end user, and installation type segmentation dimensions drove analytical framework construction throughout the modeling period. CAGRs derived from capacity addition run-rates, auction price trajectory analysis, and offtake contract tenor distributions. Forecast inputs incorporated REPowerEU permitting reform implementation velocity, North Sea vessel fleet expansion schedules, and EU carbon border adjustment mechanism phase-in timing.
Material uncertainties — grid congestion allocation reform delays, F-Gas Regulation substitution technology readiness, and rare earth supply chain geopolitical disruption — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained REPowerEU funding continuity and corporate PPA demand persistence from data center load growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Solar EPC Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Solar Watch Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Wind Turbine Foundation Market