
 West Africa Renewable Energy Market | 2026-2036
West Africa Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Renewable Energy Market Analytics
ECOWAS Renewable Energy Policy is recalibrating the cost-of-entry calculus for independent power producers across West African markets. Energicity Corp leverages decentralized microgrid architectures to anchor rural electrification in Sierra Leone and Liberia. Sterling & Wilson Renewable Energy sustains EPC dominance through utility-scale solar deployment expertise. REDAVIA GmbH specializes in containerized solar leasing models that reduce capital barriers for commercial off-takers.
West Africa renewable energy encompasses electricity generation from solar photovoltaic arrays, onshore wind turbines, small-to-medium hydropower installations, and agricultural biomass digesters, typically operating at 15-45% capacity factors depending on resource quality and grid stability. The primary purpose is to displace expensive diesel-fired generation while expanding access to populations beyond centralized transmission networks. Solar photovoltaic systems lead installed capacity due to abundant irradiance and modular deployment flexibility, while hybrid and microgrid configurations represent the fastest-expanding system type as they integrate battery storage with multiple generation assets. Agricultural applications command attention from development finance institutions seeking productive-use electrification, though industrial off-takers currently absorb the largest share of contracted megawatts.
Nigeria's Electricity Regulatory Commission, Ghana's Energy Commission, and Senegal's Commission de Régulation du Secteur de l'Electricité collectively enforce grid codes, licensing frameworks, and tariff methodologies that determine project bankability and market access timelines. The ECOWAS Centre for Renewable Energy and Energy Efficiency harmonizes standards across member states, reducing cross-border equipment certification burdens. Stakeholders must monitor how national implementation of the AfCFTA protocols reshapes equipment sourcing rules and local content requirements before committing capital to multi-country portfolios.
Market Dynamics
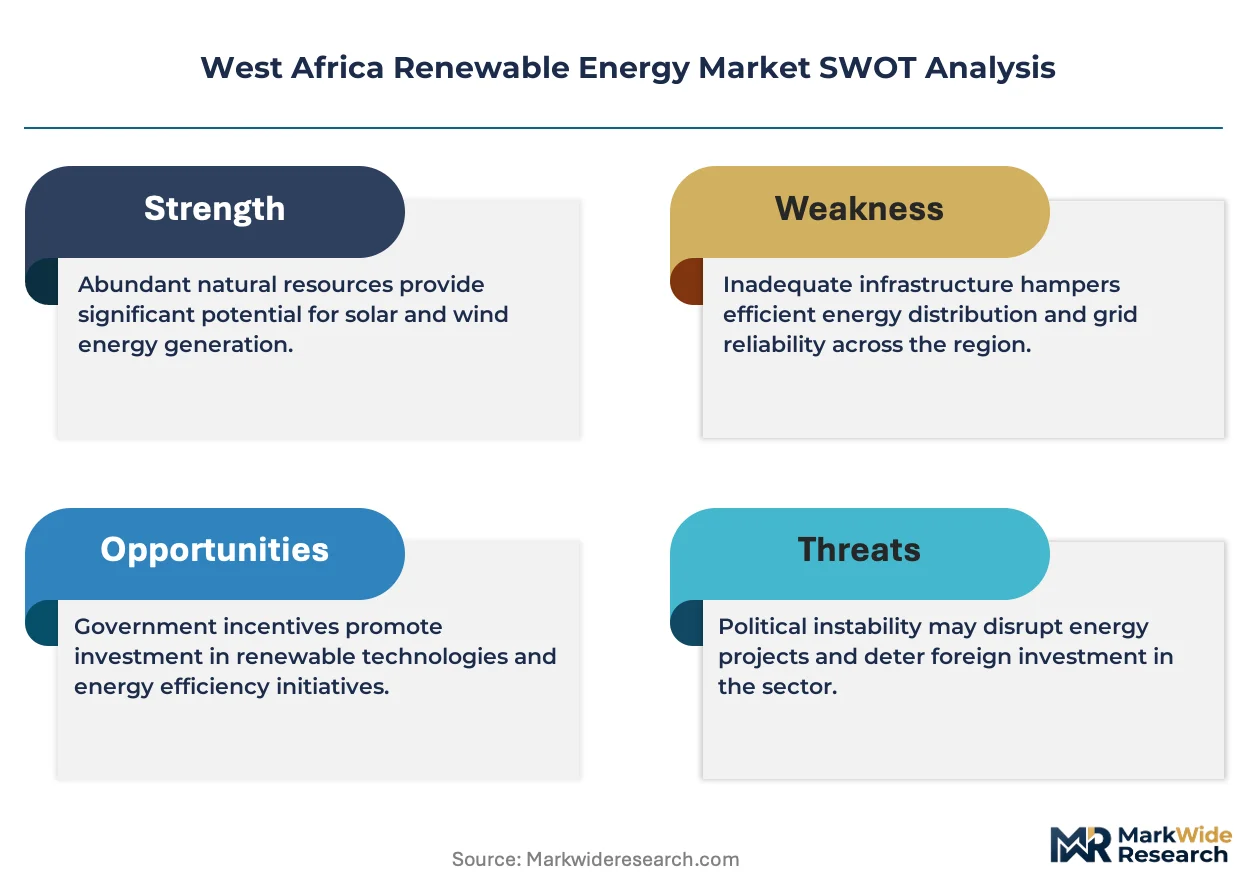
Diesel generation cost parity collapse is forcing capital reallocation toward solar-hybrid microgrids across ECOWAS member states, with national feed-in tariff revisions compressing project development timelines from feasibility to financial close.
Growth Catalysts
- ECOWAS Renewable Energy Policy:Harmonized licensing frameworks reduce cross-border equipment certification burdens, accelerating multi-country portfolio deployment for independent power producers.
- Agricultural cooperatives:Productive-use electrification programs channel development finance toward irrigation pumping and cold chain infrastructure, anchoring rural demand.
- Containerized solar leasing:Modular deployment models eliminate upfront capital barriers for commercial off-takers in markets with shallow banking penetration.
Market Restraints
- Currency convertibility risk:Naira and Leone volatility against dollar-denominated equipment imports inflate levelized cost of electricity calculations beyond tariff affordability thresholds.
- Grid instability:Weak transmission infrastructure in Nigeria and Ghana forces hybrid system oversizing, inflating battery storage requirements per installed megawatt.
- Diesel price subsidies:Nigeria's petroleum product price controls sustain artificial cost advantages for fossil backup generation in commercial applications.
Strategic Opportunities
- Sierra Leone rural corridors:Decentralized microgrid architectures address electrification gaps beyond 50 kilometers of existing transmission, unlocking agricultural processing demand.
- AfCFTA equipment sourcing protocols:Local content requirement harmonization enables consolidated procurement across Senegal, Ghana, and Nigeria, reducing logistics premiums.
- Solar-wind-battery convergence:Hybrid system integration with lithium-ion storage and small-scale wind turbines extends productive hours for commercial off-takers.
Industry Challenges
- Grid code compliance timelines:Nigeria's Electricity Regulatory Commission certification processes for inverter and battery systems extend project commissioning by four to eight months.
- Technical workforce scarcity:Photovoltaic installation and battery management system commissioning skills concentrate in Lagos and Accra, constraining rural deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Renewable Energy Market |
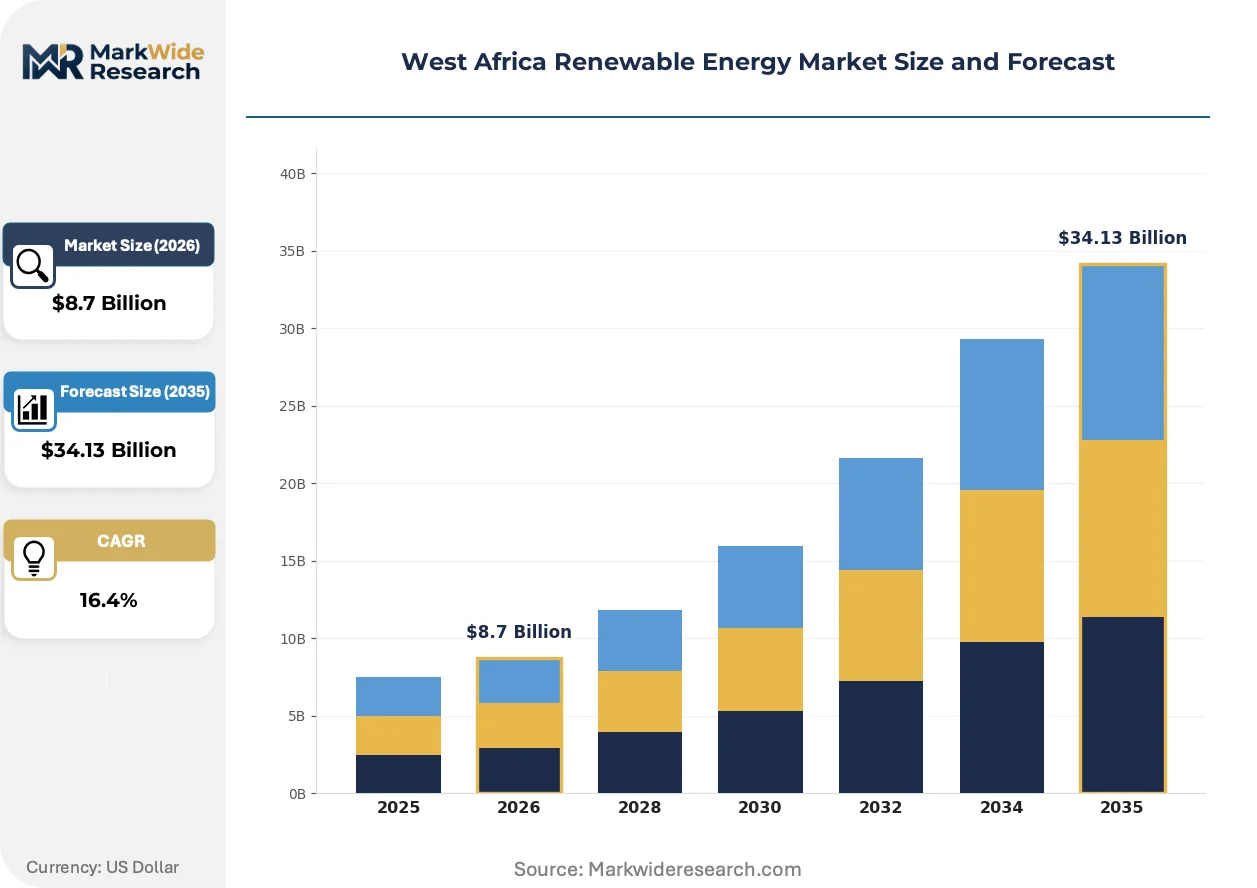
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydropower System Type: Grid-Tied, Off-Grid, Hybrid, Microgrid Application: Commercial, Residential, Industrial, Agricultural Technology: Photovoltaic, Concentrated Solar Power, Turbines, Biogas |
| Companies Covered | Energicity Corp, Sterling & Wilson Renewable Energy, REDAVIA GmbH, Masdar (Abu Dhabi Future Energy Company), Infinity Power Holding, China Civil Engineering Construction Corporation, Power Construction Corporation of China, Oolu, Wärtsilä Oyj Abp, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Renewable Energy Market Evolving Landscape
Capital deployment is rotating toward integrated energy-as-a-service models that bundle generation, storage, and demand management under long-term power purchase agreements, compressing customer acquisition costs and operational risk allocation.
Containerized solar-plus-storage systems is electrifying commercial and industrial load centers previously served by diesel gensets, with mining operations and telecom tower operators adopting these configurations fastest due to remote location requirements and 24-hour reliability needs; this technology convergence is electrifying the displacement pathway for liquid fuel backup across West African extraction and communications infrastructure.
Ghana's Energy Commission has tightened renewable energy licensing requirements to mandate local engineering participation in project development, compelling foreign developers to establish joint ventures with Accra-based technical partners; this regulatory pivot is compressing pure foreign direct investment flows while expanding domestic engineering capacity in utility-scale solar deployment.
Power purchase agreement tenor preferences are shortening among commercial off-takers, with agricultural processors and cold chain operators now demanding five-to-seven-year contracts versus traditional fifteen-year structures; this buyer behavior shift is forcing developers toward merchant revenue exposure or battery-backed peak shaving services to recover capital, most visible in Senegal's groundnut processing corridor and Nigeria's tomato paste concentration facilities.
West Africa Renewable Energy Market Segmentation
Segmentation reveals how deployment patterns diverge across West Africa's heterogeneous electrification landscape. Resource endowments, grid proximity, and customer creditworthiness fragment the addressable market into distinct investment profiles requiring tailored technology configurations.
Energy Source:
Technology choice hinges on irradiance mapping, river flow data, and agricultural residue availability across the ECOWAS corridor.
- Solar:Photovoltaic arrays dominate installed capacity due to 4.5-6.5 kWh/m² daily irradiance across the Sahel and coastal zones. Nigeria's northern states and Senegal's groundnut basin anchor utility-scale procurement, though currency volatility inflates module import costs beyond tariff ceilings.
- Wind:Onshore turbines concentrate in coastal Ghana and Senegal where Atlantic trade winds sustain 6-8 m/s annual averages. Technical workforce scarcity in Takoradi and Dakar constrains commissioning velocity for multi-megawatt installations.
- Biomass:Agricultural digesters process cassava waste and rice husks in Nigeria's Niger Delta and Sierra Leone's wetland corridors.
- Hydropower:Small-to-medium run-of-river installations exploit Guinea's Fouta Djallon highlands and Ghana's Volta tributaries.
Mature deployment sits with Solar. Newer deployment is concentrated in Biomass.
System Type:
Grid infrastructure quality dictates whether projects interconnect, isolate, or hybridize across Nigeria, Ghana, and Senegal.
- Grid-Tied:Large-scale solar farms feed into Ghana's 161kV backbone and Senegal's SENELEC network under feed-in tariff contracts. Nigeria's transmission losses exceeding 40% force developers toward captive offtake arrangements rather than export.
- Off-Grid:Stand-alone systems electrify communities beyond 50 kilometers of existing infrastructure in Liberia's Lofa County and Sierra Leone's Kono District. Diesel price subsidies in Nigeria sustain artificial cost competition for commercial applications.
- Hybrid:Solar-diesel-battery configurations displace liquid fuel backup at Nigerian telecom towers and Ghanaian mining camps. Battery storage requirements inflate 30-50% above nameplate capacity due to grid instability forcing oversizing.
- Microgrid:Decentralized architectures cluster generation, storage, and distribution for agricultural cooperatives in Senegal's groundnut processing corridor. Containerized deployment models reduce capital barriers for commercial off-takers with shallow banking access.
Grid-Tied systems absorb the largest capital commitments. Hybrid configurations are expanding most quickly as battery costs decline.
Application:
Customer credit profiles and load predictability segment the market across productive-use and consumption-driven demand.
- Commercial:Cold chain operators, telecom tower companies, and retail banks constitute the most bankable off-taker class. Power purchase agreement tenors are compressing from fifteen years toward five-to-seven-year structures, forcing developers toward merchant exposure or peak shaving services.
- Industrial:Mining operations and cement manufacturers in Ghana's Tarkwa corridor and Nigeria's Edo State anchor the largest contracted megawatt volumes. 24-hour reliability requirements drive rapid adoption of solar-plus-storage displacing diesel gensets.
- Residential:Pay-as-you-go solar home systems penetrate urban peripheries and secondary cities with established mobile money rails.
- Agricultural:Irrigation pumping and post-harvest processing electrification channels development finance toward cooperatives in Sierra Leone's rice belts and Senegal's horticulture zones.
Industrial off-takers command premium pricing certainty. Agricultural applications attract the fastest policy attention from ECOWAS rural electrification mandates.
Technology:
Equipment specifications differentiate between modular distributed generation and centralized thermal conversion systems.
- Photovoltaic:Crystalline silicon modules and string inverters constitute the standardized technology stack for utility and commercial deployment. Nigeria's Electricity Regulatory Commission certification processes extend commissioning timelines four to eight months for inverter and battery systems.
- Concentrated Solar Power:Parabolic trough and tower configurations with molten salt storage remain pre-commercial across West Africa due to higher capital intensity and water requirements for cooling.
- Turbines:Horizontal-axis wind turbines predominate in coastal installations, with Ghanaian and Senegalese projects sourcing European and Chinese OEMs.
- Biogas:Anaerobic digesters and gas engines convert agricultural and municipal organic waste to electricity in Nigeria's Abia State and Ghana's Ashanti Region.
Photovoltaic technology anchors current deployment. Biogas represents the steepest expansion trajectory as waste-to-energy regulations tighten across ECOWAS capitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for renewable energy across West Africa concentrates in Nigeria, Ghana, and Senegal, where diesel generation cost parity collapse and rural electrification mandates are accelerating capital deployment toward solar-hybrid microgrids and utility-scale photovoltaic installations.
Nigeria
Telecom tower operators and cement manufacturers in Edo State and the northern states anchor industrial demand for solar-plus-storage systems displacing diesel gensets. The Electricity Regulatory Commission enforces grid codes and licensing frameworks that extend inverter and battery certification timelines by four to eight months. Lagos hosts the largest concentration of photovoltaic installation and battery management system commissioning skills, constraining rural deployment velocity to secondary cities.
Ghana
Mining operations in the Tarkwa corridor and cold chain operators in Accra drive commercial and industrial procurement of hybrid configurations integrating lithium-ion storage. The Energy Commission has tightened licensing requirements to mandate local engineering participation, compelling foreign developers to establish joint ventures with Accra-based technical partners. The 161kV transmission backbone in the Ashanti Region anchors utility-scale solar farms under feed-in tariff contracts.
Senegal
Groundnut processing cooperatives and horticulture zones in the groundnut basin generate agricultural demand for decentralized microgrid architectures. The Commission de Régulation du Secteur de l'Electricité administers tariff methodologies that determine project bankability timelines. Dakar and the coastal zone concentrate onshore wind development where Atlantic trade winds sustain 6-8 m/s annual averages, though technical workforce scarcity constrains multi-megawatt commissioning velocity.
Sierra Leone
Rice belt cooperatives and agricultural processors in Kono District and Lofa County beyond 50 kilometers of existing transmission infrastructure drive productive-use electrification demand. National rural electrification programs channel development finance toward irrigation pumping and post-harvest processing infrastructure. Containerized solar leasing models reduce capital barriers for commercial off-takers with shallow banking access in Freetown peripheries.
Liberia
Off-grid communities in Lofa County and rubber plantation processing facilities anchor demand for stand-alone solar systems and agricultural biomass digesters. The ECOWAS Centre for Renewable Energy and Energy Efficiency harmonizes equipment certification standards, reducing cross-border logistics premiums for developers operating multi-country portfolios. Monrovia-based mobile money rails enable pay-as-you-go solar home system penetration in urban peripheries.
West Africa Renewable Energy Market Competitive Landscape
Nigerian and Ghanaian project developers anchor one tier of the competitive structure; European and Gulf-based energy specialists hold another through utility-scale solar deployment expertise and decentralized microgrid architectures. The vendor base stratifies across integrated EPC contractors, containerized leasing operators, and development finance-backed rural electrification platforms. Three archetypes dominate: utility-scale solar developers, microgrid specialists targeting agricultural cooperatives, and energy-as-a-service providers bundling generation with demand management. Competitive intensity concentrates on strategic partnerships with local engineering firms and compressed power purchase agreement tenor structures.
Among the microgrid specialists, Energicity Corp exemplifies the decentralized rural electrification archetype through Sierra Leone and Liberia operations. Sterling & Wilson Renewable Energy occupies a position representing integrated EPC capability for utility-scale deployment. REDAVIA GmbH anchors the containerized solar leasing tier, reducing upfront capital barriers for commercial off-takers in markets with constrained banking penetration.
| Leading Market Players |
|---|
| Energicity Corp |
| Sterling & Wilson Renewable Energy |
| REDAVIA GmbH |
| Masdar (Abu Dhabi Future Energy Company) |
| Infinity Power Holding |
| China Civil Engineering Construction Corporation |
| Power Construction Corporation of China |
| Oolu |
| Wärtsilä Oyj Abp |
| Others |
Value Network & Pricing Analysis
Captive integration into lithium-ion battery assembly and module manufacturing anchors both supply security and margin retention for developers confronting currency volatility across Nigeria, Ghana, and Senegal. This backward control over storage costs determines project bankability where dollar-denominated equipment imports inflate levelized electricity calculations beyond tariff ceilings.
Pricing Analysis
Volume procurement by industrial mining operators and cement manufacturers commands standard-tier pricing, while agricultural cooperatives with shallow banking access face premium capital recovery rates under shorter power purchase agreement tenors. Price differentiation hinges on offtaker creditworthiness and local engineering participation mandates from Ghana's Energy Commission. Cost compression in commercial segments intensifies as containerized solar leasing models proliferate. Telecom tower operators exhibit the lowest price sensitivity due to 24-hour reliability requirements; rural agricultural processors remain the most price-constrained buyer class.
Supply Chain Analysis
Dual-sourcing requirements from ECOWAS Centre for Renewable Energy and Energy Efficiency protocols compel developers to qualify module suppliers from both China and Southeast Asian manufacturing hubs. Photovoltaic cells and lithium-ion battery packs flow predominantly from Chinese and South Korean production centers, with inverter systems sourced from European and Chinese OEMs. Tariff exposure on steel mounting structures and aluminum frames creates margin vulnerability for EPC contractors. Distribution runs through Accra, Lagos, and Dakar logistics corridors before final-mile deployment to rural microgrid sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over battery storage supply chains determines which developers survive compressed power purchase agreement tenors and currency volatility. Captive sourcing of lithium-ion systems represents the decisive upstream lever.
For Market Incumbents: Extend EPC capabilities into long-term asset ownership and operation, converting one-time construction margins into recurring energy-as-a-service revenue streams. Consolidate around Accra-based engineering joint ventures mandated by Ghana's tightened licensing requirements to defend against pure foreign capital inflows. Secure captive battery supply agreements with Chinese cell manufacturers before regional procurement competition intensifies. For New Entrants and Emerging Players: ECOWAS Renewable Energy Policy harmonization across member states opens a window for multi-country portfolio deployment with standardized equipment certification. Target Sierra Leone's rural corridors beyond 50 kilometers of transmission infrastructure where agricultural processing demand remains unserved. Pursue containerized solar leasing models that eliminate upfront capital barriers for commercial off-takers with constrained banking access. For Investors and Strategic Acquirers: Exit pathways concentrate in energy-as-a-service platform acquisitions by integrated utilities seeking operational capabilities without greenfield development risk. Long-term viability favors developers with backward integration into storage systems and established local engineering joint ventures. Watch for feed-in tariff revision announcements across Nigeria, Ghana, and Senegal as the signal for capital deployment acceleration or retrenchment.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | Shorter tenors with telecom tower operators like IHS Towers reduce counterparty risk exposure. |
| Vertical Integration into Battery Storage | Captive lithium-ion supply chains insulate developers from currency-driven cost volatility. |
| Local Engineering Joint Ventures | Ghana's Energy Commission mandates Accra-based participation, compressing pure foreign investment flows. |
| Containerized Solar Leasing Expansion | Modular deployment models unlock commercial demand in Freetown peripheries with shallow banking penetration. |
| Multi-Country Portfolio Harmonization | ECOWAS equipment certification standards reduce logistics premiums across Senegal, Ghana, and Nigeria. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators across Lagos, Accra, and Dakar. Bottom-up project pipeline analysis triangulated against top-down ECOWAS electrification target assessments. Secondary validation drew from Nigeria Electricity Regulatory Commission licensing databases, Ghana Energy Commission procurement registers, and Senegal Commission de Régulation du Secteur de l'Electricité tariff filings.
Granularity-level modeling disaggregated capacity additions by energy source, system type, application, and technology configuration across the projection horizon. Analytical frameworks incorporated diesel generation cost parity trajectories, currency volatility scenarios, and rural electrification program disbursement timelines. CAGRs derived from segment-level unit economics and policy implementation velocity rather than aggregate market extrapolation. Forecast inputs included battery cost decline curves and transmission infrastructure investment schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery storage or green hydrogen backup would alter the outlook for hybrid system configurations. Deviation in ECOWAS feed-in tariff implementation timelines or AfCFTA local content requirement enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Solar Boat Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Ocean Power Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market