
 Solar Highway Market | 2026-2036
Solar Highway Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Highway Market Analytics
Transportation agency procurement is broadening as the dominant demand channel for solar highway deployments. Wattway leverages its parent Colas Group's civil engineering scale to anchor European project pipelines. Canadian Solar competes on module cost structure and manufacturing scale across North American bids. Solar Roadways specializes in embedded LED-integrated surface systems that differentiate its offering from standard photovoltaic overlays.
A solar highway integrates photovoltaic cells into road surfaces, typically using tempered glass or composite overlays with load-bearing capacity exceeding 12 tons per axle to capture solar energy while supporting vehicle traffic. The primary purpose is decentralized electricity generation for grid injection, roadside infrastructure, or electric vehicle charging without additional land use. Photovoltaic panel technology dominates current installations due to proven efficiency metrics and established supply chains, while smart grid integration represents the fastest-expanding segment as utilities require bidirectional power management. Energy generation applications command the largest revenue share, though charging station deployment is accelerating fastest as electric vehicle penetration rises.
The EU Green Deal and F-Gas Regulation shape product standards for embedded electrical systems across European solar highway projects, while the US Department of Transportation's Federal Highway Administration guidelines influence surface safety certification stateside. China's MIIT issues GB standards for photovoltaic integration in transportation infrastructure that affect export compatibility for international suppliers. Stakeholders must monitor evolving load-testing protocols and grid interconnection rules as these will determine which technology configurations achieve commercial viability at scale.
Market Dynamics
Transportation electrification mandates are compressing deployment timelines for photovoltaic road surfaces as utilities and highway authorities seek distributed generation assets without land-use expansion.
Growth Catalysts
- EU Green Deal infrastructure mandates:The EU Green Deal's decarbonization targets require member states to integrate renewable generation into transportation corridors, creating binding procurement obligations for national highway agencies.
- Embedded LED-integrated surface systems:Smart road technologies that combine photovoltaic capture with dynamic lane marking and traffic management are attracting municipal buyers seeking multi-function infrastructure assets.
- France:Operational precedent from pilot installations has established technical validation and risk reduction for transportation agencies evaluating first commercial deployments.
Market Restraints
- Silicon supply concentration:Photovoltaic cell manufacturing depends on polysilicon refining capacity concentrated in China, exposing project developers to input cost volatility and trade policy friction.
- Load-bearing composite material costs:Tempered glass and specialized polymer substrates required for vehicle-weight tolerance carry 3-4x cost premiums versus standard module encapsulation.
- Grid interconnection queue delays:Utility approval processes for distributed generation assets create 18-36 month project timelines that erode developer returns.
Strategic Opportunities
- Electric vehicle charging corridor deployment:Highway rest stop and service plaza electrification creates anchor demand for solar highway segments with guaranteed offtake through charging station operators.
- Bidirectional power management integration:Smart grid convergence with vehicle-to-grid protocols enables solar highways to function as dispatchable storage assets, opening utility-scale revenue streams.
- US Department of Transportation Federal Highway Administration guidelines:Surface safety certification standards being finalized will unlock federal funding mechanisms for state transportation department pilots.
Industry Challenges
- Electromechanical systems integration:Embedded wiring, junction boxes, and thermal management components must survive decades of vibration, thermal cycling, and moisture ingress under dynamic vehicle loading.
- Skilled installation workforce scarcity:Civil contractors lack training in photovoltaic electrical work, while solar installers lack heavy highway construction certifications, creating project execution bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Highway Market |
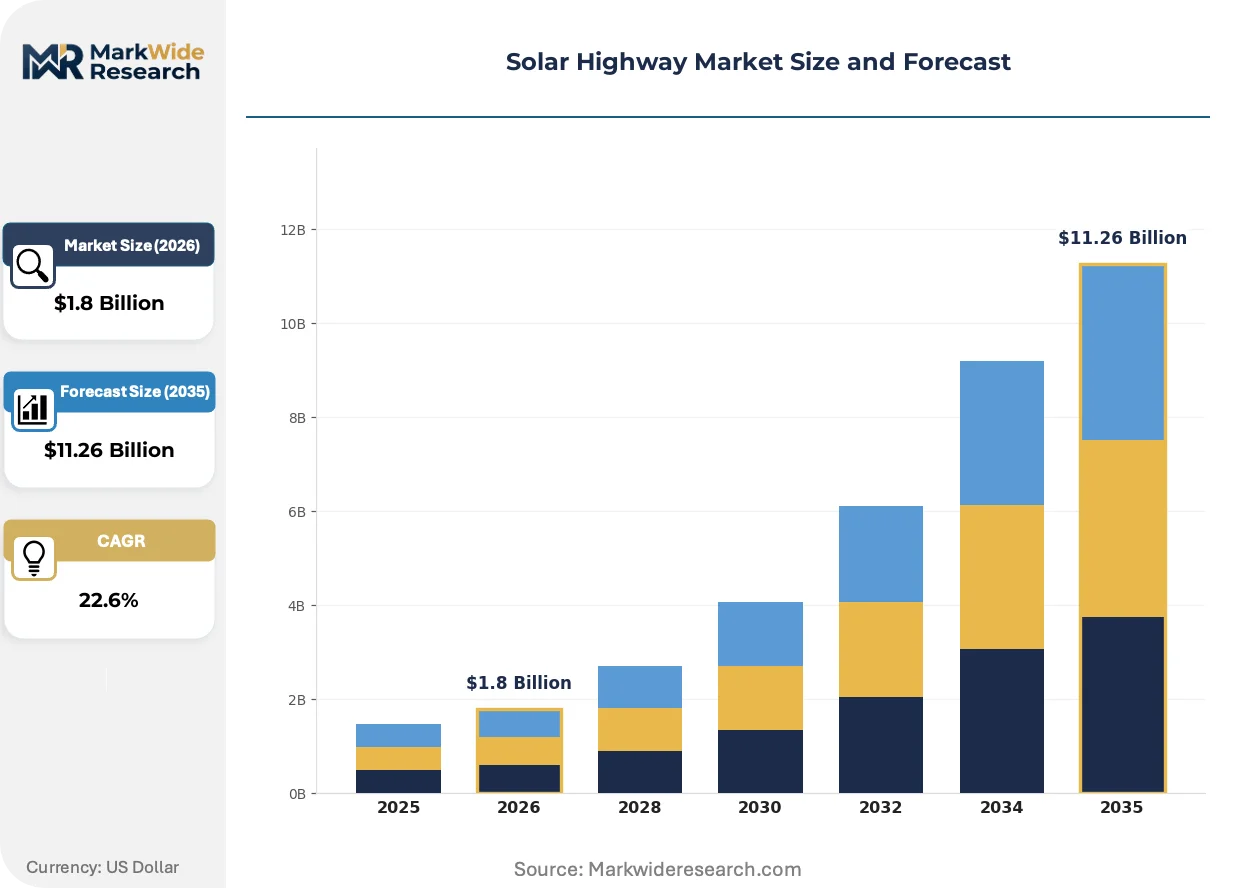
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.26 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic Panels, Solar Roadways, Integrated Systems, Smart Grids Application: Highway Lighting, Energy Generation, Charging Stations, Safety Markings End User: Government, Infrastructure Developers, Urban Planners, Transportation Agencies Installation Type: Retrofit, New Construction, Maintenance, Temporary Installations |
| Companies Covered | Wuxi Suntech Power Co Ltd, Wattway, Onyx Solar Energy, PLATIO Solar, Colas Group, Solar Roadways, Canadian Solar, SunPower, SolaRoad Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Highway Market Evolving Landscape
Photovoltaic road surface technology is maturing from demonstration projects toward standardized product platforms as buyers demand predictable performance warranties and installation protocols.
Perovskite-silicon tandem cell architectures are consolidating research investment from module manufacturers seeking higher conversion efficiency in limited surface areas. Highway authorities in Germany and the Netherlands are evaluating pilot specifications that specify minimum wattage per lane-meter. This technology compression is forcing crystalline silicon suppliers to demonstrate cost-performance parity against emerging thin-film alternatives.
The EU F-Gas Regulation is restricting fluorinated greenhouse gases used in conventional heat pump and cooling systems, indirectly accelerating interest in embedded road-surface heating as an alternative to mechanical snow removal. Project developers are responding by integrating resistive heating elements into composite substrates for cold-climate installations. Nordic transportation agencies are now specifying active de-icing capability as a procurement requirement.
Bid requests from transportation agencies are bundling energy generation, smart lighting, and traffic sensor infrastructure into single-source contracts rather than discrete component purchases. System integrators with civil engineering credentials are displacing pure-play solar developers in competitive bidding. This pattern is most pronounced in France and Germany where Colas Group and similar infrastructure conglomerates control project pipelines.
Solar Highway Market Segmentation
Technology choices in solar highways determine capital intensity, operational lifespan, and revenue model flexibility. Application focus shapes whether projects prioritize grid injection, direct consumption, or multi-functional infrastructure services. Understanding these segment boundaries enables suppliers to align R&D investment with procurement patterns.
Technology:
Buyers differentiate by integration complexity versus performance predictability, with risk-averse transportation agencies favoring proven platforms.
- Photovoltaic Panels:Crystalline silicon cells encapsulated in tempered glass or composite substrates deliver standardized efficiency metrics with established supply chains. Demand concentrates in France and Germany where Wattway and national pilot programs require bankable technology with decade-long performance warranties. The EU Green Deal's binding procurement obligations favor this segment for initial commercial scale.
- Solar Roadways:Embedded LED-integrated surface systems combine photovoltaic capture with dynamic lane marking, traffic sensing, and data transmission. Municipal buyers in the Netherlands and Denmark seek multi-function infrastructure assets that justify premium installed costs through consolidated maintenance budgets.
- Integrated Systems:Modular platforms bundle generation, storage, and grid interconnection hardware into factory-tested units.
- Smart Grids:Bidirectional power management architectures enable vehicle-to-grid protocols and utility dispatchability.
Volume sits with Photovoltaic Panels; growth tilts toward Smart Grids.
Application:
Revenue model clarity separates segments—some generate merchant electricity, others monetize through avoided infrastructure costs.
- Energy Generation:Grid-connected photovoltaic road surfaces feed centralized electricity markets or power purchase agreements. Highway authorities in Germany specify minimum wattage per lane-meter, compressing technology selection toward high-efficiency configurations.
- Charging Stations:Rest stop and service plaza electrification creates guaranteed offtake through charging station operators. France's operational precedent has validated technical performance for corridor deployment.
- Highway Lighting:Direct consumption models eliminate interconnection queues and utility dependency.
- Safety Markings:Embedded illumination reduces maintenance labor versus painted lane markings.
Revenue share concentrates in Energy Generation; steepest expansion trajectory belongs to Charging Stations.
End User:
Procurement scale and decision velocity vary sharply—national agencies move slowly with large volumes, while urban planners execute faster with smaller tickets.
- Transportation Agencies:National highway authorities in France, Germany, and the Netherlands issue multi-kilometer tenders with performance-based specifications. EU F-Gas Regulation compliance requirements and EU Green Deal mandates create binding procurement obligations.
- Government:Federal and state ministries fund pilot programs through infrastructure stimulus mechanisms.
- Infrastructure Developers:Private concessionaires seek revenue diversification across toll road portfolios.
- Urban Planners:Municipal departments prioritize pedestrian safety and smart city integration over generation capacity.
Contract value peaks with Transportation Agencies; deal velocity favors Urban Planners.
Installation Type:
Project risk allocation and margin structure hinge on whether work occurs within existing traffic corridors or greenfield rights-of-way.
- New Construction:Greenfield highway projects integrate photovoltaic surfaces during initial civil works, eliminating retrofit coordination costs. Nordic agencies specify active de-icing capability as standard procurement requirements.
- Retrofit:Overlay installation on operational roadways requires lane closure management and accelerated construction schedules.
- Maintenance:Scheduled resurfacing cycles create predictable replacement demand.
- Temporary Installations:Event-based or pilot deployments validate technology before permanent commitment.
Project pipeline depth rests with New Construction; margin expansion concentrates in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes the dominant share of installed solar highway capacity, while China concentrates photovoltaic cell manufacturing. Germany and the Netherlands validate pilot specifications that shape procurement standards across the continent.
France
Wattway's operational precedent in Normandy and Tourouvre-au-Perche has established technical validation for photovoltaic road surfaces. The EU Green Deal mandates binding infrastructure decarbonization targets for national highway agencies. Colas Group's civil engineering scale anchors project pipelines through the Île-de-France and Auvergne-Rhône-Alpes regions.
Germany
Federal highway authorities specify minimum wattage per lane-meter, compressing technology selection toward high-efficiency configurations. The KBA enforces surface safety certification standards that influence embedded electrical system designs. Pilot deployments cluster in Baden-Württemberg and Bavaria where automotive corridor electrification intersects with renewable generation planning.
Netherlands
Municipal buyers in Amsterdam and Rotterdam seek multi-function infrastructure assets combining generation with smart traffic management. The EU F-Gas Regulation accelerates interest in embedded road-surface heating alternatives to mechanical snow removal. SolaRoad's pilot in Krommenie provides operational data for North Holland's expanding cycle path electrification programs.
United States
State transportation departments await finalized Federal Highway Administration surface safety certification standards to unlock federal funding mechanisms. The Department of Transportation guidelines influence load-testing protocols for vehicle-weight tolerance. Solar Roadways maintains development activity in Idaho and the Pacific Northwest for LED-integrated surface systems.
China
MIIT issues GB standards for photovoltaic integration in transportation infrastructure that affect export compatibility for international suppliers. Polysilicon refining capacity concentration creates input cost leverage across downstream project economics. Manufacturing clusters in Jiangsu and Zhejiang provinces supply crystalline silicon cells for tempered glass encapsulation systems.
Solar Highway Market Competitive Landscape
Top-tier vendors anchor civil engineering conglomerates with highway construction credentials, while specialized photovoltaic developers occupy technology demonstration niches. The vendor base stratifies across infrastructure-scale integrators, module manufacturers competing on cost structure, and smart surface specialists pursuing differentiated functionality. Three archetypes dominate: civil engineering conglomerates leveraging existing procurement relationships, photovoltaic module suppliers adapting standard products for load-bearing applications, and embedded systems innovators integrating LED and sensor capabilities. Competitive moves concentrate on strategic partnerships between solar developers and highway contractors, plus technology licensing agreements that transfer surface encapsulation intellectual property.
Among infrastructure-integrated conglomerates, Colas Group and Wattway exemplify the civil engineering archetype with parent-subsidiary structures enabling turnkey project delivery. Canadian Solar and SunPower represent module-centric competitors adapting crystalline silicon platforms for transportation applications. Solar Roadways occupies a position within the embedded systems tier, specializing in surface-integrated electronics that differentiate from standard photovoltaic overlays.
| Leading Market Players |
|---|
| Wuxi Suntech Power Co Ltd |
| Wattway |
| Onyx Solar Energy |
| PLATIO Solar |
| Colas Group |
| Solar Roadways |
| Canadian Solar |
| SunPower |
| SolaRoad Inc |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's binding infrastructure decarbonization mandates gate qualified supply access and premium-tier pricing power, compressing procurement timelines while concentrating certified supplier margins among civil engineering conglomerates with established highway agency relationships.
Pricing Analysis
Margin tightening in high-efficiency photovoltaic panel tiers reflects polysilicon input volatility and tempered glass encapsulation premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and load-bearing performance warranty duration. Pricing pressure stems from Chinese module manufacturers competing on crystalline silicon cost structure. Transportation agencies exhibit lowest price sensitivity due to EU Green Deal procurement obligations, while municipal urban planners demand economy-tier solutions.
Supply Chain Analysis
Polysilicon refining capacity rests on Chinese manufacturing clusters in Jiangsu and Zhejiang provinces. Crystalline silicon cells, tempered glass substrates, and specialized polymer encapsulation materials constitute critical input dependencies. Single-source vulnerability concentrates in photovoltaic cell supply. Distribution runs through civil engineering conglomerates with established highway construction certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a compliance moat that elevates certified suppliers above uncertified competitors, embedding cost-of-entry barriers into cold-climate procurement specifications.
For Market Incumbents: Deploy backward integration into polysilicon supply to buffer input cost volatility from Chinese concentration. Anchor project pipelines through Colas Group-style parent-subsidiary structures that bundle civil engineering scale with photovoltaic expertise. Perovskite-silicon tandem research investment represents a defensive lever against thin-film displacement. For New Entrants and Emerging Players: Direct-to-transportation-agency digital procurement portals offer white-space access bypassing incumbent relationship networks. Target Nordic markets specifying active de-icing capability as mandatory procurement requirements. LED-integrated surface systems provide differentiated entry against standard photovoltaic overlays. For Investors and Strategic Acquirers: Federal Highway Administration surface safety certification finalization is the leading indicator that unlocks US federal funding mechanisms and state transportation department pilot scale. Long-term viability centers on system integrators with civil engineering credentials displacing pure-play solar developers. Watch for KBA certification expansion as German standards propagate across continental procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Supply | Captive supply of crystalline silicon inputs buffers Wattway and Canadian Solar against Chinese trade policy friction. |
| Perovskite-Silicon Tandem R&D Investment | Higher conversion efficiency per lane-meter addresses German minimum wattage specifications compressing technology selection. |
| Civil Engineering Partnership Structuring | Colas Group's parent-subsidiary model anchors European project pipelines through turnkey delivery credibility. |
| Active De-Icing Capability Integration | Resistive heating elements satisfy Nordic procurement requirements accelerated by EU F-Gas Regulation restrictions. |
| Federal Highway Administration Certification Pursuit | Surface safety validation unlocks US Department of Transportation funding for state pilot programs. |
Research Methodology
Document review covered EU Green Deal implementation directives, Federal Highway Administration guideline drafts, and MIIT GB standards, complemented by interviews with highway authority procurement officers, EPC contractors, photovoltaic module technical directors, and smart grid integration specialists. Secondary validation drew from FERC interconnection queue data, customs trade records for tempered glass substrates, and national transportation agency tender databases. Bottom-up project pipeline aggregation triangulated against top-down infrastructure spending forecasts.
Installed capacity and revenue outputs trace segment-level buildups across technology, application, end user, and installation type dimensions throughout the forecast period. CAGRs derive from logistic diffusion curves fitted to pilot-to-commercial deployment trajectories. Load-bearing composite material cost curves and grid interconnection approval timelines constitute industry-specific model inputs.
The model holds under stable EU procurement mandate enforcement and Chinese polysilicon export continuity; deviation in trade policy severity or F-Gas Regulation scope expansion would shift deployment timelines. A small set of named triggers—Federal Highway Administration certification finalization, KBA safety standard adoption, and Nordic de-icing specification proliferation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
South Korea Renewable Energy Market