
 Solar Showers Market | 2026-2036
Solar Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Showers Market Analysis
Chinese vacuum tube manufacturing is shifting toward higher-efficiency coatings for solar thermal applications. Coleman Company Inc. leverages its established outdoor retail distribution to sustain volume leadership in North American camping channels. GROHE AG anchors premium positioning through its architectural fixed-shower designs for hospitality and residential poolside installations. HelioZ competes in the portable segment with ultralight systems targeting backcountry enthusiasts.
A solar shower is a self-contained water heating unit that uses solar thermal energy—typically via black polymer bags, flat-plate collectors, or evacuated glass tubes—to raise water temperature without electrical or fuel-based inputs, achieving operational temperatures of 100–140°F depending on ambient solar irradiance and collector design. The device serves off-grid sanitation needs across camping, emergency relief, and remote workforce housing applications. Portable showers occupy the largest volume share due to low entry cost and recreational buyer familiarity, while fixed showers capture stronger margin pools in commercial campground and resort deployments. Wall-mounted configurations represent the fastest-growing installation category as permanent outdoor living spaces expand in suburban markets.
EPA WaterSense guidelines influence product efficiency claims in the United States, while EU Ecodesign requirements and the F-Gas Regulation shape thermal component sourcing across European supply chains. ISO 9806 testing standards for solar thermal collectors provide baseline performance certification for cross-border trade. Stakeholders must monitor evolving building codes for outdoor plumbing and water heating efficiency as municipalities revise permit requirements for permanent backyard installations.
Market Dynamics
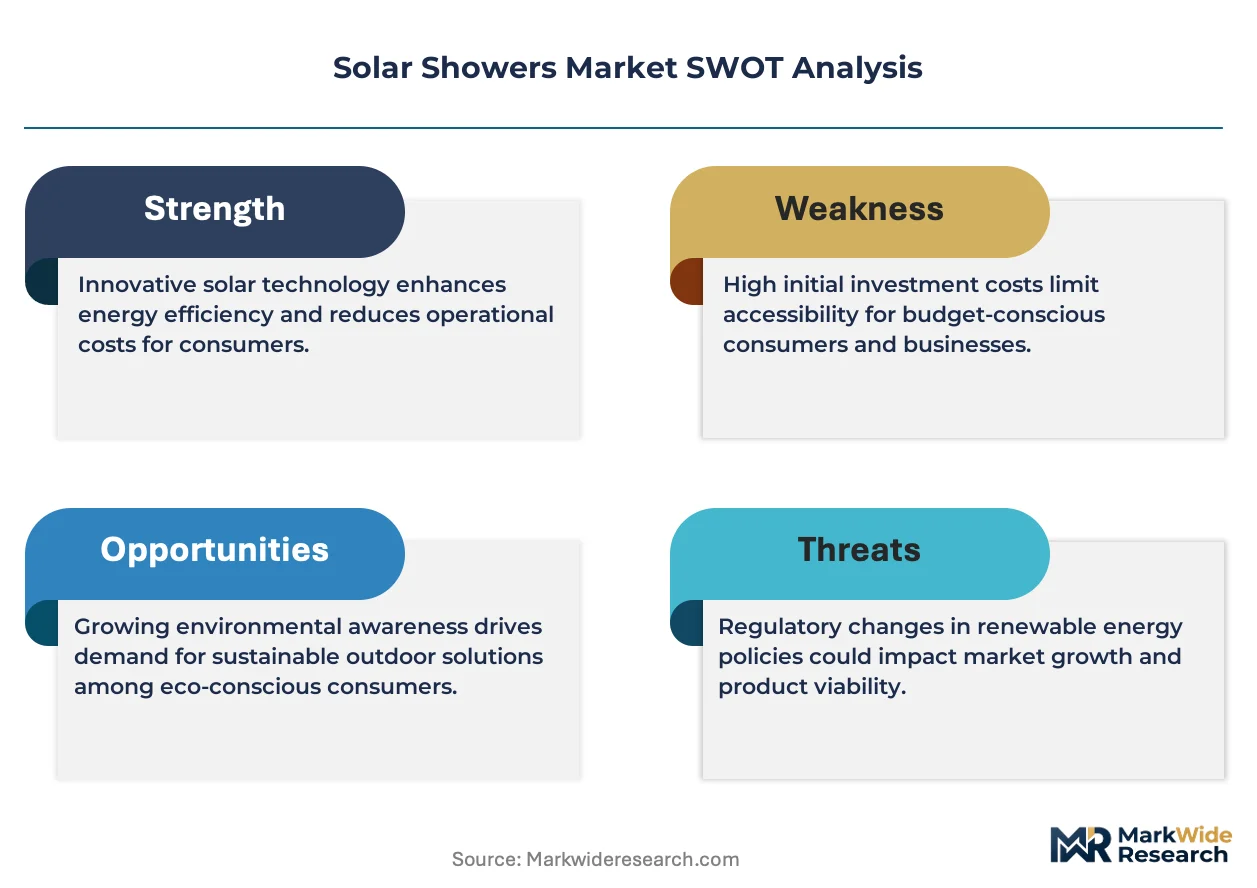
European campground operators face tightening sustainability mandates that accelerate fixed solar shower deployments, while vacuum tube thermal collector improvements extend operational viability into cooler northern climates previously served by fossil-fuel alternatives.
Growth Catalysts
- EU Ecodesign requirements:The directive mandates minimum thermal efficiency standards for outdoor water heating equipment, pushing commercial campgrounds toward certified solar thermal systems ahead of enforcement deadlines.
- Vacuum tube coatings:Chinese manufacturers advance selective absorption layer deposition techniques that boost collector efficiency in diffuse light conditions, expanding addressable geography into maritime and high-latitude zones.
- Suburban outdoor living:Permanent backyard kitchen and poolside installations in Germany, France, and Italy create steady demand for wall-mounted fixed showers with architectural integration.
Market Restraints
- Evacuated glass tube fragility:Transportation breakage rates during last-mile distribution to remote campgrounds inflate total installed costs and deter thin-margin operators.
- Copper and aluminum price volatility:Collector manifold and heat-exchanger fabrication depends on non-ferrous metal inputs exposed to commodity exchange fluctuations.
- F-Gas Regulation compliance costs:Heat-pump hybrid systems using synthetic refrigerants face phase-down quotas that constrain European supply chains and extend procurement timelines.
Strategic Opportunities
- Backcountry ultralight segment:Alpine guide services and thru-hiking communities in the Pyrenees and Dolomites seek sub-kilogram solar shower systems with integrated filtration.
- EU Green Deal renovation wave:Public funding streams for outdoor recreation infrastructure upgrades in Italy subsidize fixed shower installations at municipal campgrounds.
- IoT-enabled monitoring:Temperature sensors and mobile connectivity converge with solar thermal hardware to enable predictive maintenance for hospitality operators managing distributed shower assets.
Industry Challenges
- ISO 9806 certification timelines:Third-party thermal performance testing for evacuated tube collectors creates 4-6 month product launch delays that mismatch seasonal procurement cycles.
- Seasonal demand compression:Northern European campgrounds concentrate 70% of annual shower purchases into Q1-Q2 pre-season windows, straining manufacturer working capital and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Showers Market |
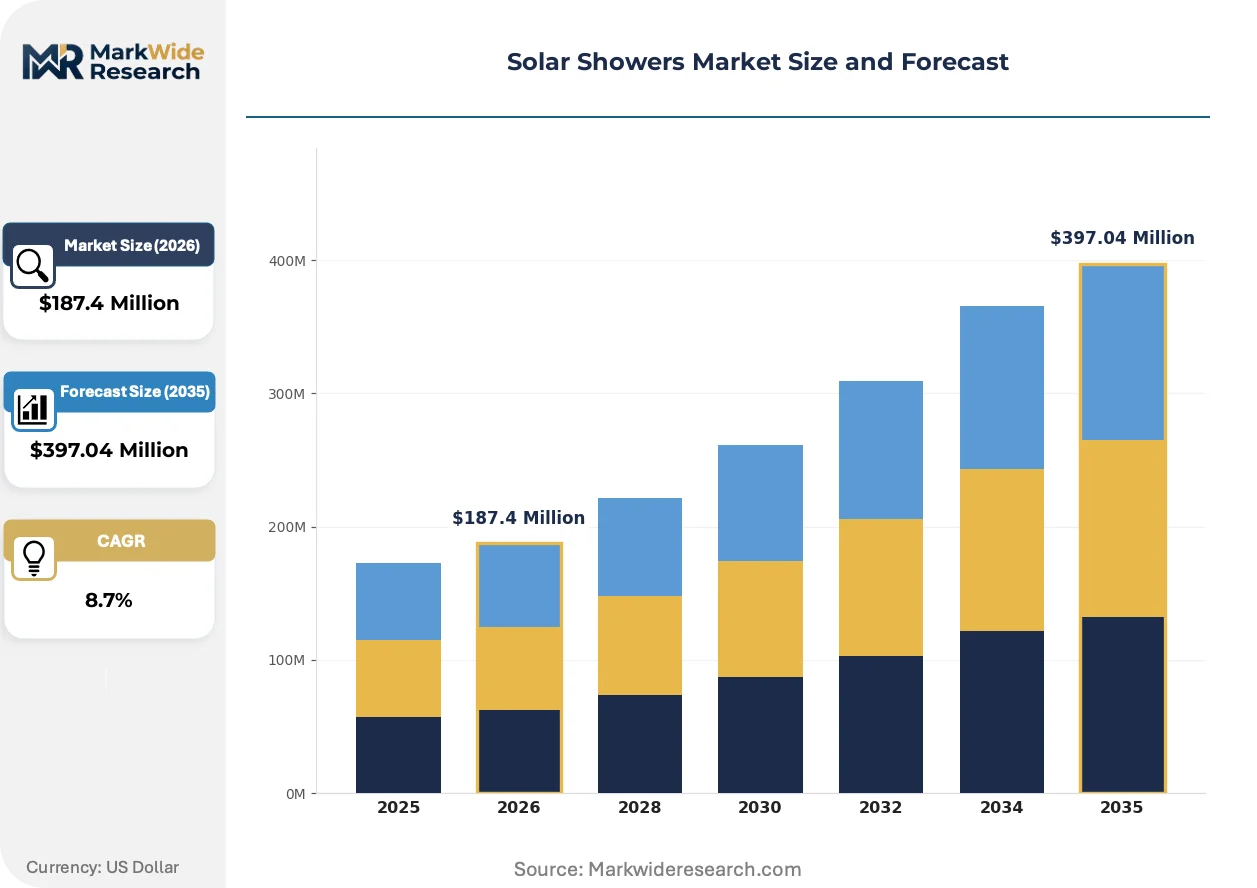
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Showers, Fixed Showers, Inflatable Showers, Wall-Mounted Showers Use Case: Camping, Outdoor Events, Backyard, Emergency Preparedness Installation: Standalone, Integrated, Temporary, Permanent Capacity: 5 Gallons, 10 Gallons, 15 Gallons, 20 Gallons |
| Companies Covered | GROHE AG, Coleman Company Inc., HelioZ, Kampa GmbH, Eccotemp Systems Inc., Zodi Outdoor Innovations, Geyser Systems, Nemo (Helio), Sunlight Supply Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Showers Market Emerging Trajectories
Product development in solar showers centers on thermal efficiency gains, regulatory compliance automation, and buyer-side operational intelligence that together reshape competitive positioning across portable and fixed installation categories.
Selective surface coatings on evacuated glass tubes is converging with anti-reflective outer layer treatments to push optical efficiency above 0.92 absorptance ratios. German hospitality operators with alpine and lakeside properties are adopting these collectors for poolside showers despite higher unit costs. The technology is converging with building-integrated solar thermal design standards that treat outdoor showers as architectural elements rather than utility appendages.
France's ANSM and DGCCRF coordinate with EU-level F-Gas enforcement to inspect heat-pump hybrid shower systems for refrigerant leak rates and service documentation. Manufacturers must redesign compressor-integrated units to use natural refrigerants or low-GWP alternatives before quota restrictions tighten. Fixed shower deployments in commercial campgrounds face the steepest compliance burden as operators cannot easily substitute failed units mid-season.
Campground procurement officers now bundle shower assets into 5-7 year facility management contracts with performance guarantees on hot water availability hours. Equipment suppliers compete on uptime commitments rather than unit price, displacing transactional spot purchasing. This shift concentrates most visibly in German Land-level municipal campground networks that centralize capital planning across multiple sites.
Solar Showers Market Segmentation
Solar shower procurement splits sharply between recreational buyers prioritizing portability and commercial operators optimizing for durability and regulatory compliance. Understanding these divergent purchase logics clarifies why identical thermal technologies command vastly different price premiums across installation contexts.
Product Type:
Buyers choose between mobility and permanence based on trip duration, infrastructure access, and seasonal storage constraints.
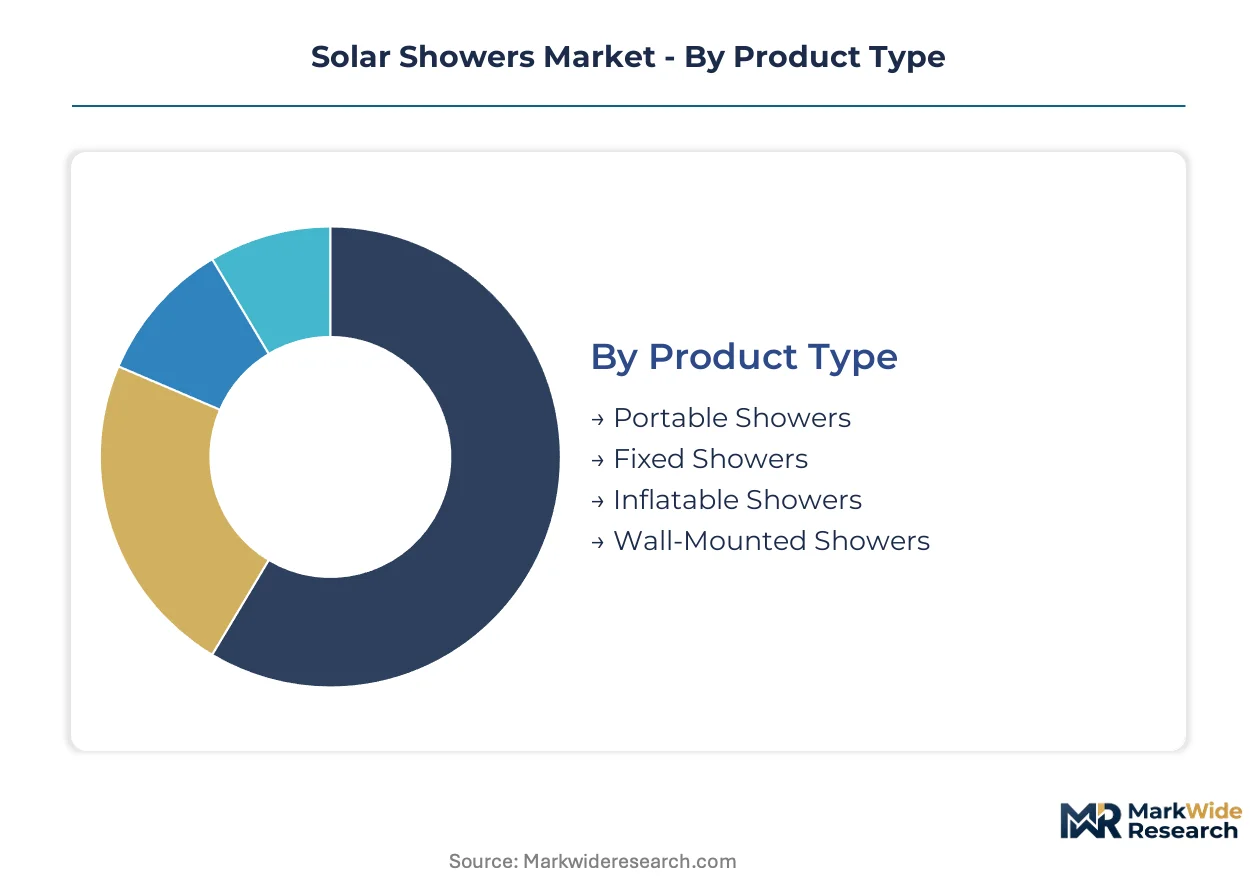
- Portable Showers:Black polymer bag systems with gravity-fed delivery dominate recreational sales through outdoor retail channels. Demand concentrates in Germany and France where weekend camping participation rates sustain high-volume turnover and replacement cycles.
- Fixed Showers:Rigid collector assemblies with plumbed drainage anchor commercial campground infrastructure investments. Italian municipal campground networks under EU Green Deal renovation subsidies drive procurement for permanent poolside and sanitary block installations.
- Inflatable Showers:Collapsible bladder designs with integrated foot pumps serve festival organizers and temporary event contractors seeking rapid deployment without structural permits.
- Wall-Mounted Showers:Architectural-grade evacuated tube collectors with building-integrated mounting brackets expand fastest in suburban German and French backyard kitchen projects.
Volume sits with Portable Showers; growth tilts toward Wall-Mounted Showers.
Use Case:
Application context determines thermal performance requirements, regulatory exposure, and replacement frequency.
- Camping:Weekend recreational trips sustain baseline demand for lightweight bag systems. German discount outdoor retailers move highest unit volumes through seasonal pre-season promotions.
- Outdoor Events:Music festivals and sporting gatherings in France and Italy drive rental fleet investments in rapid-setup shower infrastructure with minimal ground disturbance.
- Backyard:Permanent suburban outdoor living spaces in Italian and French residential markets create sustained demand for architecturally integrated fixed systems with municipal permit compliance.
- Emergency Preparedness:Humanitarian relief agencies and civil defense coordinators in Germany stockpile portable units for grid-disruption scenarios, prioritizing durability over heating speed.
Camping commands current volume; Backyard applications are climbing the fastest as permanent outdoor living investments mature.
Installation:
Permanence expectations shape buyer willingness to absorb foundation costs and regulatory compliance burdens.
- Standalone:Self-supporting frames with independent water reservoirs suit remote campgrounds lacking plumbing infrastructure. French alpine sites favor these for seasonal relocation flexibility.
- Integrated:Hard-plumbed connections to existing sanitary systems dominate Italian municipal campground upgrades receiving public infrastructure funding.
- Temporary:Rapid-assembly configurations without ground anchoring serve event contractors and seasonal operators in Germany seeking lease-compliant mobility.
- Permanent:Foundation-mounted systems with drainage integration capture strongest margins in French and Italian resort properties where architectural consistency matters.
Standalone units dominate transaction counts; Permanent installations gain share fastest on hospitality operator balance sheets.
Capacity:
User throughput requirements and heating time trade-offs drive sizing decisions across solo travelers versus group facilities.
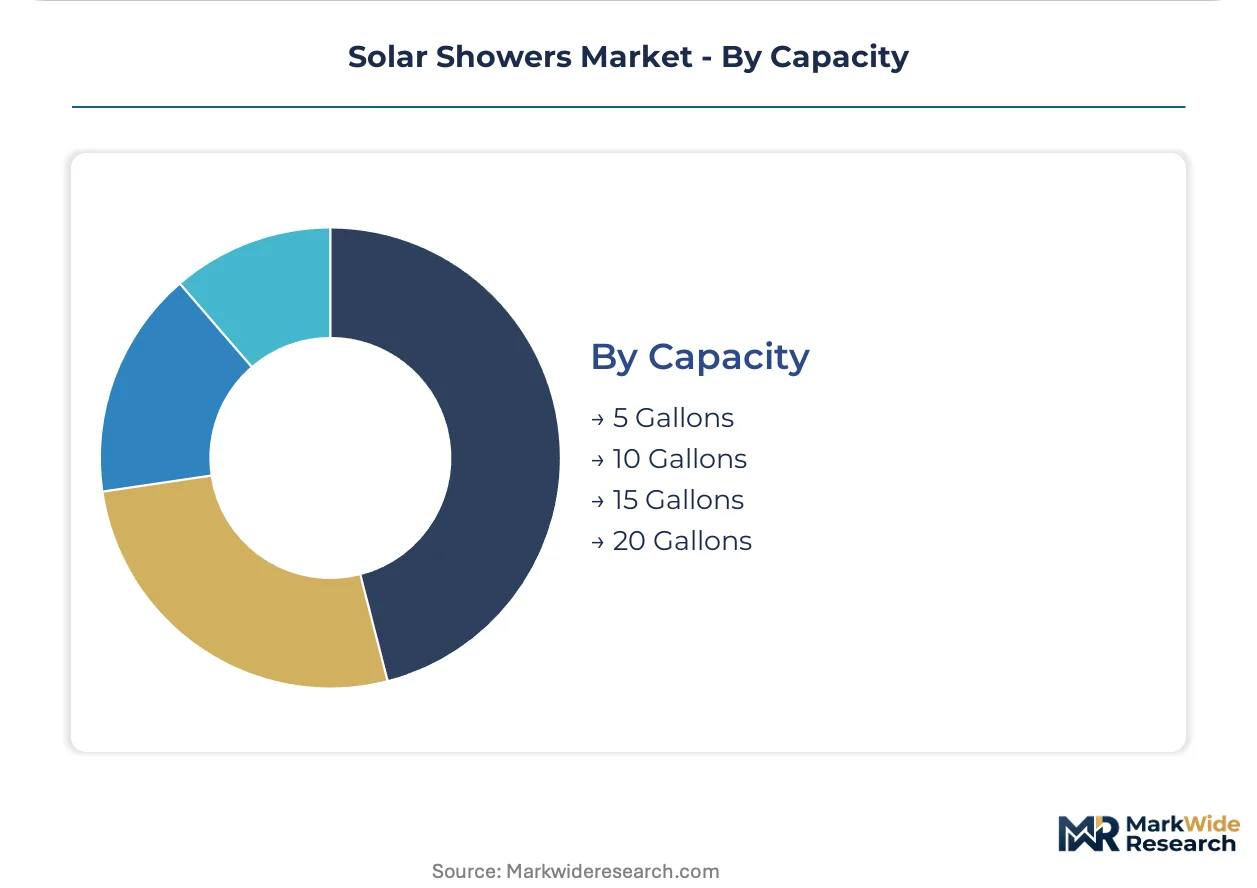
- 5 Gallons:Individual backpacker systems prioritize weight minimization over shower duration. German thru-hiking communities in the Alps drive demand for sub-kilogram compact designs.
- 10 Gallons:Couple-sized bags balance portability with adequate rinse cycles for weekend campers. French retail channels move highest volumes in this mid-range specification.
- 15 Gallons:Family camping configurations suit multi-day basecamp setups where vehicle access permits heavier loads. Italian lakeside campgrounds specify this capacity for rental fleet standardization.
- 20 Gallons:Commercial-grade reservoirs with extended collector surface area serve high-throughput sanitary blocks. German municipal campground networks centralize procurement around this specification for group facility consistency.
10 Gallon systems hold volume leadership; 20 Gallon specifications show steepest expansion trajectory on commercial operator upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese borosilicate glass manufacturing clusters supply evacuated tube substrates that enable thermal efficiency gains across European and North American assembly operations. Vacuum tube coating facilities concentrate in Jiangsu and Zhejiang provinces, anchoring upstream material flows for solar thermal collector production worldwide.
Germany
Alpine campground operators in Bavaria and Baden-Württemberg drive fixed solar shower procurement under Land-level sustainability procurement rules. The F-Gas Regulation enforces refrigerant phase-down quotas on heat-pump hybrid systems, compressing supplier lead times. The Black Forest tourism corridor exhibits strongest wall-mounted installation growth as municipal campgrounds consolidate facility upgrades.
France
Lakeside resort properties in Provence-Alpes-Côte d'Azur specify architectural-grade evacuated tube collectors for poolside shower infrastructure. ANSM and DGCCRF coordinate refrigerant compliance inspections under EU F-Gas enforcement frameworks. The Auvergne-Rhône-Alpes mountain tourism zone sustains portable system demand through guide services and alpine hut networks.
Italy
Municipal campground networks in Lombardy and Veneto access EU Green Deal renovation subsidies for permanent sanitary block upgrades. Ecodesign requirements mandate minimum thermal efficiency thresholds for outdoor water heating equipment in commercial installations. The Italian Lakes District exhibits concentrated procurement activity as regional tourism boards centralize infrastructure capital planning.
United States
Western states campground operators in California and Colorado face EPA WaterSense guideline compliance for efficiency claims on solar thermal products. The National Park Service procurement specifications influence vendor qualification requirements across federal concession contracts. The Pacific Northwest outdoor retail channel moves highest portable system volumes through seasonal pre-season inventory builds.
China
Domestic vacuum tube manufacturers in Jiangsu province advance selective absorption coating deposition techniques for export markets. The national dual carbon goals accelerate solar thermal component standardization under GB performance benchmarks. The Yangtze River Delta industrial cluster supplies evacuated glass substrates to European and North American collector assemblers under ISO 9806 certification protocols.
Solar Showers Market Vendor Landscape
Global majors compete with regional champions across distribution channel access and thermal technology integration depth. The vendor base stratifies into three tiers: multinational plumbing fixtures conglomerates with hospitality sector relationships, specialized outdoor equipment manufacturers with recreational retail penetration, and emerging ultralight specialists targeting expedition-grade portability. Strategic moves concentrate on portfolio diversification into adjacent water heating categories and selective geographic expansion through distributor network acquisitions.
Within the premium architectural tier, GROHE AG anchors positioning through fixed-installation designs targeting hospitality and residential poolside applications. Coleman Company Inc. exemplifies the recreational retail archetype with established outdoor channel distribution sustaining volume leadership in North American camping markets. HelioZ occupies the ultralight specialist position, representing backcountry-focused product development for alpine and thru-hiking user segments.
| Leading Market Players |
|---|
| GROHE AG |
| Coleman Company Inc. |
| HelioZ |
| Kampa GmbH |
| Eccotemp Systems Inc. |
| Zodi Outdoor Innovations |
| Geyser Systems |
| Nemo (Helio) |
| Sunlight Supply Inc. |
| Others |
Supply Flow & Price Mechanics
Architectural-grade fixed installations versus recreational portable systems diverge sharply in both procurement economics and upstream sourcing footprints. German hospitality operators absorb premium pricing for evacuated tube collectors with ISO 9806 certification and multi-year service bundling, while discount outdoor retailers in France and Germany move high-volume polymer bag systems through seasonal promotional cycles with minimal after-sales support.
Pricing Analysis
Warranty and service bundling separates commercial campground procurement from recreational retail transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence: ISO 9806-tested evacuated tube systems command architectural premiums, CE-marked mid-tier units serve municipal campground networks, and uncertified polymer bags dominate mass-market camping channels. Price differentiation hinges on thermal performance guarantees and installation complexity. Cost compression in the portable tier intensifies because Chinese manufacturing overcapacity floods European discount channels. Municipal procurement officers show lowest price sensitivity, prioritizing uptime commitments over unit economics.
Supply Chain Analysis
ISO 9806 certification gating constrains supplier qualification for commercial-grade evacuated tube assemblies. Chinese borosilicate glass manufacturing in Jiangsu and Zhejiang provinces feeds collector fabrication, while German and Italian assembly operations handle final integration and testing. Raw material dependencies center on copper manifold tubing, aluminum heat exchangers, and selective absorption coating chemicals. Single-source vulnerability concentrates in Chinese vacuum tube coating deposition capacity. Distribution runs through outdoor retail chains for portable systems and direct contractor relationships for fixed hospitality installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over evacuated tube coating capacity to secure thermal efficiency advantages and compress certification timelines.
For Market Incumbents: To counter refrigerant compliance cost inflation under EU F-Gas phase-down quotas, GROHE AG and Coleman Company Inc. should deepen backward integration into selective absorption coating supply through Jiangsu province partnerships, while expanding captive ISO 9806 testing laboratories to compress product launch cycles ahead of seasonal procurement windows. For New Entrants and Emerging Players: Alpine guide services and thru-hiking communities in the Pyrenees and Dolomites represent the most penetrable white-space segment, with sub-kilogram ultralight systems commanding minimal regulatory burden and premium pricing. A direct-to-expedition-outfitter go-to-market model bypasses established retail channel gatekeepers entirely. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale fixed-installation specialists given EU Green Deal renovation subsidy acceleration across Italian municipal campground networks. Long-term viability over a decade horizon favors targets with hospitality sector relationships and F-Gas-compliant natural refrigerant heat-pump hybrid pipelines. The signal to watch is ANSM enforcement action intensity on refrigerant leak rate documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Tube Coating | Captive Jiangsu province coating capacity secures selective absorption layer supply and compresses ISO 9806 certification timelines. |
| Natural Refrigerant Heat-Pump Hybrid Development | F-Gas Regulation compliance ahead of quota restrictions protects German and Italian commercial campground market access. |
| IoT-Enabled Predictive Maintenance Platform | Temperature sensor integration with mobile connectivity enables hospitality operators to guarantee hot water availability hours. |
| Alpine Guide Service Direct Distribution | Expedition outfitter partnerships bypass saturated outdoor retail channels for ultralight backcountry system penetration. |
| EU Green Deal Subsidy Qualification Engineering | Italian municipal campground procurement centralization under renovation wave funding streams requires dedicated compliance architecture. |
Methodological Framework
Independent corroboration across campground operator procurement officers, vacuum tube manufacturing engineers, and outdoor retail category buyers underwrites the qualitative findings. The analysis combines primary interviews with facility managers at German Land-level municipal campground networks, thermal coating specialists at Jiangsu province manufacturing clusters, and distribution planners at French alpine tourism boards with secondary validation through EU Ecodesign directive documentation, F-Gas Regulation enforcement records, and ISO 9806 certification registries. Bottom-up unit shipment estimates triangulate against top-down addressable market sizing across recreational and commercial installation contexts.
Comparable-period anchoring to historical pre-season procurement cycles calibrated the forecast window against seasonal demand compression patterns. The analytical framework segments by product type, use case, installation permanence, and capacity tier throughout the forecast period. CAGRs derive from installed base growth rates and replacement cycle acceleration in commercial hospitality applications. Industry-specific inputs include EU Green Deal subsidy allocation trajectories and ANSM refrigerant inspection enforcement intensity.
Caveats apply where F-Gas Regulation quota tightening or copper and aluminum commodity volatility could materially shift the outlook. Forecasts reflect assumptions on certification timeline stability and seasonal procurement pattern persistence. A model refresh is warranted upon material change in EU Ecodesign enforcement deadlines or Chinese borosilicate glass export capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Ocean Power Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
East Europe Renewable Energy Market