
 Green Renewable Energy Market | 2026-2036
Green Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Green Renewable Energy Market Insights
Software-defined grid management is realigning what developers monetize, shifting revenue from pure generation to frequency regulation and virtual power plant participation. NextEra Energy leverages its transmission footprint to bundle storage co-location services. Vestas Wind Systems anchors its offshore platform with long-term service contracts that lock in twenty-year revenue streams.
Green renewable energy encompasses electricity derived from naturally replenishing sources—solar photovoltaics converting 20-22% of incident irradiance under standard test conditions, wind turbines extracting kinetic energy through 80-120 meter rotor diameters, and bioenergy systems processing organic feedstocks via anaerobic digestion or combustion—to displace fossil-derived grid power and distributed thermal applications. Solar photovoltaic deployment dominates capacity additions across utility-scale and residential application segments, while wind turbine installations command higher capital intensity but deliver superior capacity factors in offshore corridors. Bioenergy retains structural importance in industrial heat applications where electrification faces thermodynamic constraints.
The EU Green Deal, EPA tailpipe standards, and India's CEA renewable purchase obligations collectively mandate procurement thresholds that harden demand visibility for developers and equipment suppliers. China's MIIT dual carbon targets and GB standards for photovoltaic module efficiency are compressing technology upgrade cycles for manufacturers serving multiple jurisdictions. Stakeholders must track how carbon border adjustment mechanisms in Europe and North America redirect capital toward domestic manufacturing capacity versus continued reliance on imported module supply chains.
Market Dynamics
Software-defined grid management is compressing developer revenue models from pure generation toward frequency regulation and virtual power plant participation, forcing asset operators to revalue their infrastructure around ancillary service capabilities.
Growth Catalysts
- India's CEA renewable purchase obligations:State-level tightening of procurement mandates hardens demand visibility for utility-scale developers and equipment suppliers.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive goods redirect capital toward domestic manufacturing capacity for photovoltaic modules.
- Offshore wind foundation technology:Floating platform advances unlock deep-water corridors previously inaccessible to fixed-bottom installations.
Market Restraints
- Polysilicon supply concentration:Overreliance on Xinjiang-based ingot and wafer production exposes module assemblers to forced labor due diligence requirements and tariff exposure.
- Interconnection queue backlogs:FERC Order 2023 implementation gaps delay commercial operation dates for utility-scale solar and storage hybrids.
- Grid-forming inverter technical limitations:Current silicon carbide semiconductor architectures face thermal cycling durability constraints in high-temperature desert installations.
Strategic Opportunities
- Indonesia captive power displacement:Nickel processing and smelting facilities face mounting pressure to replace diesel and coal-fired self-generation with solar-plus-storage hybrids.
- Green hydrogen offtake contracts:Electrolyzer manufacturers bundling renewable energy supply agreements with industrial ammonia and steel producers.
- Virtual power plant aggregation platforms:Residential battery installers enrolling distributed assets into wholesale market participation programs.
Industry Challenges
- Power systems engineering talent scarcity:Grid integration specialists capable of modeling inverter-based resource dynamics command premium compensation and extended recruitment timelines.
- ISO 55000 asset management certification complexity:Offshore wind operators navigating divergent national interpretations of maintenance protocol standards across North Sea jurisdictions.
- Legacy SCADA system integration friction:Utility control rooms retrofitting decades-old distribution management systems to accommodate bidirectional power flows and distributed energy resource telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Renewable Energy Market |
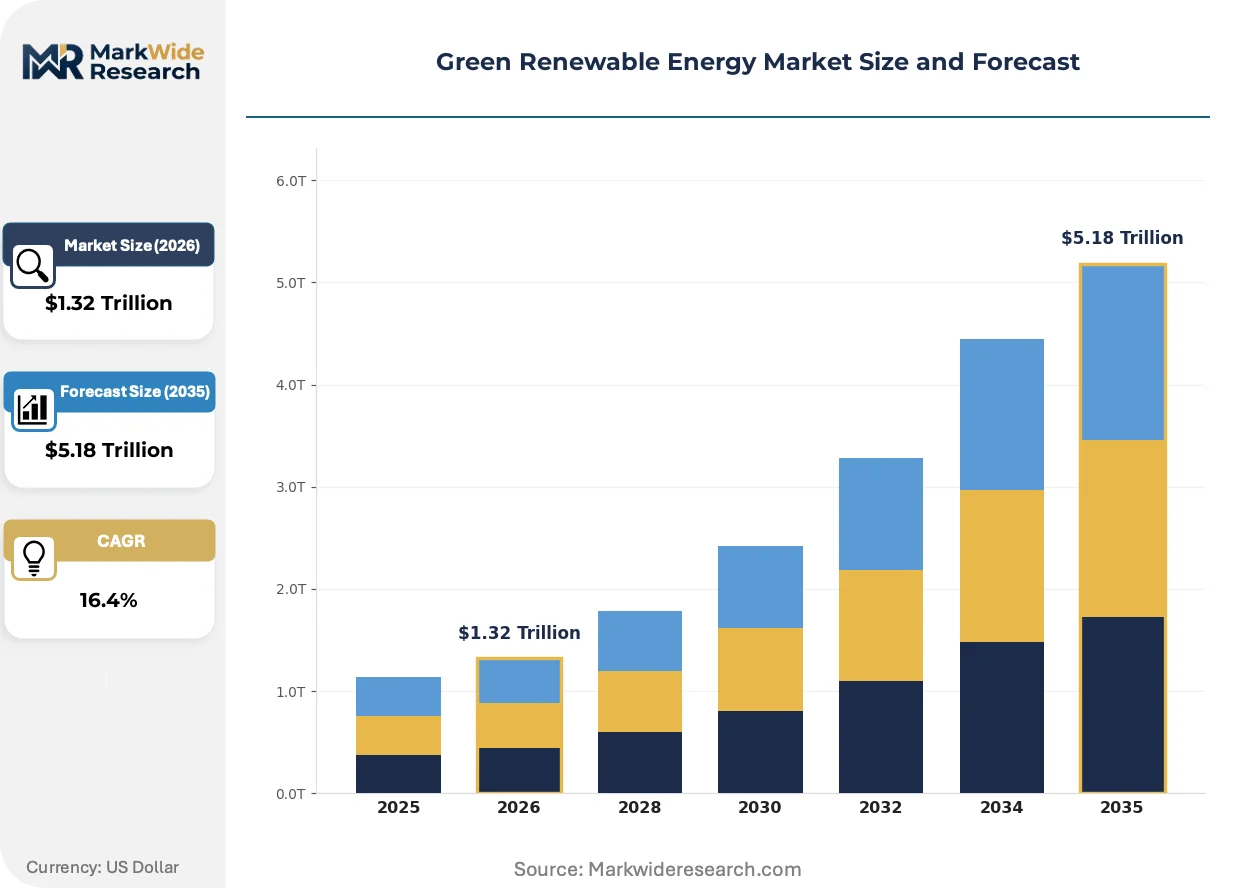
| Market Size in 2026 | $1.32 Trillion |
| Market Size in 2035 | $5.18 Trillion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydro, Biomass Technology: Photovoltaic, Wind Turbines, Bioenergy, Geothermal Application: Residential, Commercial, Industrial, Utility-scale End User: Governments, Corporations, Homeowners, NGOs |
| Companies Covered | NextEra Energy, GE Vernova, Sungrow Power Supply, Adani Green Energy, LONGi Green Energy, ACWA Power, Vestas Wind Systems, First Solar, Bloom Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Renewable Energy Market Trends and Innovations
Artificial intelligence is penetrating renewable asset operations, compressing maintenance intervals and redefining how developers contract performance guarantees with offtakers.
Computer vision-based drone inspection is automating blade damage detection for wind turbine operators, reducing manual climb-down requirements by maintenance technicians. European offshore fleets are deploying these systems at scale across North Sea corridors. The technology is automating condition-based maintenance scheduling, shifting service contracts from time-based to predictive outcome structures.
The EU Green Deal's carbon border adjustment mechanism imposes embedded emissions reporting on imported photovoltaic modules and electrolyzers entering European customs territory. Manufacturers in Southeast Asia are restructuring supply chains to source polysilicon from non-Xinjiang origins. Indian module assemblers serving European utility procurement are accelerating backward integration into cell manufacturing to demonstrate supply chain traceability.
Corporate renewable energy buyers are consolidating procurement through aggregated virtual power purchase agreements, pooling offtake commitments across multiple mid-cap enterprises to achieve utility-scale contract minimums. Clean energy aggregators in Texas and California are brokering these structures between developer pipelines and commercial-industrial load clusters. The model concentrates buyer negotiation leverage while fragmenting developer counterparty risk across diversified credit profiles.
Green Renewable Energy Market Segmentation
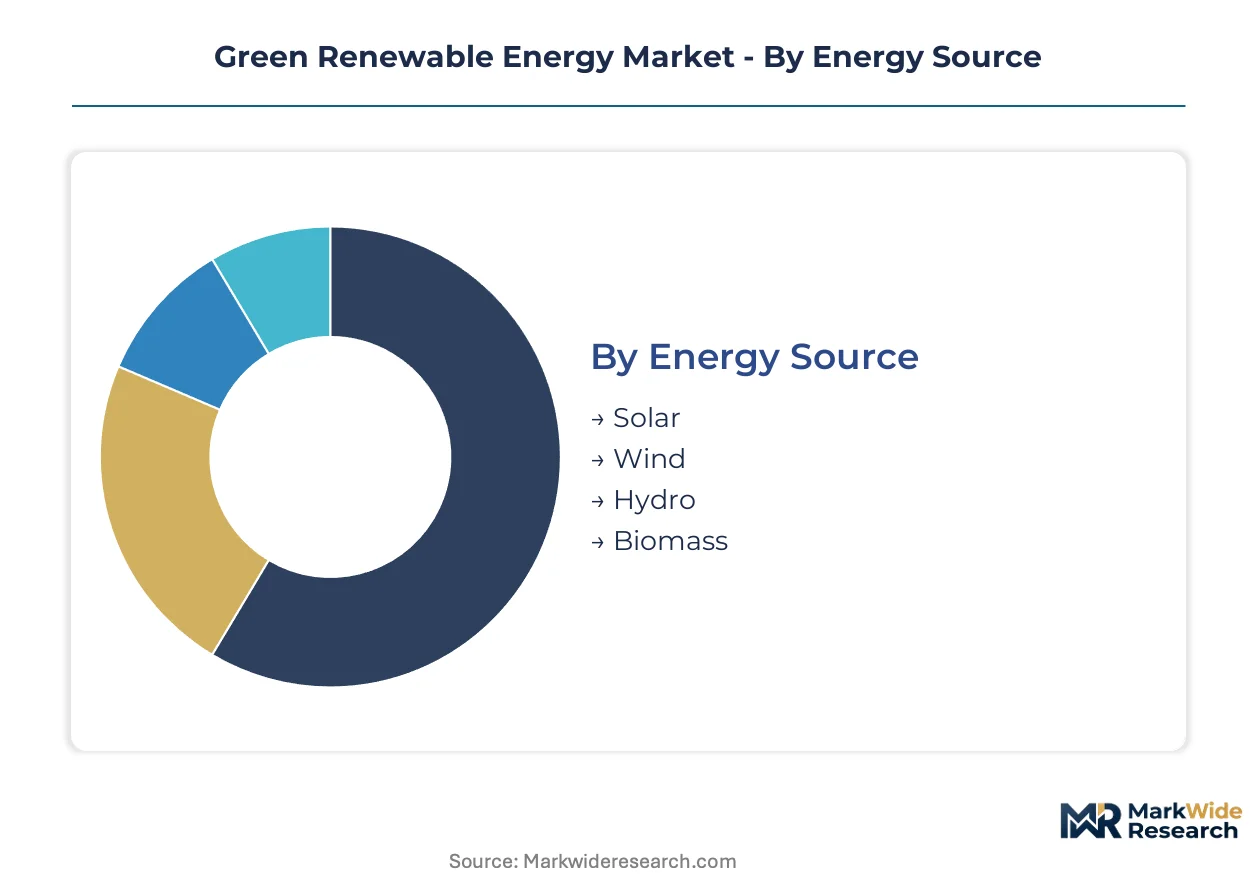
Capital deployment patterns across the Green Renewable Energy Market diverge sharply by segment, with developers prioritizing asset classes that align grid-scale generation with ancillary revenue streams. Understanding these allocation preferences clarifies where equipment suppliers concentrate R&D and where project finance flows most readily.
Energy Source:
Capital intensity varies enormously across primary energy sources, with offshore wind demanding the highest upfront investment per megawatt and utility-scale solar offering the lowest barrier to entry for new developers.
- Solar:Photovoltaic modules convert 20-22% of incident irradiance under standard test conditions, with crystalline silicon dominating module supply. Utility-scale procurement in India accelerates as state-level renewable purchase obligations tighten procurement mandates for distribution companies.
- Wind:Turbines extract kinetic energy through 80-120 meter rotor diameters, with offshore platforms commanding capital intensity multiples above onshore equivalents. Floating foundation advances unlock deep-water corridors off Portugal and Japan previously inaccessible to fixed-bottom installations.
- Hydro:Run-of-river and pumped-storage configurations provide grid-balancing services that intermittent sources cannot replicate. Environmental permitting constraints in the US Pacific Northwest and Brazil's Amazon basin limit greenfield development velocity.
- Biomass:Anaerobic digestion and combustion systems process organic feedstocks for industrial heat applications where electrification faces thermodynamic constraints. Cogeneration facilities in Scandinavia and Southeast Asia anchor baseload renewable supply.
Utility-scale solar absorbs the bulk of installed capacity; offshore wind is expanding most quickly as floating platform technology matures.
Technology:
Technology selection determines a project's revenue stack flexibility, with some platforms enabling frequency regulation and virtual power plant participation while others remain confined to pure generation.
- Photovoltaic:Silicon-based cell architectures dominate module production, with passivated emitter and rear contact designs pushing laboratory efficiencies above 26%. China's MIIT dual carbon targets compress upgrade cycles for manufacturers serving multiple jurisdictions.
- Wind Turbines:Gearless direct-drive generators reduce maintenance intervals in offshore salt-air environments. Vestas and Siemens Gamesa anchor their platforms with twenty-year service contracts that lock in long-term revenue visibility.
- Bioenergy:Combined heat and power systems retain structural importance for district heating networks in Denmark and industrial process steam in Brazil's sugarcane sector. Feedstock logistics constrain project economics more than conversion technology.
- Geothermal:Binary-cycle plants exploit low-to-moderate temperature resources for baseload generation. Indonesia's volcanic arc and Kenya's Rift Valley host the most attractive undeveloped resource concentrations.
Photovoltaic technology commands the greatest cumulative deployment; geothermal is gaining share fastest as drilling costs decline and resource mapping improves.
Application:
Application segments structure offtake contract tenors, risk profiles, and developer counterparty requirements, with utility-scale procurement offering the longest revenue visibility and residential the most fragmented.
- Residential:Rooftop systems paired with battery storage enable homeowners to participate in virtual power plant aggregation programs. California's SGIP incentive and Germany's EEG feed-in tariffs shape deployment economics.
- Commercial:On-site generation reduces exposure to retail tariff volatility for manufacturing and data center loads. Corporate renewable energy buyers in Texas and California consolidate procurement through aggregated virtual power purchase agreements.
- Industrial:Captive power displacement accelerates as nickel smelters in Indonesia and aluminum producers in Iceland face pressure to replace coal and diesel self-generation. Solar-plus-storage hybrids offer the most credible substitution pathway.
- Utility-scale:Grid-connected projects sell into wholesale markets or secure power purchase agreements with investment-grade offtakers. Interconnection queue backlogs under FERC Order 2023 implementation gaps delay commercial operation dates.
Utility-scale applications absorb the bulk of capital deployment; commercial distributed generation is climbing the fastest as aggregated procurement structures mature.
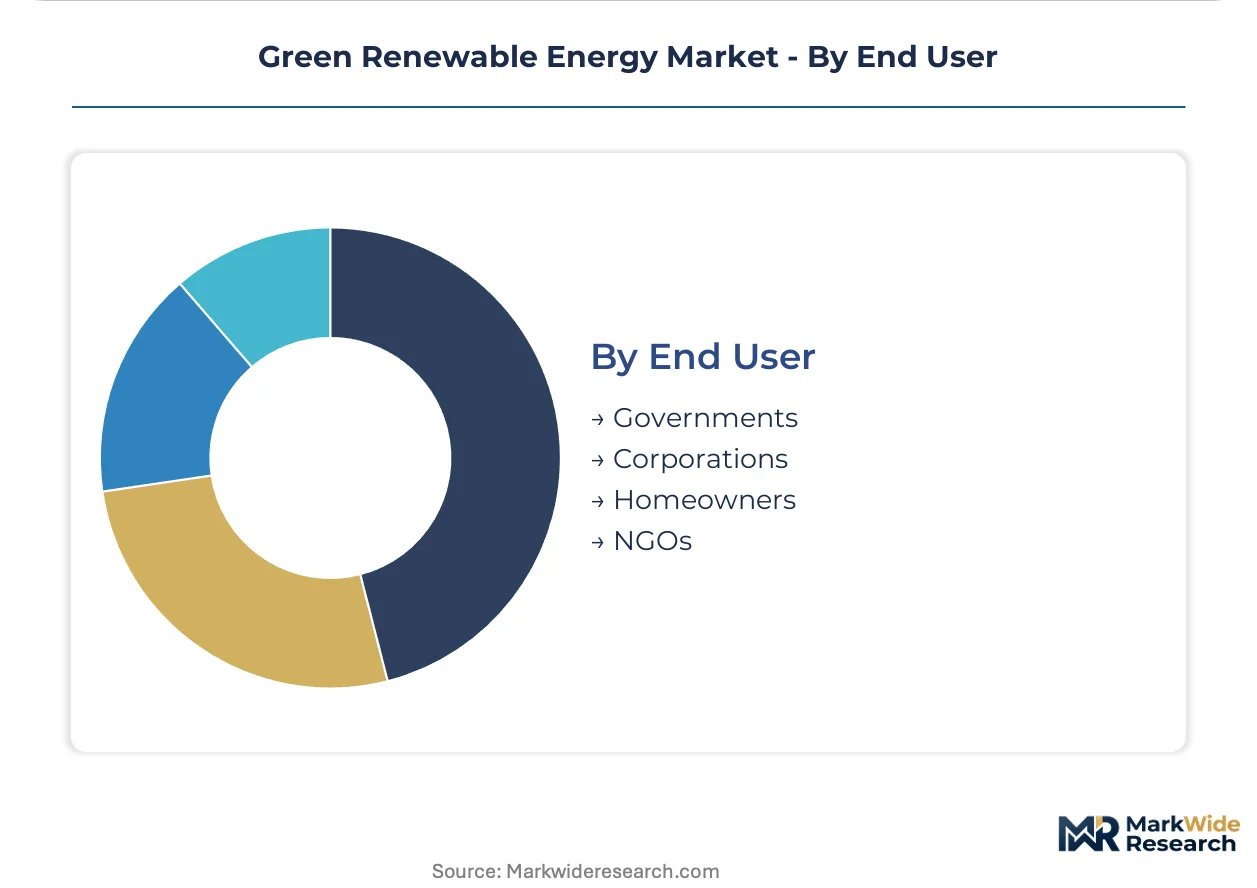
End User:
End user categories determine procurement sophistication, contract negotiation leverage, and tolerance for technology performance risk, with governments and corporations driving the largest transaction volumes.
- Governments:Public sector procurement anchors demand visibility through renewable purchase obligations, carbon border adjustments, and sovereign green bond issuance. The EU Green Deal and India's CEA mandates harden enforcement timelines.
- Corporations:Industrial offtakers contract for renewable supply to meet science-based targets and secure price hedges against volatile fossil fuel markets. Clean energy aggregators broker structures between developer pipelines and commercial-industrial load clusters.
- Homeowners:Individual consumers respond to net metering policies and battery storage incentives that vary by state and utility service territory. Virtual power plant enrollment transforms passive load into grid-interactive assets.
- NGOs:Development finance institutions and climate funds provide concessional capital for projects in frontier markets. Their participation de-risks early-stage pipelines that commercial lenders would otherwise bypass.
Corporate offtakers absorb the bulk of contracted capacity; government procurement is accelerating most rapidly as carbon border mechanisms tighten compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of photovoltaic modules and wind turbine components, while the United States and Europe absorb the highest per-capita clean electricity consumption. This production-consumption divide shapes trade flows, tariff exposure, and supply chain restructuring decisions across the industry.
United States
Utility-scale solar procurement accelerates in Texas and California as interconnection reforms under FERC Order 2023 attempt to clear queue backlogs. The Inflation Reduction Act's domestic content bonuses redirect capital toward module assembly facilities in Arizona and Ohio. Arizona's manufacturing corridor attracts polysilicon-to-module investments seeking to bypass forced labor scrutiny on imported wafers.
China
MIIT dual carbon targets compress technology upgrade cycles for manufacturers serving multiple export jurisdictions. GB standards for photovoltaic module efficiency push laboratory architectures toward passivated emitter and rear contact designs. Xinjiang's polysilicon concentration exposes module assemblers to European and North American due diligence requirements, triggering supply chain restructuring.
Germany
The EU Green Deal's carbon border adjustment mechanism imposes embedded emissions reporting on imported electrolyzers and photovoltaic modules entering Hamburg and Rotterdam ports. North Sea offshore wind clusters anchor turbine service contracts that lock in twenty-year revenue streams. Bavaria's industrial load centers contract for green hydrogen offtake to displace natural gas in chemical processing.
India
State-level renewable purchase obligations under CEA mandates harden demand visibility for utility-scale developers in Gujarat and Rajasthan. Gujarat's manufacturing corridor attracts module and cell investments seeking to demonstrate supply chain traceability for European offtakers. Rajasthan's solar parks concentrate capacity additions where land availability and irradiance levels align.
Brazil
Bioenergy retains structural importance in São Paulo state's sugarcane sector, where cogeneration facilities anchor baseload renewable supply. The country's national development bank channels concessional capital toward run-of-river hydro in the Amazon basin. Minas Gerais hosts wind corridors where capacity factors rival offshore equivalents in European markets.
Green Renewable Energy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the renewable energy equipment sector. The market fragments vertically between upstream material suppliers, midstream component fabricators, and downstream project developers. Three archetypes dominate: integrated energy conglomerates bundling generation with grid services, pure-play equipment manufacturers anchoring revenue through long-term service contracts, and project developers monetizing development rights rather than manufacturing scale. Consolidation pressure concentrates in module assembly, while turbine supply remains oligopolistic.
Among integrated energy conglomerates, NextEra Energy and GE Vernova exemplify the bundled-service archetype. Vestas Wind Systems occupies a position within the pure-play equipment tier, anchoring offshore platform economics through multi-decade maintenance protocols. LONGi Green Energy represents the vertically integrated module specialist archetype, with Chinese corporate structures enabling upstream control over polysilicon supply.
| Leading Market Players |
|---|
| NextEra Energy |
| GE Vernova |
| Sungrow Power Supply |
| Adani Green Energy |
| LONGi Green Energy |
| ACWA Power |
| Vestas Wind Systems |
| First Solar |
| Bloom Energy |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China and India anchor polysilicon-to-module manufacturing, concentrating supply-side pricing power while contract-based offtake structures in Europe and North America insulate developers from spot volatility. This ownership pattern compresses margins for independent assemblers lacking captive ingot supply while amplifying margin capture for integrated specialists commanding backward linkages.
Pricing Analysis
Price erosion across standard-tier photovoltaic modules traces to Xinjiang-origin polysilicon displacement costs and European carbon border compliance investments. Contract-based long-term offtake structures dominate utility-scale procurement, with premium-mid-economy pricing differentiation anchored in IEC certification tier and volume scale. Cost-down pressure on economy-tier suppliers accelerates because forced labor due diligence requirements disqualify legacy supply sources. Corporate offtakers exhibit lowest price sensitivity; residential installers face acute margin compression.
Supply Chain Analysis
Direct-to-IPP channels handle hyperscale developer demand while distributor networks serve fragmented commercial and residential installers. Geographic supply concentration centers on China for polysilicon and wafers, Vietnam for cell assembly, and India for module finishing serving European traceability requirements. Raw material dependencies rest on metallurgical-grade silicon, silver paste for cell metallization, and ethylene-vinyl acetate encapsulants. Single-source vulnerability in Xinjiang polysilicon exposes assemblers to tariff exposure and supply disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysilicon purification capacity constraints prop module pricing discipline, creating supply-constrained conditions that favor integrated manufacturers over pure-play assemblers.
For Market Incumbents: Deepen upstream control over ingot and wafer production to secure supply chain traceability for European carbon border compliance. Expand cell manufacturing capacity in India and Southeast Asia to diversify geographic exposure beyond Xinjiang-dependent sources. Vestas and LONGi demonstrate how captive supply of critical inputs defends margin position against tariff-driven cost shocks. For New Entrants and Emerging Players: Virtual power plant aggregation platforms offer the most penetrable entry vector, enabling residential battery installers to enroll distributed assets into wholesale market participation without generation asset ownership. Target Indonesia's nickel smelter captive power displacement with solar-plus-storage hybrids, leveraging regulatory pressure to displace diesel self-generation. Partner with established EPC contractors to de-risk project execution credibility gaps. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale IPP developers with interconnection queue positions in Texas and California, where FERC Order 2023 implementation gaps delay commercial operation dates and strain sponsor liquidity. Long-term viability hinges on ancillary service revenue capture rather than pure generation merchant exposure. Monitor grid-forming inverter certification progress as inflection indicator for storage co-location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Secures supply chain traceability for EU Green Deal carbon border compliance requirements. |
| Power Purchase Agreement Expansion | Locks in twenty-year revenue visibility for offshore wind platforms in North Sea corridors. |
| Virtual Power Plant Platform Launch | Enables residential battery aggregators to capture frequency regulation revenue streams. |
| Green Hydrogen Offtake Contracting | Bundles electrolyzer supply with industrial ammonia and steel producer demand. |
| Floating Offshore Wind Foundation Deployment | Unlocks deep-water corridors off Portugal and Japan previously inaccessible to fixed-bottom installations. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings. Primary interviews with transmission interconnection specialists and renewable procurement leads at industrial offtakers combined with secondary validation from EIA generation data, IEA renewable market reports, FERC interconnection filings, and project development databases. Bottom-up capacity addition tracking and top-down policy impact assessment triangulate market sizing.
Comparable-period anchoring to historical installation data and capacity factor benchmarks calibrated the projection framework across the analysis window. Segmentation dimensions modeled include energy source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed capacity trajectories and capital cost learning curves. Forecast inputs incorporate polysilicon supply expansion timelines and carbon border adjustment mechanism implementation schedules.
The model holds under sustained renewable purchase obligation enforcement and interconnection reform progress; deviation in tariff escalation or queue clearance delays would shift deployment trajectories. Practitioners should monitor FERC Order 2023 implementation gaps and EU carbon border adjustment phase-in schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Solar Tree Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
China Wind Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
China Solar Energy Market