
 Hydrokinetic Converters Market | 2026-2036
Hydrokinetic Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrokinetic Converters Market Analytics
Performance-based operations and maintenance contracts is pivoting how hydrokinetic projects monetize output. Sigma Design leverages its engineering heritage to dominate structural design for harsh marine environments. ABB sustains technology leadership through integrated power conversion and grid connection systems. Maini Renewables anchors its position with specialized deployment vessels and installation logistics.
Hydrokinetic converters transform the kinetic energy of moving water—tidal streams, ocean currents, and wave motion—into electrical power through submerged or surface-mounted turbine assemblies, typically rated from tens of kilowatts to several megawatts per unit. Tidal turbines capture the largest share of installed capacity due to predictable resource availability and established project pipelines, while wave energy converters represent the fastest-growing product type as control algorithms improve energy capture efficiency. Deployment type segmentation shows offshore installations commanding premium margins because of higher energy density and fewer spatial constraints, though nearshore distributed generation appeals to island utilities seeking supply independence.
The EU Green Deal and the F-Gas Regulation shape equipment specifications and grid interconnection standards across European project zones, while the UK's Marine Management Organisation and Crown Estate leasing rounds determine site access and development timelines. ISO 19901-6 offshore structure standards and IEC TS 62600-200 tidal energy measurement protocols define certification pathways that influence investor confidence and insurance terms. Stakeholders must monitor how evolving seabed licensing frameworks and evolving grid codes for variable renewable injection reshape project bankability and technology selection criteria.
Market Dynamics
Performance-based contracting is restructuring how hydrokinetic projects secure financing, as developers now monetize verified energy output rather than installed capacity. This shift forces equipment suppliers to guarantee availability metrics and absorb operational risk.
Growth Catalysts
- EU Green Deal auction mechanisms:Revenue support schemes in member states reduce merchant price exposure for tidal array developers. Strike prices under contract-for-difference frameworks improve project bankability.
- Scotland's Pentland Firth resource density:The strait's tidal velocities exceed 3 meters per second across multiple lease blocks. Crown Estate seabed licensing rounds have allocated 12 sites for commercial-scale deployment.
- Composite blade manufacturing:Glass-reinforced polymer rotors cut unit weight by 40% versus steel equivalents. Lighter assemblies reduce foundation loads and simplify vessel-based installation logistics.
Market Restraints
- Subsea cable cost volatility:Copper and cross-linked polyethylene prices fluctuate with commodity cycles. Array-scale projects require 20-40 kilometers of dynamic cable per installation.
- Specialized vessel scarcity:Heavy-lift jack-up units capable of precision turbine placement number fewer than 15 globally. Day rates exceed $200,000 during North Atlantic weather windows.
- IEC TS 62600-200 certification timelines:Full-type testing for tidal turbines requires 24-36 months of monitored operation. Insurance underwriters mandate completion before commercial coverage activates.
Strategic Opportunities
- Island utility supply independence:Orkney, Shetland, and Scottish Western Isles seek to displace diesel generation. Distributed hydrokinetic units align with net-zero commitments and grid isolation needs.
- Wave-tidal hybrid platforms:Co-located energy capture devices share mooring infrastructure and export cables. Combined systems improve capacity factors and reduce levelized cost per megawatt-hour.
- UK Marine Management Organisation leasing reform:Streamlined environmental consenting timelines compress development cycles. New regional marine plans designate priority zones for tidal energy.
Industry Challenges
- Marine operations technician shortage:Diving-qualified electrical engineers command premium wages. Training programs at Scottish colleges produce fewer than 50 certified graduates annually.
- ISO 19901-6 fatigue analysis complexity:Submerged structures face 10^7 load cycles over design life. Detailed finite-element modeling extends engineering phase duration and consultant fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrokinetic Converters Market |
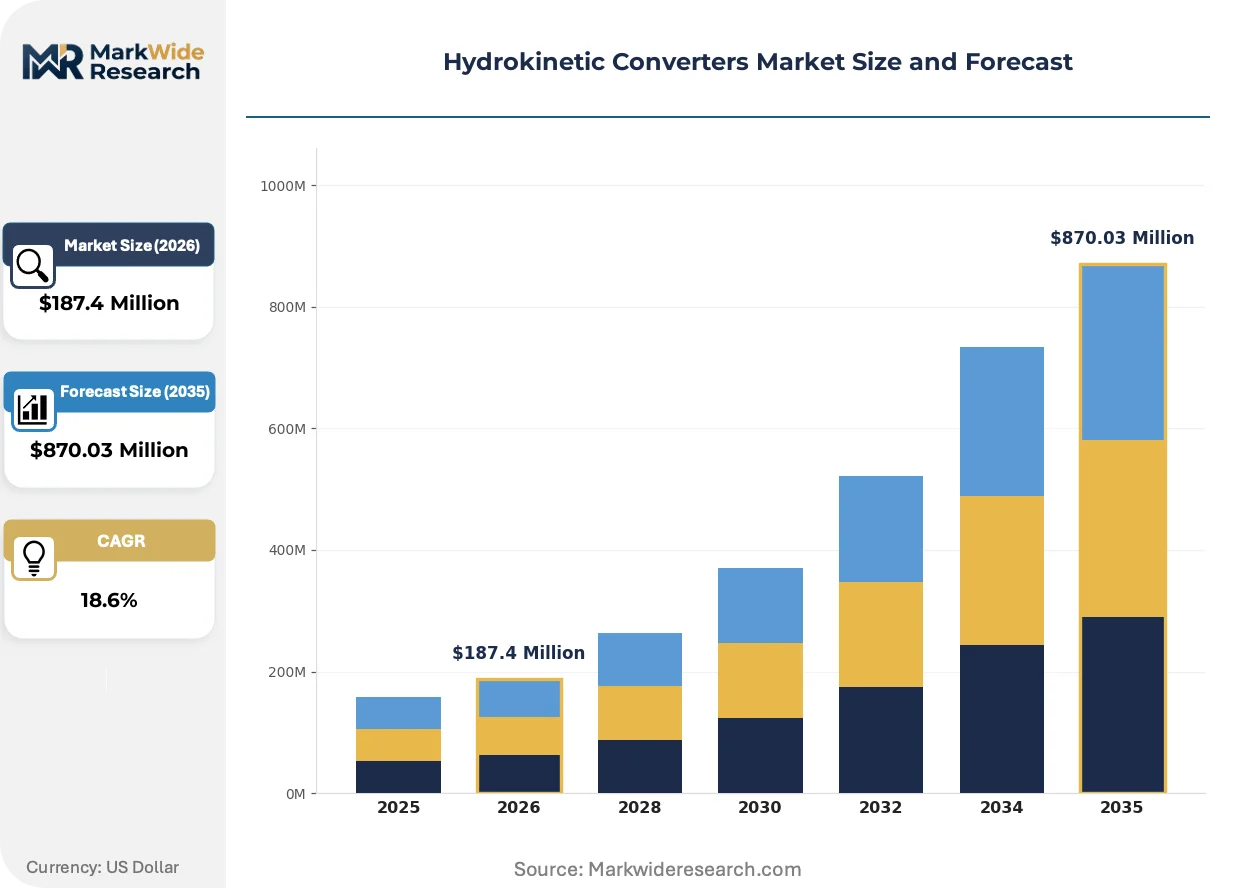
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tidal Turbines, Wave Energy Converters, Ocean Current Turbines, Hybrid Systems Deployment Type: Onshore, Offshore, Nearshore, Distributed Generation End User: Utilities, Government Agencies, Industrial Sector, Research Institutions Technology: Active Control Systems, Passive Systems, Biomimetic Systems, Integrated Systems |
| Companies Covered | Sigma Design, Norweco, ABB, Maini Renewables, ARECOR Energy, NREL, Hydrokinetica Energy Corp, Gaia Turbine SA, HOMER Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrokinetic Converters Market Evolving Landscape
Digital twin architectures and predictive maintenance algorithms are displacing scheduled overhaul regimes. Equipment suppliers now embed sensor networks that feed real-time structural health data to shore-based control centers.
Variable-pitch rotor systems is converging with machine-learning control algorithms to optimize energy capture across tidal velocity ranges. Developers in Scotland's Pentland Firth deploy these integrated packages to maintain rated output during spring-neap cycle variations. The convergence is compressing capacity factor gaps between tidal and offshore wind assets.
The F-Gas Regulation in Europe mandates phase-down of sulfur hexafluoride in switchgear applications. Tidal array developers must specify vacuum-interrupter or clean-air alternatives for offshore substations. Equipment procurement specifications in UK waters now exclude SF6-insulated apparatus from bid packages.
Utility procurement teams now require availability guarantees with liquidated damages clauses rather than equipment purchase with separate service agreements. This unbundling of capital and operational risk transfers turbine performance accountability to OEM balance sheets. ScottishPower and SSE have adopted this contracting mode for upcoming lease round submissions.
Hydrokinetic Converters Market Segmentation
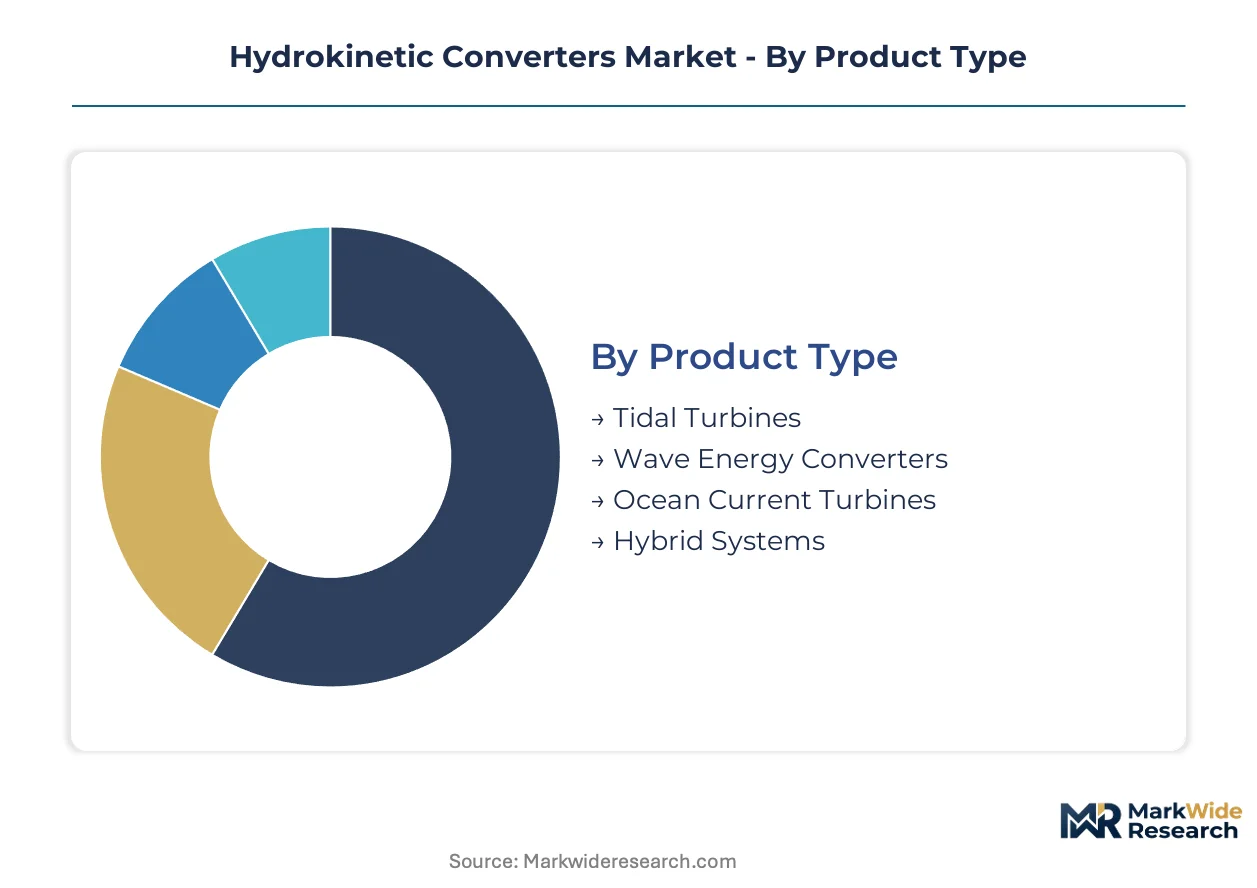
Hydrokinetic converter segmentation reveals how technology maturity and site economics shape procurement patterns. Developers match product specifications to resource characteristics and grid interconnection requirements.
Product Type:
Standalone tidal turbines dominate commercial deployments, while embedded hybrid systems integrate multiple energy capture mechanisms within unified platforms.
- Tidal Turbines:Horizontal-axis and vertical-axis rotor assemblies extract kinetic energy from predictable tidal streams. Pentland Firth arrays in Scotland concentrate demand due to velocity profiles exceeding three meters per second.
- Wave Energy Converters:Oscillating water column, point absorber, and attenuator architectures transform wave motion through hydraulic or direct-drive power take-off systems. Control algorithm advances are compressing capacity factor gaps with tidal assets.
- Ocean Current Turbines:Submerged fixed or floating platforms target steady western boundary currents.
- Hybrid Systems:Co-located wave-tidal units share mooring infrastructure and export cables.
Volume placements concentrate in tidal turbines; the faster expansion belongs to wave energy converters.
Deployment Type:
Cost tier differentiation separates capital-intensive offshore foundations from lower-cost nearshore distributed units serving isolated grids.
- Offshore:Deep-water installations exploit higher energy density and reduced spatial constraints. Premium margins reflect specialized vessel requirements and dynamic cable costs.
- Nearshore:Shallow-water deployments reduce foundation complexity and maintenance access costs. Scottish island utilities favor these configurations for diesel displacement.
- Onshore:River-run and estuary installations integrate with existing civil infrastructure.
- Distributed Generation:Small-scale units serve remote communities without transmission interconnection.
Offshore commands premium pricing; distributed generation climbs fastest as island utilities pursue supply independence.
End User:
Customer type determines contracting structures, with utilities driving performance-based availability guarantees and government agencies shaping demonstration project pipelines.
- Utilities:Grid-scale developers procure multi-megawatt arrays under contract-for-difference frameworks. ScottishPower and SSE require liquidated damages clauses for output shortfalls.
- Government Agencies:Public funding bodies de-risk early commercial deployments through capital grants and revenue support mechanisms.
- Industrial Sector:Offshore oil and gas platforms explore hybrid renewable integration.
- Research Institutions:Universities and national laboratories validate component performance and environmental impact.
Utility procurement dominates capital deployment; research institutions expand most quickly as certification protocols mature.
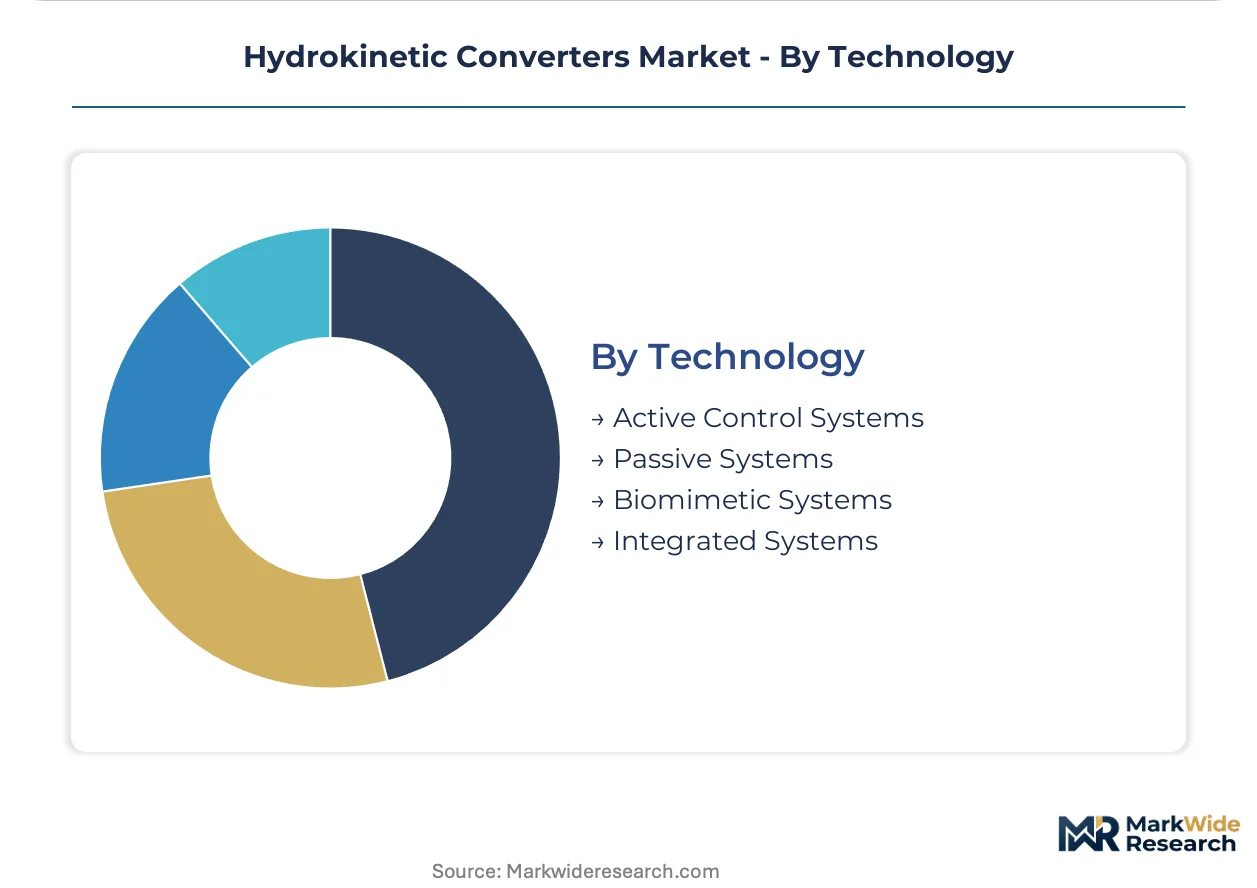
Technology:
Maturity gradients separate field-proven passive systems from emerging biomimetic architectures mimicking aquatic locomotion.
- Active Control Systems:Variable-pitch rotors and real-time power electronics optimize energy capture across velocity ranges. Machine-learning algorithms now automate spring-neap cycle compensation.
- Passive Systems:Fixed-geometry designs rely on structural optimization without moving control surfaces. Established supply chains and simpler maintenance protocols reduce operational risk.
- Biomimetic Systems:Fin- and flipper-inspired geometries emulate tuna or dolphin propulsion efficiency.
- Integrated Systems:Combined energy storage and grid-forming inverters enable standalone microgrid operation.
Passive systems anchor current installations; active control systems gain share fastest as predictive algorithms improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Scotland and Norway, while project deployment concentrates in UK waters. Consumption patterns diverge between grid-scale utility procurement and island diesel displacement applications.
United Kingdom
Crown Estate leasing rounds and Marine Management Organisation consenting frameworks drive tidal array development. The EU Green Deal's contract-for-difference mechanisms reduce merchant price exposure for ScottishPower and SSE projects. Pentland Firth hosts the densest concentration of operational turbines, with velocity profiles exceeding three meters per second across twelve allocated lease blocks.
Scotland
Orkney and Shetland island utilities pursue diesel displacement through distributed nearshore installations. Scottish government funding streams and national renewable energy auctions shape project economics. European Marine Energy Centre testing facilities in Orkney validate component performance before commercial deployment.
France
ANSM coastal permitting and maritime spatial planning designate priority zones for tidal energy in Brittany and Normandy. The country's national renewable energy regulator oversees strike price negotiations under EU auction mechanisms. Raz Blanchard in Normandy attracts developer interest due to exceptional tidal stream velocities.
Norway
Equinor and Statkraft anchor utility procurement for hybrid offshore platforms combining tidal and wave capture. The Norwegian Water Resources and Energy Directorate regulates seabed licensing and environmental impact assessments. Trondheim's marine technology cluster supplies composite blade manufacturing and subsea cable integration expertise.
Canada
Bay of Fundy tidal velocities attract developer consortia seeking to replicate Scottish deployment models. Natural Resources Canada funding programs de-risk early commercial arrays through capital grants. Nova Scotia's FORCE testing centre validates turbine performance in extreme current conditions before grid connection.
Hydrokinetic Converters Market Competitive Landscape
Top-tier vendors anchor integrated system supply, while specialized component fabricators occupy mid-tier positions. Engineering consultancies and national laboratories complete the vendor ecosystem through certification and testing services. Three archetypes dominate: full-system integrators, structural design specialists, and power electronics providers. Competitive moves center on performance-based contracting adoption and strategic partnerships for vessel access.
Among full-system integrators, Sigma Design exemplifies structural engineering heritage for harsh marine environments. ABB occupies a position spanning power conversion and grid connection systems. Maini Renewables represents the deployment logistics archetype through specialized vessel and installation capabilities. These three anchors illustrate how risk transfer to OEM balance sheets reshapes competitive positioning.
| Leading Market Players |
|---|
| Sigma Design |
| Norweco |
| ABB |
| Maini Renewables |
| ARECOR Energy |
| NREL |
| Hydrokinetica Energy Corp |
| Gaia Turbine SA |
| HOMER Energy |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's F-Gas Regulation gates qualified supply for offshore substation equipment and anchors premium-tier pricing access for tidal array developers specifying vacuum-interrupter switchgear. Buyers without certified component sourcing face exclusion from Crown Estate lease rounds.
Pricing Analysis
Cost-down pressure on offshore turbine assemblies accelerates because composite blade manufacturers in Norway and Scotland are scaling glass-reinforced polymer production. Three-tier pricing structure across IEC-certified, pre-certified, and uncertified equipment tiers reflects certification timeline differentials and insurance underwriting requirements. ScottishPower and SSE procurement teams drive pricing softness through performance-based contracting with liquidated damages clauses. Island utilities in Orkney and Shetland show highest price sensitivity due to diesel displacement budget constraints, while UK mainland grid-scale developers absorb premium pricing for availability guarantees.
Supply Chain Analysis
Dual-sourcing mandates from ABB and Sigma Design require qualified secondary suppliers for power conversion modules and structural steel forgings. Manufacturing gravity centers on Scotland, Norway, and France for turbine assembly, with subsea cable integration anchored in Trondheim and Aberdeen. Critical inputs include copper conductors, cross-linked polyethylene insulation, and carbon fiber composite resins. Single-source vulnerability concentrates in heavy-lift jack-up vessel availability, with fewer than fifteen qualified units serving North Atlantic weather windows. Distribution runs through EPC contractors managing Crown Estate lease development timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around performance-based risk transfer, with IEC TS 62600-200 certification timelines forcing undercapitalized component suppliers into acquisition or exit.
For Market Incumbents: Extend availability guarantee coverage to capture utility procurement mandates from ScottishPower and SSE. Deepen backward integration into composite blade manufacturing to offset copper and polymer commodity volatility. Lock exclusive vessel charter agreements before North Atlantic weather windows compress installation schedules further. For New Entrants and Emerging Players: Specialized diving-qualified electrical engineering contractors represent the most penetrable service layer, given Scottish colleges produce fewer than fifty certified graduates annually. Target Orkney and Shetland island utility diesel displacement programs with nearshore distributed generation packages. Partner with European Marine Energy Centre testing facilities to validate components before commercial scale-up. For Investors and Strategic Acquirers: Crown Estate seabed licensing round announcements are the leading indicator that project finance liquidity is unlocking for tidal array deployment. Five-to-ten year viability hinges on contract-for-difference strike price competitiveness versus offshore wind. Acquisition targets should display integrated power electronics capabilities and active Marine Management Organisation consenting pipelines. Deviation in F-Gas Regulation enforcement timelines would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Adoption | Liquidated damages clauses transfer operational risk to OEM balance sheets and reshape competitive positioning. |
| Composite Blade Manufacturing Scale-Up | Glass-reinforced polymer production in Norway cuts unit weight forty percent versus steel equivalents. |
| Heavy-Lift Vessel Charter Lock-In | Exclusive agreements secure installation capacity during constrained North Atlantic weather windows. |
| Dual-Supplier Qualification Programs | Secondary sourcing for power conversion modules reduces single-source dependency on ABB. |
| IEC Certification Fast-Track Investment | Accelerated type testing timelines unlock commercial insurance coverage and utility procurement eligibility. |
Research Methodology
Independent corroboration across Crown Estate lease allocation records, Marine Management Organisation consenting databases, and EU Green Deal auction mechanism filings underwrites the qualitative findings. Primary interviews with tidal project developers, offshore vessel operators, composite manufacturing plant managers, and utility procurement officers combined with secondary validation from IEC technical specification documents, FERC-equivalent grid interconnection filings, and seabed licensing authority records. Bottom-up project pipeline aggregation and top-down regulatory framework analysis triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by product type, deployment depth, end-user contracting structure, and technology maturity tier. CAGRs derive from installed capacity build-out trajectories, strike price evolution under contract-for-difference frameworks, and vessel day-rate forecasting. Industry-specific inputs include Pentland Firth velocity measurement campaigns, spring-neap cycle capacity factor modeling, and F-Gas Regulation compliance cost curves for switchgear replacement.
Caveats apply where IEC TS 62600-200 certification timeline extensions, copper commodity price spikes, or Crown Estate leasing round delays could materially shift the outlook. Deviation in EU Green Deal auction strike price floors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Cooker Market
Renewable Energy
Solar Farm Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Solar Tree Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Solar Bicycle Shed Market