
 Austria Renewable Energy Market | 2026-2036
Austria Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Renewable Energy Market Outlook
Software-defined energy trading is expanding how Austrian utilities monetize renewable assets beyond raw generation. Verbund AG leverages its hydropower dominance to anchor premium trading positions across Central European power exchanges. enspired trading competes through algorithmic flexibility optimization for commercial and industrial portfolios. 21energy differentiates by specializing in decentralized heat pump systems paired with rooftop photovoltaic arrays.
Austria renewable energy encompasses electricity and heat derived from solar radiation, wind kinetic energy, organic biomass conversion, and gravitational water flow through alpine terrain, typically harnessed via photovoltaic panels with 400-600 Wp module ratings, horizontal-axis wind turbines, anaerobic digesters, and Francis or Pelton hydro turbines. Hydropower occupies the most mature margin pool given decades of Alpine reservoir infrastructure, while photovoltaic installations represent the fastest-expanding technology segment driven by building-integrated deployment mandates. Wind turbine capacity concentrates in Lower Austria and Burgenland where flat terrain and consistent Pannonian air currents support higher capacity factors than mountainous western provinces.
The Austrian Energy Regulatory Authority and the Federal Ministry for Climate Action shape market access through renewable auction designs and grid connection priority rules under the national green electricity framework. EU Green Deal alignment and REPowerAct obligations force faster permitting timelines while tightening sustainability criteria for biomass feedstock eligibility. Stakeholders must monitor how forthcoming capacity market reforms interact with existing feed-in tariff legacy contracts to determine optimal asset repowering schedules.
Market Dynamics
Alpine hydropower reservoirs and distributed photovoltaic arrays now compete for grid priority under Austria's Renewable Expansion Act, forcing asset operators to optimize dispatch timing against real-time price signals rather than static feed-in guarantees.
Growth Catalysts
- Building-Integrated Photovoltaics Mandate:Vienna's urban planning codes require solar-ready roofing on new commercial construction above 500 square meters. Developers pre-wire electrical infrastructure during framing to reduce retrofit costs.
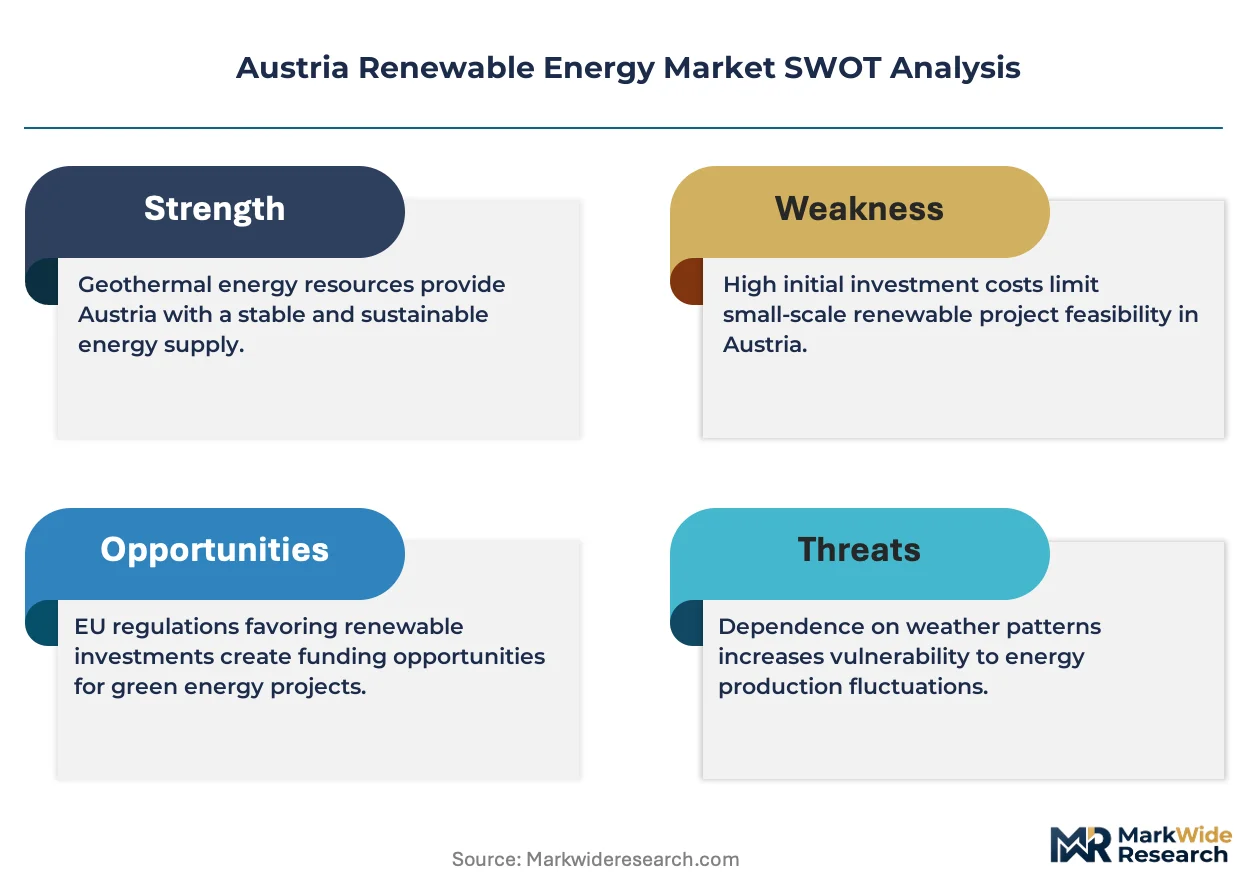
- Industrial Clean Power Procurement:Steel and chemical manufacturers in Upper Austria sign long-term power purchase agreements to meet EU Green Deal Scope 2 emissions targets. These offtake contracts provide revenue certainty for greenfield wind and solar projects.
- Alpine Pumped Hydro Reactivation:Grid operators upgrade dormant reservoir infrastructure to provide frequency regulation services. Francis turbine retrofits enable sub-minute response times for balancing volatile renewable output.
Market Restraints
- Silicon Module Supply Concentration:Austrian installers source photovoltaic panels predominantly from East Asian manufacturers. Tariff volatility and shipping bottlenecks create margin compression during project commissioning windows.
- Permitting Timeline Fragmentation:Nine provincial governments administer environmental impact assessments under divergent procedural rules. Burgenland approves wind farms in eight months while Tyrol requires twenty-four months for identical turbine specifications.
- Biomass Feedstock Sustainability Criteria:The Federal Ministry for Climate Action restricts agricultural residue eligibility to certified organic sources. Conventional farming operations lose revenue streams as compliance costs exceed market prices for thermal energy.
Strategic Opportunities
- Grid-Scale Battery Co-Location:Developers pair lithium-ion storage with existing substations in Vienna's metropolitan ring. This configuration captures arbitrage spreads between midday solar oversupply and evening demand peaks.
- Cross-Border Hydropower Trading:Verbund AG leverages transmission rights into Germany and Switzerland to monetize peak generation. Alpine reservoir flexibility commands premium pricing against nuclear baseload in neighboring markets.
- Decentralized Heat Pump Integration:Rural municipalities combine rooftop photovoltaic arrays with ground-source heat pumps. This thermal-electric coupling reduces natural gas dependency in districts beyond district heating network reach.
Industry Challenges
- Grid Connection Queue Management:Distribution system operators lack standardized interconnection study protocols. Project developers face eighteen-month delays for technical feasibility assessments in Lower Austria's high-penetration zones.
- Legacy Feed-In Tariff Contract Renegotiation:Assets commissioned under 2012-2017 support schemes approach repowering decisions. Owners must model residual value against new auction-based revenue streams with fifteen-year contract terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Renewable Energy Market |
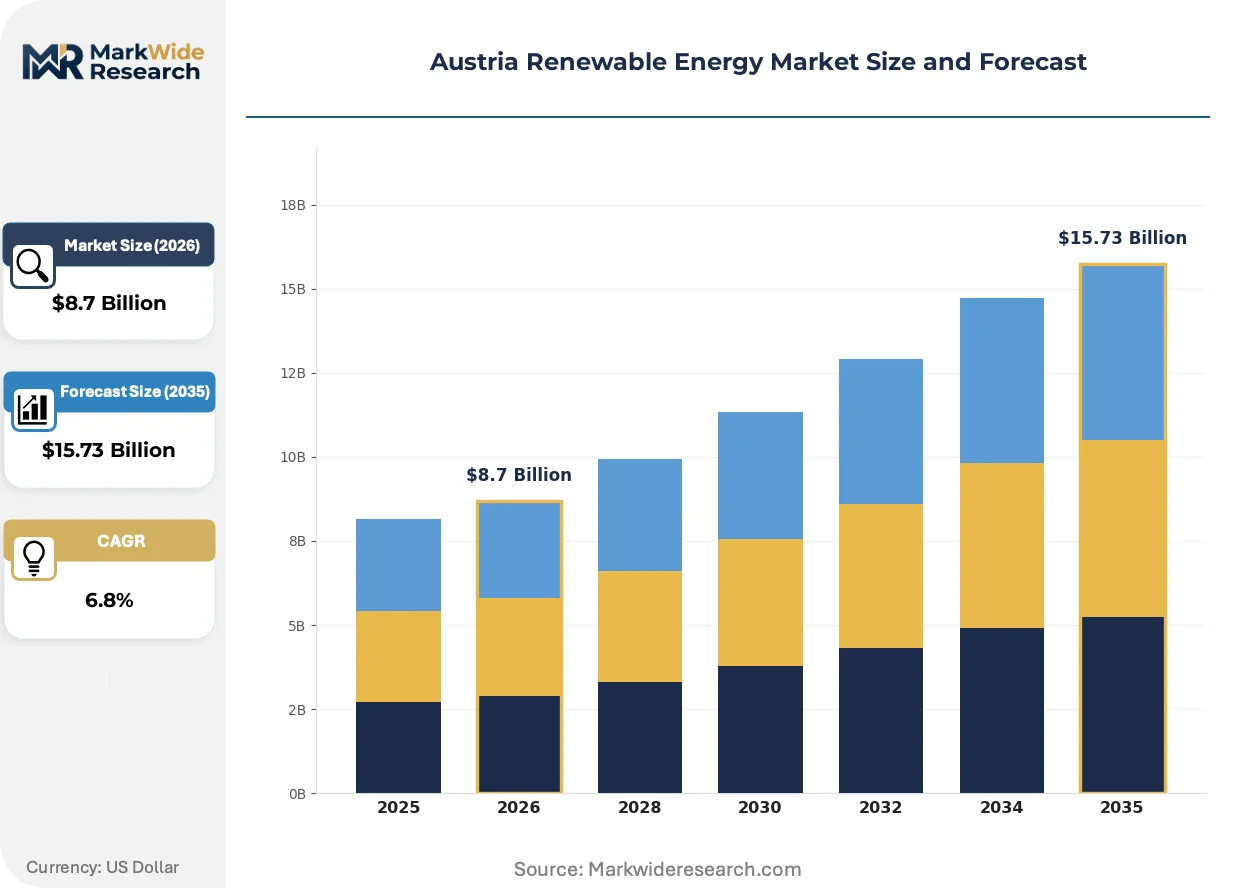
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Wind, Biomass, Hydropower Technology: Photovoltaic, Wind Turbines, Bioenergy, Hydro Turbines Application: Residential, Commercial, Industrial, Utility Scale End User: Households, Corporates, Government, NGOs |
| Companies Covered | Balun Energy, 21energy, Verbund AG, eologix sensor technology, Heizma, enspired trading, Bioenergy and Sustainable Technologies, WOHNWAGON, GridSingularity, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Renewable Energy Market Strategic Shifts
Software-defined trading platforms and modular generation assets are compressing the interval between electricity production and financial settlement, rewarding operators who optimize dispatch algorithms rather than maximizing raw output.
String inverter architectures with module-level power electronics is overtaking central inverter configurations in Austrian commercial solar deployments. Agricultural cooperatives in Burgenland favor distributed conversion to isolate shading losses from individual tracker rows. This granularity is overtaking economies of scale that previously favored megawatt-scale inverter stations, enabling sub-megawatt projects to achieve comparable capacity factors.
The EU Green Deal's REPowerAct acceleration clauses compress permitting timelines for renewable projects in designated priority zones. Austria's Federal Ministry for Climate Action must render environmental decisions within twelve months or face automatic approval. Grid-scale solar developers in Lower Austria exploit this regulatory pressure to bypass provincial objections that historically stalled wind farm approvals.
Corporate buyers now procure electricity through synthetic power purchase agreements rather than physical delivery contracts. Industrial manufacturers in Upper Austria settle price differences against exchange benchmarks while continuing to draw from the public grid. This financial structuring concentrates creditworthy offtakers in portfolio auctions, displacing smaller municipal utilities from competitive bidding rounds.
Austria Renewable Energy Market Segmentation
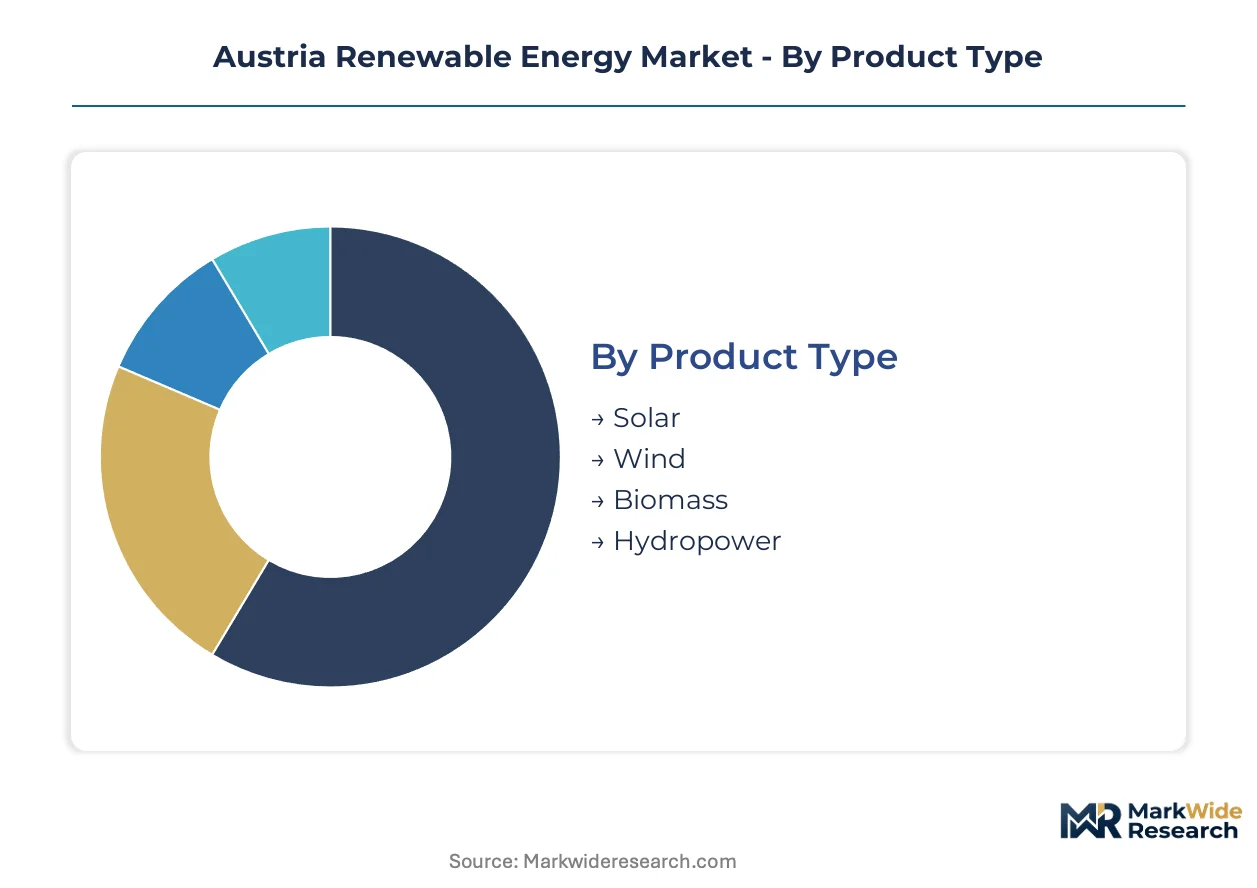
Asset operators in Austria must align procurement strategies with distinct technology lifecycles and application requirements. Segmentation reveals where repowering investments concentrate versus where greenfield deployment dominates.
Product Type:
Upgrade cycles vary dramatically across generation assets, from century-old alpine reservoirs requiring turbine retrofits to photovoltaic arrays facing inverter replacements every decade.
- Solar:Building-integrated photovoltaic mandates in Vienna and Upper Austria drive rooftop deployment above 500 square meters. Commercial developers pre-wire infrastructure during construction to capture streamlined permitting under the Renewable Expansion Act.
- Wind:Horizontal-axis turbines concentrate in Lower Austria and Burgenland where Pannonian air currents deliver superior capacity factors. Flat terrain enables larger rotor diameters than mountainous western provinces permit.
- Biomass:Anaerobic digesters process agricultural residues under tightened Federal Ministry sustainability criteria. Certified organic feedstock eligibility restricts conventional farming operations from thermal energy revenue streams.
- Hydropower:Francis and Pelton turbines anchor Alpine reservoir infrastructure. Verbund AG leverages decades of reservoir flexibility to capture premium pricing across Central European power exchanges.
Hydropower sits at the top of the volume ranking, with solar climbing the fastest.
Technology:
Cost tiers separate mature mechanical systems with decades of operational data from semiconductor-dependent technologies facing supply chain volatility.
- Photovoltaic:String inverter architectures with module-level power electronics displace central inverter configurations in commercial deployments. Burgenland agricultural cooperatives favor distributed conversion to isolate shading losses across tracker rows.
- Wind Turbines:Grid-scale installations require eighteen-month interconnection studies in Lower Austria's high-penetration zones. Distribution system operators lack standardized feasibility protocols.
- Bioenergy:Thermal conversion systems face margin compression as compliance costs for organic certification exceed conventional feedstock market prices. Federal Ministry restrictions reshape project economics.
- Hydro Turbines:Francis turbine retrofits enable sub-minute frequency regulation response times. Grid operators reactivate dormant pumped storage to balance volatile renewable output.
Photovoltaic technology gains share fastest, while hydro turbines retain the steepest margin pool.
Application:
Customer scale determines whether procurement emphasizes synthetic financial contracts or physical infrastructure integration.
- Residential:Rooftop arrays pair with ground-source heat pumps in rural municipalities beyond district heating network reach. Thermal-electric coupling reduces natural gas dependency.
- Commercial:Steel and chemical manufacturers in Upper Austria sign synthetic power purchase agreements. Price differences settle against exchange benchmarks while offtakers draw from the public grid.
- Industrial:Clean electricity procurement targets EU Green Deal Scope 2 emissions compliance. Long-term contracts provide revenue certainty for greenfield wind and solar developers.
- Utility Scale:Grid-scale battery co-location at Vienna metropolitan substations captures arbitrage spreads. Lithium-ion storage monetizes midday solar oversupply against evening demand peaks.
Utility scale applications dominate absolute capacity additions, with commercial offtake expanding most quickly.
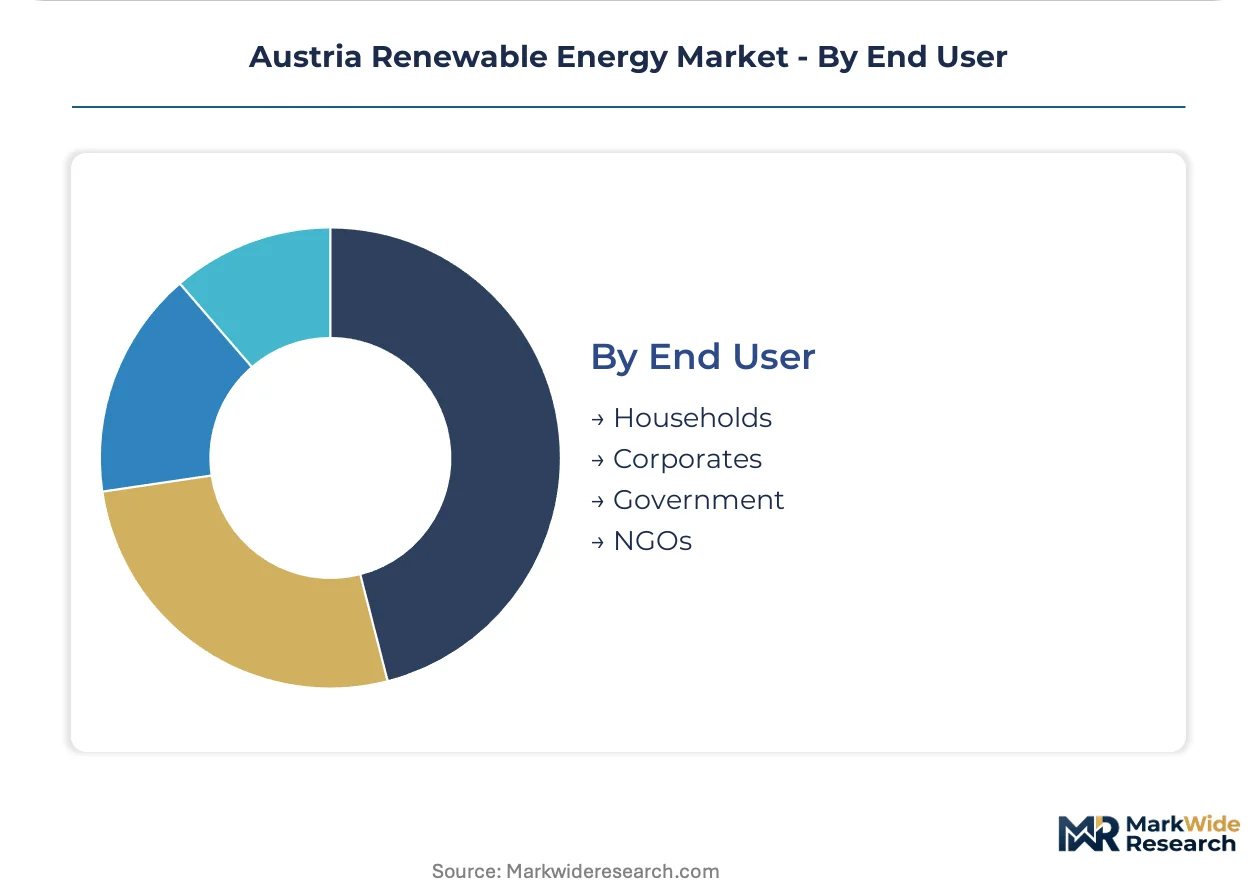
End User:
Procurement authority and creditworthiness stratify across institutional actors with divergent risk appetites and contract tenors.
- Households:Distributed generation adoption concentrates in Burgenland and Lower Austria where agricultural land availability supports ground-mounted arrays. Building codes in Vienna mandate solar-ready roofing.
- Corporates:Creditworthy manufacturers displace smaller municipal utilities from competitive auction bidding. Portfolio concentration favors synthetic structures over physical delivery.
- Government:Federal Ministry for Climate Action administers renewable auction designs and grid connection priority rules. EU Green Deal alignment forces faster permitting timelines.
- NGOs:Environmental advocacy groups monitor sustainability criteria enforcement for biomass feedstock eligibility. Certification standards reshape agricultural residue market access.
Corporate end users anchor contract volume, with government procurement showing the steepest policy-driven expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial clean power procurement outpaces Austria's building-integrated mandates in absolute contract volume, though Vienna's metropolitan battery co-location projects achieve faster regulatory approval cycles than Berlin's equivalent grid-scale developments.
Lower Austria
Pannonian wind corridors attract horizontal-axis turbine deployments with capacity factors exceeding mountainous western provinces. The Federal Ministry for Climate Action administers streamlined permitting under the Renewable Expansion Act for flat-terrain installations. Steel manufacturers in Linz sign synthetic power purchase agreements to meet EU Green Deal Scope 2 targets.
Upper Austria
Chemical producers anchor industrial clean electricity demand through long-term offtake contracts with greenfield solar developers. Provincial environmental offices coordinate with federal regulators to compress grid connection timelines. Grid-scale battery integration concentrates around Linz metropolitan substations to capture midday solar arbitrage spreads.
Vienna
Urban planning codes mandate solar-ready roofing on commercial construction above 500 square meters. Developers pre-wire electrical infrastructure during framing to reduce retrofit costs under building-integrated photovoltaic requirements. Metropolitan ring substations host lithium-ion storage paired with existing distribution infrastructure.
Burgenland
Agricultural cooperatives favor distributed string inverter architectures to isolate shading losses across tracker rows. Provincial governments approve wind farms in eight months versus Tyrol's twenty-four month timelines for identical specifications. Ground-mounted arrays dominate household distributed generation adoption beyond district heating network reach.
Tyrol
Alpine pumped hydro reservoirs undergo Francis turbine retrofits for sub-minute frequency regulation response times. Dormant reservoir infrastructure reactivation supports grid balancing against volatile renewable output. Extended permitting timelines constrain new wind development despite superior hydropower flexibility.
Austria Renewable Energy Market Competitive Environment
Top-tier vendors anchor utility-scale generation and trading infrastructure, while specialized technology developers occupy mid-tier positions around distributed assets and algorithmic optimization. The competitive terrain splits between consolidated hydropower incumbents with decades of reservoir control and fragmented solar-battery integrators competing on installation speed. Three archetypes dominate: alpine reservoir operators leveraging transmission rights, algorithmic trading platforms monetizing flexibility, and decentralized heat-electrical coupling specialists. Strategic moves concentrate on cross-border trading partnerships and building-integrated photovoltaic pre-wiring contracts with commercial developers.
Among Austria-based energy incumbents, Verbund AG occupies a position representing the reservoir-flexibility archetype, while enspired trading exemplifies algorithmic optimization platforms for commercial and industrial portfolios. 21energy sits within the decentralized integration tier, specializing in heat pump systems paired with rooftop photovoltaic arrays. These three entities collectively illustrate the competitive spectrum from centralized trading infrastructure through distributed asset coupling.
| Leading Market Players |
|---|
| Balun Energy |
| 21energy |
| Verbund AG |
| eologix sensor technology |
| Heizma |
| enspired trading |
| Bioenergy and Sustainable Technologies |
| WOHNWAGON |
| GridSingularity |
| Others |
Value Chain & Pricing Dynamics
Silicon module costs from East Asian manufacturers cascade through Austrian installation tenders, compressing margins for EPC contractors while building-integrated photovoltaic mandates in Vienna sustain premium pricing tiers for pre-wired commercial developments.
Pricing Analysis
Capacity additions in Lower Austria and Burgenland are reshaping price floors for utility-scale solar and wind offtake. Project-based long-term power purchase agreements dominate, with price differentiation resting on certification grade for EU Green Deal compliance and volume scale of industrial buyers. Pricing pressure stems from silicon module supply concentration and shipping bottlenecks during commissioning windows. Municipal utilities show highest price sensitivity, while creditworthy steel and chemical manufacturers in Upper Austria accept tighter margins for revenue certainty.
Supply Chain Analysis
Single-source vulnerability sits with East Asian photovoltaic panel manufacturers supplying Austrian installers. Geographic supply concentration centers on China, Vietnam, and South Korea for silicon modules, lithium-ion cells, and power electronics. Raw material dependencies include polysilicon feedstock, rare earth magnets for turbine generators, and copper for grid interconnection. Tariff exposure on imported components creates margin volatility. Distribution runs through specialized EPC contractors and regional equipment distributors serving provincial development clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Austria renewable energy market compounds steadily as EU Green Deal alignment forces accelerated permitting timelines and corporate Scope 2 compliance drives contracted offtake growth.
For Market Incumbents: Acquire dormant Alpine pumped hydro reservoir assets to anchor frequency regulation revenue streams against volatile solar and wind output. Retrofit Francis turbines for sub-minute response times. Consolidate transmission rights into Germany and Switzerland to monetize peak generation spreads. Defend against algorithmic trading platforms by embedding flexibility optimization into proprietary dispatch software. For New Entrants and Emerging Players: Enter via decentralized heat pump integration paired with rooftop photovoltaic arrays in rural municipalities beyond district heating network reach. Target Burgenland agricultural cooperatives favoring distributed string inverter architectures. Exploit streamlined provincial permitting timelines. Lead with thermal-electric coupling value propositions that reduce natural gas dependency. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy feed-in tariff assets approach repowering decisions against auction-based revenue streams. Frame long-term viability around grid-scale battery co-location at metropolitan substations capturing arbitrage spreads. Target EPC contractors with established interconnection queue positions in Lower Austria's high-penetration zones. Watch for automatic approval triggers under REPowerAct acceleration clauses as inflection signals for development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Alpine Pumped Hydro Reactivation | Francis turbine retrofits enable sub-minute frequency regulation services for grid operators balancing renewable volatility. |
| Building-Integrated Photovoltaic Pre-Wiring | Vienna's solar-ready roofing mandates create captive demand channels for commercial developers reducing retrofit costs. |
| Cross-Border Hydropower Trading | Verbund AG leverages transmission rights into Germany and Switzerland to monetize peak generation against nuclear baseload. |
| Grid-Scale Battery Co-Location | Lithium-ion storage at Vienna metropolitan substations captures arbitrage spreads between midday solar oversupply and evening peaks. |
| Synthetic Power Purchase Agreement Structuring | Upper Austria steel manufacturers settle price differences against exchange benchmarks while drawing from the public grid. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged utility planning officers at Verbund AG and regional grid operators, IPP project developers active in Lower Austria and Burgenland, EPC contractors managing interconnection queues, and Federal Ministry for Climate Action officials administering auction designs. Secondary validation drew from E-Control regulatory filings, IEA renewable energy reports, EU Green Deal implementation documents, and provincial environmental impact assessment records. Bottom-up project pipelines and top-down macroeconomic drivers were triangulated to anchor value estimates.
Segment-weighting approaches distributed capacity additions across technology type, application scale, and provincial regulatory framework. The analytical framework modeled solar, wind, hydropower, and biomass segments separately across the projection horizon, with cross-elasticities between building-integrated mandates and utility-scale development. CAGRs were derived from installed capacity trajectories and normalized revenue per megawatt-hour under evolving auction mechanisms. Grid connection queue depth and permitting timeline differentials between provinces fed directly into deployment velocity assumptions.
Inputs from Federal Ministry auction databases and E-Control interconnection registers were available through the study window; gaps in real-time commercial and industrial offtake contract terms introduce uncertainty bands around revenue forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
China Wind Power Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
PV Water Heater Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market