
 Renewable Energy Consulting Market | 2026-2036
Renewable Energy Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Consulting Market Insights
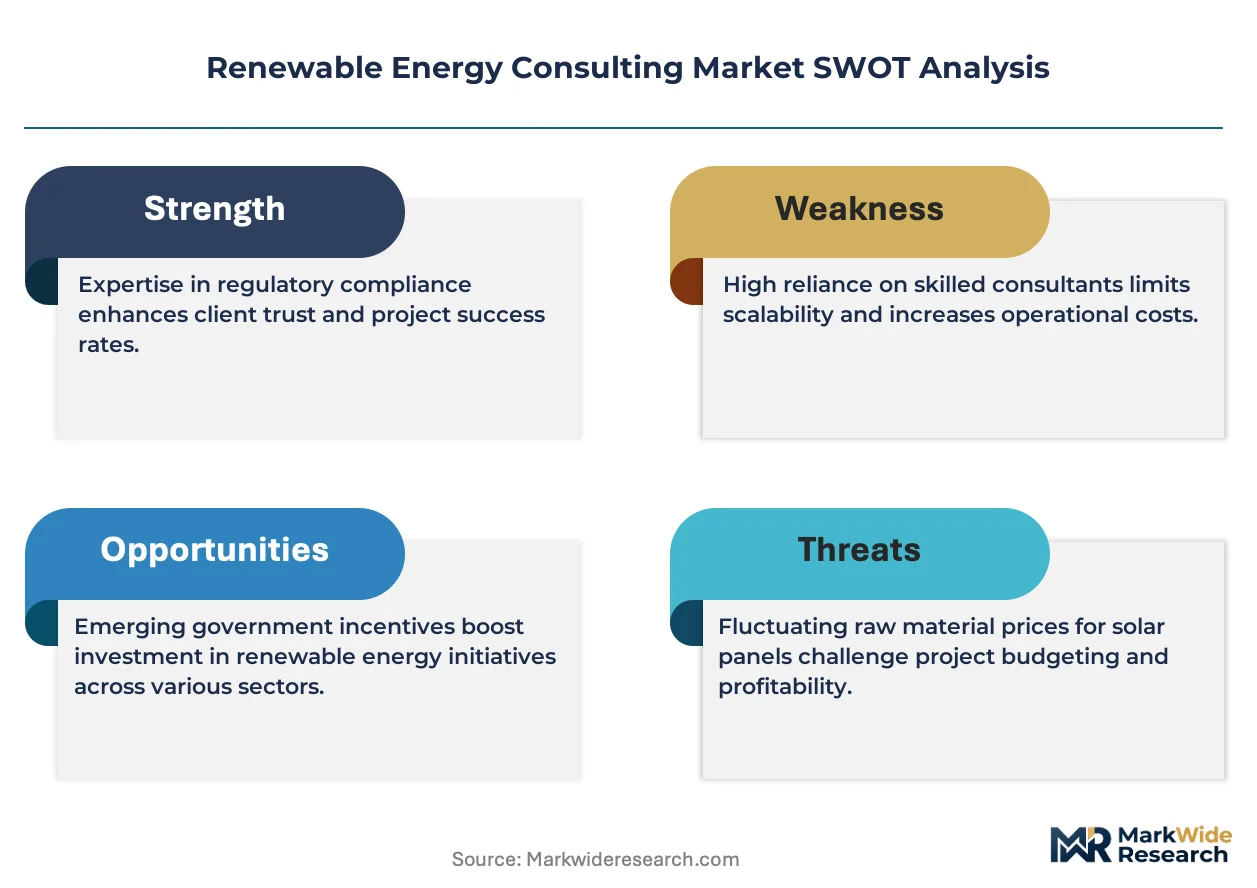
The gap between standalone engineering assessments and full-project development advisory is narrowing as battery storage and hybrid renewable configurations complicate grid integration workflows. Wood Mackenzie anchors its competitive position through proprietary power market modeling tools that span LCOE forecasting to merchant revenue stress-testing. E3 (Energy and Environmental Economics) specializes in California and Texas nodal price analysis, leveraging deep regional regulatory fluency. McKinsey & Company extends its energy practice into hydrogen and carbon capture feasibility, competing for capital-intensive project advisory mandates.
Renewable energy consulting encompasses technical, economic, and regulatory advisory services that evaluate resource potential, optimize project design, and navigate permitting for clean energy assets; consultants deploy geospatial mapping, production simulation software, and power purchase agreement structuring to de-risk capital deployment across solar, wind, and emerging storage technologies. Policy advisory and renewable energy feasibility services capture the dominant share of fee revenue as developers front-load regulatory risk assessment before financial close. Among technology segments, solar power and wind energy consulting occupy mature, high-volume positions, while biomass and hydro energy attract niche specialist firms with distinct civil engineering and resource assessment capabilities.
The US Inflation Reduction Act, administered through IRS guidance and FERC interconnection rules, creates compliance-driven demand for tax credit monetization and queue reform advisory. In Europe, the EU Green Deal and REPowerEU framework, enforced through national energy regulators and the EMA-related sustainability disclosure rules, mandate corporate renewable procurement strategies that require external consultant support. Stakeholders must monitor how evolving grid connection timelines and domestic content bonus credit rules reshape the skill mix and pricing power of specialized advisory practices.
Market Dynamics
Utility-scale developers now bundle grid interconnection studies with resource feasibility assessments, compressing traditional service boundaries as battery storage and hybrid configurations complicate power flow modeling and merchant revenue forecasting.
Growth Catalysts
- US IRA Production Tax Credits:The Inflation Reduction Act's domestic content bonus credits redirect capital toward clean energy manufacturing, creating compliance-driven demand for tax credit monetization advisory.
- Germany's Energiewende Mandates:Grid modernization requirements sustain consultant utilization across transmission planning, storage siting, and renewable integration studies.
- Hybrid Project Proliferation:Solar-plus-storage and wind-plus-battery configurations require integrated technical and economic modeling that standalone engineering firms cannot deliver.
Market Restraints
- Interconnection Queue Backlogs:FERC Order 2023 implementation delays extend project timelines, freezing consultant engagement cycles and deferring fee recognition.
- Specialized Talent Scarcity:Power market modelers with nodal price forecasting expertise command premium compensation, compressing advisory firm margins.
- Software Commoditization:Open-source production simulation tools erode proprietary model differentiation that previously anchored pricing power.
Strategic Opportunities
- Hydrogen and Carbon Capture Feasibility:Capital-intensive project advisory for emerging clean fuel and industrial decarbonization assets opens high-margin mandates beyond traditional renewables.
- Corporate Renewable Procurement Strategy:EU CSRD and REPowerEU sustainability disclosure rules mandate external consultant support for corporate buyers structuring virtual power purchase agreements.
- Merchant Revenue Stress-Testing:Wholesale market exposure analysis for battery storage and hybrid projects creates recurring advisory relationships beyond development-phase engagements.
Industry Challenges
- Grid Integration Complexity:Battery storage and hybrid renewable configurations demand cross-functional teams combining power systems engineering, energy market economics, and regulatory expertise that few firms have assembled.
- Permitting Timeline Uncertainty:Evolving environmental review requirements and transmission access protocols force consultants to maintain redundant scenario libraries and revise deliverables mid-engagement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Consulting Market |
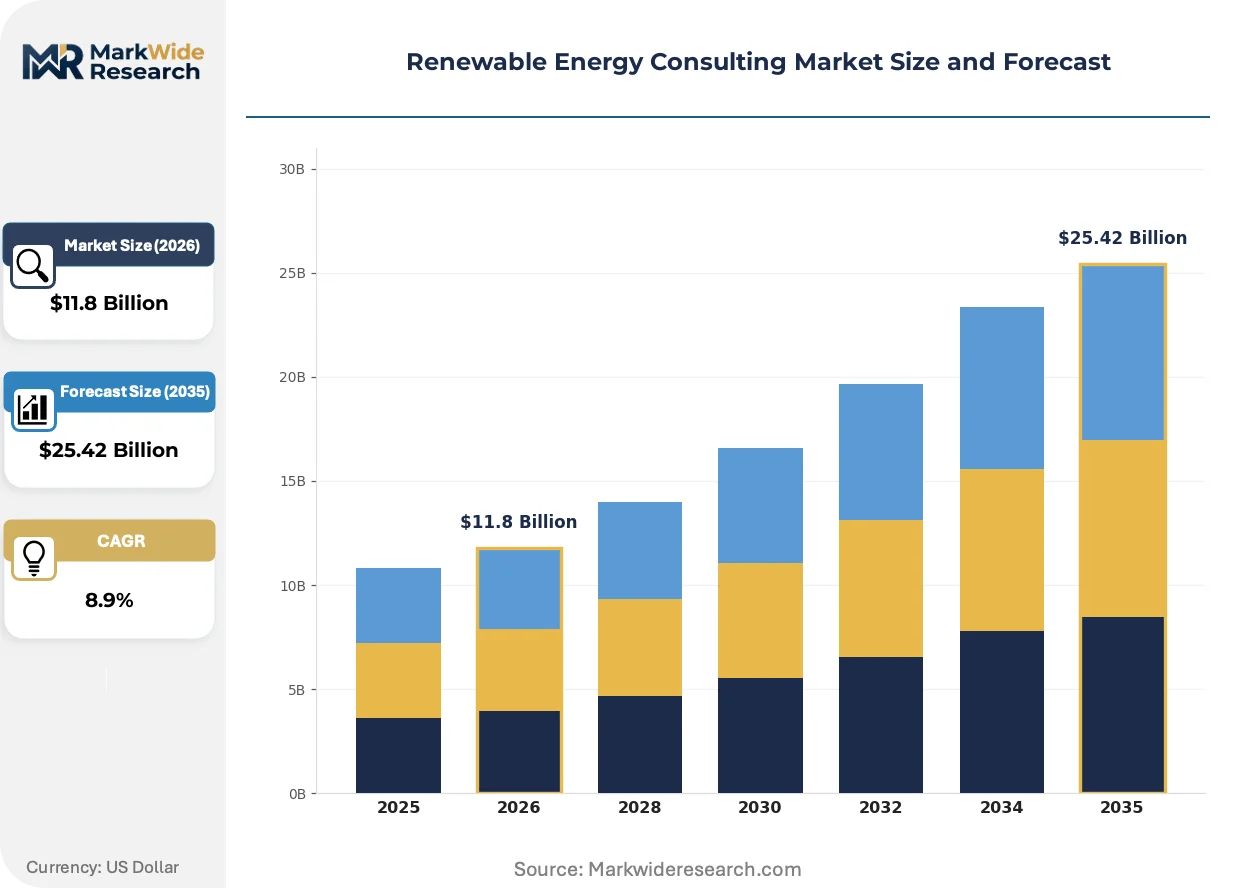
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25.42 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Carbon Footprint Analysis, Renewable Energy Feasibility, Policy Advisory, Sustainability Assessment Client Type: Corporations, Government Entities, Nonprofits, Educational Institutions Technology: Solar Power, Wind Energy, Biomass, Hydro Energy End Use Industry: Manufacturing, Transportation, Agriculture, Real Estate |
| Companies Covered | ICF International, E3 (Energy and Environmental Economics), Wood Mackenzie, McKinsey & Company, Boston Consulting Group, Deloitte, Bain & Company, Ernst & Young, ERM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Consulting Market Trends and Innovations
Advisory service delivery is fragmenting across specialized technical boutiques and integrated strategy consultancies as project complexity outpaces generalist capabilities and regulatory compliance demands deepen domain expertise requirements.
Power market modeling is migrating from deterministic production cost simulations toward stochastic merchant revenue analysis that captures price volatility, basis risk, and battery arbitrage value. Large-scale storage developers now require nodal price forecasting and congestion revenue rights valuation as standard scope. This capability compression favors consultancies with proprietary wholesale market data partnerships and in-house dispatch optimization engines.
The EU Green Deal and REPowerEU framework, enforced through national energy regulators and CSRD-related sustainability disclosure obligations, mandate corporate renewable procurement strategies that require external advisory support. Industrial buyers must document clean energy sourcing against Scope 2 emissions targets. This regulatory pressure concentrates consultant demand in Germany, Spain, and the Netherlands where manufacturing clusters face the most stringent disclosure timelines.
Fee structures are unbundling from lump-sum development advisory toward modular engagements aligned with project milestones. Developers now procure resource assessment, grid interconnection study, and offtake structuring as separate contracts rather than bundled mandates. This disaggregation is most visible in Texas and California, where nodal market complexity and queue reform uncertainty prompt developers to stage consultant spend against regulatory clarity and interconnection agreement execution.
Renewable Energy Consulting Market Segmentation
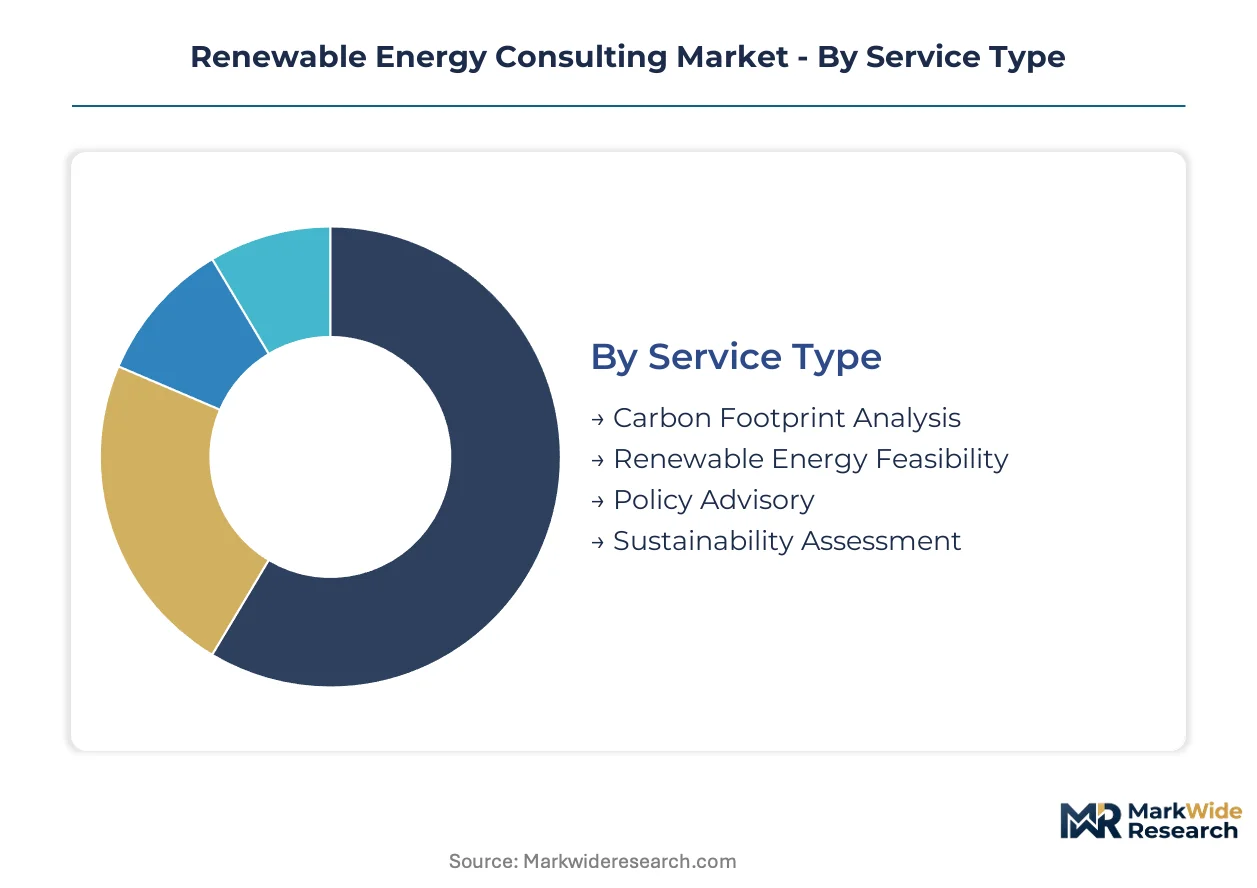
Renewable energy consulting engagements fragment across service maturity, client sophistication, and technology complexity. Each segmentation axis demands distinct capability bundles and pricing architectures from advisory providers.
Service Type:
Mature compliance-driven services anchor fee revenue while emerging analytical offerings capture premium pricing.
- Policy Advisory:Regulatory navigation across FERC interconnection rules, IRA tax credit guidance, and EU Green Deal implementation commands front-loaded engagement fees. Developers in Germany and Texas procure these services before financial close to de-risk permitting timelines.
- Renewable Energy Feasibility:Resource assessment, production simulation, and LCOE modeling constitute the technical core of development-phase advisory. Utility-scale solar and wind developers in California and Spain bundle geospatial analysis with grid integration studies.
- Carbon Footprint Analysis:Scope 2 emissions accounting and clean energy procurement documentation supports corporate CSRD compliance.
- Sustainability Assessment:ESG disclosure preparation and supply chain decarbonization roadmaps serve industrial manufacturing clusters.
Policy Advisory retains volume leadership; Renewable Energy Feasibility holds the steepest expansion curve.
Client Type:
Procurement scale and regulatory exposure determine engagement scope and fee structure across buyer categories.
- Corporations:Industrial buyers structure virtual power purchase agreements and document renewable sourcing against Scope 2 targets. Manufacturing clusters in the Netherlands and Spain drive demand amid stringent EU sustainability disclosure timelines.
- Government Entities:Grid modernization mandates and transmission planning contracts sustain multi-year advisory relationships. German Energiewende implementation and US Department of Energy loan guarantee applications require specialized regulatory fluency.
- Nonprofits:Mission-driven clean energy procurement and grant-funded feasibility studies operate on constrained budgets.
- Educational Institutions:Campus decarbonization planning and research partnership structures generate episodic, lower-margin engagements.
Corporations dominate current spend; Government Entities provide the most durable contract pipelines.
Technology:
Consulting intensity varies with project complexity and merchant revenue exposure across generation technologies.
- Solar Power:Distributed and utility-scale photovoltaic deployment drives the highest advisory volume. Developers require interconnection queue strategy, domestic content compliance, and battery co-location optimization across Texas, California, and Spain.
- Wind Energy:Offshore and onshore project development demands specialized resource assessment and marine spatial planning. North Sea lease rounds and Great Plains transmission access drive consultant utilization in Germany and the US.
- Biomass:Feedstock supply chain validation and emissions accounting complexity attracts niche specialist firms.
- Hydro Energy:Civil engineering requirements and environmental review timelines limit addressable market scope.
Solar Power commands the deepest consultant penetration; Wind Energy is climbing fastest in offshore advisory.
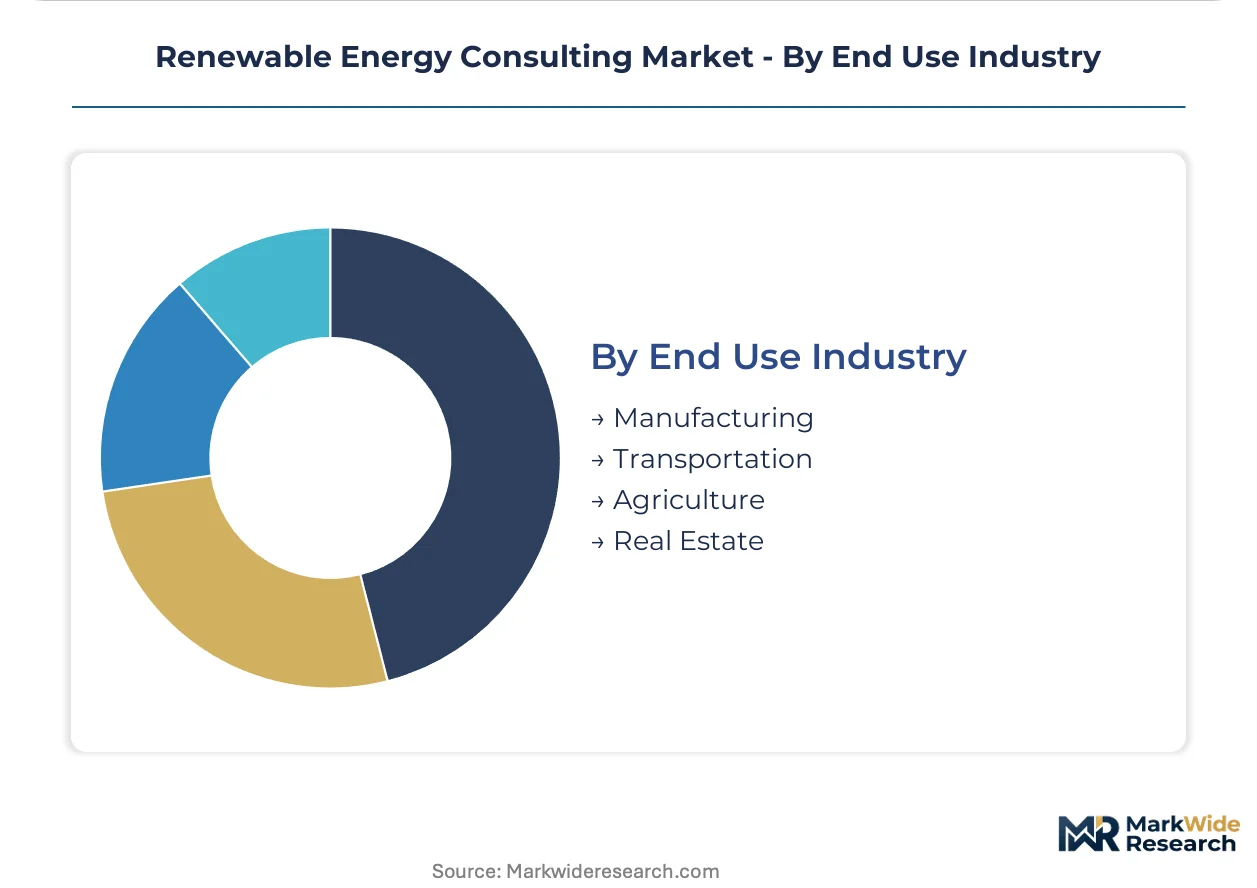
End Use Industry:
Sector-specific decarbonization pressures and energy intensity shape advisory demand patterns.
- Manufacturing:Energy-intensive industrial facilities face the most stringent Scope 2 disclosure requirements. German automotive and Dutch chemical clusters procure renewable procurement strategy and on-site generation feasibility.
- Transportation:Fleet electrification and hydrogen fuel infrastructure planning create emerging advisory demand. Port authorities and logistics operators in California and the Netherlands require charging infrastructure and clean fuel supply chain analysis.
- Agriculture:On-farm solar and biogas development supports rural decarbonization with modest consulting intensity.
- Real Estate:Building-integrated renewable systems and green lease structuring generate localized, project-scale engagements.
Manufacturing anchors current revenue; Transportation is expanding most quickly in hydrogen and electrification advisory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering consultancies export grid modernization advisory to Polish and Baltic utilities expanding renewable integration capacity. This trade corridor channels specialized transmission planning expertise eastward as EU cohesion funds accelerate clean energy deployment across Central Europe.
United States
Texas and California nodal markets drive demand for merchant revenue forecasting and battery arbitrage valuation. FERC Order 2023 interconnection reforms and IRA domestic content bonus credits sustain compliance advisory spend. ERCOT price volatility in Houston and CAISO congestion management in San Diego anchor specialized consultant deployment.
Germany
Grid operators procure transmission expansion and storage siting studies under Energiewende implementation mandates. Bundesnetzagentur enforcement of renewable integration timelines sustains multi-year advisory contracts. Industrial clusters in North Rhine-Westphalia and Bavaria commission corporate PPA structuring for Scope 2 compliance.
Spain
Utility-scale solar and hybrid project developers require resource assessment and grid integration studies for auction participation. REPowerEU framework implementation through national energy regulators mandates external advisory support. Manufacturing concentrations in Catalonia and Andalusia drive corporate renewable procurement strategy engagements.
Netherlands
Port authorities and chemical clusters procure hydrogen infrastructure and electrification feasibility studies. EU CSRD sustainability disclosure rules enforce Scope 2 documentation requirements for industrial buyers. Rotterdam and Eindhoven manufacturing hubs anchor clean energy sourcing advisory demand.
United Kingdom
Offshore wind lease rounds and grid connection queue reform create specialized marine spatial planning and transmission access advisory. Contracts for Difference auction mechanics sustain LCOE optimization and revenue forecasting demand. Scottish and North Sea development clusters anchor technical consultancy utilization.
Renewable Energy Consulting Market Competitive Landscape
On the supply side, the industry is consolidating around integrated strategy consultancies with energy practices and specialized technical boutiques with proprietary modeling capabilities. Tiered competition separates premium advisory firms commanding project development mandates from mid-market players competing on regulatory compliance volume. Three archetypes dominate: global strategy houses extending energy sector coverage, engineering-derived consultancies with power systems expertise, and regulatory specialists with deep FERC or EU administrative fluency. M&A activity concentrates on acquiring nodal price forecasting talent and grid interconnection queue management capabilities.
Within the engineering-specialist tier, Wood Mackenzie and E3 exemplify proprietary model differentiation, while McKinsey & Company occupies the strategy-consultancy vector extending into hydrogen and carbon capture feasibility. These three firms represent distinct competitive positioning archetypes: data-anchored power market modeling, regional regulatory depth, and capital-intensive project advisory scale.
| Leading Market Players |
|---|
| ICF International |
| E3 (Energy and Environmental Economics) |
| Wood Mackenzie |
| McKinsey & Company |
| Boston Consulting Group |
| Deloitte |
| Bain & Company |
| Ernst & Young |
| ERM |
| Others |
Pricing and Supply Chain Analysis
Houston's concentration of power market modeling talent anchors pricing power for merchant revenue forecasting services, with ERCOT nodal expertise commanding premium rates that compress margins for firms without proprietary dispatch optimization capabilities. Domestic content bonus credit rules under the US IRA reshape procurement patterns as developers stage consultant spend against interconnection agreement execution and regulatory clarity.
Pricing Analysis
Solar-plus-storage project advisory commands rates 40% above standalone solar feasibility studies, while wind-plus-battery configurations and hydrogen feasibility sit at the premium tier. Project-based engagement structures dominate, with fee differentiation driven by proprietary model access and regulatory certification depth. Pricing pressure stems from open-source production simulation tools eroding proprietary differentiation. Corporate procurement teams exhibit highest price sensitivity; utility-scale developers with IRA tax credit exposure show lowest.
Supply Chain Analysis
US export controls on power systems simulation software limit technology transfer to Chinese engineering consultancies, constraining supply expansion. Talent concentrates in the United States, Germany, and the United Kingdom, where grid operator relationships and regulatory fluency develop over multi-year engagement cycles. The supply chain draws from academic power systems programs, utility planning departments, and specialized regulatory boutiques. Single-source vulnerability sits with nodal price forecasting specialists. Distribution runs through direct developer relationships and EPC contractor referrals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advisory service fragmentation creates entry niches as hybrid project complexity outpaces generalist capabilities and regulatory compliance demands deepen domain expertise requirements.
For Market Incumbents: Build proprietary data moats through exclusive wholesale market data partnerships and in-house dispatch optimization engines. Acquire nodal price forecasting talent in Texas and California to defend against engineering boutiques capturing merchant revenue stress-testing mandates. Deepen vertical integration into grid interconnection queue management capabilities.
For New Entrants and Emerging Players: Establish a beachhead in hydrogen and carbon capture feasibility advisory, where capital-intensive project complexity and limited specialist supply create white-space opportunity. Target corporate manufacturing clusters in the Netherlands and Spain facing stringent CSRD Scope 2 disclosure timelines. Lead with sustainability assessment and clean energy procurement documentation as entry wedge.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because policy implementation timelines across FERC interconnection reform and EU Green Deal enforcement sustain multi-year advisory demand. Acquisition targets should combine power systems engineering with regional regulatory fluency. Watch FERC Order 2023 implementation velocity as inflection indicator for consultant utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Model Development | Power market dispatch engines differentiate Wood Mackenzie and E3 from compliance-focused competitors. |
| Regulatory Certification Investment | Deep FERC and Bundesnetzagentur fluency secures multi-year grid modernization contracts. |
| Specialist Talent Acquisition | Nodal price forecasters with ERCOT and CAISO expertise command premium engagement rates. |
| Corporate PPA Structuring Capability | Virtual power purchase agreement expertise captures EU CSRD-driven manufacturing demand. |
| Hydrogen Feasibility Expansion | Capital-intensive clean fuel advisory opens high-margin mandates beyond mature solar and wind. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base. Primary interviews combined with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up engagement tracking across service types, client categories, and technology segments triangulated with top-down market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling across fuel source, generation capacity tier, project scale, and regional grid type. CAGRs derived from installed capacity forecasts, consultant utilization rates, and fee structure evolution. Wholesale market volatility indices and interconnection queue depth served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and clean energy capital availability would shift the trajectory. Forecasts reflect documented assumptions on IRA implementation timelines and EU Green Deal enforcement velocity. Material shifts in FERC interconnection reform pace or domestic content bonus credit rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Rectenna Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market