
 Algeria Oil and Gas Upstream Market | 2026-2036
Algeria Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Oil and Gas Upstream Market Outlook
Algerian conventional producers is pivoting toward unconventional and deepwater portfolios to offset decline at maturing Saharan supergiants. Sonatrach anchors domestic output through its dominance of the Hassi Messaoud and Hassi R'Mel complexes. TotalEnergies leverages its long-standing partnership with Sonatrach to sustain positions in the Timimoun and Reggane basins. Eni competes through specialized expertise in desert exploration and tight gas development.
The Algeria Oil and Gas Upstream sector encompasses exploration, drilling, production and enhanced oil recovery activities targeting hydrocarbon reservoirs at depths from 2,000 to 5,000 meters across onshore and offshore concessions. Crude oil and natural gas extraction serves refineries, power generation facilities and export markets via pipeline and LNG terminal infrastructure. Natural gas production leads segment value due to established pipeline supply contracts with Southern European buyers. Enhanced oil recovery is expanding fastest as operators deploy waterflooding and gas injection to boost recovery factors at mature fields.
Algeria's hydrocarbon sector operates under framework law and oversight from the national hydrocarbon regulator, with licensing rounds structured to attract international capital under production-sharing terms. The country's national petroleum agency shapes market access through bid round design and local content requirements that mandate Algerian workforce and supplier participation. Stakeholders must monitor regulatory revisions to production-sharing contract fiscal terms and the pace of unconventional exploration licensing.
Market Dynamics
Algerian upstream operators face mounting pressure to extract more from maturing Saharan supergiants as conventional reserves deplete, forcing accelerated adoption of enhanced oil recovery and unconventional drilling techniques to sustain production volumes.
Growth Catalysts
- Enhanced Recovery Mandates:The national hydrocarbon regulator is tightening recovery factor requirements at mature fields, compelling operators to deploy waterflooding and gas injection systems.
- European Pipeline Contracts:Long-term supply agreements with Italian and Spanish buyers anchor natural gas offtake, financing upstream reinvestment in the Illizi and Berkine basins.
- Unconventional Licensing Rounds:New exploration permits for shale and tight gas formations in southern Algeria are attracting specialized drilling contractors with horizontal fracturing expertise.
Market Restraints
- Capital Intensity Barriers:Deepwater and shale projects require sustained investment cycles exceeding conventional field timelines, straining operator balance sheets.
- Service Provider Concentration:Desert drilling and completions capacity clusters with a limited pool of international contractors, creating bottleneck risks during activity surges.
- Subsidy-Dominated Domestic Market:Price controls on natural gas for Algerian power generation and industry compress upstream returns, diverting capital toward export-oriented developments.
Strategic Opportunities
- Offshore Frontier Zones:Unexplored deepwater blocks in the Mediterranean shelf offer untapped reserve potential for operators with subsea production system capabilities.
- Carbon Capture Integration:Associated gas reinjection for enhanced oil recovery aligns with emerging EU carbon border adjustment mechanisms, preserving European market access.
- Local Content Partnerships:Joint ventures with Algerian service firms satisfy workforce participation rules while building permanent technical capacity in-country.
Industry Challenges
- Specialized Talent Scarcity:Reservoir engineers with tight gas and shale fracturing experience remain concentrated with international operators, constraining Sonatrach's technology transfer goals.
- Legacy Infrastructure Integration:New digital monitoring systems must interface with decades-old surface facilities at Hassi Messaoud and Hassi R'Mel, compling automation rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Oil and Gas Upstream Market |
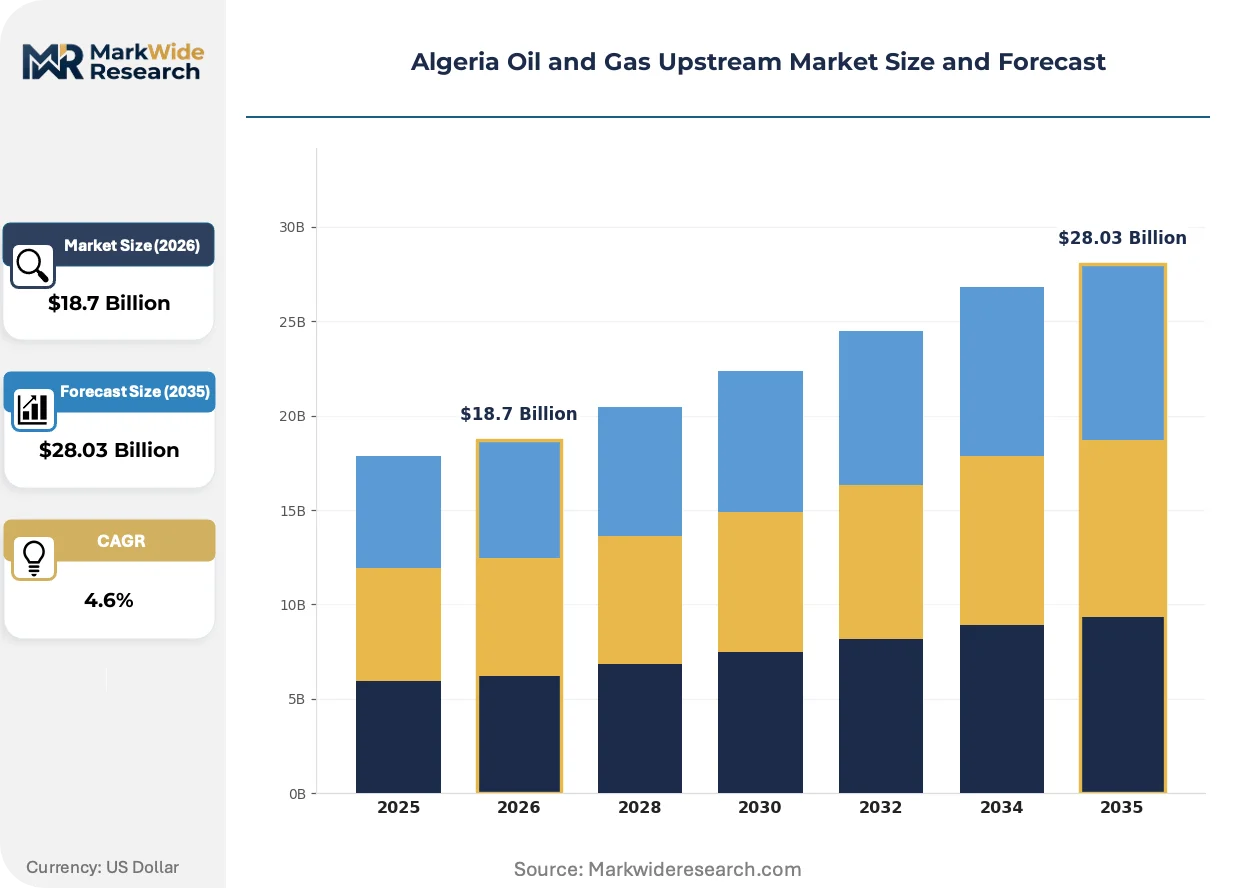
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Condensate, NGL Technology: Exploration, Drilling, Production, Enhanced Oil Recovery End User: Refineries, Power Plants, Petrochemical Plants, Export Markets Service Type: Field Development, Maintenance, Equipment Supply, Consulting |
| Companies Covered | BP, PTTEP, Sonatrach, Zhongman Petroleum, Sinopec, TotalEnergies, QatarEnergy, Equinor, Eni, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Oil and Gas Upstream Market Strategic Shifts
Digital reservoir characterization and subsea processing architectures are redefining how Algerian operators approach mature field rejuvenation and frontier exploration, compressing decision cycles from seismic acquisition to first production.
Advanced 4D seismic monitoring is consolidating subsurface imaging capabilities across Algerian concessions. Sonatrach and its partners now deploy permanent ocean-bottom and buried cable arrays to track fluid movement in real time. This capability is consolidating reservoir management from reactive well intervention to predictive optimization, extending economic field life at Hassi Messaoud.
Algeria's hydrocarbon framework law revisions are tightening local content thresholds and production-sharing fiscal terms. The national petroleum agency now mandates Algerian workforce percentages and domestic supplier participation in drilling contracts. Offshore license holders face the steepest compliance adjustments as frontier developments require the most imported equipment and expertise.
European refinery buyers are compressing contracting cycles from annual tenders to multi-year offtake partnerships. ENI and TotalEnergies have shifted from spot market exposure to integrated supply agreements spanning exploration through delivery. This concentration is most visible in pipeline-linked gas contracts serving Italy's Po Valley industrial cluster and Spain's regasification terminals.
Algeria Oil and Gas Upstream Market Segmentation
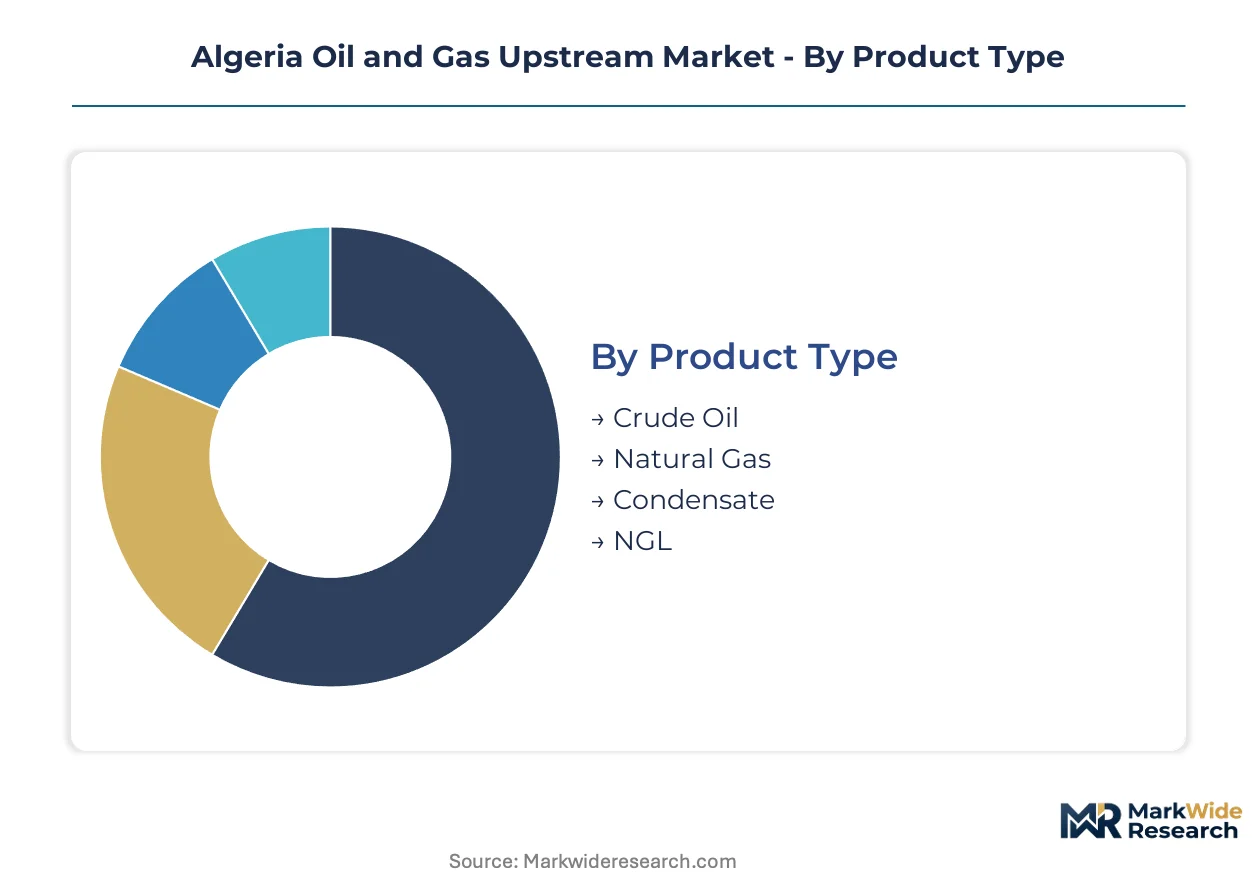
Upstream operators in Algeria deploy distinct technical and commercial configurations to access conventional, unconventional, and offshore reservoirs. Segment boundaries reflect where capital concentrates, which recovery technologies dominate, and how European offtake contracts shape field development priorities.
Product Type:
Supply concentrates around pipeline-ready natural gas and export-grade crude, with infrastructure availability determining which streams attract development capital.
- Natural Gas:Dry and associated gas from the Hassi R'Mel complex and Illizi Basin fields. European pipeline contracts with Italian and Spanish buyers anchor offtake, financing continued drilling in mature Saharan provinces.
- Crude Oil:Light sweet grades from the Hassi Messaoud supergiant and Berkine Basin extensions. Refinery demand from European Mediterranean ports sustains production, though recovery factors require waterflooding investment to maintain volumes.
- Condensate:Light liquid hydrocarbons separated from wet gas streams at surface facilities. Processing capacity at Hassi R'Mel limits output scaling.
- NGL:Propane, butane, and heavier fractions recovered from gas processing trains. Petrochemical feedstock demand in Algeria's domestic market absorbs most volumes.
Today's leader: Natural Gas. Tomorrow's challenger: Condensate.
Technology:
Cost tiers separate frontier exploration from mature field rejuvenation, with capital intensity climbing steeply as operators move from conventional production to enhanced recovery and unconventional drilling.
- Enhanced Oil Recovery:Waterflooding and gas injection systems deployed at Hassi Messaoud and mature Berkine fields. Regulatory mandates for improved recovery factors are accelerating capital allocation toward these techniques.
- Drilling:Extended-reach and horizontal wells targeting tight gas formations in southern Algeria. Specialized desert drilling contractors command premium rates for shale and deep basin access.
- Exploration:3D seismic acquisition and frontier wildcatting in offshore Mediterranean blocks and southern shale provinces. Licensing rounds are attracting Asian NOC capital for untested formations.
- Production:Conventional beam pumps and gas lift systems at established Saharan fields. Surface facility constraints limit output flexibility at aging infrastructure.
Enhanced Oil Recovery commands the steepest expansion trajectory as operators confront decline curves at supergiant fields.
End User:
Customer type determines contract structure, with long-term pipeline agreements offering volume certainty against spot market exposure.
- Export Markets:Pipeline deliveries to Italy and Spain plus LNG cargoes to European regasification terminals. Multi-year offtake partnerships are replacing annual tenders, concentrating buyer relationships around ENI and TotalEnergies.
- Refineries:Mediterranean coastal processors seeking light sweet crude for gasoline yield. Algerian grades compete with Libyan and Caspian supply into European refining circuits.
- Power Plants:Domestic Algerian gas-fired generation serving subsidized electricity tariffs. Price controls compress upstream returns, diverting investment toward export-oriented developments.
- Petrochemical Plants:Ethane and propane feedstock demand from Algeria's emerging downstream complex. Local content requirements shape supplier selection for integrated projects.
Export Markets absorb the dominant revenue share. Power Plants face the steepest margin compression from domestic pricing policy.
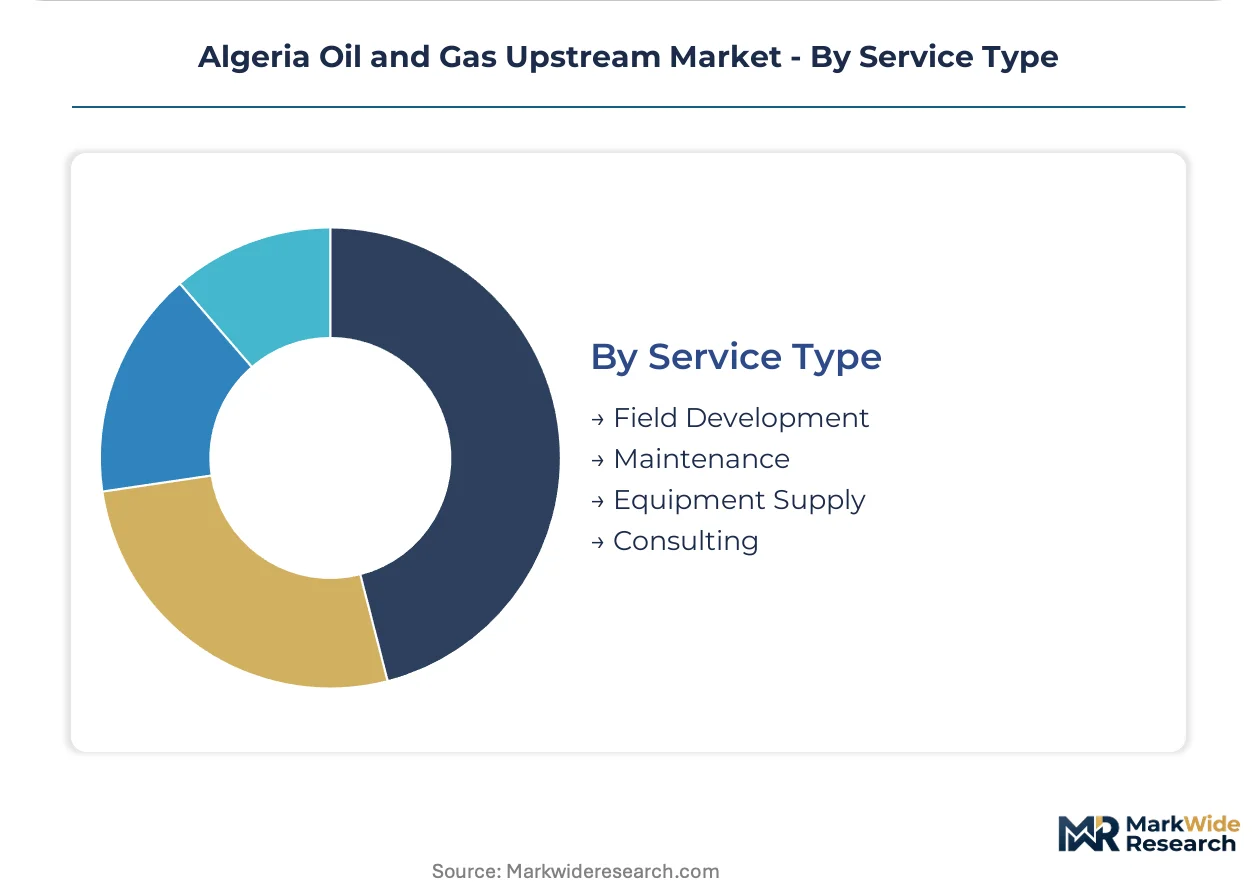
Service Type:
Geography fragments service provider concentration, with desert drilling capacity clustering around international contractors while maintenance work distributes across Algerian joint ventures.
- Field Development:Integrated project execution spanning seismic through production hookup. Sonatrach partnerships with international operators concentrate expertise in Timimoun and Reggane basin developments.
- Equipment Supply:Subsea trees, wellheads, and processing modules for offshore and onshore installations. Local content thresholds are mandating Algerian supplier participation in procurement.
- Maintenance:Workover rigs and facility integrity management at mature Saharan fields. Workforce localization requirements are building permanent technical capacity in-country.
- Consulting:Reservoir characterization and production optimization studies. Tight gas and shale fracturing expertise remains concentrated with international specialists, constraining technology transfer.
Field Development captures the largest contract values. Consulting faces the tightest talent scarcity as unconventional exploration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward basins with lighter fiscal terms and lower recovery-cost thresholds. Algeria's southern provinces attract capital that faces stricter environmental compliance in North African coastal concessions.
Illizi Basin
Gas-focused drilling targets tight sandstone formations near the Libyan border. The national hydrocarbon regulator permits extended-reach horizontal wells under revised production-sharing terms. Operators cluster around In Amenas and In Salah processing facilities where pipeline connectivity to European markets is established.
Berkine Basin
Light crude output from Hassi Messaoud extensions sustains refinery supply contracts with Spanish Mediterranean ports. SONATRACH enforces enhanced recovery mandates through waterflooding requirements at mature fields. Field camps at Rhourde El Baguel support drilling contractors with desert logistics infrastructure.
Timimoun Basin
Tight gas development absorbs specialized fracturing capacity from Asian service providers. Local content rules mandate Algerian workforce participation in drilling contracts. Production facilities at Timimoun field integrate with the Trans-Saharan pipeline corridor serving Algerian power generation demand.
Reggane Basin
Deep basin gas exploration licenses attract NOC investment under frontier terms with extended cost-recovery periods. The national petroleum agency structures bid rounds to capture technology transfer for shale drilling expertise. Camp-based operations at Ahnet field cluster international contractor capacity for extended-reach completions.
Offshore Mediterranean
Unexplored deepwater blocks require subsea production systems and floating platform capability. Offshore licensing carries the steepest local content thresholds for equipment procurement. Operators evaluate prospects near Algiers coastal infrastructure where pipeline tieback costs are minimized.
Algeria Oil and Gas Upstream Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue frontier exploration licenses and unconventional drilling partnerships. SONATRACH dominates domestic production through control of Hassi Messaoud and Hassi R'Mel infrastructure. International operators concentrate in partnership structures with the national champion. Competitive moves center on technology licensing for enhanced recovery and portfolio diversification into shale and deepwater positions.
Within the national champion tier, Sonatrach anchors domestic output and controls pipeline access. Among European integrated operators, TotalEnergies and Eni exemplify partnership-based positioning through long-standing production-sharing arrangements. BP represents the international specialist archetype with deepwater and desert exploration expertise. These three occupy positions that reflect distinct strategic vectors: state-backed vertical integration, European offtake integration, and technical specialization.
| Leading Market Players |
|---|
| BP |
| PTTEP |
| Sonatrach |
| Zhongman Petroleum |
| Sinopec |
| TotalEnergies |
| QatarEnergy |
| Equinor |
| Eni |
| Others |
Value Chain & Pricing Dynamics
Captive integration into SONATRACH-controlled pipeline infrastructure anchors both supply security and pricing power for Algerian upstream operators. European offtake contracts through the Trans-Mediterranean and Medgaz pipelines lock in volume commitments that insulate producers from spot market volatility while compressing margin flexibility for domestic power sector sales.
Pricing Analysis
Contract-based long-term offtake agreements with Italian and Spanish buyers dominate Algerian gas pricing, with ENI and TotalEnergies securing pipeline-linked supply through integrated partnerships. Price differentiation rests on sulfur content specifications and delivery reliability guarantees rather than spot market exposure. Cost compression in domestic power sector supply is intensifying because regulated tariffs compress upstream returns below export parity levels. Industrial buyers in Italy's Po Valley cluster exhibit the least price sensitivity due to baseload contract structures, while Algerian power utilities face the steepest budget constraints under subsidy frameworks.
Supply Chain Analysis
Freight costs for subsea production equipment and horizontal drilling assemblies from the United States, Norway, and China constitute a material share of frontier project economics in Algerian deepwater and shale provinces. Raw material dependencies center on specialized steel alloys for wellhead assemblies, high-pressure fracturing proppants, and subsea umbilical systems. Single-source vulnerability concentrates with a limited pool of desert drilling contractors capable of extended-reach completions in southern basins. Distribution runs through SONATRACH-operated processing facilities at Hassi R'Mel and Hassi Messaoud before pipeline injection or LNG liquefaction at Arzew and Skikda terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Algerian upstream operations hinges on technology transfer partnerships that reduce reliance on imported drilling services and unlock premium-tier recovery rates at mature Saharan fields.
For Market Incumbents: Deploy enhanced recovery mandates as a defensive lever to extend economic field life at Hassi Messaoud and Berkine Basin extensions. SONATRACH should accelerate waterflooding and gas injection partnerships to counter decline curves at supergiant fields. International operators must deepen local content compliance to secure license renewals under tightening workforce participation rules. Certification investment in carbon capture integration preserves European market access under emerging border adjustment mechanisms. For New Entrants and Emerging Players: Capture white-space opportunity in offshore Mediterranean blocks where subsea production system capabilities remain underrepresented among Asian NOC investors. The Illizi Basin's tight gas formations offer the most penetrable entry point for specialized fracturing contractors with horizontal drilling expertise. A go-to-market angle centered on technology licensing partnerships with SONATRACH satisfies regulatory transfer requirements while building operational track record. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap drilling service specialists because workforce localization mandates are fragmenting procurement across Algerian joint ventures. The five-to-ten year viability window favors operators with proven desert logistics infrastructure and established relationships with the national hydrocarbon regulator. Acquisition targets should demonstrate subsea or unconventional completion expertise. The signal to watch is licensing round frequency for shale and deepwater blocks as an inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Deployment | Waterflooding mandates at Hassi Messaoud extend productive life of mature Saharan supergiants under regulatory pressure. |
| Local Content Partnership | Joint ventures with Algerian service firms satisfy workforce rules while building permanent technical capacity in-country. |
| Carbon Capture Integration | Associated gas reinjection aligns with EU carbon border adjustments, preserving pipeline contract access for SONATRACH. |
| Offshore Licensing Round Participation | Deepwater Mediterranean blocks attract NOC capital with extended cost-recovery terms under frontier fiscal frameworks. |
| Technology Licensing Agreement | Horizontal fracturing expertise transfers from international operators to SONATRACH through structured drilling partnerships. |
Study Parameters
Multiple input streams — structured interviews with upstream project managers and reservoir engineers, regulatory filings with Algeria's national hydrocarbon agency, and operational data from SONATRACH partnership disclosures — were reconciled to construct supply and demand estimates. Primary fieldwork engaged drilling contractors, EPC specialists, and European offtake procurement officers across the Mediterranean supply corridor. Secondary validation drew from customs records for equipment imports, IEA natural gas market reports, and pipeline flow data from Italian and Spanish transmission system operators. Bottom-up field-level production estimates were triangulated against top-down basin-wide capacity assessments.
Data-stream reconciliation anchored volume projections across the analysis window, with segmentation dimensions spanning product type, recovery technology, end-user contract structure, and regional basin characteristics. CAGRs were derived from production decline curve analysis at mature fields and greenfield development timelines for unconventional and offshore provinces. Forecast inputs incorporated licensing round schedules, local content threshold revisions, and European pipeline contract renewal patterns.
Regulatory framework changes, partner dispute resolution outcomes, and European demand destruction events are the dominant revision risks to Algerian upstream projections. Forecasts reflect assumptions around SONATRACH's partnership continuity and shale exploration permitting velocity. A model refresh is warranted upon material change in EU carbon border adjustment implementation timelines or Algerian hydrocarbon law fiscal term revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market