
 Global Solar Water Heaters Market | 2026-2036
Global Solar Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Water Heaters Market Outlook
China is rewriting production economics for solar thermal equipment through concentrated vacuum tube manufacturing zones in Shandong and Zhejiang provinces. Himin Solar Energy Group leverages vertical integration from glass tubing to finished collector assembly, sustaining cost advantages across export markets. Rheem Manufacturing Company anchors North American distribution through residential contractor networks, while Ariston Group competes in European premium segments with heat pump-solar hybrid configurations.
Solar water heaters harness solar radiation through glazed flat plate or evacuated tube collectors to transfer thermal energy to potable water or hydronic heating loops, typically achieving 40-80% solar fraction depending on climate and load profile. Evacuated tube collectors dominate cold-climate installations due to superior heat retention and frost resistance, while flat plate collectors occupy cost-sensitive tropical markets where ambient temperatures reduce vacuum insulation advantages. Active pumped systems lead commercial and industrial end user segments where recirculation control maximizes collector efficiency, whereas passive thermosiphon configurations retain share in residential applications across Southern Europe and South Asia.
EPA Energy Star certification and EU Ecodesign regulations shape product efficiency thresholds and testing protocols for market access in North America and Europe. China's GB standards mandate collector performance labeling, while India's BIS certification and MNRE subsidy linkage control public procurement eligibility for domestic installations. Stakeholders must monitor building code electrification mandates that could displace standalone solar thermal in favor of PV-to-heat pump configurations.
Market Dynamics
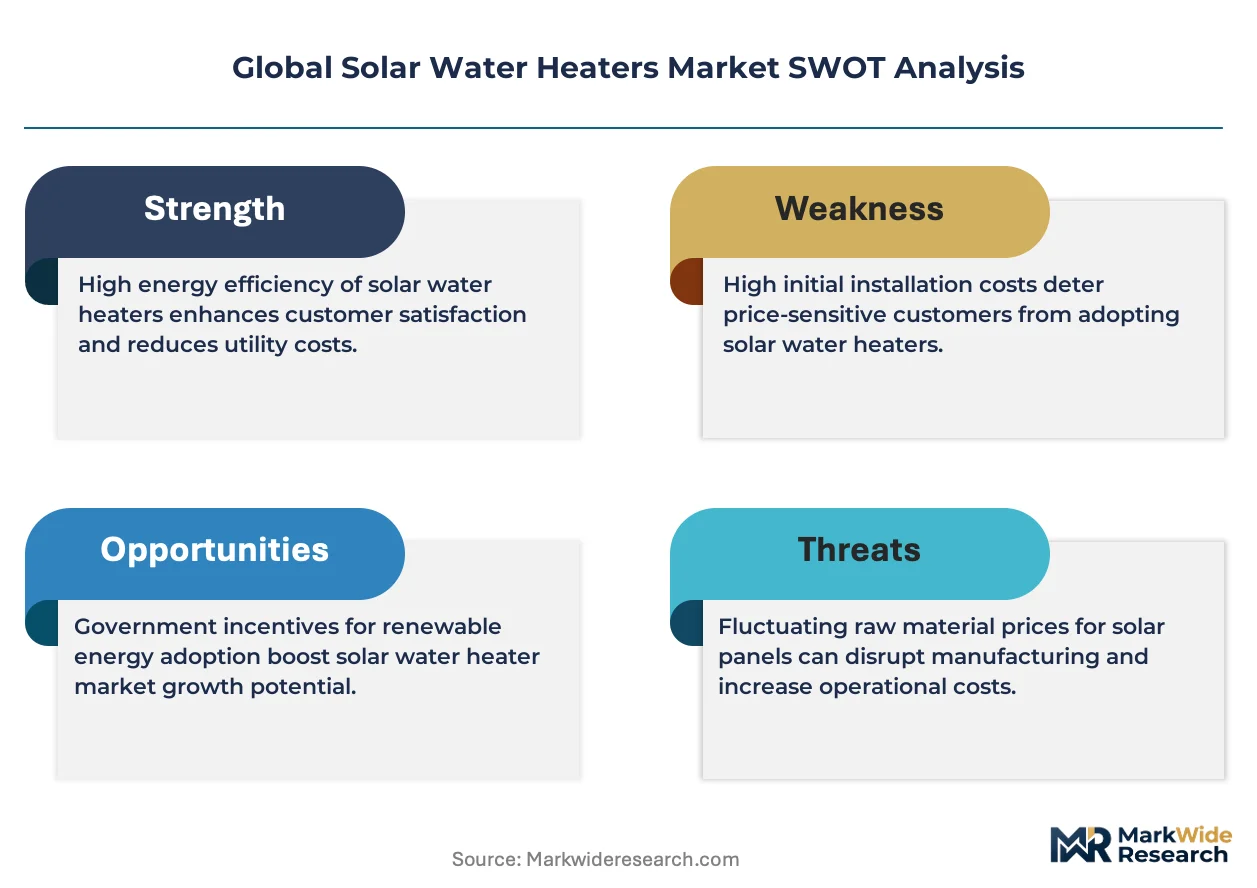
Building electrification mandates across Germany, California, and Australia are forcing solar thermal manufacturers to integrate with heat pump systems or face displacement from new construction specifications.
Growth Catalysts
- EU Green Deal building renovation mandates:Housing cooperatives in Germany must retrofit heating systems, creating pull for solar-thermal hybrids in multi-unit residential blocks.
- Evacuated tube collector frost resistance:Cold-climate installations in northern China and Mongolia favor vacuum insulation over flat plate alternatives for year-round operation.
- India's BIS-MNRE certification linkage:Subsidy eligibility requires performance labeling, concentrating demand around certified domestic manufacturers.
Market Restraints
- Copper and aluminum input volatility:Absorber plate and piping materials expose manufacturers to London Metal Exchange price swings that compress margin on fixed-price contracts.
- Shandong-Zhejiang supply concentration:China's vacuum tube manufacturing clusters create single-source risk for importers in Southeast Asia and Africa.
- PV-to-heat pump substitution:Falling photovoltaic module costs and inverter efficiency gains enable all-electric alternatives that bypass thermal collectors entirely.
Strategic Opportunities
- Industrial process heat underpenetration:Food processing and textile dyeing operations in Vietnam and Bangladesh remain unserved by solar thermal despite suitable load profiles.
- Heat pump-solar hybrid convergence:Combined systems qualify for enhanced subsidies under Germany's BEG program while delivering higher solar fraction than standalone units.
- Direct-to-installer digital channels:Bypassing traditional wholesaler networks captures margin and enables configuration tools that size systems for specific roof orientations.
Industry Challenges
- Skilled installer scarcity:Plumbing and roofing coordination requires certified technicians that training pipelines in Italy and Spain fail to replenish.
- EPA Energy Star retesting timelines:Revised thermal performance protocols delay market access for redesigned collector geometries.
- Legacy hydronic integration complexity:Retrofit installations must accommodate existing boiler controls and circulation pumps without full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Water Heaters Market |
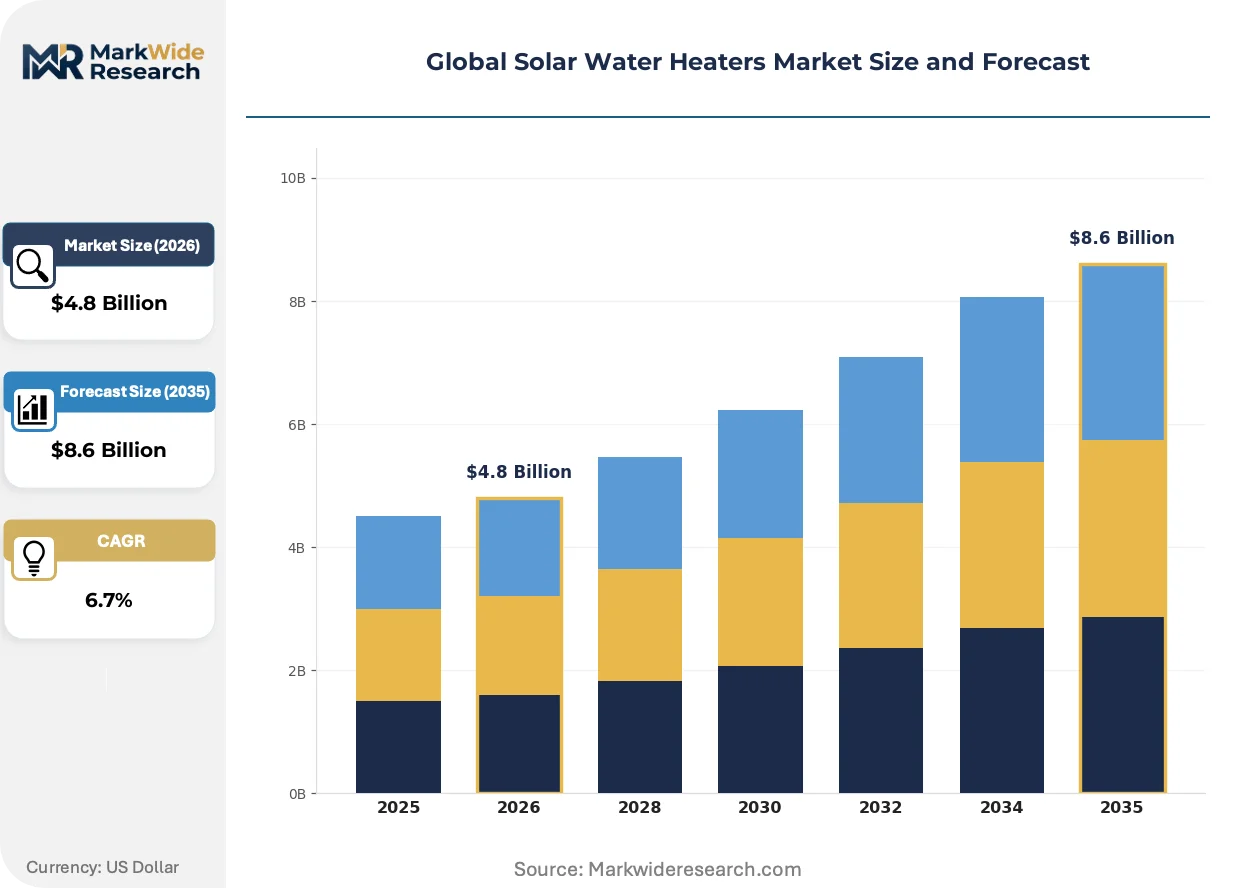
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate Collectors, Evacuated Tube Collectors, Integrated Systems, Batch Heaters End User: Residential, Commercial, Industrial, Agricultural Installation Type: Roof-mounted, Ground-mounted, Building-integrated, Portable Technology: Active Systems, Passive Systems, Hybrid Systems, Thermodynamic Systems |
| Companies Covered | Ariston Group, Stiebel Eltron Inc., Robert Bosch GmbH, Tata Power Solar Systems Limited, A. O. Smith, Hubbell Incorporated, Rheem Manufacturing Company, Himin Solar Energy Group, Viessmann Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Water Heaters Market Strategic Shifts
Active system controls and polymer heat exchangers are compressing the cost-performance gap between evacuated tubes and flat plates while regulatory pressure accelerates hybrid configurations.
Polymer-based absorber coatings are rendering obsolete traditional selective black chrome surfaces in cost-sensitive tropical markets. Residential developers in Brazil and Mexico specify these lighter collectors for rooftop installations where structural load limits apply. The shift is rendering obsolete the aluminum-copper composite absorber supply chains that dominated flat plate manufacturing for four decades.
California's Title 24 building code now mandates solar-ready infrastructure in new residential construction, effectively pre-wiring homes for thermal or photovoltaic systems. The regulation forces developers to allocate roof space and plumbing chase capacity regardless of immediate equipment selection. Multi-family housing projects in Los Angeles and San Diego counties are responding by specifying pre-installed solar loop infrastructure that reduces future retrofit costs.
Aggregated procurement through housing cooperatives and property management platforms is consolidating what were fragmented residential purchases. Installer networks in the Netherlands and Denmark now bid on hundred-unit maintenance contracts rather than individual household sales. This concentration is most visible in social housing portfolios where municipalities bundle renovation specifications across entire districts.
Global Solar Water Heaters Market Segmentation
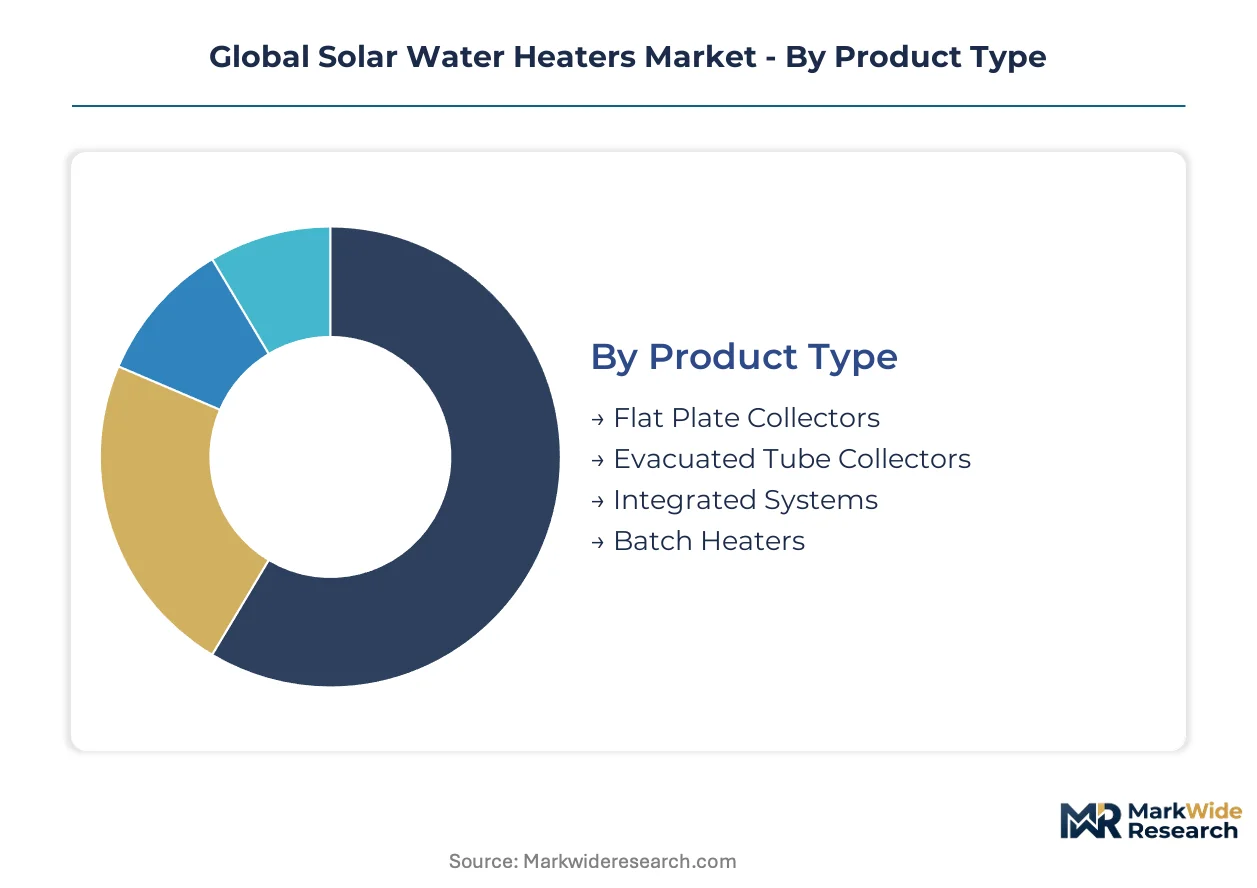
Segmentation in solar water heaters reveals distinct procurement cycles and margin structures across collector technologies and installation contexts. Equipment replacement timelines vary from 15-20 years for passive residential units to 8-12 years for active commercial systems with pumped circulation.
Product Type:
Replacement cycles stretch longest for batch heaters and shortest for integrated systems requiring electronic control maintenance, creating divergent aftermarket revenue profiles.
- Flat Plate Collectors:Aluminum-copper composite absorber plates with tempered glass glazing dominate tropical installations where ambient temperatures reduce insulation requirements. Brazilian residential developers specify these for favela upgrading programs where structural load limits apply.
- Evacuated Tube Collectors:Borosilicate glass vacuum tubes with selective absorption coatings achieve superior heat retention in sub-zero conditions. Northern Chinese district heating retrofits and Mongolian ger district upgrades drive concentrated demand for frost-resistant configurations.
- Integrated Systems:Factory-sealed pump and control units reduce field commissioning errors. German housing cooperatives favor these for multi-unit blocks under BEG subsidy programs.
- Batch Heaters:Passive thermosiphon tanks with integrated absorber surfaces serve off-grid rural markets. Indian MNRE-subsidized installations in Rajasthan and Gujarat deploy these for agricultural labor housing.
Evacuated tube collectors anchor the volume base while integrated systems gain share at the steepest rate.
End User:
Cost tiers separate specification authority from payment responsibility across customer categories.
- Residential:Single-family and multi-unit dwellings with decentralized decision-making. California Title 24 mandates solar-ready infrastructure in new construction, pre-wiring homes for future thermal or photovoltaic connection.
- Commercial:Hotels, hospitals, and office buildings with centralized procurement through facilities managers. Vietnam's hospitality sector in Da Nang and Phu Quoc deploys these for laundry and kitchen hot water loads.
- Industrial:Process heat applications in food processing and textile dyeing. Bangladesh's garment washing facilities in Gazipur remain underpenetrated despite suitable 60-80°C temperature requirements.
- Agricultural:Greenhouse heating and livestock water warming. Dutch horticulture clusters in Westland integrate these with geothermal backup for year-round tomato production.
Residential installations anchor the volume base while industrial process heat climbs the fastest as fuel price volatility accelerates payback calculations.
Installation Type:
Geographic deployment constraints and structural engineering requirements differentiate specification pathways.
- Roof-mounted:Tilted rack assemblies on pitched or flat residential and commercial structures. Los Angeles County multi-family projects specify pre-installed solar loop infrastructure to reduce future retrofit costs.
- Ground-mounted:Seasonally adjustable arrays for agricultural and industrial process heat. Australian dairy operations in Victoria deploy these for bulk tank washing with frost protection.
- Building-integrated:Façade-mounted collectors serving dual weatherproofing and thermal functions. Copenhagen social housing renovations incorporate these for district heating feed-in.
- Portable:Mobile units for construction camps and disaster relief. UNHCR procurement for Syrian refugee settlements in Jordan specifies these for temporary health clinic deployment.
Roof-mounted configurations anchor the volume base while building-integrated designs expand most quickly as urban density limits available surface area.
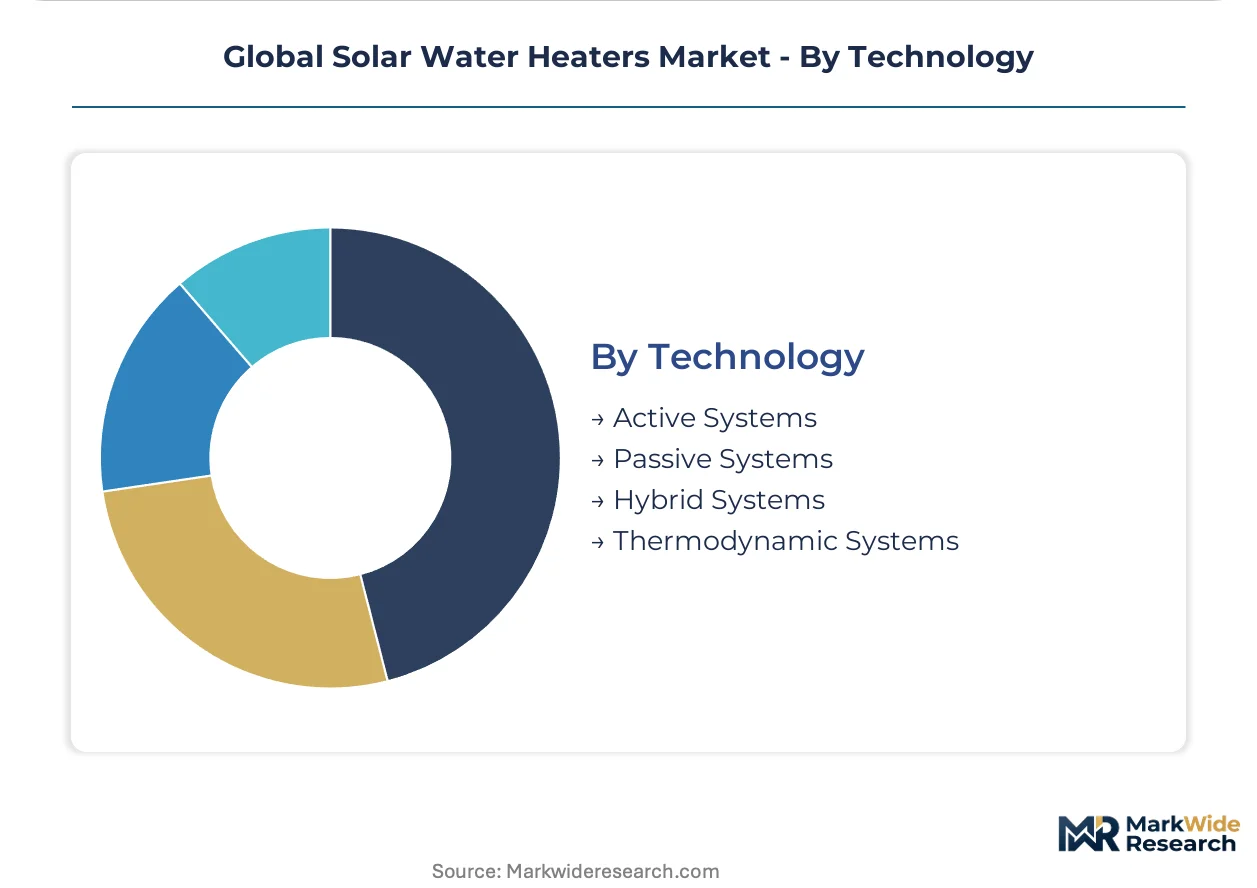
Technology:
Application complexity and control precision requirements stratify technology selection across end-use contexts.
- Active Systems:Pumped circulation with differential temperature controllers maximizing collector efficiency. German commercial installations under EU Ecodesign regulations favor these for guaranteed performance metrics.
- Passive Systems:Thermosiphon circulation without electrical components. Southern European and South Asian residential markets retain share where grid reliability concerns apply.
- Hybrid Systems:Solar-thermal integration with heat pump boosters. Denmark's aggregated housing cooperative procurement concentrates demand for these under enhanced BEG subsidy tiers.
- Thermodynamic Systems:Refrigerant-based heat extraction from ambient air with solar augmentation. Spain's installer networks face skilled technician scarcity for these complex refrigeration circuits.
Active systems anchor the volume base while hybrid configurations show the steepest expansion trajectory as electrification mandates force thermal-electric convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys evacuated tube collectors for district heating retrofits while Germany mandates heat pump-solar hybrids under building codes; India and Brazil favor passive thermosiphon units for rural electrification gaps. These consumption-mix differentials reflect climate conditions, subsidy structures, and electrification maturity across markets.
China
Shandong and Zhejiang provinces host concentrated vacuum tube manufacturing clusters serving northern district heating retrofits. GB standards mandate collector performance labeling for subsidy eligibility. Himin Solar Energy Group anchors production in Dezhou, Shandong, supplying frost-resistant configurations to Inner Mongolian ger district upgrades.
Germany
Housing cooperatives in Berlin and Hamburg scale multi-unit installations under EU Green Deal renovation mandates. The BEG program offers enhanced subsidy tiers for heat pump-solar hybrid configurations. North Rhine-Westphalia's industrial cities concentrate demand for commercial process heat integration with existing hydronic infrastructure.
India
Rajasthan and Gujarat deploy batch heaters for agricultural labor housing under MNRE-subsidized rural electrification programs. BIS certification linkage restricts public procurement to domestic manufacturers. Karnataka's Bengaluru-Tumkur corridor hosts emerging absorber coating fabrication for cost-sensitive tropical specifications.
Brazil
Favela upgrading programs in Rio de Janeiro and São Paulo specify polymer-coated flat plate collectors where structural load limits apply. National social housing mandates require solar-ready infrastructure in new construction. Minas Gerais mining towns drive commercial demand for hotel and hospital hot water systems.
Australia
Victorian dairy operations deploy ground-mounted arrays for bulk tank washing with frost protection integration. Victoria and New South Wales building codes accelerate heat pump displacement of standalone thermal systems. Perth's residential construction sector pre-installs solar loop infrastructure under statewide sustainability mandates.
Global Solar Water Heaters Market Competitive Environment
Capability concentration sits with vertically integrated glass-to-collector manufacturers; scale advantage sits with diversified heating equipment conglomerates. The market structures around three tiers: Chinese vacuum tube specialists with captive borosilicate supply, European premium-system integrators with heat pump convergence, and North American distribution-heavy brands with contractor network lock-in. Dominant competitive moves include backward integration into absorber materials and strategic partnerships with heat pump manufacturers to secure electrification-mandate compliance.
Within the vertically integrated tier, Himin Solar Energy Group exemplifies upstream control from glass tubing through finished collector assembly. Among diversified heating conglomerates, Robert Bosch GmbH and Viessmann Manufacturing occupy positions spanning residential boilers through solar-thermal hybrids. Rheem Manufacturing Company anchors North American distribution density through residential contractor network relationships.
| Leading Market Players |
|---|
| Ariston Group |
| Stiebel Eltron Inc. |
| Robert Bosch GmbH |
| Tata Power Solar Systems Limited |
| A. O. Smith |
| Hubbell Incorporated |
| Rheem Manufacturing Company |
| Himin Solar Energy Group |
| Viessmann Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Shandong province's concentrated vacuum tube manufacturing capacity in Dezhou and Jinan directly shapes downstream pricing power across export markets, with captive borosilicate glass supply insulating Chinese producers from London Metal Exchange volatility that compresses margins for flat plate manufacturers elsewhere.
Pricing Analysis
Chinese-manufactured evacuated tubes command a price spread against European-assembled flat plates, with three-tier pricing structure across premium, standard, and economy levels driven by certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because polymer absorber coatings displace aluminum-copper composites in tropical specifications. Commercial installers exhibit lowest price sensitivity due to BEG subsidy absorption, while rural residential buyers in India and Brazil face acute cost constraints.
Supply Chain Analysis
Copper and aluminum feedstock from Chile and Australia feeds absorber plate fabrication, while borosilicate glass tubing draws from captive furnaces in Shandong and Zhejiang provinces. Single-source vulnerability concentrates in China's vacuum tube clusters, exposing Southeast Asian and African importers to supply disruption. Distribution runs through residential contractor networks in North America and housing cooperative procurement platforms in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global solar water heaters sit in early-cycle expansion as electrification mandates in Germany, California, and Australia force thermal-electric hybrid adoption that expands addressable system value beyond standalone units.
For Market Incumbents: Entrench position through backward integration into absorber coating materials and heat pump manufacturing partnerships that secure compliance with building code electrification mandates. Rheem Manufacturing Company's contractor network density offers a template for channel control that resists PV-to-heat pump substitution threats.
For New Entrants and Emerging Players: Build out direct-to-installer digital channels that bypass traditional wholesaler markups, targeting industrial process heat in Vietnam's food processing sector and Bangladesh's textile dyeing operations where solar thermal remains underpenetrated despite suitable temperature requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vertically integrated glass-to-collector manufacturers with heat pump convergence capabilities will capture disproportionate share as subsidy programs favor hybrid configurations. Watch for BEG program tier adjustments as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Absorber Materials | Captive supply of selective coatings reduces exposure to London Metal Exchange copper volatility. |
| Heat Pump-Solar Hybrid Development | Combined systems qualify for enhanced BEG subsidy tiers in Germany's multi-unit residential segment. |
| Direct-to-Installer Digital Channel | Bypassing wholesaler networks captures margin and enables roof-orientation configuration tools. |
| Industrial Process Heat Expansion | Food processing and textile operations in Vietnam and Bangladesh remain unserved despite suitable load profiles. |
| Polymer Absorber Coating Transition | Lighter collectors penetrate structural-load-constrained markets like Brazilian favela upgrading programs. |
Study Parameters
Cross-validation between installer network interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork engaged solar thermal system designers, housing cooperative procurement officers, EPC contractors, and MNRE subsidy administrators across India, Germany, and China. Secondary sources include EU Ecodesign directive documentation, BIS certification registries, EPA Energy Star test protocols, and customs trade data for borosilicate glass and copper absorber plate flows. Bottom-up collector shipment tallies triangulate against top-down building renovation mandate targets.
Calibration against historical subsidy program uptake curves and equipment replacement cycles shapes the analytical framework across the analysis window. Segmentation dimensions span collector technology, installation context, end-use sector, and regional regulatory cluster. CAGRs derive from slope-consistent extrapolation of mandate-driven procurement volumes and electrification policy trajectory. Forecast inputs incorporate heat pump cost curves and PV module price elasticity effects on thermal collector substitution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese vacuum tube specialists or sudden BEG program suspension would shift outcomes. Material shifts in copper and aluminum input costs, building code electrification acceleration, or heat pump efficiency breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
New Zealand Solar Energy Market