
 Egypt Solar Photovoltaic (PV) Market | 2026-2036
Egypt Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Solar Photovoltaic (PV) Market Foresight
IEC 61215 certification for crystalline silicon module durability is unwinding the competitive field, forcing smaller assemblers toward thin-film partnerships or exit. ACWA Power leverages its Saudi development pedigree to anchor gigawatt-scale pipeline access in Upper Egypt. KarmSolar differentiates through off-grid commercial specialization, serving industrial zones beyond national grid reach. ELSEWEDY Electric controls domestic manufacturing scale, producing cells and modules at its 10th of Ramadan complex.
Egypt Solar Photovoltaic (PV) refers to semiconductor-based energy conversion systems that transform sunlight into direct-current electricity through p-n junction excitation, with monocrystalline modules achieving conversion efficiencies exceeding 21% in field conditions. These systems serve grid-connected generation, distributed commercial supply, and isolated rural electrification across Egypt's high-insolation territories. Crystalline silicon products dominate installed capacity due to proven bankability and local assembly lines, while bifacial modules gain traction in utility-scale desert applications where albedo reflection boosts yield. Off-grid systems represent the fastest-growing application segment as agricultural pumping and remote industrial loads escape diesel dependency. Ground-mounted installations occupy the vast majority of megawatt-scale deployment, constrained by rooftop structural limitations in Egypt's informal urban fabric.
Egypt's New and Renewable Energy Authority governs project licensing and power purchase agreements, while the Egyptian Electricity Regulatory Agency sets feed-in tariff ceilings that directly determine developer returns. The country's building codes under the Housing and Building National Research Center increasingly mandate solar-ready design for commercial structures, expanding addressable rooftop demand. Stakeholders must monitor forthcoming carbon credit framework negotiations and their interaction with existing sovereign guarantee structures.
Market Dynamics
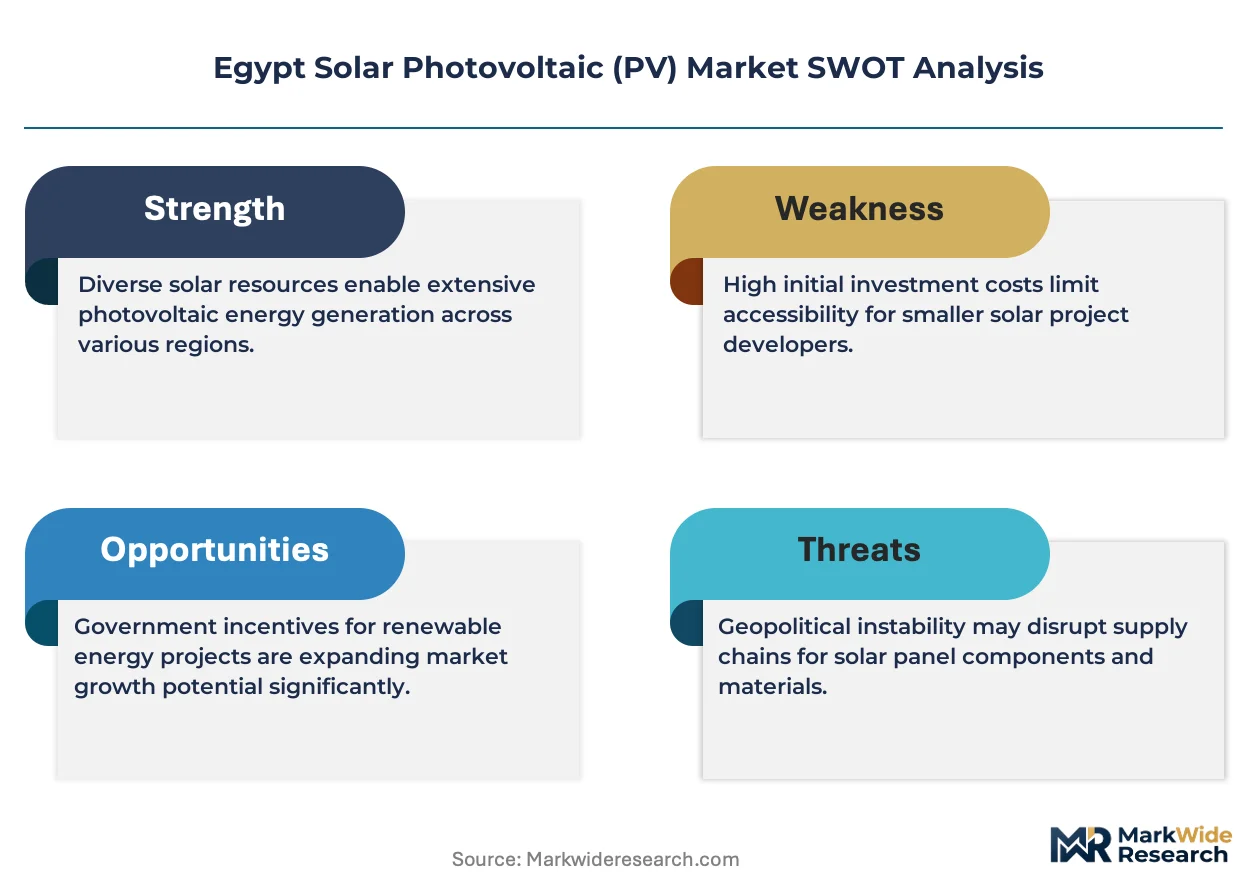
Feed-in tariff reforms by the Egyptian Electricity Regulatory Agency are compressing developer margins and forcing procurement model reinvention across the Nile Valley corridor. Utility-scale developers now optimize for sovereign guarantee structures rather than tariff ceilings alone.
Growth Catalysts
- Net-metering expansion:Commercial and industrial consumers in Cairo and Alexandria deploy rooftop systems to offset grid purchases, bypassing utility-scale queue delays.
- Benban cluster infrastructure:Dedicated 220 kV substations and land parcelling by the New and Renewable Energy Authority attract concentrated developer capital to Upper Egypt.
- Agricultural diesel displacement:Off-grid solar pumping systems eliminate fuel logistics burdens for Nile Delta farming cooperatives facing subsidy removal.
Market Restraints
- Import dependency for polysilicon:Egyptian cell assemblers source 100% of feedstock from Chinese and German suppliers, exposing margins to freight rate volatility and currency mismatch.
- Grid absorption limits:The Egyptian Electricity Transmission Company restricts new connection permits in Western Desert zones where evacuation infrastructure remains unbuilt.
- Land tenure complexity:Desert land allocation through military and agricultural authority overlaps creates permitting delays for projects outside the Benban framework.
Strategic Opportunities
- Sinai Peninsula electrification:Remote military and tourism loads in North and South Sinai governorates lack grid extension, creating captive demand for hybrid solar-storage microgrids.
- Green hydrogen offtake anchoring:The Suez Canal Economic Zone positions electrolyzer projects as baseload demand for gigawatt-scale solar parks under long-term power purchase agreements.
- Building-integrated photovoltaics:Revised commercial construction codes by the Housing and Building National Research Center mandate solar-ready design for new administrative and retail structures.
Industry Challenges
- Electrical engineering talent scarcity:Grid integration specialists and inverter commissioning engineers command premium wages, constraining project execution velocity for mid-scale developers.
- IEC 61215 certification timelines:Local module assemblers face 8-14 month testing queues at international laboratories, delaying bankability for domestic manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Solar Photovoltaic (PV) Market |
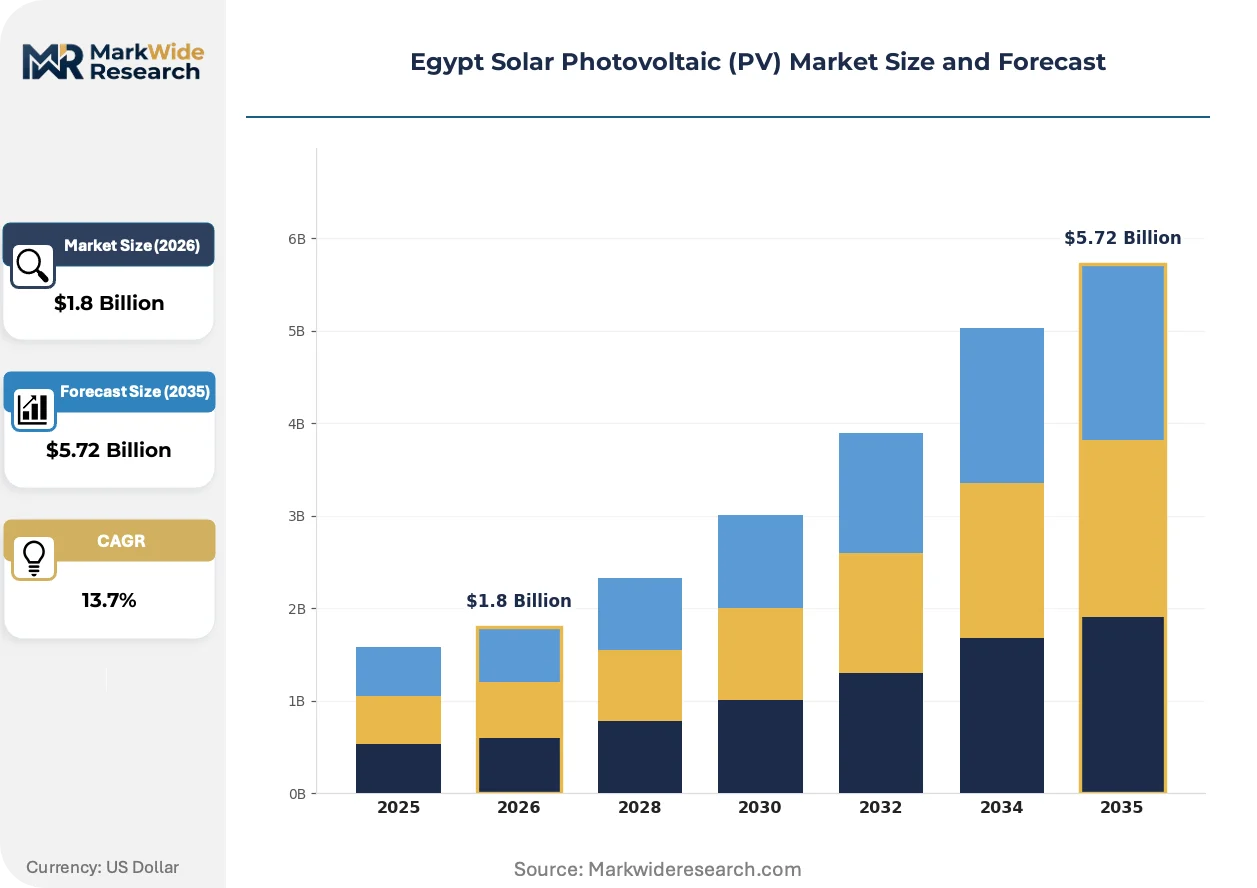
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Silicon, Thin-Film, Bifacial, Concentrated PV Application: Utility-Scale, Commercial, Residential, Off-Grid Systems Installation Type: Ground-Mounted, Rooftop, Building-Integrated, Vehicle-Mounted Technology: Monocrystalline, Polycrystalline, CdTe, CIGS |
| Companies Covered | ACWA Power, KarmSolar, Scatec ASA, EliTe Solar, ELSEWEDY Electric, Egyptian Electricity Holding Company, Infinity Power, Voltalia SA, Masdar Clean Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Solar Photovoltaic (PV) Market Shifts & Advancements
Bifacial module architecture and string inverter topology are compressing balance-of-system costs across Egypt's desert utility sites. Technology selection now determines project returns more than tariff negotiation.
Bifacial monocrystalline modules are miniaturizing tracker footprints while boosting specific yield through rear-side albedo capture. ACWA Power and Scatec deploy these units across Benban phases four through six, reducing steel tonnage per megawatt by 12-15%. The technology is miniaturizing civil works scope and accelerating construction schedules for 500 MW-plus single-phase developments.
The Egyptian Electricity Regulatory Agency's 2024 net-metering decree eliminates capacity caps for commercial self-consumption systems below 25 MW. Industrial zones in 10th of Ramadan and Sadat City accelerate behind-the-meter deployment to hedge against grid tariff indexation. Food processing and textile manufacturers constitute the fastest-responding buyer segment, with aggregate installed commercial capacity doubling within eighteen months of implementation.
Aggregator-led portfolio procurement is displacing bilateral developer-utility negotiations for distributed commercial assets. KarmSolar and Solarize Egypt bundle rooftop installations across multiple industrial clients, selling aggregated output through standardized power purchase agreements to offtakers seeking renewable energy certificates. This model concentrates most rapidly in Greater Cairo's 6th of October industrial corridor where land scarcity prevents ground-mounted alternatives.
Egypt Solar Photovoltaic (PV) Market Segmentation
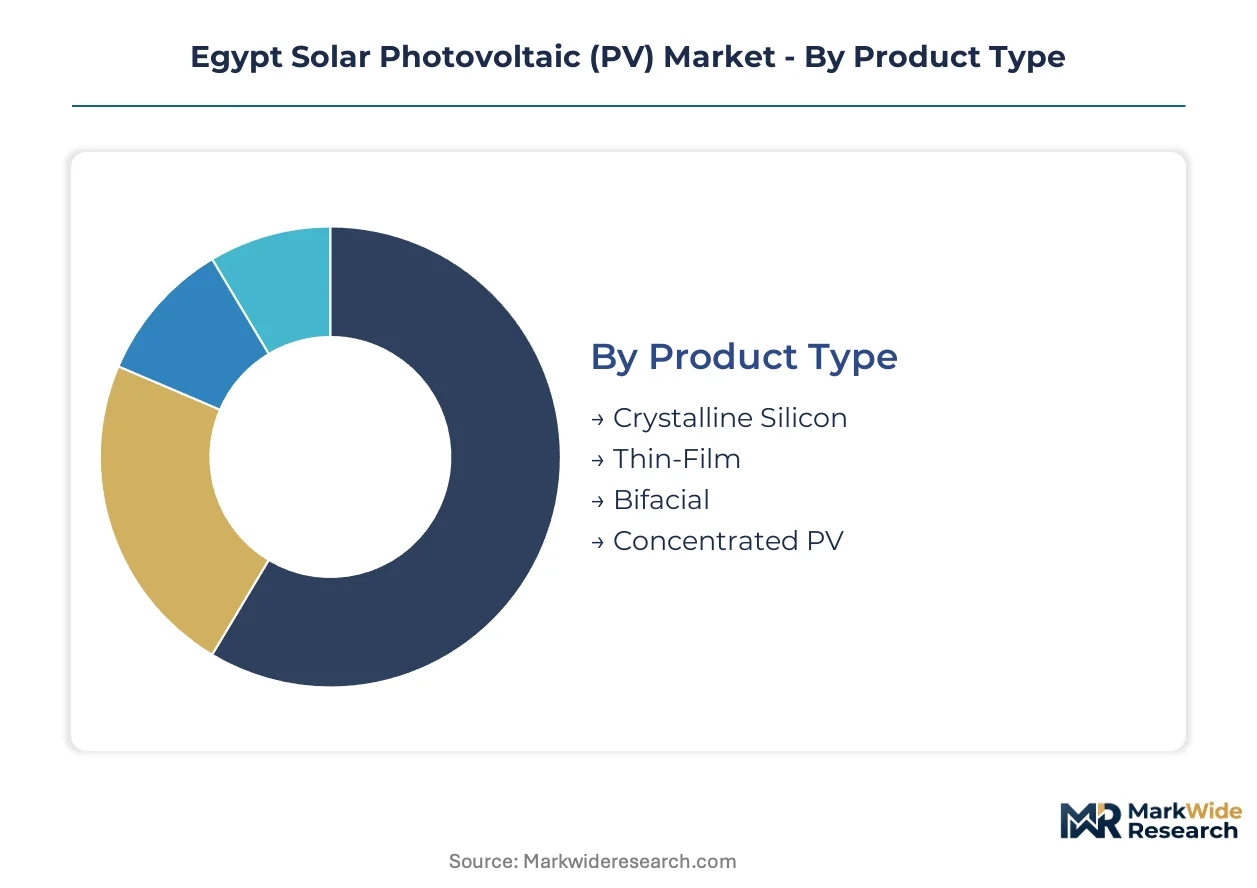
Module technology selection and installation topology determine project economics across Egypt's high-insolation territories. Procurement patterns diverge sharply between utility-scale desert parks and distributed commercial rooftops, creating distinct competitive arenas with separate margin structures.
Product Type:
Crystalline silicon modules face intensifying substitution pressure from bifacial architectures in utility-scale procurement, while thin-film alternatives struggle to displace bankable crystalline options in commercial segments.
- Crystalline Silicon:P-type and n-type monocrystalline cells dominate Egyptian assembly lines at ELSEWEDY Electric's 10th of Ramadan complex. Benban Solar Park developers specify these modules for proven degradation curves and IEC 61215 certification accessibility.
- Thin-Film:Cadmium telluride and amorphous silicon technologies occupy niche applications where weight constraints or low-light performance outweigh efficiency premiums. Agricultural pumping stations in the Western Desert deploy these units for tolerance to partial shading and soiling.
- Bifacial:Dual-glass monocrystalline modules capture rear-side albedo reflection from desert sand surfaces, boosting specific yield by 8-12% in Aswan governorate installations. ACWA Power and Scatec specify these for tracker-mounted phases at Benban.
- Concentrated PV:Multi-junction cell systems with dual-axis tracking concentrate direct normal irradiance for ultra-high conversion efficiencies exceeding 40%. These systems concentrate in demonstration projects near Hurghada where DNI levels exceed 2800 kWh/m² annually.
Crystalline silicon anchors the volume base while bifacial gains share at the steepest rate.
Application:
Cost tier segmentation separates sovereign-guaranteed utility procurements from behind-the-meter commercial investments with divergent return thresholds.
- Utility-Scale:Grid-connected parks exceeding 50 MW capacity deliver bulk power through Egyptian Electricity Transmission Company evacuation infrastructure. Benban cluster phases represent the dominant deployment mode, with long-term power purchase agreements indexed to sovereign guarantee structures.
- Commercial:Industrial and administrative facilities in Cairo, Alexandria, and the Suez Canal zone deploy rooftop and carport systems to offset grid purchases. Net-metering expansion since 2024 eliminates prior capacity caps for self-consumption systems below 25 MW.
- Residential:Single-family and multi-unit dwellings in informal urban fabric face structural constraints from rooftop load-bearing limitations. Deployment concentrates in gated compounds and new administrative city developments with engineered structural capacity.
- Off-Grid Systems:Standalone solar-storage configurations serve agricultural pumping, remote tourism facilities, and Sinai military outposts beyond national grid reach. KarmSolar specializes in this segment, eliminating diesel logistics burdens for Nile Delta farming cooperatives.
Utility-scale installations anchor the volume base while off-grid systems climb the fastest as subsidy removal accelerates diesel displacement.
Installation Type:
Application context dictates structural configuration, with ground-mounted systems dominating megawatt-scale deployment and building-integrated alternatives constrained by Egypt's construction code evolution.
- Ground-Mounted:Steel pile or concrete foundation structures support tracker and fixed-tilt arrays across desert territories. Benban Solar Park phases four through six deploy these configurations exclusively, with single-axis trackers optimizing for seasonal sun angles.
- Rooftop:Ballasted and penetrating mounting systems attach to industrial warehouse and commercial administrative structures. Greater Cairo's 6th of October industrial corridor concentrates aggregate deployment as land scarcity prevents ground-mounted alternatives.
- Building-Integrated:Photovoltaic elements substitute for conventional cladding, glazing, or roofing materials in new construction. Housing and Building National Research Center codes increasingly mandate solar-ready design for commercial structures, expanding addressable demand.
- Vehicle-Mounted:Portable solar arrays deploy on military transport, desert expedition vehicles, and mobile telecommunications units. Sinai Peninsula security operations and remote tourism logistics drive limited procurement volumes.
Ground-mounted configurations anchor the volume base while building-integrated installations expand most quickly on regulatory mandate momentum.
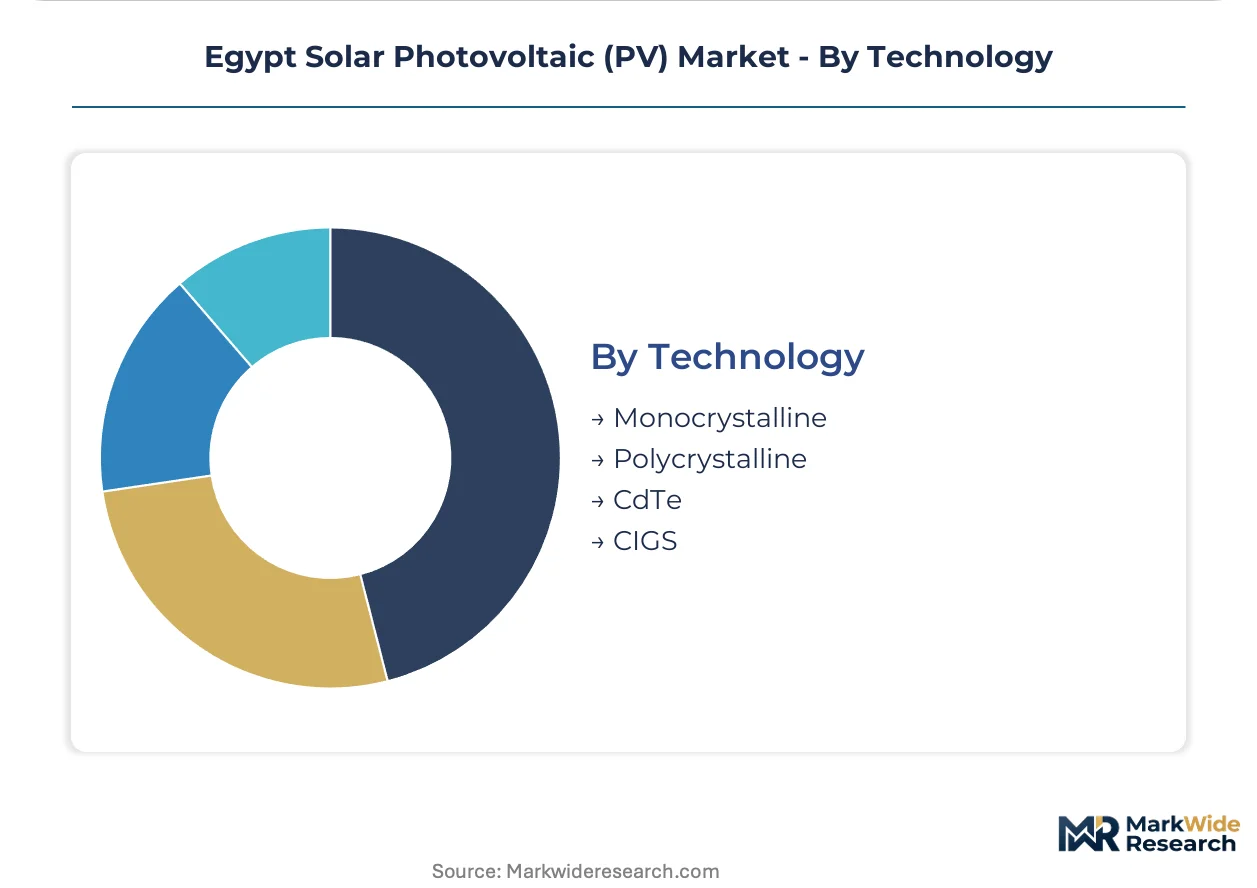
Technology:
Cell architecture segmentation tracks manufacturing process maturity and efficiency differentiation, with monocrystalline formats commanding premium positioning against polycrystalline cost alternatives.
- Monocrystalline:Single-crystal silicon ingots yield higher conversion efficiencies exceeding 21% in field conditions. Passivated emitter and rear contact variants dominate premium utility-scale procurement at Benban.
- Polycrystalline:Multi-crystal silicon casting reduces manufacturing energy intensity and capital cost per watt-peak. These modules concentrate in price-sensitive distributed commercial segments where rooftop area constraints are less severe.
- CdTe:Cadmium telluride thin-film deposition on glass substrates delivers temperature coefficient advantages in desert climates. First Solar technology underpins limited Egyptian project deployment through international developer partnerships.
- CIGS:Copper indium gallium selenide flexible substrates enable lightweight applications on weight-constrained structures. Niche deployment concentrates on heritage building retrofits and mobile installations where rigid glass-glass modules prove impractical.
Monocrystalline technology anchors the volume base while CIGS gains share fastest in specialized lightweight applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Egyptian Electricity Regulatory Agency's feed-in tariff reforms and net-metering expansion are redistributing investment flows across the Nile Valley corridor, with Upper Egypt capturing concentrated utility-scale deployment while the Delta and coastal zones accelerate commercial rooftop adoption.
Upper Egypt
Benban Solar Park phases four through six anchor gigawatt-scale procurement through dedicated 220 kV substations and sovereign guarantee structures. The New and Renewable Energy Authority's land parcelling program attracts ACWA Power and Scatec deployments. Aswan governorate's albedo conditions favor bifacial tracker configurations.
Greater Cairo
Industrial zones in 6th of October and 10th of Ramadan drive behind-the-meter commercial deployment to hedge grid tariff indexation. The Housing and Building National Research Center's solar-ready building codes expand addressable rooftop demand. Food processing and textile manufacturers constitute the fastest-responding buyer segment.
Alexandria and the North Coast
Port infrastructure and Mediterranean shipping lanes position the zone for module import logistics and export-oriented manufacturing. Net-metering elimination of 25 MW capacity caps accelerates warehouse and logistics facility deployment. Borg El Arab industrial city concentrates aggregate commercial installation.
Sinai Peninsula
Remote military and tourism loads in North and South Sinai governorates lack grid extension, creating captive demand for hybrid solar-storage microgrids. Security operations and coastal resort electrification drive limited but high-margin procurement. KarmSolar specializes in diesel displacement for isolated loads.
Nile Delta
Agricultural pumping cooperatives face diesel subsidy removal, accelerating off-grid solar adoption for irrigation. The Egyptian Electricity Holding Company restricts new connection permits where evacuation infrastructure remains unbuilt. ELSEWEDY Electric's domestic manufacturing complex supplies module assembly for distributed applications.
Egypt Solar Photovoltaic (PV) Market Competitive Landscape
Listed leaders compete with private specialists across development scale and technology integration depth. The vendor base segments into utility-scale park developers, off-grid commercial specialists, and domestic manufacturing incumbents. Three archetypes dominate: Saudi-backed gigawatt developers, Egyptian-founded distributed energy specialists, and integrated industrial conglomerates with captive cell assembly. Competitive moves concentrate on sovereign guarantee access, manufacturing certification timelines, and aggregator-led portfolio bundling.
Within the utility-scale developer tier, ACWA Power and Scatec ASA represent Saudi and Norwegian development pedigrees anchoring Benban pipeline access. ELSEWEDY Electric exemplifies the integrated industrial archetype through its 10th of Ramadan manufacturing complex. KarmSolar occupies the off-grid specialist position, serving agricultural and remote industrial loads beyond national grid reach.
| Leading Market Players |
|---|
| ACWA Power |
| KarmSolar |
| Scatec ASA |
| EliTe Solar |
| ELSEWEDY Electric |
| Egyptian Electricity Holding Company |
| Infinity Power |
| Voltalia SA |
| Masdar Clean Energy |
| Others |
Supply & Pricing Matrix
Eight-to-fourteen-month IEC 61215 certification queues at international laboratories compress domestic assemblers' pricing power while amplifying cost premiums for bankable module tiers. This lead-time bottleneck concentrates margin capture among certified incumbents and forces uncertified players toward thin-film partnerships or market exit.
Pricing Analysis
Certification level creates the primary spread between bankable and non-bankable module tiers in Egyptian procurement. Three-tier pricing structure across premium IEC-certified, standard domestic-assembled, and economy import-direct segments dominates project economics. Pricing pressure stems from feed-in tariff ceiling compression by the Egyptian Electricity Regulatory Agency, which squeezes developer margins and forces module cost absorption. Utility-scale developers with sovereign guarantee access exhibit least price sensitivity, while distributed commercial installers in Greater Cairo's industrial zones negotiate hardest on per-watt-peak terms.
Supply Chain Analysis
Strategic stockpile preferences dominate polysilicon procurement as Egyptian cell assemblers confront 100% import dependency on Chinese and German feedstock suppliers. Raw material flows draw from polysilicon ingots, silver paste metallization, and ethylene-vinyl acetate encapsulant streams. Single-source vulnerability concentrates in Chinese polysilicon supply, exposing margins to freight rate volatility and EGP-USD currency mismatch. Distribution runs through Alexandria port infrastructure and overland trucking networks to the 10th of Ramadan manufacturing complex and Benban Solar Park assembly yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operations and maintenance service contracts are expanding faster than module hardware sales as utility-scale parks mature and performance guarantees lengthen. This recurring-revenue layer commands superior margin stability compared to episodic EPC project wins.
For Market Incumbents: Compound sovereign guarantee access through accelerated pipeline origination in Upper Egypt before land parcelling saturates. Deepen backward integration into polysilicon procurement via long-term offtake agreements with Chinese suppliers to defend against currency mismatch. IEC 61215 certification investment represents the priority defensive lever as uncertified competitors face forced exit. For New Entrants and Emerging Players: Differentiate on off-grid commercial specialization serving agricultural pumping cooperatives and Sinai military outposts beyond national grid reach. Target the Nile Delta irrigation segment where diesel subsidy removal accelerates solar displacement fastest. Pursue aggregator-led portfolio bundling across multiple industrial rooftops to bypass bilateral utility negotiation complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across distributed commercial segments as standardized net-metering systems reduce project-specific engineering overhead. Acquisition targets with captive installation crews and O&M service platforms offer superior five-to-ten-year viability versus pure development shops. Watch for feed-in tariff renegotiation signals as sovereign guarantee restructuring would compress utility-scale returns and redirect capital toward behind-the-meter deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Sovereign guarantee terms determine developer returns more than tariff ceilings alone. |
| Backward Integration into Polysilicon Procurement | Long-term Chinese supply contracts hedge Egyptian assemblers against currency volatility. |
| Net-Metering Portfolio Aggregation | Bundled rooftop installations bypass utility-scale queue delays for commercial offtakers. |
| IEC Certification Fast-Tracking | Accelerated laboratory access unlocks bankability for domestic manufacturing lines. |
| Hybrid Solar-Storage Microgrid Deployment | Sinai Peninsula electrification creates captive demand beyond grid extension economics. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation. Stakeholder interviews combined with customs records, New and Renewable Energy Authority licensing databases, Egyptian Electricity Regulatory Agency tariff filings, and IEA renewable energy reports. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation anchored volume and value estimates.
Variance decomposition across technology selection, installation topology, and regulatory framework segments structured the analytical framework over the projection horizon. Modeled dimensions span module type, application tier, installation configuration, and cell architecture. CAGRs derived from segment-level growth trajectory synthesis and macroeconomic elasticity assumptions. Forecast inputs incorporated sovereign guarantee availability and net-metering decree implementation velocity.
The analysis sits within stated boundaries; outcomes outside sustained feed-in tariff enforcement or currency stability would require recalibration. Forecasts reflect documented assumptions regarding land allocation continuity and grid absorption capacity expansion. Revision becomes warranted when Egyptian Electricity Transmission Company connection permit restrictions cross thresholds that strand committed project capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Hybrid Solar Panel Market