
 Solar Ceiling Fans Market | 2026-2036
Solar Ceiling Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Ceiling Fans Market Insights
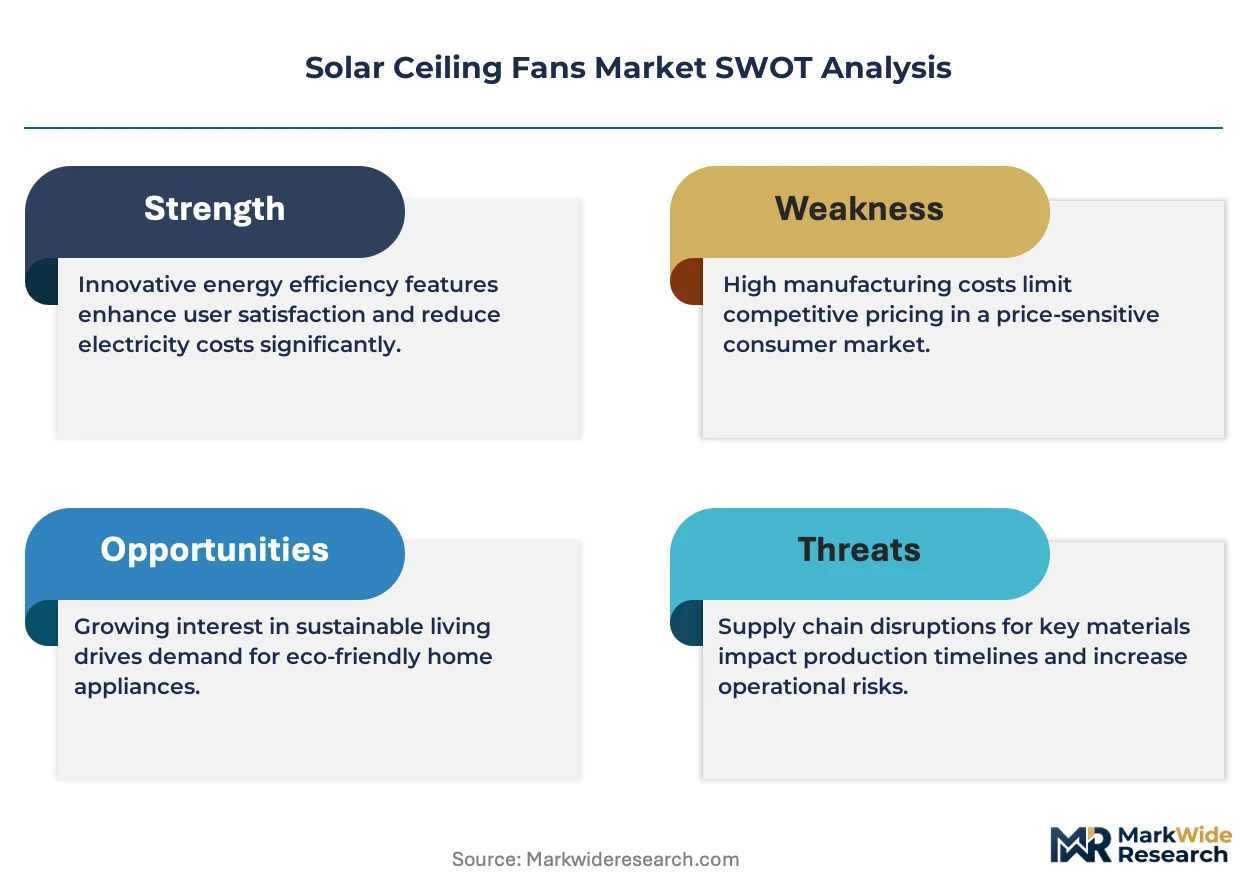
The rural residential electrification segment is pivoting toward decentralized cooling as grid extension lags population growth in emerging economies. Havells anchors its position through backward integration into solar motor manufacturing across Indian states. Emerson Electric Co. competes on variable frequency drive technology leadership for humid climates. Leeline Energy specializes in battery-operated configurations targeting African markets with unreliable daytime solar exposure.
Solar ceiling fans integrate photovoltaic panels, DC brushless motors, and lithium-ion or lead-acid storage to deliver air circulation independent of grid connectivity, with typical blade spans ranging from 36 to 60 inches and power draws below 35 watts at full speed. Energy-efficient product types dominate unit shipments due to BEE and ENERGY STAR compliance requirements, while smart segment growth accelerates fastest as IoT-enabled load management appeals to commercial buyers seeking demand-response participation. Photovoltaic technology leads installations where sunlight hours exceed five daily, though battery-operated configurations capture margin pools in equatorial zones with pronounced rainy seasons.
India's Bureau of Energy Efficiency mandates star-labeling for solar fans sold domestically, while the EU F-Gas Regulation indirectly shapes component sourcing by restricting refrigerant-linked supply chains that compete for motor manufacturing capacity. The US EPA and DOE coordinate on off-grid appliance test procedures that determine federal procurement eligibility. Stakeholders must monitor how national building codes incorporate solar fan pre-wiring mandates as net-zero construction standards expand beyond pilot jurisdictions.
Market Dynamics
Decentralized electrification is accelerating demand for off-grid cooling solutions as grid extension lags behind population growth in emerging economies, creating a structural pull toward solar-powered alternatives to conventional ceiling fans.
Growth Catalysts
- Rural electrification programs:Sub-Saharan African government initiatives are accelerating residential adoption of off-grid cooling solutions where grid infrastructure remains underdeveloped.
- Bureau of Energy Efficiency mandates:India's updated appliance star-rating requirements for solar-powered fans are creating compliance-driven replacement cycles across tier-2 and tier-3 cities.
- DC brushless motor technology:Advances in permanent magnet motor efficiency are reducing power draws below 35 watts at full speed, expanding addressable markets with smaller photovoltaic arrays.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack costs remain vulnerable to raw material price volatility concentrated in cobalt and lithium processing geographies.
- Lead-acid battery substitution economics:Lower upfront costs for lead-acid storage configurations continue to suppress margin realization in price-sensitive rural segments.
- Intermittent solar exposure:Equatorial zones with pronounced rainy seasons face technical limitations in daytime-only photovoltaic installations without storage augmentation.
Strategic Opportunities
- IoT-enabled load management:Smart segment expansion is creating demand-response participation pathways for commercial buyers seeking grid-interactive cooling assets.
- Net-zero construction standards:National building codes incorporating solar fan pre-wiring mandates are opening specification channels in green building projects across pilot jurisdictions.
- Battery-operated configurations:Lithium-ion storage integration is capturing margin pools in African markets with unreliable daytime solar exposure and extended evening cooling needs.
Industry Challenges
- Certification timeline compression:Bureau of Energy Efficiency star-labeling requirements and US EPA off-grid appliance test procedures are extending product validation cycles for multi-market entrants.
- Supply chain reconfiguration:EU F-Gas Regulation restrictions on refrigerant-linked supply chains are competing for motor manufacturing capacity and complicating component sourcing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Ceiling Fans Market |
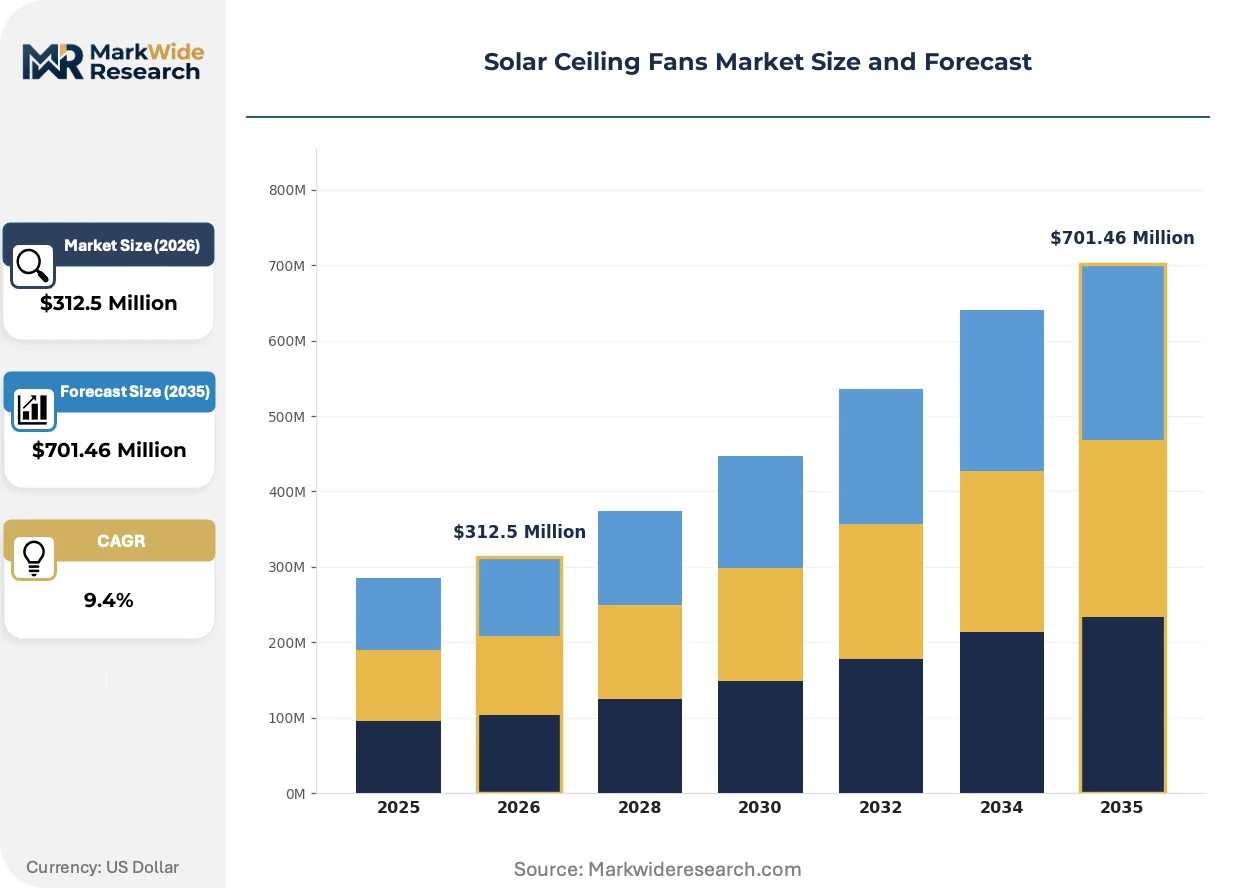
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Energy-Efficient, Smart, Hybrid Application: Residential, Commercial, Industrial, Outdoor Technology: Photovoltaic, Battery-Operated, Direct Current, Variable Frequency Drive End User: Homeowners, Businesses, Contractors, Renewable Energy Enthusiasts |
| Companies Covered | Havells, Emerson Electric Co., Hunter Fan Company, Shell Electric Holdings Limited, NuTone Inc., Crompton Greaves Consumer Electricals Limited, Minka Group, Leeline Energy, Orient Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Ceiling Fans Market Trends and Innovations
Technology convergence between photovoltaic generation, DC motor efficiency, and battery storage is rewriting competitive requirements for ceiling fan manufacturers serving off-grid and unreliable-grid segments.
Variable frequency drive integration is rewriting how humid climate installations manage airflow efficiency. Commercial hospitality buyers across Southeast Asian resort properties are specifying VFC-equipped units to reduce humidity-related motor stress. The technology is compressing maintenance intervals and extending product replacement cycles in coastal installations.
REACH and RoHS compliance requirements are reshaping component sourcing for motor winding insulation and electronic control modules. Manufacturers serving European markets must certify against substance restrictions that exceed baseline international standards. This regulatory friction is diverting R&D expenditure toward material substitution programs rather than core performance improvements.
Direct-to-installer distribution models are displacing traditional wholesale channels in rural African markets. Solar product distributors are building captive installation networks to capture service revenue streams and reduce customer acquisition costs. Kenya and Nigeria represent the most visible geographies for this channel restructuring, with pay-as-you-go financing bundling hardware and installation services.
Solar Ceiling Fans Market Segmentation
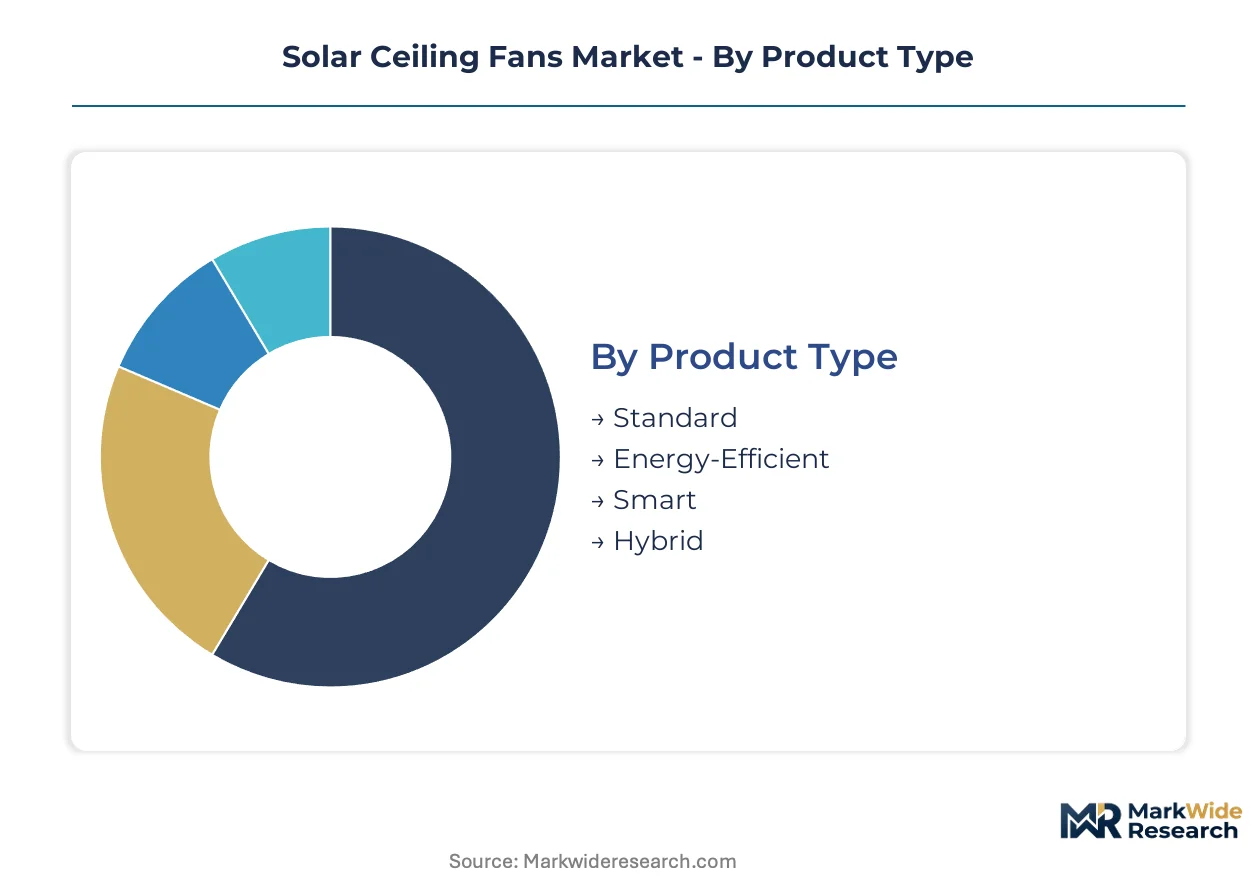
Solar ceiling fan manufacturers configure product portfolios around four intersecting dimensions: capital requirements for photovoltaic integration, installation complexity across building types, storage technology choices, and buyer sophistication levels. Each segmentation axis reveals distinct margin pools and compliance burdens.
Product Type:
Capital intensity varies sharply across product tiers, with smart and hybrid configurations demanding the highest upfront engineering investment for IoT integration and dual-power architectures.
- Standard:Basic DC motor units without storage or connectivity features target price-sensitive rural electrification programs. Demand clusters in Indian tier-3 cities where BEE star-labeling mandates drive replacement cycles among cost-constrained households.
- Energy-Efficient:Permanent magnet brushless motors with optimized blade geometry reduce power draw below 35 watts. ENERGY STAR and BEE compliance positions this segment for federal procurement eligibility under US EPA test procedures.
- Smart:IoT-enabled load management systems allow demand-response participation. Commercial buyers in Southeast Asian hospitality properties specify these units for humidity-optimized airflow control through variable frequency integration.
- Hybrid:Dual-power architectures combining grid-tie capability with solar autonomy require the most complex power electronics. Net-zero construction standards in pilot jurisdictions are creating specification channels for pre-wired installations.
Energy-Efficient units absorb the bulk of installed capacity; Smart configurations are expanding most quickly.
Application:
Installation scale and buyer procurement authority separate application segments, with industrial and commercial deployments commanding volume pricing and extended service contracts.
- Residential:Single-unit purchases through retail and direct-to-installer channels dominate unit shipments. Sub-Saharan African rural electrification programs and Indian tier-2 cities with intermittent grid reliability drive concentrated demand.
- Commercial:Multi-unit specifications for offices, retail, and hospitality require coordinated photovoltaic array sizing. REACH and RoHS compliance requirements reshape component sourcing for European market entrants.
- Industrial:High-airflow installations in warehouses and manufacturing facilities stress motor durability. Variable frequency drive technology reduces humidity-related motor stress in coastal installations.
- Outdoor:Weatherproof enclosures and corrosion-resistant finishes target agricultural and recreational end-uses. Equatorial zones with pronounced rainy seasons favor battery-operated configurations over daytime-only photovoltaic systems.
Residential applications account for the greatest unit volume; Commercial specifications yield the highest revenue per installation.
Technology:
Technology choice determines supply chain exposure, with battery-operated configurations vulnerable to lithium-ion cell price volatility and photovoltaic installations constrained by geographic irradiance patterns.
- Photovoltaic:Direct panel-to-motor systems eliminate storage costs where sunlight exceeds five daily hours. Indian states with high irradiance favor this architecture for agricultural and rural residential cooling.
- Battery-Operated:Lithium-ion or lead-acid storage enables evening operation in African markets with unreliable daytime solar exposure. Lead-acid substitution economics suppress margins in price-sensitive segments.
- Direct Current:Native DC architectures eliminate inverter losses and simplify off-grid installations. DC brushless motor advances from Emerson Electric and Havells are compressing power requirements.
- Variable Frequency Drive:Humidity-responsive speed control extends motor life in coastal and tropical installations. Southeast Asian resort properties specify VFD-equipped units to reduce maintenance intervals.
Photovoltaic technology claims the largest installed base; Battery-Operated systems are climbing the fastest as storage costs moderate.
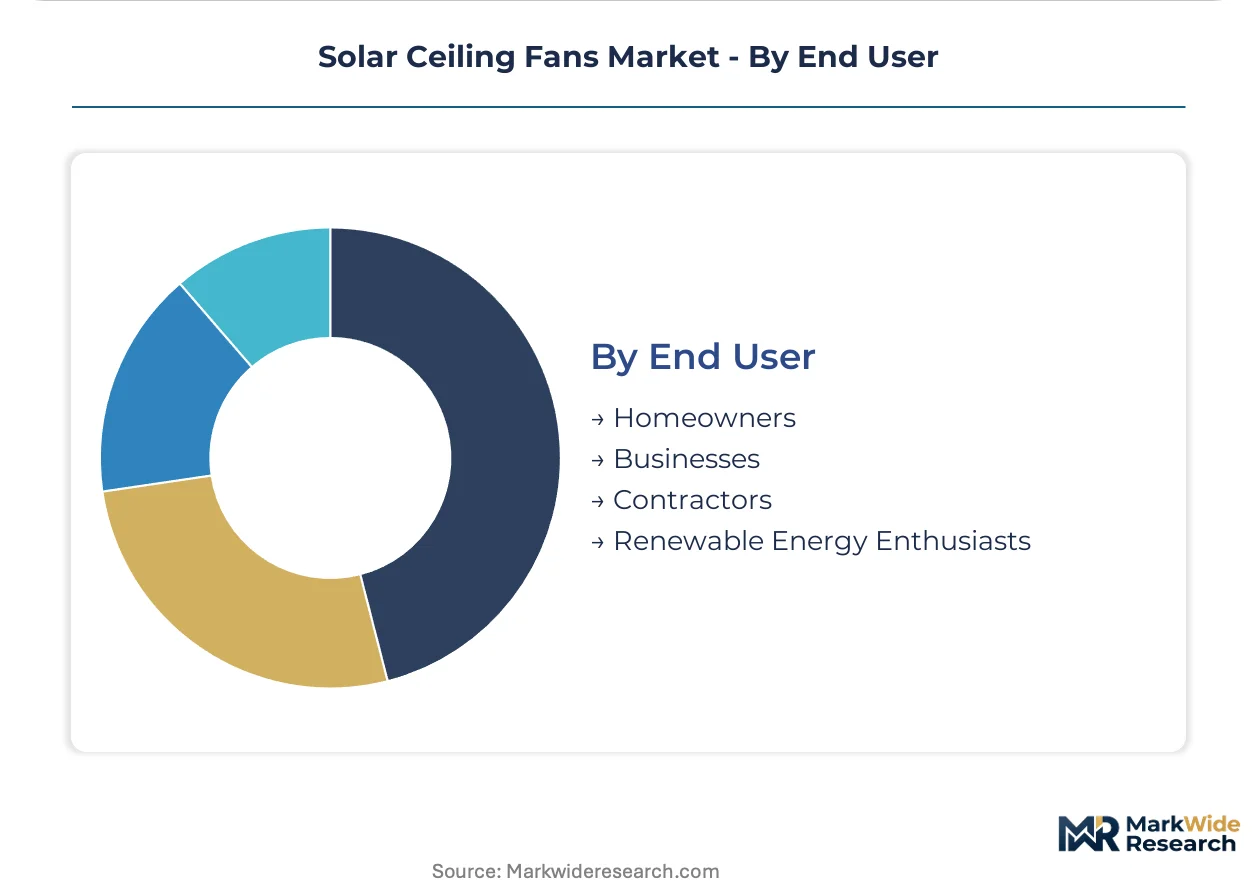
End User:
Buyer technical sophistication and procurement scale create distinct service requirements, from homeowner self-installation to contractor-managed commercial deployments.
- Homeowners:Individual purchasers prioritize upfront cost and ease of installation. Pay-as-you-go financing bundles in Kenya and Nigeria reduce customer acquisition costs through captive installer networks.
- Businesses:Commercial entities specify for operational reliability and demand-response eligibility. Smart segment IoT capabilities appeal to grid-interactive cooling asset strategies.
- Contractors:Installation professionals influence specification through service revenue relationships. Direct-to-installer distribution models in rural African markets displace traditional wholesale channels.
- Renewable Energy Enthusiasts:Early adopters drive specification for premium hybrid and smart configurations. Net-zero construction pilot jurisdictions attract this buyer category for technology validation.
Homeowners represent the broadest addressable base; Businesses deliver the most predictable recurring revenue through service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in India and China while consumption spreads across emerging economies with unreliable grid infrastructure. Manufacturing scale advantages in Asian production hubs supply decentralized electrification programs across sub-Saharan Africa and South Asia. Regional demand patterns diverge sharply between high-irradiance zones favoring direct photovoltaic systems and equatorial regions requiring battery augmentation.
India
Rural electrification gaps and intermittent grid reliability in tier-2 and tier-3 cities drive residential demand for off-grid cooling alternatives. The Bureau of Energy Efficiency mandates star-labeling compliance for all solar fans sold domestically, accelerating replacement cycles among cost-conscious households. Manufacturing clusters in Gujarat and Maharashtra host backward-integrated motor production facilities serving both domestic and export markets.
China
Component manufacturing scale and DC brushless motor technology leadership position Chinese suppliers as upstream providers to global assembly operations. The MIIT oversees industrial standards for energy-efficient appliances while dual carbon goals incentivize photovoltaic-integrated product development. Production gravity centers on the Yangtze River Delta and Pearl River Delta regions where electronics manufacturing ecosystems support rapid prototyping and cost optimization.
United States
Federal procurement programs and net-zero construction pilot jurisdictions create specification channels for hybrid and smart configurations. The EPA coordinates with DOE on off-grid appliance test procedures that determine eligibility for government purchasing programs. California and Texas lead residential adoption through state-level building code incentives and high solar irradiance profiles favoring photovoltaic-dominant installations.
Kenya
Pay-as-you-go financing models and direct-to-installer distribution networks reduce customer acquisition costs in rural electrification programs. The national rural electrification authority supports decentralized solar product deployment where grid extension remains economically unviable. Nairobi anchors distribution logistics while Mombasa serves as the import gateway for Asian-manufactured components entering East African markets.
Nigeria
Unreliable grid infrastructure and diesel generator cost volatility push commercial and residential buyers toward autonomous solar cooling solutions. The country's national energy regulator oversees off-grid electrification frameworks that enable private-sector solar product distribution. Lagos and Kano represent the primary demand centers where captive installer networks bundle hardware, financing, and maintenance services.
Solar Ceiling Fans Market Competitive Landscape
Top-tier vendors anchor premium and smart segments, while mid-scale fabricators compete on cost-optimized standard configurations for rural electrification programs. The vendor base stratifies across three tiers: integrated electrical conglomerates with captive motor manufacturing, specialized solar appliance pure-plays, and contract assembly operations serving price-sensitive African markets. Two strategic archetypes dominate: backward-integrated manufacturers controlling DC motor supply chains, and distribution-focused specialists building captive installer networks. Capacity expansion in Indian states and strategic partnerships with rural electrification agencies represent the dominant competitive moves.
Among integrated electrical conglomerates, Havells India Limited and Crompton Greaves Consumer Electricals Limited exemplify the backward-integration archetype with in-house motor manufacturing capabilities across Indian production facilities. Emerson Electric Co. occupies a position within the technology leadership tier, representing variable frequency drive competency for humid climate applications. These three companies anchor distinct competitive vectors: manufacturing scale, component integration depth, and climate-specific engineering specialization respectively.
| Leading Market Players |
|---|
| Havells |
| Emerson Electric Co. |
| Hunter Fan Company |
| Shell Electric Holdings Limited |
| NuTone Inc. |
| Crompton Greaves Consumer Electricals Limited |
| Minka Group |
| Leeline Energy |
| Orient Electric |
| Others |
Pricing and Supply Chain Analysis
India's Bureau of Energy Efficiency star-labeling mandate gates qualified supply and premium-tier pricing access, forcing manufacturers to absorb certification costs or exit domestic channels entirely. Compliance investment separates BEE-certified suppliers commanding specification premiums from gray-market entrants competing solely on upfront cost.
Pricing Analysis
Margin tightening in standard-tier configurations reflects lead-acid battery substitution economics suppressing realized returns. Three-tier pricing structure across premium, standard, and economy levels differentiates by BEE certification grade and after-sales service bundling. Pricing pressure intensifies in African rural segments as captive installer networks compress hardware margins to capture financing revenue. Tier-2 Indian households exhibit highest price sensitivity; Southeast Asian hospitality buyers show lowest sensitivity due to humidity-optimized VFD specifications.
Supply Chain Analysis
Refurbishment flows for DC brushless motors and lithium-ion battery packs remain underdeveloped, constraining circularity economics. Component manufacturing concentrates in China, India, and Vietnam, with motor winding insulation drawing from REACH-compliant European suppliers. Cobalt and lithium processing dependencies create single-source vulnerability concentrated in African mining geographies. Distribution runs through direct-to-installer networks in Kenya and Nigeria, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: India's BEE star-labeling mandate creates a barrier-to-entry moat that rewards pre-certified incumbents while screening out undercapitalized challengers.
For Market Incumbents: Extend backward integration into solar motor manufacturing to defend margin position against contract assemblers from Chinese production hubs. Anchor capacity expansion in Gujarat and Maharashtra production clusters to secure BEE certification proximity and reduce logistics exposure to lithium-ion cell price volatility. For New Entrants and Emerging Players: Capture specification channels in net-zero construction pilot jurisdictions where pre-wiring mandates favor hybrid configurations with complex power electronics. Target renewable energy enthusiast buyer segments through premium smart-tier positioning, leveraging IoT-enabled load management as the primary go-to-market angle. For Investors and Strategic Acquirers: BEE certification timeline compression is the leading indicator that regulatory friction will consolidate vendor tiers toward backward-integrated manufacturers. Long-term viability centers on acquiring motor manufacturing capabilities rather than distribution assets. Monitor EPA-DOE coordination on off-grid appliance test procedures as the signal for federal procurement eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Havells anchors competitive position through captive DC brushless motor production across Indian states. |
| Direct-to-Installer Distribution Buildout | Pay-as-you-go financing bundles in Kenya and Nigeria reduce customer acquisition costs through captive service networks. |
| BEE Star-Labeling Certification Investment | Compliance positioning unlocks tier-2 and tier-3 city replacement cycles driven by mandate-driven demand. |
| Variable Frequency Drive Technology Licensing | Emerson Electric leverages humidity-optimized airflow control to extend motor life in coastal Southeast Asian installations. |
| Battery-Operated Configuration Development | Leeline Energy captures African margin pools where unreliable daytime solar exposure necessitates lithium-ion storage integration. |
Research Methodology
Document review covered BEE regulatory filings, EPA off-grid appliance test procedures, and EU F-Gas Regulation implementation guidance, complemented by interviews with solar product distributors, DC motor procurement leads at electrical conglomerates, rural electrification program officers, and captive installer network managers. Secondary validation drew from customs trade data, SEC 10-K disclosures from listed electrical manufacturers, and IEA electrification access databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Output projections span the analysis window across product type, application, technology choice, and end-user sophistication dimensions. CAGRs derived from regression-weighted historical growth rates applied to penetration curves for off-grid and unreliable-grid segments. Industry-specific inputs included irradiance-hour thresholds for photovoltaic viability and battery cost decline trajectories for storage-augmented configurations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion raw material price volatility and BEE mandate enforcement intensity. Projections reflect assumptions on rural electrification program funding continuity and net-zero construction code adoption pace. Practitioners should monitor cobalt supply chain disruptions and EPA test procedure finalization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
China Wind Power Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Austria Renewable Energy Market